
 Germany AC Motor Market | 2026-2036
Germany AC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Germany AC Motor Market Insights
Copper winding substitution with aluminum in fractional-horsepower motor designs is realigning cost structures for mass-produced industrial units. Siemens AG leverages captive supply chains for laminated steel cores to sustain margin stability across its Nuremberg manufacturing complex. SEW-EURODRIVE GmbH & Co KG anchors its position through deep specialization in gearmotor integration, while Bosch competes aggressively in the compact motor segment serving appliance OEMs.
An AC motor converts alternating current electrical energy into mechanical rotation through electromagnetic induction between stator windings and a rotor assembly, typically operating at speeds determined by supply frequency and pole count. These machines power conveyor systems, compressor drives, and pump installations where continuous-duty torque output and variable-speed control determine process efficiency. Induction motors occupy the mature volume tier across German manufacturing floors, while servo motor architectures are capturing share in precision automation cells where positioning accuracy below 0.01 degrees is mandatory. Variable Frequency Drive pairings with standard induction platforms are extending equipment life and trimming energy draw in pumping applications throughout the Ruhr industrial basin.
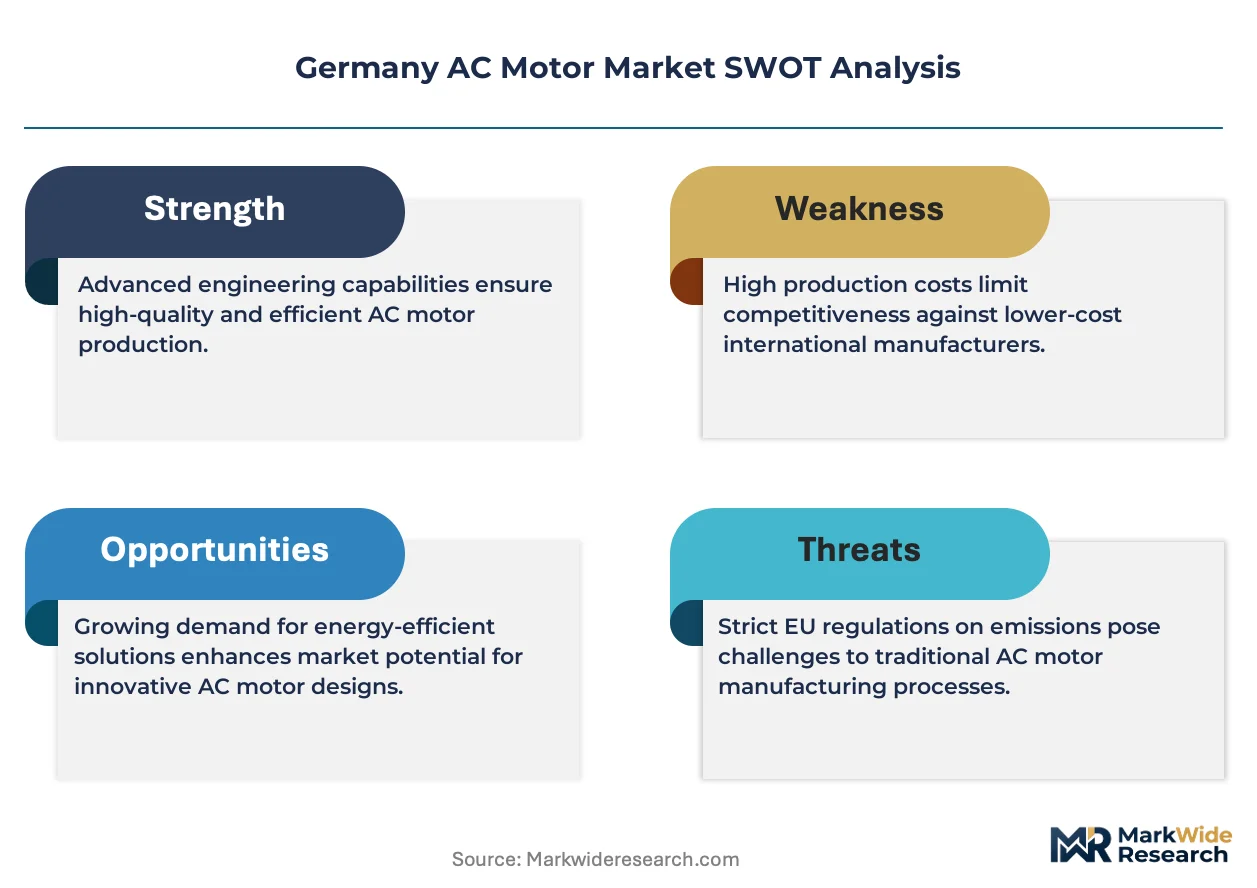
KBA efficiency labeling requirements and the EU Ecodesign Directive frame product compliance thresholds, compelling manufacturers to certify motors at IE3 premium-efficiency minimums for outputs above 0.75 kilowatts. Germany's Federal Ministry for Economic Affairs and Climate Action enforces procurement guidelines that favor IE4 and IE5 super-premium classes in public infrastructure projects, effectively segmenting the market by certification tier. Stakeholders must track how the EU F-Gas Regulation and pending refrigerant phase-downs reshape compressor motor specifications in heat pump and HVAC channels, since these product lines represent critical demand anchors for mid-power asynchronous designs.
Market Dynamics
The EU Ecodesign Directive's escalating efficiency tiers are compressing demand toward IE4 and IE5 super-premium motor classes, forcing manufacturers to absorb R&D costs while OEMs in Bavaria and Baden-Württemberg accelerate procurement of high-efficiency synchronous designs for electric vehicle production lines.
Growth Catalysts
- National Hydrogen Strategy:Germany's hydrogen infrastructure buildout is stimulating demand for explosion-proof AC motors in electrolyzer compressor stations and hydrogen pipeline booster installations.
- Automotive corridor concentration:OEM and Tier-1 supplier retooling across the Stuttgart-to-Munich manufacturing belt is pulling premium-efficiency gearmotor orders from SEW-EURODRIVE and specialized integrators.
- Copper-to-aluminum substitution:Fractional-horsepower motor designers are adopting aluminum windings to offset raw material volatility, expanding addressable volume in mass-produced industrial units.
Market Restraints
- Laminated steel core supply concentration:Captive supply chains for electrical steel in Nuremberg and surrounding manufacturing clusters create dependency on a limited supplier base for high-efficiency core materials.
- IE3 minimum efficiency regulation:The Ecodesign Directive's 0.75-kilowatt threshold for premium-efficiency certification raises unit costs for smaller motor applications, squeezing margin in price-sensitive segments.
- Servo motor substitution:Precision automation cells below 0.01-degree positioning tolerance are displacing standard induction platforms in high-accuracy manufacturing, compressing volume in mature asynchronous categories.
Strategic Opportunities
- Ruhr industrial basin retrofit cycles:Aging pump and compressor installations across North Rhine-Westphalia present replacement demand for Variable Frequency Drive pairings with premium-efficiency induction motors.
- F-Gas Regulation phase-down:Pending refrigerant restrictions under EU F-Gas rules are reshaping compressor motor specifications in heat pump and HVAC channels, opening specification windows for mid-power asynchronous redesigns.
- Public infrastructure procurement guidelines:Federal Ministry for Economic Affairs and Climate Action preference for IE4 and IE5 classes in government projects creates a protected demand tier for super-premium efficiency certification.
Industry Challenges
- Electrical steel metallurgy expertise:Thin-gauge, high-silicon laminated core production requires specialized lamination and annealing capabilities that concentrate in a narrow supplier base, constraining capacity scaling.
- KBA efficiency labeling compliance timelines:Certification testing and documentation requirements for efficiency tier verification extend product development cycles, delaying market entry for redesigned motor platforms.
- Legacy Variable Frequency Drive integration:Retrofitting existing pumping and conveyor installations with new premium-efficiency motors requires compatibility validation with installed drive electronics, complicating field deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany AC Motor Market |
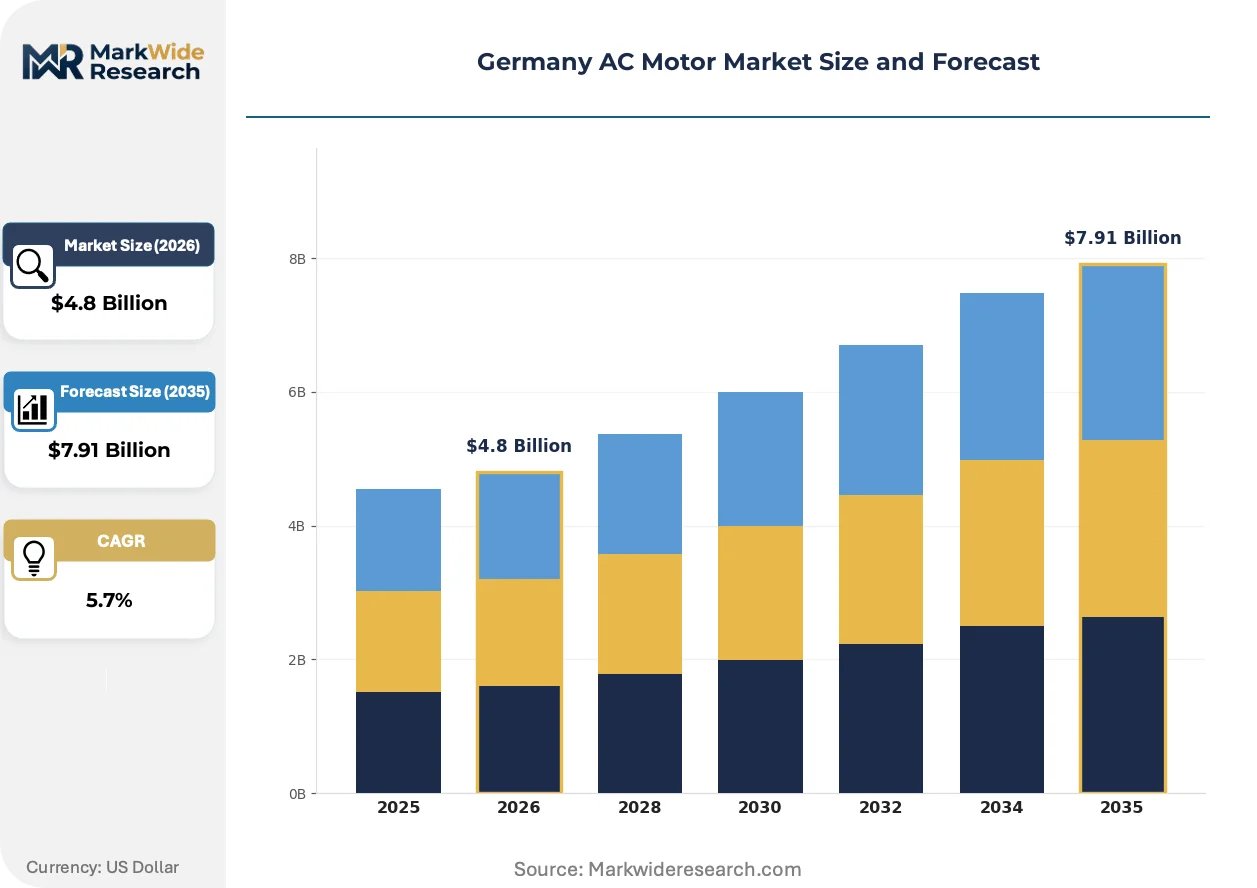
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Motor, Synchronous Motor, Universal Motor, Servo Motor End User: Manufacturing, HVAC, Pumping, Transportation Technology: Variable Frequency Drive, Direct On-Line, Soft Starter, Bluetooth Controlled Application: Industrial Automation, Home Appliances, Electric Vehicles, Renewable Energy |
| Companies Covered | Siemens AG, ABB Ltd., Nidec Corporation, WEG, Teco Electric Europe Ltd., Bosch, Johnson Controls, SEW-EURODRIVE GmbH & Co KG, Groschopp AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany AC Motor Market Trends and Innovations
Permanent magnet synchronous motor architectures are penetrating industrial automation at accelerating rates, while regulatory pressure on refrigerant systems and procurement digitization are restructuring how efficiency-certified equipment reaches end-users.
Axial flux motor topologies are decentralizing traditional radial flux design dominance in compact, high-torque applications. Material handling and robotics OEMs in Baden-Württemberg are adopting these configurations for space-constrained drivetrains. The technology is decentralizing motor-gearbox integration patterns by enabling direct-drive architectures that eliminate mechanical reduction stages.
KBA efficiency labeling requirements now mandate third-party verification for IE3 and above classifications, tightening documentation burdens on manufacturers. The regulation compresses product development timelines by adding certification gates before market release. Heat pump and HVAC OEMs are responding by pre-qualifying motor suppliers against anticipated F-Gas Regulation refrigerant phase-down schedules.
Digital procurement platforms are consolidating specification-to-order workflows for standard industrial motors, displacing traditional distributor-led technical consultation models. MRO buyers in the Ruhr industrial basin are adopting these channels for fractional-horsepower replacement orders. This channel shift is most visible among mid-sized manufacturing facilities seeking to compress spare parts procurement cycles.
Germany AC Motor Market Segmentation
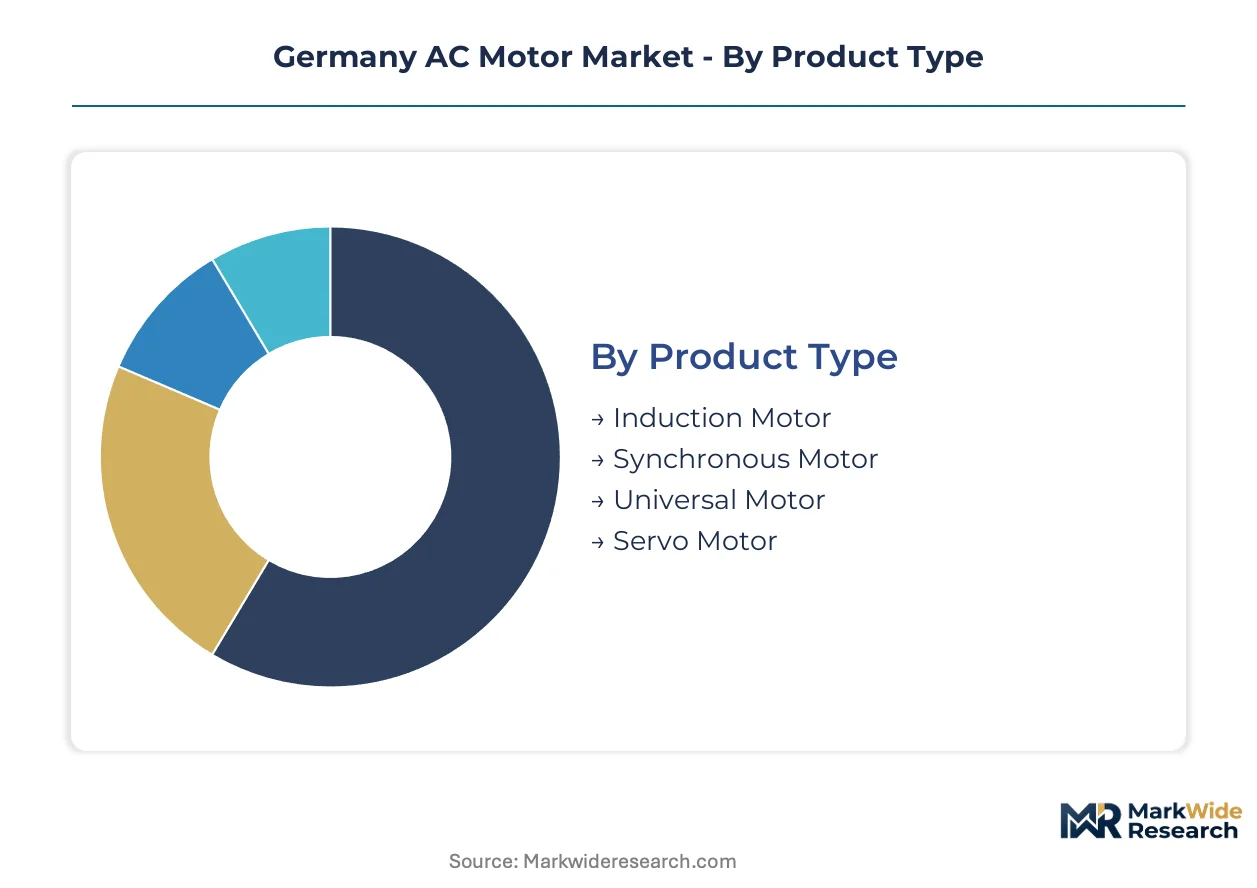
German AC motor procurement patterns diverge sharply across efficiency tiers, control architectures, and end-use torque requirements. Segment boundaries determine compliance pathways under KBA labeling rules and Ecodesign Directive thresholds.
Product Type:
Buyers in this category differentiate primarily by rotor excitation method and speed control precision required for their installed base.
- Induction Motor:Squirrel-cage rotor designs dominate continuous-duty applications across Ruhr industrial basin pumping stations and conveyor networks. Bavarian automotive stamping plants specify these for press feed drives where constant speed operation suffices.
- Synchronous Motor:Permanent magnet architectures deliver precise speed holding for electric vehicle production line robotics in Stuttgart-to-Munich manufacturing corridors. EU Ecodesign IE4 and IE5 efficiency mandates are accelerating displacement of induction platforms in premium automation cells.
- Universal Motor:Series-wound commutator designs power handheld power tools and domestic appliances where high starting torque at variable speed is essential.
- Servo Motor:Closed-loop positioning systems with resolver or encoder feedback achieve sub-0.01-degree accuracy for precision assembly in Baden-Württemberg electronics manufacturing.
Induction motors lead volumes today; synchronous architectures are gaining share fastest.
End User:
Application torque profiles and duty cycle intensity separate procurement specifications across German industrial sectors.
- Manufacturing:Automated assembly lines in automotive OEM plants demand servo-synchronous hybrids for coordinated multi-axis motion. SEW-EURODRIVE gearmotor integration dominates this channel.
- HVAC:Centrifugal fan and compressor drives in commercial buildings specify mid-power asynchronous motors paired with Variable Frequency Drives. F-Gas Regulation refrigerant phase-downs are forcing motor-rewind specification reviews.
- Pumping:Water treatment and process fluid installations across North Rhine-Westphalia favor premium-efficiency induction platforms with VFD retrofit compatibility.
- Transportation:Traction motor requirements for rail electrification and emerging hydrogen fuel cell bus platforms specify explosion-proof synchronous designs.
Manufacturing commands the largest installed base; transportation applications are expanding most quickly.
Technology:
Control integration depth and startup torque management distinguish capital expenditure tiers and energy recovery potential.
- Variable Frequency Drive:Scalar and vector control algorithms enable energy recovery in pumping and HVAC applications. Ruhr basin retrofit cycles favor VFD-induction pairings for demand-responsive flow control.
- Direct On-Line:Across-the-line starting remains standard for fractional-horsepower fans and compressors where inrush current constraints are absent.
- Soft Starter:Reduced-voltage starting protects mechanical transmission components in high-inertia conveyor and crusher drives.
- Bluetooth Controlled:Wireless commissioning and diagnostics are penetrating maintenance-intensive installations where technician access is constrained.
Variable Frequency Drive installations dominate new specification; Bluetooth-enabled platforms are climbing the fastest.
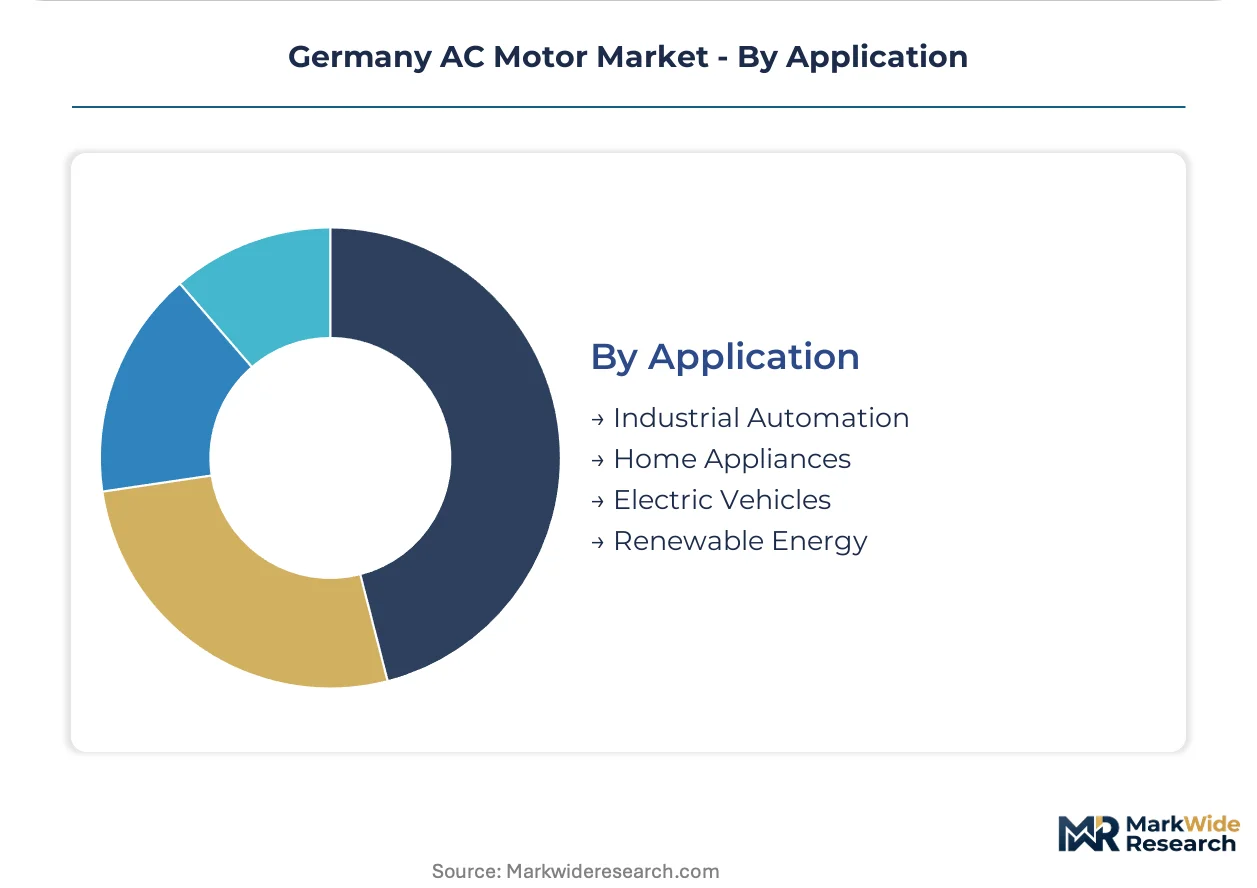
Application:
Positioning accuracy requirements and thermal cycling tolerance separate design priorities across German end-use sectors.
- Industrial Automation:Multi-axis robotics and material handling systems in automotive Tier-1 supplier plants specify servo-grade synchronous motors with integrated safety encoders.
- Home Appliances:Washing machine and dishwasher OEMs in Bosch's supply radius favor compact universal and induction designs with aluminum winding cost structures.
- Electric Vehicles:Battery-electric powertrain manufacturing in Bavaria is pulling high-efficiency interior permanent magnet motors for traction and thermal management pumps.
- Renewable Energy:Wind turbine pitch control and solar tracking actuators specify ruggedized synchronous platforms with extended temperature ranges.
Industrial automation maintains the deepest installed base; electric vehicle applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-to-Munich automotive manufacturing corridor anchors German AC motor demand through OEM and Tier-1 supplier retooling activity. Bavarian electric vehicle production lines and Baden-Württemberg precision automation clusters concentrate procurement of high-efficiency synchronous and servo motor platforms. Federal procurement guidelines under the National Hydrogen Strategy and EU Ecodesign Directive reshape specification patterns across sub-regional industrial bases.
Bavaria
Battery-electric vehicle powertrain manufacturing in Munich and Ingolstadt pulls interior permanent magnet synchronous motors for traction applications. The Federal Ministry for Economic Affairs and Climate Action enforces IE4 and IE5 procurement preferences in publicly funded infrastructure projects. Siemens AG leverages its Nuremberg manufacturing complex to supply laminated steel cores for premium-efficiency motor production serving this corridor.
Baden-Württemberg
Automotive stamping plants and robotics OEMs in Stuttgart specify servo-grade synchronous motors for multi-axis assembly systems. KBA efficiency labeling requirements mandate third-party verification for IE3 and above classifications, extending product development timelines. SEW-EURODRIVE GmbH & Co KG anchors gearmotor integration supply to Tier-1 suppliers retooling facilities across this manufacturing belt.
North Rhine-Westphalia
Aging pump and compressor installations across the Ruhr industrial basin generate replacement demand for Variable Frequency Drive pairings with premium-efficiency induction motors. The EU Ecodesign Directive's 0.75-kilowatt IE3 minimum threshold raises unit costs for smaller motor applications in this price-sensitive retrofit segment. Water treatment facilities in Düsseldorf and Dortmund favor VFD-compatible induction platforms for demand-responsive flow control.
Lower Saxony
Wind turbine pitch control and nacelle drive systems in Hanover and Braunschweig specify ruggedized synchronous platforms with extended temperature ranges. Germany's National Hydrogen Strategy stimulates demand for explosion-proof AC motors in electrolyzer compressor stations planned for this region. Bosch competes in compact motor segments serving appliance OEMs concentrated in Wolfsburg-area manufacturing zones.
Hesse
Commercial HVAC and data center cooling installations in Frankfurt specify mid-power asynchronous motors paired with Variable Frequency Drives. Pending EU F-Gas Regulation refrigerant phase-downs reshape compressor motor specifications in heat pump channels serving this financial services hub. Johnson Controls positions for specification wins in building automation retrofit cycles across Rhine-Main metropolitan infrastructure.
Germany AC Motor Market Competitive Landscape
Global majors compete with regional champions across efficiency certification tiers and gearmotor integration depth. The vendor base stratifies into three tiers: multinational conglomerates with captive electrical steel supply, mid-sized specialists in gearmotor-system integration, and compact motor suppliers serving appliance OEMs. Consolidation pressure concentrates in premium-efficiency synchronous platforms where R&D absorption costs favor scale. Dominant competitive moves include backward integration into laminated core production and strategic partnerships for hydrogen infrastructure motor certification.
Among Germany-based industrial champions, Siemens AG and SEW-EURODRIVE GmbH & Co KG exemplify divergent archetypes within the premium-efficiency segment. Siemens occupies a position anchored in captive supply chain control over electrical steel metallurgy. SEW-EURODRIVE represents deep specialization in gearmotor integration for automotive corridor demand. Bosch sits within the compact motor tier serving mass-produced appliance applications where aluminum winding substitution compresses cost structures. Swiss-Swedish conglomerate ABB Ltd. competes across multiple efficiency tiers with global scale advantages in variable frequency drive pairing technologies.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Nidec Corporation |
| WEG |
| Teco Electric Europe Ltd. |
| Bosch |
| Johnson Controls |
| SEW-EURODRIVE GmbH & Co KG |
| Groschopp AG |
| Others |
Pricing and Supply Chain Analysis
OEM procurement teams in Bavaria's electric vehicle production corridor negotiate contract-based long-term offtake agreements that compress margin for fractional-horsepower suppliers while amplifying pricing power for IE4 and IE5 super-premium motor manufacturers serving hydrogen infrastructure projects.
Pricing Analysis
Copper and electrical steel input-cost pass-through dominates pricing structures for laminated core assemblies, with three-tier pricing stratification across premium-efficiency synchronous platforms, standard induction units, and economy-grade fractional-horsepower designs. Certification tier under KBA efficiency labeling rules and IE3 minimum thresholds serve as primary price differentiation drivers. Pricing pressure intensifies in mass-produced industrial segments as aluminum winding substitution erodes legacy copper-based cost structures. Small motor applications below 0.75 kilowatts exhibit highest price sensitivity due to Ecodesign Directive compliance burdens, while hydrogen infrastructure procurement shows lowest sensitivity given National Hydrogen Strategy funding envelopes.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart-to-Munich automotive corridors, while distributor-led technical consultation retains relevance in Ruhr basin MRO replacement cycles. Geographic supply concentration centers on Germany for laminated steel core production, China for rare earth permanent magnet materials, and Eastern European manufacturing zones for wound stator assemblies. Raw material dependencies span high-silicon electrical steel, neodymium-iron-boron magnets, and aluminum winding wire. Single-source vulnerability in thin-gauge lamination capabilities constrains capacity scaling for IE5-class motors. Distribution runs through integrated gearmotor specialists for automotive Tier-1 suppliers and digital procurement platforms for mid-sized manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's AC motor market offers geographic-arbitrage positioning between EU Ecodesign-mandated efficiency tiers and Eastern European manufacturing cost bases, with regulatory compliance differential creating margin capture opportunities for producers with captive lamination capabilities.
For Market Incumbents: Acquire thin-gauge electrical steel lamination and annealing assets to secure upstream control over IE4 and IE5 core material supply. Siemens AG's Nuremberg captive supply chain model demonstrates margin stability under raw material volatility. SEW-EURODRIVE should deepen gearmotor integration patents to defend against servo motor substitution in precision automation cells. Certification investment in KBA third-party verification infrastructure creates channel control barriers against emerging synchronous motor specialists. For New Entrants and Emerging Players: Enter via Bluetooth-enabled commissioning platforms for maintenance-constrained Ruhr industrial basin installations, where technician access limitations create specification windows for wireless diagnostics. Target mid-power asynchronous redesigns for heat pump and HVAC channels anticipating EU F-Gas Regulation refrigerant phase-downs. Pursue specification partnerships with Johnson Controls and building automation retrofit contractors in Rhine-Main metropolitan infrastructure. White-space concentration exists in explosion-proof AC motors for hydrogen pipeline booster installations under Germany's National Hydrogen Strategy. For Investors and Strategic Acquirers: Industrial conglomerates with automotive powertrain exposure are the most active acquirer in this space, seeking synchronous motor capabilities for electric vehicle traction applications. Long-term viability hinges on laminated core metallurgy expertise and hydrogen infrastructure certification positioning. Acquisition target archetypes include mid-sized gearmotor integrators with Baden-Württemberg automotive corridor relationships and specialists in axial flux topologies for robotics direct-drive applications. Monitor KBA efficiency labeling compliance timeline extensions as inflection indicator for R&D absorption stress among sub-scale manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Steel | Siemens AG's Nuremberg lamination complex secures IE5 core supply against thin-gauge capacity constraints. |
| Hydrogen Infrastructure Certification | Explosion-proof motor qualification under National Hydrogen Strategy unlocks electrolyzer compressor station demand. |
| Axial Flux Topology Development | Baden-Württemberg robotics OEMs adopt direct-drive configurations eliminating mechanical reduction stages. |
| Digital Procurement Platform Partnership | Ruhr basin MRO buyers compress spare parts cycles through specification-to-order workflow consolidation. |
| Aluminum Winding Cost Restructuring | Bosch and appliance OEM suppliers offset copper volatility in mass-produced fractional-horsepower units. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers at Ruhr industrial basin pumping installations, OEM procurement teams across Bavarian electric vehicle production lines, aftermarket service heads at SEW-EURODRIVE integration centers, and HVAC specification engineers in Frankfurt commercial buildings were cross-validated against secondary sources including KBA efficiency certification databases, EU Ecodesign Directive implementation reports, Federal Ministry for Economic Affairs and Climate Action procurement guidelines, and customs records for electrical steel and permanent magnet material flows. Triangulation between demand-side installation tracking and supply-side production capacity assessments ensures segmentation integrity.
Historical trendline analysis of efficiency tier penetration rates and gearmotor integration patterns established baseline trajectory parameters across the projection horizon. The analytical framework models segmentation across product type, end user, technology, and application dimensions, with additional disaggregation by efficiency certification tier and regional industrial cluster. CAGRs were derived from fitted growth curves applied to verified installation base and replacement cycle data. Industry-specific forecast inputs include hydrogen infrastructure deployment schedules under Germany's National Hydrogen Strategy and F-Gas Regulation refrigerant phase-down timelines reshaping compressor motor specifications.
Inputs from KBA certification databases and Federal Ministry procurement disclosures were available through the study window; gaps in real-time OEM inventory positioning and Tier-1 supplier contract renewal timelines introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding Ecodesign Directive enforcement continuity and electrical steel capacity expansion trajectories. Periodic stress-testing of base assumptions against regulatory amendment proposals and raw material price shock scenarios is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Cryogenic Air Separation Units (Asus) Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
Spargers Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
Variable Speed Drive Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
China AC Motor Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Global Direct Current (DC) Motor Market
Industrial Motors
US Electric Motor Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Global Parallel Shaft Geared Motors Market