
 Asia-Pacific Induction Motor Market | 2026-2036
Asia-Pacific Induction Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Induction Motor Market Outlook
Modular motor-drive bundling is consolidating buyer preference across the Asia-Pacific induction motor landscape. ABB Ltd. leverages its integrated automation portfolio to anchor large industrial contracts in Southeast Asian manufacturing zones. Toshiba Mitsubishi-Electric Industrial Systems Corporation sustains dominance in high-voltage segment supply through captive semiconductor foundry partnerships. Siemens AG differentiates via digital twin integration that extends predictive maintenance capabilities across customer fleets.
An induction motor converts electrical energy into mechanical rotation through electromagnetic induction between stator windings and a conductive rotor, typically operating at synchronous speeds minus slip ranging from two to five percent depending on load. Its primary commercial purpose centers on driving pumps, fans, compressors, and conveyors in settings requiring rugged, brushless operation with minimal maintenance intervals. Three-phase configurations occupy the dominant share of industrial procurement given superior torque density and efficiency profiles under continuous duty cycles. Pumps application demand is accelerating fastest across water treatment and desalination infrastructure buildouts, while single-phase units retain mature positioning in residential HVAC and small agricultural equipment where power availability constraints persist.
India's Bureau of Indian Standards mandates minimum energy performance standards for induction motors rated above specified kilowatt thresholds, directly shaping product design requirements for manufacturers serving the subcontinent. China's Ministry of Industry and Information Technology enforces GB standards that classify motor efficiency tiers, creating market access barriers for non-compliant imports while accelerating domestic replacement cycles. Japan's METI maintains JIS certification protocols that influence premium pricing structures for precision manufacturing applications. Stakeholders must monitor evolving efficiency tier migrations and certification reciprocity agreements between national standards bodies to anticipate procurement specification shifts.
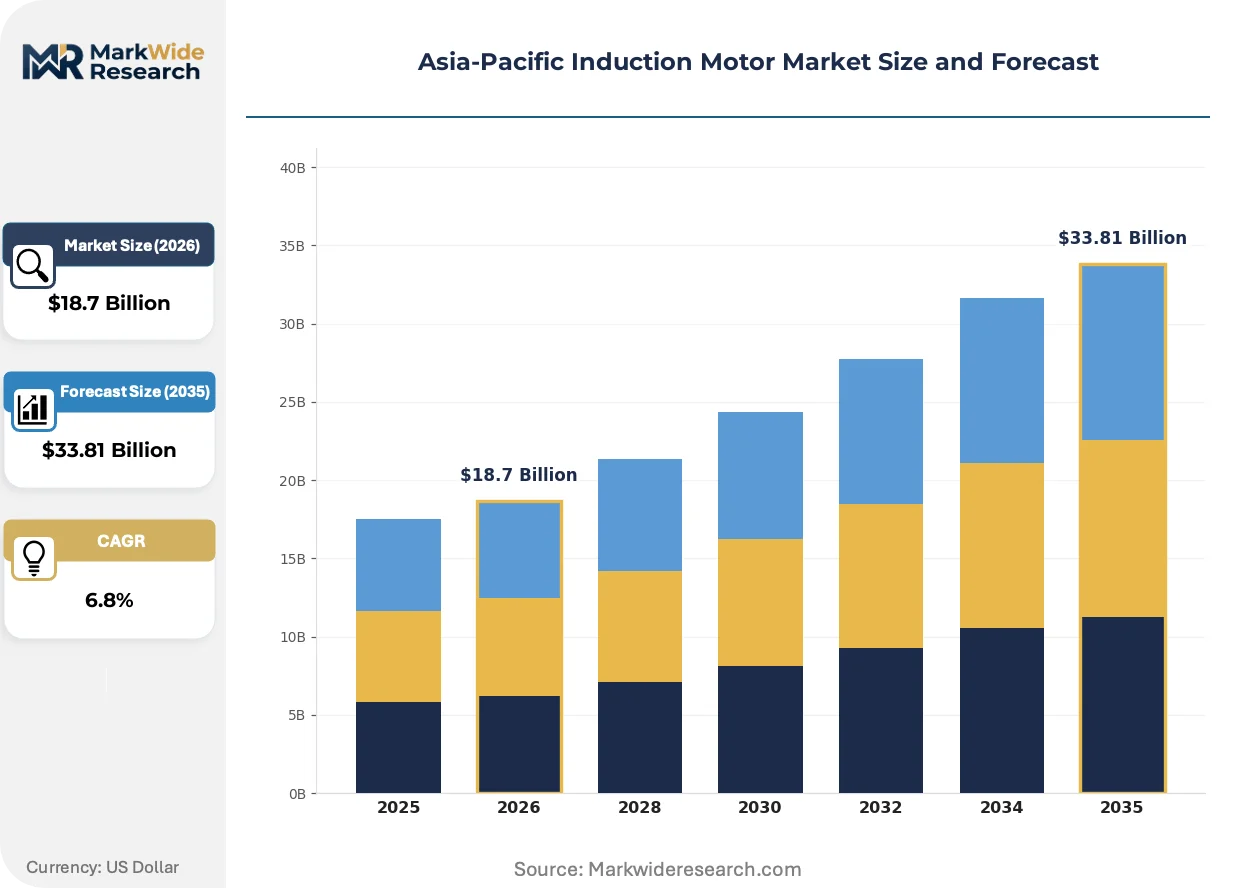
Market Dynamics
Modular motor-drive bundling is consolidating buyer preference across Asia-Pacific manufacturing zones, compressing vendor selection cycles and raising switching costs for industrial procurement teams evaluating integrated automation portfolios.
Growth Catalysts
- MIIT Efficiency Tiers:China's GB standards mandate minimum efficiency classifications for motors above specified power ratings, forcing domestic replacement cycles and blocking non-compliant imports.
- Water Infrastructure Buildouts:Desalination and wastewater treatment facilities across Southeast Asia are specifying high-torque three-phase units for continuous-duty pump applications.
- Semiconductor Foundry Integration:Captive IGBT and silicon carbide production capabilities in Japan and South Korea are securing supply chains for high-voltage motor drive systems.
Market Restraints
- Copper Price Volatility:Stator winding costs fluctuate with London Metal Exchange pricing, squeezing margin stability for manufacturers without long-term commodity hedging.
- Foundry Concentration:Cast iron and aluminum rotor production clusters heavily in eastern China, creating geographic supply risk during regional energy rationing events.
- Permanent Magnet Substitution:Rare-earth magnet motors are capturing precision positioning applications previously served by induction technology in robotics and CNC equipment.
Strategic Opportunities
- Vietnam Industrial Corridor:Northern manufacturing zones around Hai Phong and Bac Ninh are expanding motor procurement for electronics assembly automation with limited local supplier presence.
- Digital Twin Convergence:Integration of vibration sensors with cloud analytics platforms is enabling predictive maintenance service contracts as recurring revenue streams.
- BIS Efficiency Mandates:India's tightened energy performance standards for rotating electrical machines are accelerating replacement demand in textiles and cement processing.
Industry Challenges
- Power Electronics Talent Scarcity:Motor control firmware engineering expertise concentrates in Tokyo, Seoul, and Shanghai, constraining regional expansion for mid-tier manufacturers.
- Legacy System Integration:Retrofitting variable frequency drives into existing fixed-speed installations requires custom mechanical coupling solutions and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Induction Motor Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Double-Squirrel Cage, Wound Rotor End User: Manufacturing, HVAC, Agriculture, Renewable Energy Installation: Onshore, Offshore, Industrial Plant, Commercial Building Application: Conveyors, Pumps, Fans, Compressors |
| Companies Covered | Toshiba Mitsubishi-Electric Industrial Systems Corporation, Regal Rexnord Corporation, ABB Ltd., Kirloskar Electric Company, Fuji Electric Co., Ltd., Siemens AG, WEG S.A., CG Power Systems, Nidec Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Induction Motor Market Strategic Shifts
Electromechanical system architecture is fragmenting into standardized sub-assemblies, enabling faster configuration cycles and blurring traditional boundaries between motor OEMs and drive specialists.
Integrated motor-drive packages are modularizing procurement specifications across Asia-Pacific industrial buyers. Food and beverage processors in Thailand and Malaysia are specifying pre-commissioned skid-mounted units to compress installation timelines. This standardization is modularizing vendor selection criteria away from component-level specifications toward system-level performance guarantees.
India's BIS energy efficiency mandates for rotating electrical machines are tightening product design requirements for manufacturers serving the subcontinent. Domestic motor producers must redesign stator laminations and rotor cage geometries to meet revised loss-limit thresholds. The sub-11kW industrial segment faces the steepest compliance cost escalation as premium-grade electrical steel becomes mandatory.
Specification authority is migrating from maintenance departments to central procurement functions with enterprise-level automation frameworks. Large manufacturing conglomerates in China are consolidating vendor panels and demanding fleet-wide telemetry integration. This concentration is most visible in the Yangtze River Delta automotive supply base, where tier-one suppliers face mandatory interoperability standards imposed by vehicle OEM parent companies.
Asia-Pacific Induction Motor Market Segmentation
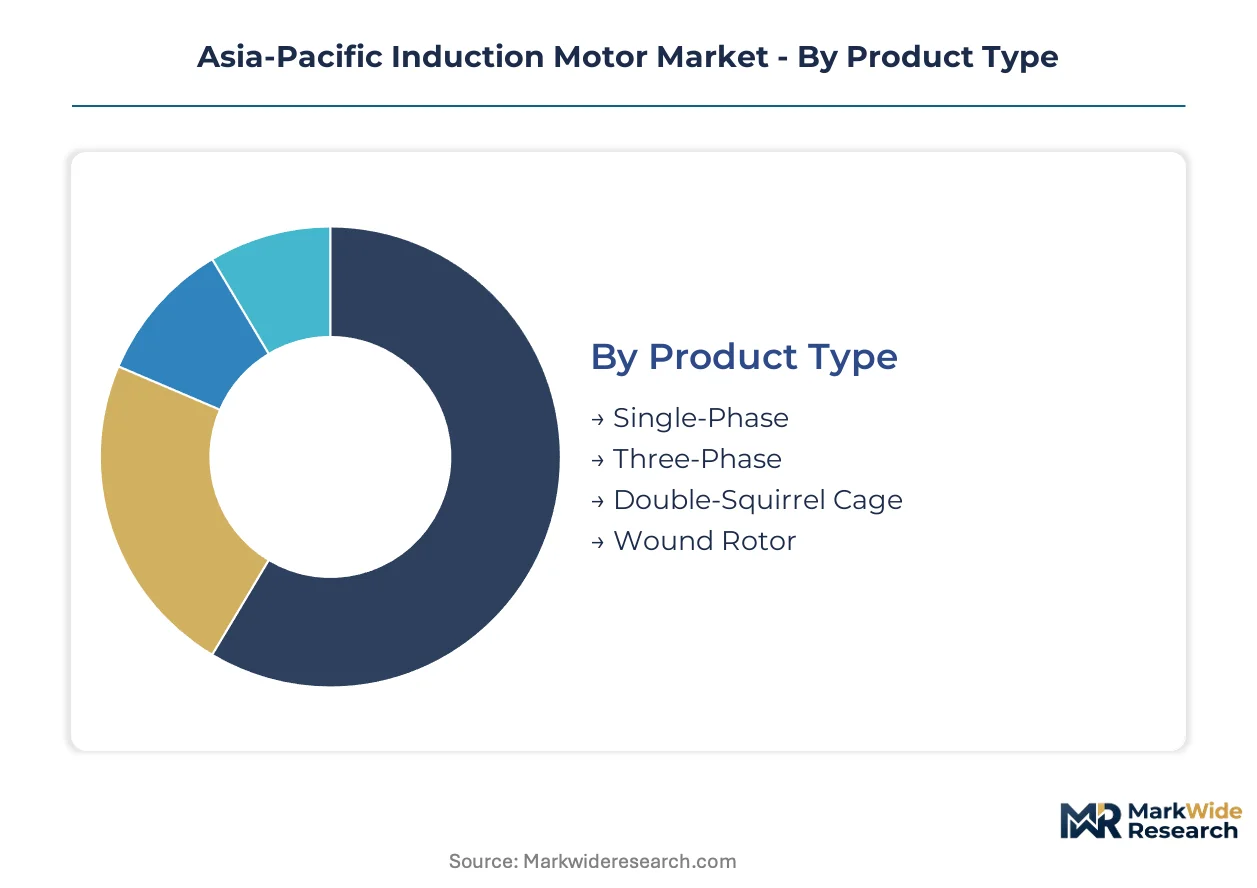
Segmentation in the Asia-Pacific induction motor market reveals how procurement specifications fragment across power infrastructure maturity, industrial automation intensity, and cooling load profiles. Buyers in Vietnam's emerging manufacturing zones prioritize different torque characteristics than established automotive suppliers in Japan's Aichi Prefecture.
Product Type:
Supply concentration for stator laminations and rotor castings heavily favors eastern Chinese foundries, compressing cost structures for standard designs while creating bottlenecks for specialized configurations requiring precision electrical steel.
- Three-Phase:These motors deploy three stator windings energized by alternating current phases displaced by 120 degrees, producing a rotating magnetic field that drives squirrel-cage or wound rotors without slip rings. Demand clusters in China's Yangtze River Delta automotive supply base, where tier-one component manufacturers face mandatory fleet telemetry integration from parent vehicle OEMs.
- Single-Phase:Split-phase or capacitor-start designs energize residential and light commercial installations where three-phase distribution remains uneconomical. India's rural electrification programs and smallholder agricultural pump schemes sustain volume procurement, though BIS efficiency mandates are forcing redesigns of sub-11kW units with premium-grade electrical steel.
- Double-Squirrel Cage:Dual rotor bar configurations deliver high starting torque with reduced inrush current for crushing and grinding applications.
- Wound Rotor:External resistance control via slip rings enables precise speed regulation for hoisting and heavy material handling.
Today's leader: Three-Phase. Tomorrow's challenger: Double-Squirrel Cage.
End User:
Cost tier differentiation separates premium-efficiency procurement in Japanese precision manufacturing from price-sensitive volume buying in Indian textiles and cement processing.
- Manufacturing:Automated production lines in Thailand's Eastern Economic Corridor and Indonesia's Batam island specify integrated motor-drive packages with predictive maintenance capabilities. Semiconductor fabrication facilities in South Korea's Giheung cluster demand clean-room compatible sealing and vibration isolation.
- HVAC:Chiller and air handling units in Singapore's commercial high-rises and Australia's green building developments specify electronically commutated alternatives for part-load efficiency, constraining induction motor share in premium segments.
- Agriculture:India's Bureau of Indian Standards tightened energy-efficiency norms for rotating electrical machines, accelerating replacement demand in groundwater irrigation.
- Renewable Energy:Wind turbine auxiliary systems and solar tracking drives require extended temperature range operation.
Manufacturing commands current procurement volume. Agriculture presents the steepest compliance-driven replacement trajectory.
Installation:
Volume concentration in industrial plant deployments reflects manufacturing automation buildouts, while offshore specifications demand corrosion-resistant enclosures and extended maintenance intervals.
- Industrial Plant:Heavy process industries across China's Shandong and Jiangsu provinces specify flameproof and increased-safety enclosures for hazardous area classification. Desalination facilities in Saudi Arabia's Red Sea coast and UAE's Al Taweelah plant source high-torque three-phase units through Asia-Pacific supply chains.
- Commercial Building:Elevator traction machines and escalator drives in Tokyo's vertical developments and Seoul's mixed-use towers prioritize compact frame sizes and low acoustic signatures.
- Onshore:Standard foot-mounted and flange-mounted configurations dominate procurement for general-purpose machinery.
- Offshore:Platform cranes and marine loading arms require IP56+ ingress protection and tropicalized insulation systems.
Industrial Plant anchors present revenue. Offshore specifications are climbing fastest as Southeast Asian energy infrastructure expands.
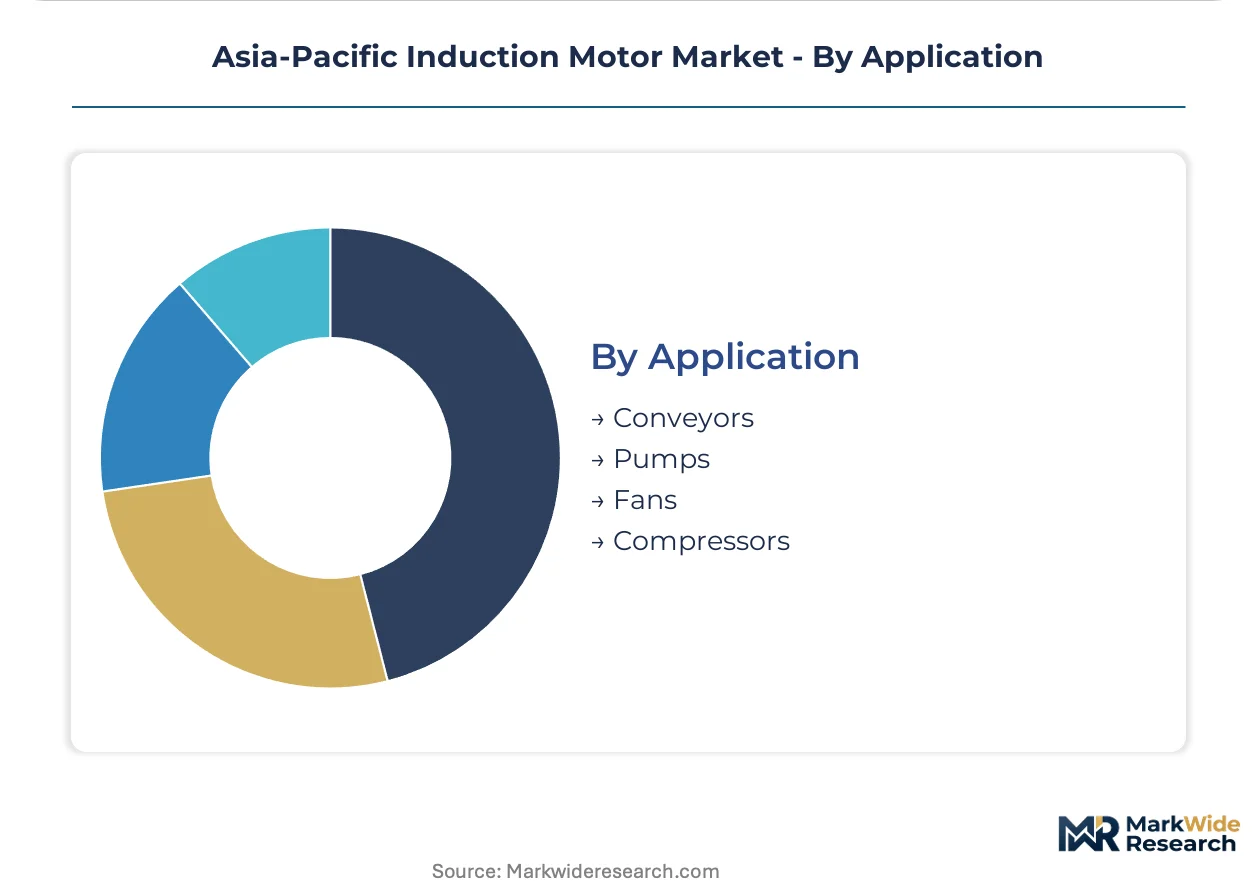
Application:
Application selection increasingly migrates from maintenance departments to central procurement functions with enterprise-level automation frameworks, consolidating vendor panels around system-level performance guarantees.
- Pumps:Centrifugal and positive displacement pump drives in water treatment and desalination infrastructure specify continuous-duty ratings with service factors above 1.15. Vietnam's municipal water utilities and Philippines' Manila Water concession are expanding procurement for raw water intake and distribution booster stations.
- Fans:Forced-draft and induced-draft applications in power generation and steelmaking balance aerodynamic load curves against motor thermal limits.
- Compressors:Rotary screw and centrifugal air compression in pneumatic automation systems demand high starting torque and frequent cycling capability.
- Conveyors:Bulk material handling in Australian mining and Indonesian coal terminals requires high-slip designs for soft starting heavy loads.
Pumps dominate current specification activity. Compressors are gaining share fastest as factory automation intensifies across ASEAN manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Induction motor manufacturing scaled through Japanese electrical conglomerates in the mid-20th century before migrating production capacity to coastal China. The technology spread through Korean chaebols and Indian engineering houses as electrification expanded across emerging economies. Today's procurement patterns reflect this diffusion across distinct national regulatory and industrial frameworks.
China
MIIT efficiency tier mandates force domestic replacement cycles for motors above specified power ratings. GB standards block non-compliant imports while accelerating factory floor upgrades. The Yangtze River Delta automotive supply base concentrates tier-one component procurement with mandatory fleet telemetry integration.
India
BIS tightened energy-efficiency norms for rotating electrical machines above defined kilowatt thresholds. Textile mills and cement processing plants face compliance-driven replacement timelines. Gujarat and Maharashtra industrial corridors absorb premium-grade electrical steel for sub-11kW redesigns.
Japan
METI maintains JIS certification protocols that sustain premium pricing for precision manufacturing applications. Semiconductor fabrication facilities in the Giheung cluster demand clean-room compatible sealing specifications. Domestic producers leverage captive IGBT foundry partnerships for high-voltage system supply security.
South Korea
Silicon carbide production capabilities anchor supply chains for high-voltage motor drive systems. Electronics assembly automation in the Seoul Capital Area specifies integrated motor-drive packages with predictive maintenance telemetry. National industrial policy prioritizes power electronics talent concentration in metropolitan research clusters.
Vietnam
Northern manufacturing zones around Hai Phong and Bac Ninh expand motor procurement for electronics assembly automation. Limited local supplier presence creates procurement windows for foreign integrated automation portfolios. Municipal water utilities in Hanoi and Ho Chi Minh City specify continuous-duty pump drives for distribution infrastructure.
Asia-Pacific Induction Motor Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification tier and integration depth. The vendor base organizes around three strategic archetypes: integrated automation conglomerates bundling motor-drive systems, specialized high-voltage manufacturers with captive semiconductor supply, and regional engineering houses serving price-sensitive procurement. Consolidation pressure intensifies through enterprise vendor panel rationalization and fleet-wide telemetry mandates. Geographic expansion and strategic partnerships dominate competitive maneuvering as manufacturers seek proximity to Southeast Asian manufacturing buildouts.
Within the integrated automation tier, ABB Ltd. and Siemens AG exemplify system-level positioning through digital twin and predictive maintenance capabilities. Toshiba Mitsubishi-Electric Industrial Systems Corporation occupies the high-voltage specialist archetype with semiconductor foundry integration. Kirloskar Electric Company represents the regional engineering house model serving Indian compliance-driven replacement cycles.
| Leading Market Players |
|---|
| Toshiba Mitsubishi-Electric Industrial Systems Corporation |
| Regal Rexnord Corporation |
| ABB Ltd. |
| Kirloskar Electric Company |
| Fuji Electric Co., Ltd. |
| Siemens AG |
| WEG S.A. |
| CG Power Systems |
| Nidec Corporation |
| Others |
Value Chain & Pricing Dynamics
Modular motor-drive bundling from procurement teams across China's Yangtze River Delta automotive supply base is compressing vendor selection cycles and forcing foundries to absorb copper price volatility into long-term contracts. This specification shift toward integrated automation portfolios concentrates pricing power with semiconductor-captive manufacturers while squeezing commodity-tier suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement specifications, with differentiation driven by MIIT GB efficiency certification tiers and captive IGBT production capabilities. Premium pricing attaches to JIS-certified precision manufacturing units from Japanese producers, while Indian textile mills and cement processors face compliance-driven cost escalation for BIS-mandated sub-11kW redesigns. Cost compression in the standard tier intensifies because eastern Chinese foundry concentration enables volume scale economics. Price-sensitive buyers cluster in Indian agricultural pump schemes and Vietnamese electronics assembly zones, whereas Japanese semiconductor fabrication facilities show minimal elasticity for clean-room compatible specifications.
Supply Chain Analysis
Regional distribution centers in Shanghai, Singapore, and Mumbai operate hub-and-spoke patterns for spare parts and aftermarket service inventory. Manufacturing concentration in eastern China, Japan, and South Korea anchors rotor casting and stator lamination supply, with captive silicon carbide production in Korean and Japanese facilities securing high-voltage drive system components. Raw material dependencies center on London Metal Exchange copper pricing, premium-grade electrical steel from Nippon Steel and POSCO, and rare-earth magnet alternatives pressuring induction motor positioning. Single-source vulnerability concentrates in eastern Chinese foundry clusters during regional energy rationing events. Distribution runs through direct OEM relationships for large industrial contracts and authorized distributor networks for replacement motors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in predictive maintenance service contracts and premium-efficiency certification tiers, as copper hedging capabilities and captive semiconductor production separate profitable vendors from commodity players.
For Market Incumbents: Deploy digital twin integration to anchor fleet-wide telemetry mandates from automotive OEM parent companies in the Yangtze River Delta. Permanent magnet substitution in robotics and CNC equipment threatens precision positioning applications previously served by induction technology. Incumbents should deepen backward integration into silicon carbide foundry partnerships to secure high-voltage system supply chains. Channel control through pre-commissioned skid-mounted packages for Thai and Malaysian food processors compresses installation timelines and raises switching costs. For New Entrants and Emerging Players: Capture procurement windows in Vietnam's northern manufacturing zones around Hai Phong and Bac Ninh, where electronics assembly automation buildouts face limited local supplier presence. White-space targets include municipal water utilities in Hanoi and Ho Chi Minh City specifying continuous-duty pump drives, and desalination infrastructure across the Philippines and Indonesia requiring high-torque three-phase units. A go-to-market angle through integrated motor-drive packages with cloud analytics platforms enables recurring revenue streams from predictive maintenance contracts. For Investors and Strategic Acquirers: Asymmetric upside sits with regional engineering houses possessing BIS compliance redesign capabilities and established distribution in Indian industrial corridors. Long-term viability over a multi-year horizon favors manufacturers with captive electrical steel sourcing and power electronics firmware engineering talent concentrated in Tokyo, Seoul, and Shanghai. Acquisition targets should demonstrate semiconductor foundry integration or backward integration into premium-grade lamination production. The signal to watch is reciprocity agreements between BIS, MIIT, and METI on efficiency certification harmonization, which would reshape cross-border procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicon Carbide Foundry Capacity | Secures supply chains for high-voltage motor drive systems against IGBT shortages. |
| Predictive Maintenance Service Contract Expansion | Transforms vibration sensor telemetry into recurring revenue from automotive OEM fleets. |
| BIS Efficiency Compliance Redesign Investment | Captures replacement demand from Indian textile mills and cement processing plants. |
| Vietnam Distribution Hub Establishment | Positions integrated automation portfolios for electronics assembly automation buildouts. |
| Digital Twin Platform Integration | Enables fleet-wide performance guarantees for enterprise procurement consolidation. |
Study Parameters
Coverage spans China, India, Japan, South Korea, and Vietnam, with primary inputs from each market obtained through structured interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads. Secondary validation drew from MIIT GB standard filings, BIS certification registries, METI JIS documentation, customs and trade data for motor imports, and SEC filings from listed electrical equipment manufacturers. Bottom-up sizing of installed base replacement cycles and top-down cross-checks against national efficiency mandate timelines provided triangulation.
Rate-of-change decomposition across the projection horizon modeled volume and value outputs through segment-level CAGRs derived from regulatory replacement timelines and manufacturing automation intensity indices. Segmentation dimensions included product type, end user, installation environment, and application, with additional modeling of efficiency tier migration patterns. Forecast inputs incorporated copper price volatility assumptions, foundry capacity utilization rates, and power electronics talent concentration metrics.
Copper price volatility, regulatory reciprocity delays, and permanent magnet substitution acceleration are the dominant revision risks that could alter replacement cycle timing and premium-tier pricing power. Forecasts reflect documented assumptions on efficiency mandate enforcement intensity and manufacturing automation capex trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Submersible Pump Motor Market
Industrial Motors
Explosion Proof Motor Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Power Scraper Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
HVAC Motors Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Industrial Motor Market
Industrial Motors
Global Induction Motors Market
Industrial Motors
United States DC Motor Market
Industrial Motors
Industrial Personnel and Burden Carriers [Electric] Market
Industrial Motors
AC Motor Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Europe Tank Insulation Market