
 Solar Fountain Pumps Market | 2026-2036
Solar Fountain Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Fountain Pumps Market Insights
Subscription-based remote monitoring and predictive maintenance software is broadening what manufacturers sell beyond hardware alone. LORENTZ leverages its digital pump management platform to anchor recurring revenue streams alongside unit sales. Grundfos Pumps sustains competitive differentiation through deep R&D investment in solar-optimized hydraulics. Shakti Pumps dominates cost-efficient manufacturing scale, positioning its product lines for price-sensitive agricultural and residential segments across South Asia and Africa.
Solar fountain pumps are photovoltaic-driven water circulation devices, typically employing brushless DC motors rated between 5 W and 250 W, designed to move water through decorative or functional features without grid electricity. Their primary commercial purpose spans aesthetic water displays, pond oxygenation, and low-pressure irrigation in off-grid or sustainability-focused settings. Submersible pumps occupy the largest installed base due to silent operation and protection from environmental exposure, while surface pumps command premium positioning in high-flow commercial installations. Solar PV technology leads unit economics, though hybrid systems integrating battery storage represent the fastest-expanding margin pool as consumers demand dusk-to-dawn operation.
EPA WaterSense certification and the EU Green Deal's renewable energy directives shape product efficiency benchmarks and market access conditions for solar-powered water equipment. India's BIS standards and PLI scheme for solar manufacturing create localized compliance requirements that favor domestic assembly over pure imports. The US IRA tax incentives for residential clean energy installations directly reduce consumer acquisition costs in key states. Stakeholders must monitor how evolving net-metering rules and battery pairing mandates in major jurisdictions reshape total system design and vendor selection criteria.
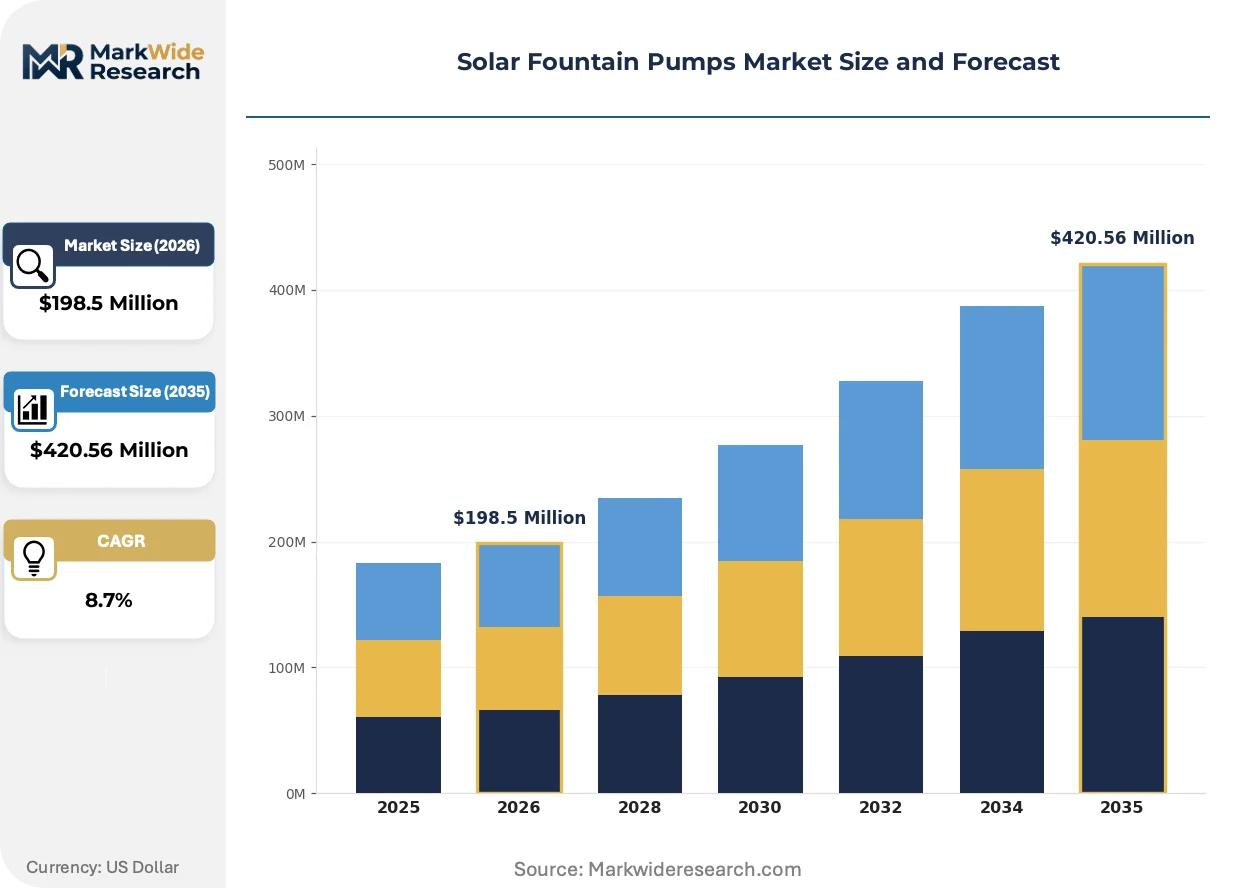
Market Dynamics
Brushless DC motor efficiency gains are compressing energy requirements while simultaneously expanding addressable applications, fundamentally restructuring how manufacturers compete on total system cost rather than component pricing alone.
Growth Catalysts
- EU Green Deal renewable energy directives:Mandates for off-grid renewable installations in decorative water features accelerate replacement cycles across German and Spanish residential developments.
- Suburban water feature culture:Australia, India, and southwestern United States exhibit converging demand patterns where high solar irradiance intersects with aesthetic landscaping preferences.
- Brushless DC motor advances:Efficiency improvements in permanent magnet motor design reduce photovoltaic array sizing requirements, lowering entry cost barriers for budget-conscious agricultural buyers.
Market Restraints
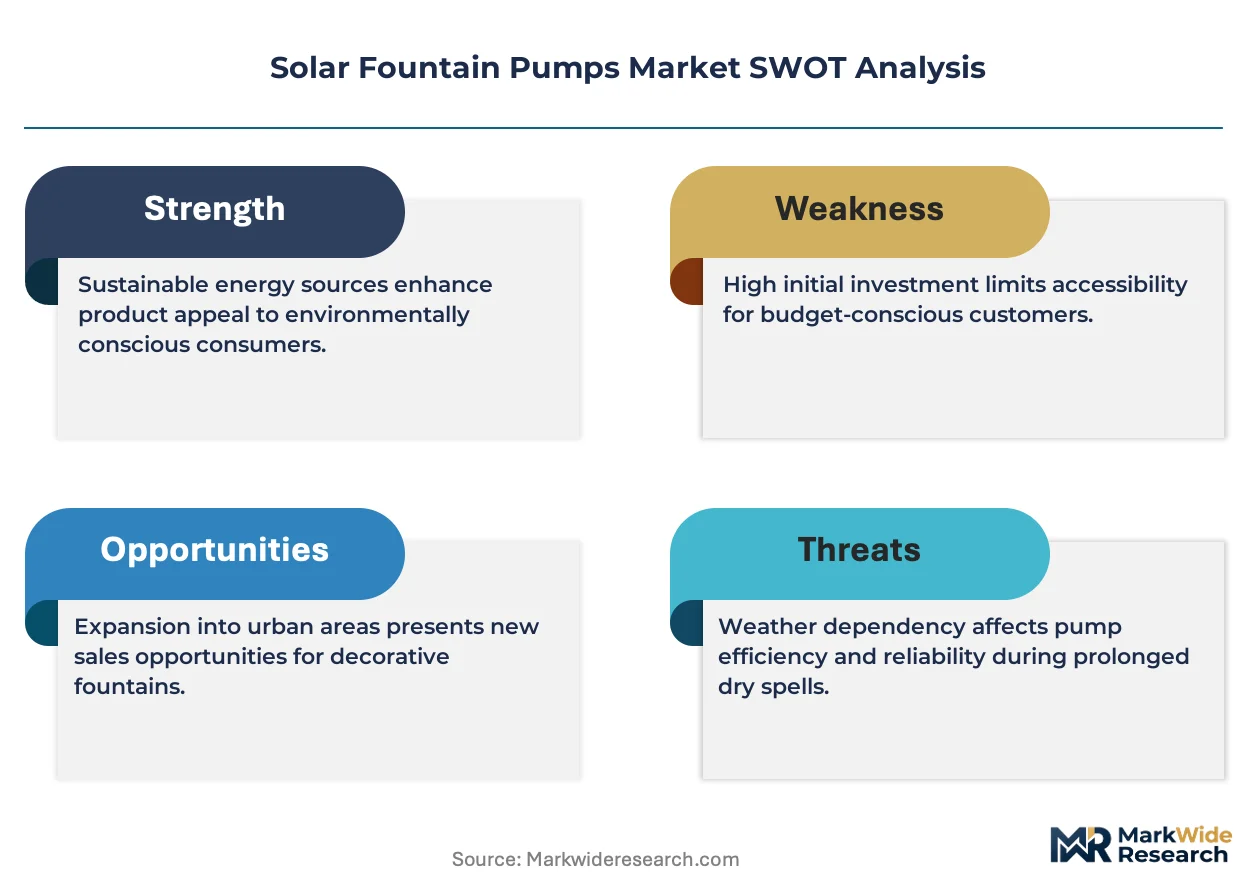
- Photovoltaic panel cost volatility:Crystalline silicon wafer pricing fluctuations transmit directly to system landed costs, compressing assembler margins during supply tightness.
- Battery chemistry constraints:Lithium-ion cell thermal degradation limits dusk-to-dawn operational guarantees in extreme climate zones, restricting hybrid system warranties.
- Grid-powered fountain residual base:Existing AC pump installations with sunk infrastructure costs create substitution friction among commercial property managers.
Strategic Opportunities
- India PLI scheme for solar manufacturing:Domestic assembly incentives favor local production over import-dependent supply chains for South Asian and African market penetration.
- Battery-solar convergence:Hybrid system architectures pairing photovoltaic generation with lithium storage capture premium positioning in residential segments demanding continuous operation.
- Subscription monitoring platforms:Recurring revenue software layers atop hardware sales transform unit economics for vendors with installed base scale.
Industry Challenges
- IP54/68 enclosure certification timelines:Extended testing protocols for submersible pump housings delay product launch windows and inflate development burn rates.
- Brushless motor controller firmware complexity:Embedded software expertise scarcity constrains in-house R&D velocity for mid-tier manufacturers lacking captive electronics capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Fountain Pumps Market |
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Submersible Pumps, Surface Pumps, Centrifugal Pumps, Jet Pumps Technology: Solar PV, Solar Thermal, Hybrid Systems, Wind-Solar Integration Application: Garden Fountains, Pond Aeration, Water Features, Agricultural Irrigation End User: Residential Users, Commercial Landscapers, Agricultural Producers, Municipalities |
| Companies Covered | Shakti Pumps, LORENTZ, Grundfos Pumps, Bright Solar, C.R.I. Pumps Private Limited, Alpex Solar, AQUA Group, Franklin Electric, KSB SE & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Fountain Pumps Market Trends and Innovations
Digital pump management platforms are unifying hardware and software value propositions, while regulatory efficiency mandates and shifting procurement preferences compress traditional sales cycles.
Maximum Power Point Tracking (MPPT) charge controllers are unifying photovoltaic input optimization with pump motor drive electronics into single-board architectures. Residential installers in Germany and California adopt these integrated systems to reduce wiring complexity and installation labor. This convergence is unifying what were separate component procurement decisions into bundled system specifications, favoring vendors with captive semiconductor design capabilities.
The US IRA residential clean energy tax credits reshape consumer acquisition economics across key states. Direct point-of-sale rebates reduce effective system prices without complex depreciation schedules. Suburban developments in Arizona, Texas, and Florida respond fastest, with builders pre-wiring solar fountain circuits to capture incentive-eligible installations during initial construction phases.
Homeowner associations and municipal planners now specify solar-native water features in landscape architecture tenders. Traditional electrical contractor channels face displacement by renewable-focused installers offering bundled photovoltaic, battery, and pump packages. This preference rotation concentrates in master-planned communities across Australia and the southwestern United States where sustainability branding drives property valuation premiums.
Solar Fountain Pumps Market Segmentation
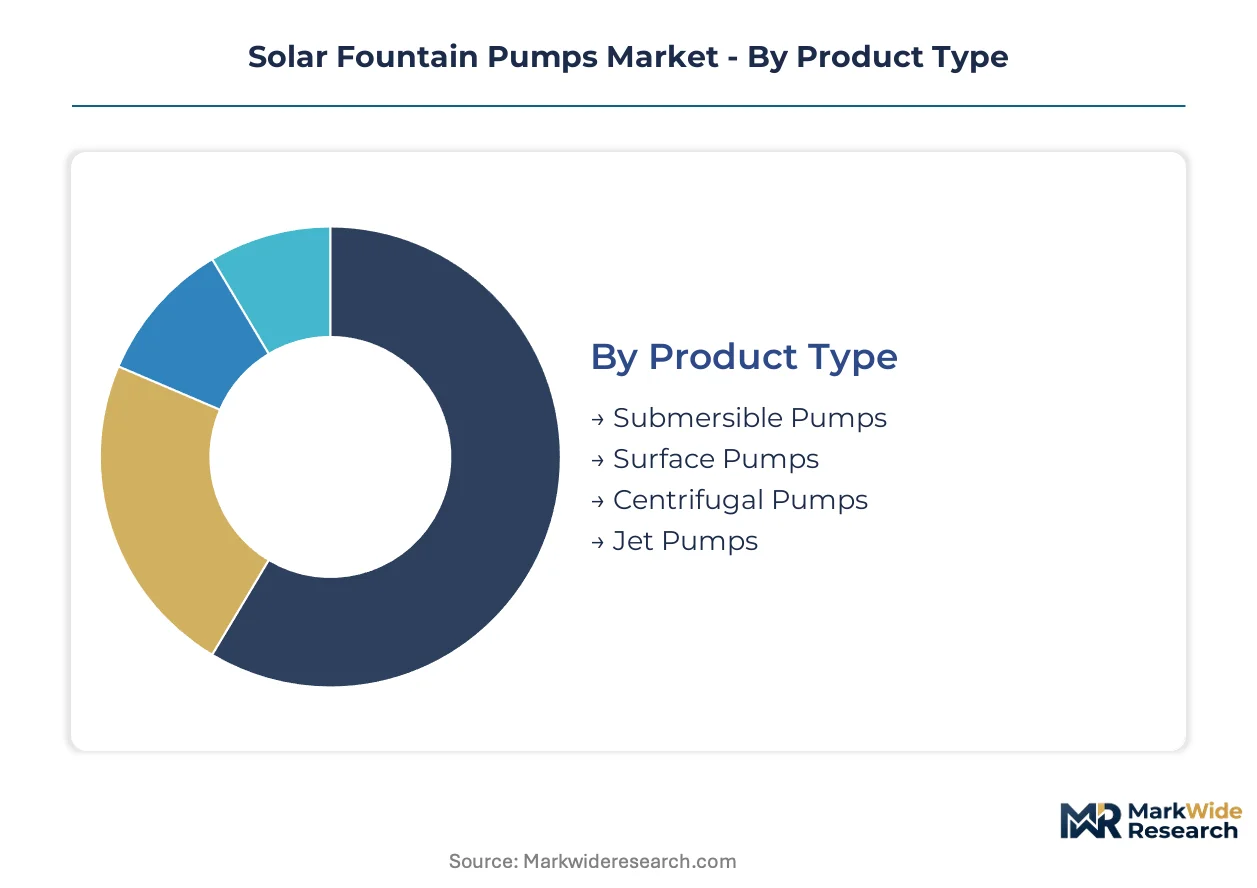
Solar fountain pump procurement decisions fragment across technical specifications, energy architectures, use-case environments, and buyer sophistication levels. Vendors must align product portfolios with distinct margin structures and installation complexity thresholds.
Product Type:
Standalone submersible units dominate residential retrofit installations, while surface-mounted systems embed into commercial infrastructure requiring higher flow rates.
- Submersible Pumps:Brushless DC motors sealed within IP68-rated housings operate silently below waterlines, eliminating noise complaints in dense German suburban developments. Demand clusters in residential garden fountain retrofits across Australia and the southwestern United States where homeowners prioritize aesthetic discretion.
- Surface Pumps:External mounting accommodates larger photovoltaic arrays and battery enclosures, supporting commercial water features with extended operating hours. California landscape architects specify these for municipal plaza installations requiring dusk-to-dawn circulation.
- Centrifugal Pumps:Radial flow impellers handle moderate head pressures for multi-tier fountain designs in Indian residential compounds.
- Jet Pumps:Self-priming suction configurations serve above-ground reservoir applications where submersion depth constraints prevent pump housing immersion.
Volume placements concentrate in Submersible Pumps; the faster expansion belongs to Surface Pumps.
Technology:
Cost tiers separate mature photovoltaic architectures from emerging hybrid configurations commanding premium positioning.
- Solar PV:Crystalline silicon panels paired with direct-drive brushless motors constitute the baseline economics for price-sensitive agricultural buyers across South Asia. The technology anchors utility-scale pond aeration contracts where operational simplicity outweighs intermittent output limitations.
- Hybrid Systems:Photovoltaic generation fused with lithium-ion storage enables guaranteed evening operation, capturing residential segments in Arizona and Texas where homeowner associations mandate continuous water circulation. Battery pairing inflates system costs substantially while unlocking incentive eligibility under US IRA provisions.
- Solar Thermal:Concentrated heat-to-mechanical conversion occupies niche applications in high-insolation desert climates with extreme diurnal temperature swings.
- Wind-Solar Integration:Dual-source generation architectures reduce battery sizing requirements in coastal Mediterranean zones with complementary resource profiles.
Current procurement concentrates in Solar PV; Hybrid Systems are climbing the fastest as battery economics improve.
Application:
Customer type maturity determines whether installations serve decorative, ecological, or productive functions.
- Garden Fountains:Decorative residential water displays in German and Spanish suburban developments drive replacement cycles as EU Green Deal directives accelerate grid-powered system phaseouts. Aesthetic preferences here prioritize pump silence and minimal visual intrusion over raw hydraulic performance.
- Agricultural Irrigation:Low-pressure drip and sprinkler systems in off-grid Indian and African farming operations constitute volume demand, with BIS certification requirements favoring domestic assembly under PLI scheme incentives. Water scarcity regulations in Gujarat and Rajasthan mandate solar-native pumping for groundwater extraction permits.
- Pond Aeration:Dissolved oxygen maintenance for aquaculture and ornamental fish stocking supports commercial landscaper procurement in Florida and Queensland.
- Water Features:Integrated architectural elements in master-planned communities across Arizona and Texas specify solar-native circuits during initial construction phases.
Shipment volumes concentrate in Garden Fountains; Agricultural Irrigation shows the steepest expansion trajectory.
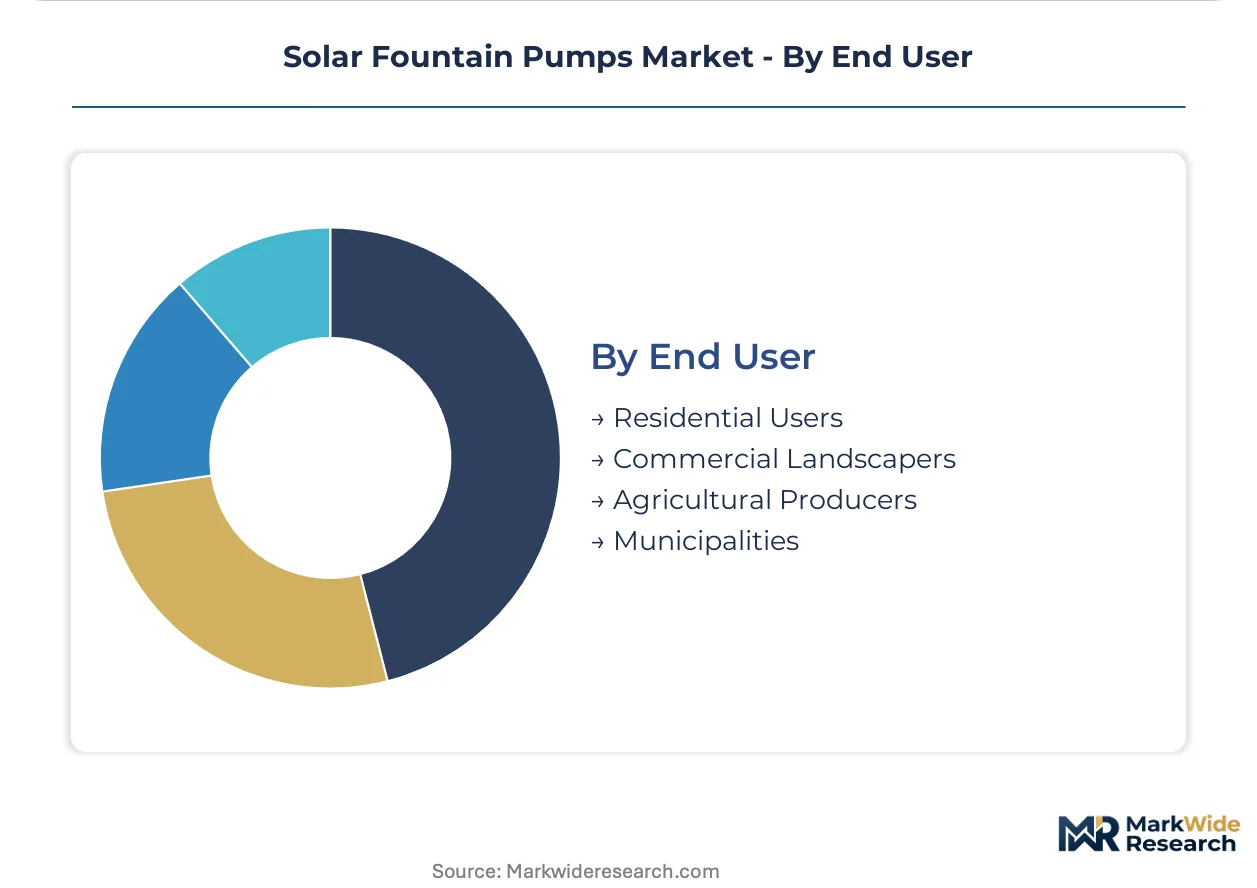
End User:
Buyer sophistication tiers separate specification-driven commercial procurement from price-elastic residential self-installation.
- Residential Users:Individual homeowners purchasing through retail and e-commerce channels exhibit high price elasticity and preference for plug-and-play kits with pre-wired photovoltaic panels. California and German buyers respond to point-of-sale rebate structures that reduce effective acquisition costs without complex tax filings.
- Commercial Landscapers:Professional installation firms serving property management companies and homeowner associations bundle solar fountain systems with broader sustainable landscaping contracts. These buyers demand extended warranties and predictive maintenance platforms that LORENTZ and Grundfos Pumps anchor through subscription software layers.
- Agricultural Producers:Farm operators in water-stressed Indian states prioritize total cost of ownership calculations over upfront capital expenditure, favoring Shakti Pumps cost-efficient manufacturing scale.
- Municipalities:Public procurement tenders in Australian and southwestern US cities increasingly specify solar-native water features for sustainability branding and climate action compliance.
Unit economics concentrate in Residential Users; Commercial Landscapers gain share fastest through bundled service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in India and China where component assembly costs remain lowest, while consumption clusters in high-insolation suburban markets across Germany, the United States, and Australia where homeowner preferences favor off-grid water features.
United States
Suburban developments across Arizona, Texas, and Florida drive residential installations as builders pre-wire solar fountain circuits during construction. The IRA residential clean energy tax credits reduce effective acquisition costs through direct point-of-sale rebates. Municipal planners in California increasingly specify solar-native water features in landscape architecture tenders for sustainability compliance.
Germany
Dense suburban developments prioritize silent submersible pumps for garden fountain retrofits where noise complaints carry regulatory weight. EU Green Deal renewable energy directives accelerate replacement cycles for grid-powered decorative water features. Bavarian homeowner associations now mandate solar-native installations in new residential construction guidelines.
India
Agricultural irrigation applications dominate volume demand across water-stressed Gujarat and Rajasthan where groundwater extraction permits require solar-native pumping. BIS certification standards and PLI scheme incentives favor domestic assembly over import-dependent supply chains. Shakti Pumps anchors manufacturing scale from its base in Pithampur for South Asian and African market penetration.
Australia
Master-planned communities in Queensland and New South Wales specify solar fountain systems for sustainability branding and property valuation premiums. High solar irradiance intersects with aesthetic landscaping preferences in suburban developments across Perth and Adelaide. TGA-equivalent state regulators enforce IP68 enclosure standards for submersible pump certifications.
China
Component manufacturing clusters in the Yangtze River Delta supply photovoltaic panels and brushless DC motors to global assemblers. Domestic demand remains limited compared to export orientation, though coastal municipalities experiment with solar-native water features in public plaza renovations. MIIT efficiency standards shape motor controller specifications for export-bound products.
Solar Fountain Pumps Market Competitive Landscape
Top-tier vendors anchor premium positioning through integrated software-hardware bundles, while mid-tier fabricators compete on manufacturing scale and cost-efficient assembly. The vendor base fragments across three strategic archetypes: digital platform operators capturing recurring revenue, scale manufacturers serving price-sensitive agricultural segments, and R&D-intensive hydraulics specialists defending technical differentiation. Dominant competitive moves include geographic expansion into PLI-incentivized Indian production zones and portfolio diversification toward hybrid battery-solar system architectures.
Within the digital platform tier, LORENTZ exemplifies subscription-based remote monitoring capabilities that transform unit economics beyond hardware sales alone. Grundfos Pumps occupies a position among R&D-intensive hydraulics specialists with captive semiconductor design capabilities for MPPT-integrated architectures. Shakti Pumps represents scale-driven manufacturing dominance from its Indian base, anchoring cost-efficient production for agricultural and residential price-sensitive segments across South Asia and Africa.
| Leading Market Players |
|---|
| Shakti Pumps |
| LORENTZ |
| Grundfos Pumps |
| Bright Solar |
| C.R.I. Pumps Private Limited |
| Alpex Solar |
| AQUA Group |
| Franklin Electric |
| KSB SE & Co. |
| Others |
Pricing and Supply Chain Analysis
Crystalline silicon wafer spot pricing cascades through solar fountain pump supply chains into three-tier pricing structure across premium, standard, and economy levels. Indian PLI scheme incentives compress domestic assembly costs while photovoltaic panel cost volatility transmits directly to landed system prices in import-dependent markets.
Pricing Analysis
Margin tightening in economy-tier agricultural pumps reflects Shakti Pumps manufacturing scale and crystalline silicon input fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates Grundfos Pumps MPPT-integrated architectures from LORENTZ subscription-bundled systems from unbranded direct-drive units. Price differentiation hinges on brushless DC motor efficiency certification and after-sales service bundling. Agricultural producers in Gujarat and Rajasthan exhibit highest price sensitivity; California municipal planners show lowest.
Supply Chain Analysis
Regional distribution centers in Pithampur, Yangtze River Delta, and Bavaria anchor hub-and-spoke patterns for photovoltaic panels, brushless DC motors, and IP68 pump housings. Manufacturing concentrates in India and China where component assembly costs remain lowest. Raw material dependencies span crystalline silicon wafers, neodymium permanent magnets, and lithium-ion cells. Single-source vulnerability in semiconductor motor controllers creates supply chain risk. Distribution runs through renewable-focused installers offering bundled photovoltaic, battery, and pump packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar fountain pumps sit in a technology-transition phase where brushless DC motor efficiency gains displace older brushed motor architectures across residential and agricultural segments.
For Market Incumbents: To counter Shakti Pumps cost-efficient manufacturing scale, Grundfos Pumps and LORENTZ must deepen R&D investment in MPPT-integrated architectures and anchor recurring revenue through predictive maintenance software layers. Certification investment in BIS and EPA WaterSense tiers defends channel access in India and US markets. For New Entrants and Emerging Players: E-commerce direct-to-consumer routes offer lowest barrier entry for plug-and-play residential kits in Australian and southwestern US suburban developments. White-space targets include battery-solar hybrid systems for Arizona homeowner associations and agricultural irrigation in water-stressed African markets. Subscription monitoring platforms provide differentiated go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor R&D-intensive hydraulics specialists with captive semiconductor design capabilities in Germany and California. Long-term viability frames around 5-10 year battery-solar convergence and software-hardware bundling transition. Signal to watch: PLI scheme incentive exhaustion in India reshaping manufacturing cost curves.| Strategic Initiative | Industry Significance |
|---|---|
| MPPT-Integrated Architecture Development | Unifies photovoltaic optimization with motor drive electronics, reducing wiring complexity for German and California installers. |
| Subscription Monitoring Platform Launch | Transforms unit economics through recurring revenue software layers atop hardware sales for LORENTZ and Grundfos Pumps. |
| Domestic Assembly Expansion Under PLI | Leverages Indian manufacturing incentives to serve price-sensitive agricultural segments across South Asia and Africa. |
| Battery-Solar Hybrid System Portfolio | Captures premium residential positioning in Arizona and Texas where homeowner associations mandate continuous operation. |
| IP68 Enclosure Certification Investment | Accelerates product launch timelines and defends market access in Australian and German submersible pump segments. |
Research Methodology
Document review covered customs/trade data, SEC filings, and EIA renewable energy disclosures, complemented by interviews with solar pump manufacturers, renewable-focused installers, agricultural procurement officers, and landscape architects. Primary fieldwork with LORENTZ digital platform operators and Shakti Pumps production heads cross-referenced against secondary validation from EPA WaterSense certification databases and EU Green Deal directive texts. Bottom-up shipment tallies by product type and technology triangulated against top-down market sizing.
Historical volume trajectories cross-referenced against expert panel input on brushless DC motor adoption curves and battery pairing penetration rates. Segmentation modeling spanned product type, technology architecture, application environment, and end-user sophistication across the projection horizon. CAGRs derived from regression analysis of photovoltaic cost decline curves and residential clean energy incentive elasticity. Industry-specific inputs included solar irradiance mapping for installation feasibility and PLI scheme uptake rates for manufacturing cost forecasting.
The model holds under stable crystalline silicon pricing and continued IRA tax credit eligibility; deviation in photovoltaic tariff structures or lithium-ion cell thermal degradation breakthroughs would shift hybrid system adoption trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
North America Positive Displacement Pumps Market
Pumps and Control Devices
Global Solar-Powered Pump Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Asia Pacific Vacuum Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Axial Flow Pump Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Progressing Cavity Pump Market
Pumps and Control Devices
Global Hydraulic Gear Pump Market
Pumps and Control Devices
Water Desalination Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Europe Submersible Pump Market
Pumps and Control Devices
Latin America Positive Displacement Pumps Market
Pumps and Control Devices
High Precision Microfluidic Pump Market
Pumps and Control Devices
Dry Vacuum Pumps Market
Pumps and Control Devices
Global Smart Pumps Market