
 United States DC Motor Market | 2026-2036
United States DC Motor Market Size, Share, and Industry Trends Forecast 2026-2036
United States DC Motor Market Insights
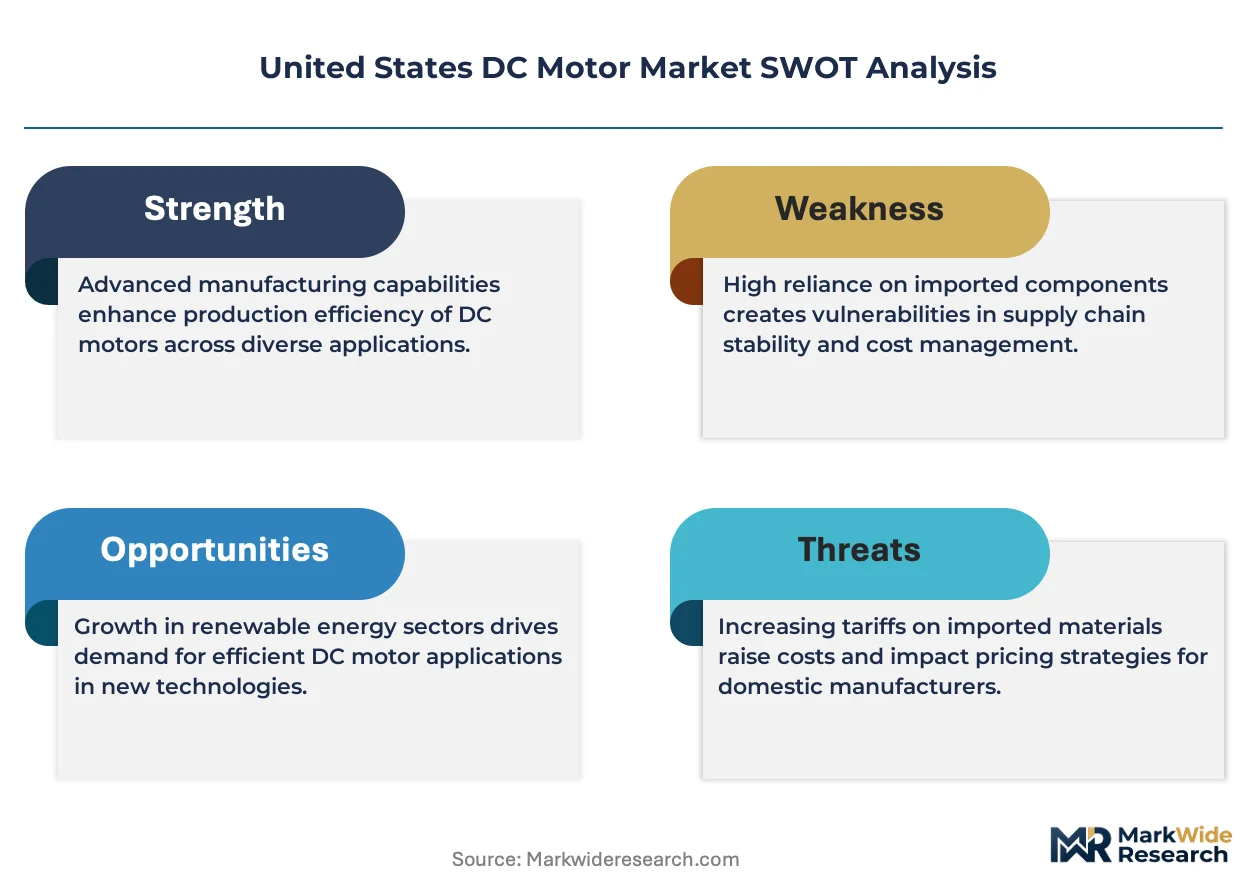
Permanent magnet topology is fragmenting traditional brushed DC architectures across industrial and mobility applications. Nidec Corporation leverages its scale in precision brushless platforms for robotics and medical devices. Siemens AG anchors high-voltage DC systems for rail and heavy machinery through its domestic manufacturing footprint. Allied Motion Inc. specializes in customized motion solutions for aerospace and defense end users.
A DC motor converts direct current electrical energy into mechanical rotation through electromagnetic interaction between stator windings and a rotor, with brushless variants achieving efficiencies above 90% through electronic commutation rather than mechanical brush-rotor contact. The technology powers everything from surgical tools to warehouse automation conveyors. Brushless motor types command premium positioning due to reduced maintenance intervals and superior thermal performance in continuous-duty cycles. Automotive applications absorb the largest volume share as EV traction motors and auxiliary pump drives displace belt-driven mechanical systems. Precision power rating segments attract the highest margins where torque ripple below 1% is mandatory for semiconductor manufacturing equipment.
NHTSA Corporate Average Fuel Economy standards and DOE appliance efficiency regulations are tightening minimum performance thresholds for motor systems sold into transportation and building equipment. EPA energy star specifications and OSHA machine safety directives further constrain product design space for domestic manufacturers. State-level zero-emission vehicle mandates in California and New York are cascading into procurement specifications for fleet operators and transit authorities. Stakeholders must monitor how NHTSA rulemaking on heavy-duty truck electrification reshapes power density requirements and supplier qualification timelines.
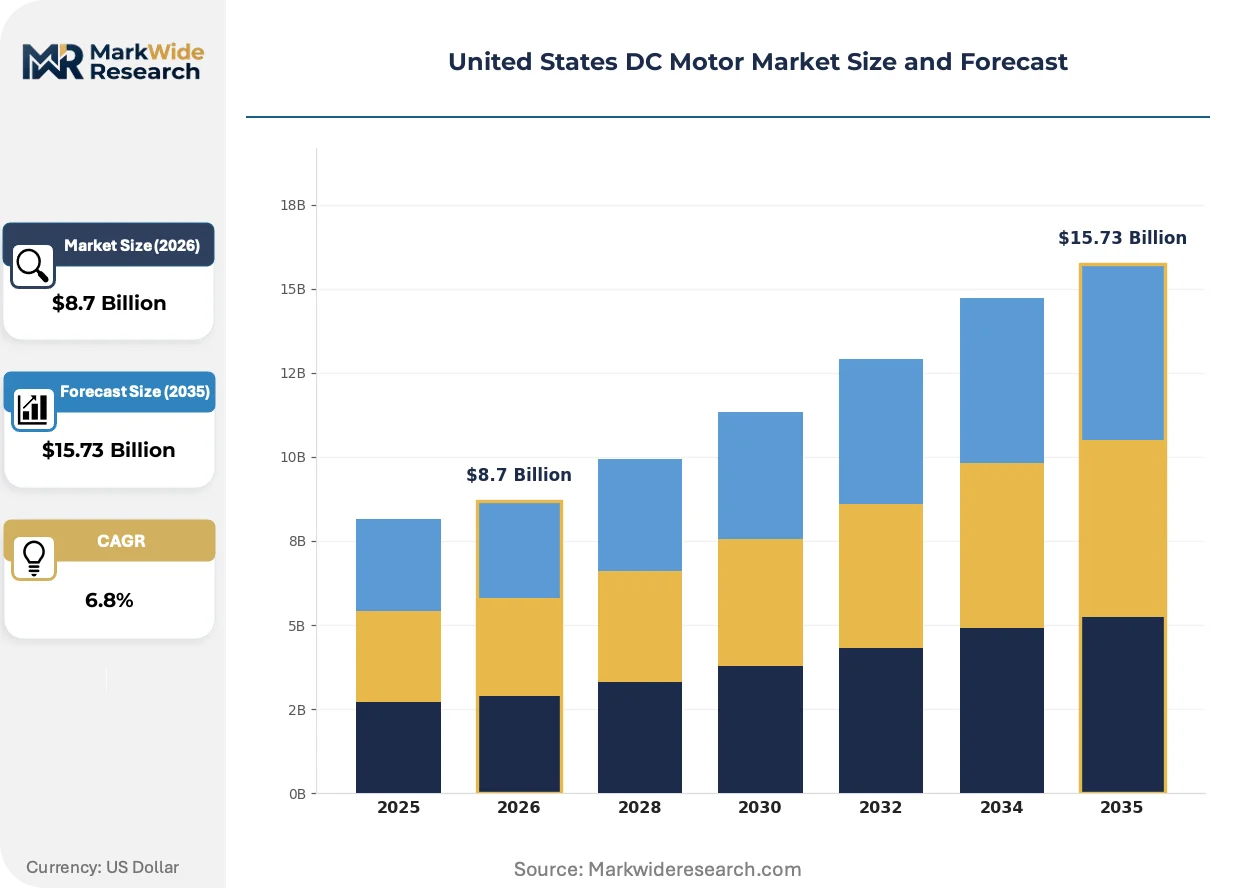
Market Dynamics
Powertrain electrification mandates from NHTSA and California Air Resources Board are compressing supplier qualification timelines while fragmenting motor architectures across brushed, brushless, and wound-field topologies.
Growth Catalysts
- Heavy-duty truck electrification:NHTSA rulemaking on medium- and heavy-duty vehicle emissions is mandating zero-emission powertrains for fleet operators, expanding high-torque brushless motor demand for axle and auxiliary systems.
- Robotics cluster densification:California's semiconductor equipment and warehouse automation corridors are absorbing precision brushless platforms for pick-and-place and wafer-handling applications.
- DOE efficiency mandates:Appliance and industrial motor efficiency regulations are accelerating replacement cycles in HVAC and pump systems across the Midwest manufacturing belt.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on concentrated overseas refining capacity creates input cost volatility for permanent magnet motor producers.
- Copper price cyclicality:Stator and rotor winding material costs fluctuate with commodity markets, compressing margins on cost-competitive brushed motor segments serving price-sensitive industrial buyers.
- Technical limitation in high-temperature environments:Permanent magnet demagnetization thresholds constrain brushless motor deployment in downhole drilling and aerospace propulsion applications requiring sustained operation above 180°C.
Strategic Opportunities
- Texas energy transition corridor:Oilfield electrification and renewable energy manufacturing are creating demand for explosion-proof DC motors in drilling automation and wind turbine pitch control systems.
- Medical device miniaturization:Surgical robotics and portable diagnostic equipment are absorbing coreless and slotless brushless architectures for torque ripple below 0.5% in battery-powered platforms.
- IRA clean energy incentives:Domestic content bonuses for electric vehicle and renewable energy manufacturing are reshoring motor winding and magnet assembly operations to Michigan and Ohio supplier networks.
Industry Challenges
- Power electronics integration complexity:Brushless motor systems require tight coupling between motor windings and inverter control algorithms, demanding cross-functional engineering teams with scarce embedded software and magnetics co-design expertise.
- NHTSA functional safety certification timelines:ASIL-D qualification for automotive traction motors extends development cycles by 18-24 months, straining R&D budgets for Tier-2 suppliers.
- Legacy equipment retrofit friction:Industrial facilities in the Rust Belt face mechanical incompatibility when upgrading from DC brushed to electronically commutated systems, requiring custom mounting adapters and control interface bridges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States DC Motor Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Motor Type: Brushless, Brushed, Stepper, Linear Application: Automotive, Robotics, HVAC, Industrial Machinery Power Rating: Low Power, Medium Power, High Power, Precision End User: Manufacturers, OEMs, Distributors, Aftermarket Providers |
| Companies Covered | ABB Limited, Siemens AG, Nidec Corporation, Maxon, AMETEK Inc., Allied Motion Inc., Johnson Electric Holdings Limited, Regal Rexnord Corporation, Schneider Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States DC Motor Market Trends and Innovations
Silicon carbide power semiconductors and advanced magnet materials are compressing motor-inverter system boundaries while enabling new thermal and efficiency operating envelopes across mobility and industrial applications.
Axial-flux motor topology is hybridizing radial-flux design conventions in electric vehicle traction applications. Detroit-based powertrain engineering teams are adopting pancake-shaped air-gap configurations for packaging density in wheel-hub and inboard axle layouts. This topology is hybridizing supplier value chains by merging traditional motor winding expertise with printed circuit board stator manufacturing capabilities.
NHTSA Corporate Average Fuel Economy standards and EPA greenhouse gas emissions rules are tightening fleet-average efficiency thresholds for light-duty vehicles through 2032. Domestic automakers are responding by eliminating belt-driven accessories in favor of on-demand brushless pump and fan drives. California's zero-emission vehicle mandate is cascading into procurement specifications for transit authorities in New York and Washington, reshaping bus and rail auxiliary motor requirements.
Integrated motor-drive systems are displacing discrete component procurement in warehouse automation and semiconductor manufacturing. End users in Arizona's chip fabrication corridor are specifying sealed IP65-rated brushless platforms with embedded field-oriented control, eliminating separate inverter cabinets and shortening commissioning timelines. This consolidation is most visible in cleanroom environments where particle generation from mechanical commutation is prohibited.
United States DC Motor Market Segmentation
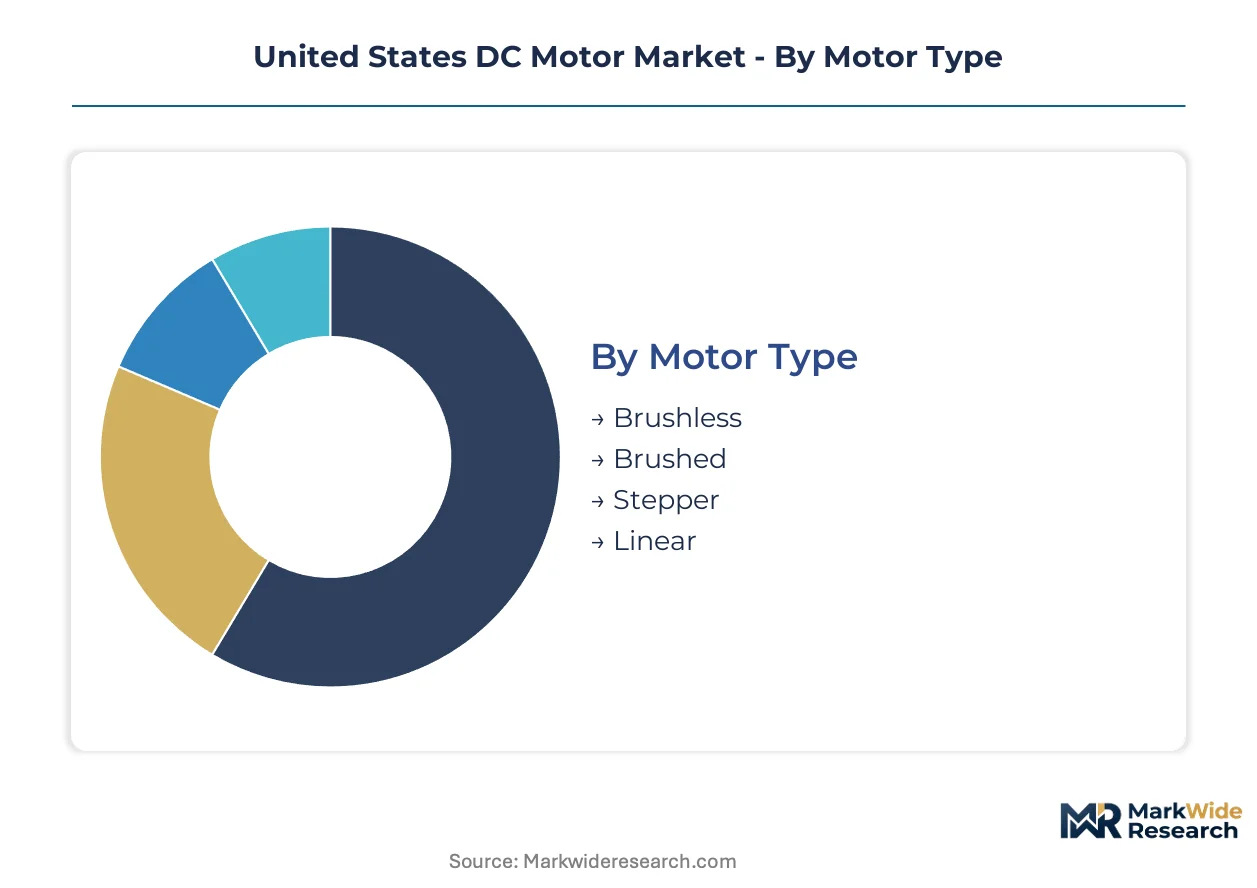
DC motor segmentation in the United States reflects divergent replacement cycles across mobility, industrial, and building systems. Brushless platforms in automotive powertrains turn over on 7-10 year vehicle design cycles, while HVAC aftermarket motors refresh on 15-20 year equipment lifespans. Understanding these rhythm differences shapes inventory positioning and R&D allocation for suppliers serving Detroit's EV corridors versus Midwest industrial belts.
Motor Type:
Replacement velocity varies dramatically: brushless motors in precision robotics refresh every 3-5 years with equipment upgrades, while brushed motors in legacy industrial machinery persist for decades with periodic brush maintenance.
- Brushless:Electronic commutation eliminates mechanical wear components, achieving efficiencies above 90% through permanent magnet rotors and silicon carbide inverters. Demand concentrates in California's semiconductor equipment corridor where NHTSA-backed EV mandates and cleanroom particle restrictions converge.
- Brushed:Carbon brush-rotor contact provides simple speed control but requires maintenance intervals every 2,000-5,000 hours. Cost-sensitive industrial buyers in Ohio and Indiana manufacturing belts specify wound-field architectures for conveyors and pump drives where capital constraints override efficiency premiums.
- Stepper:Discrete angular positioning through toothed rotors and pulsed stator excitation serves CNC machining and 3D printing axes. Texas-based automation integrators deploy hybrid stepper systems for oilfield equipment positioning.
- Linear:Direct thrust generation without rotary-to-linear conversion mechanisms enables precision stages in medical imaging and semiconductor lithography. Arizona chip fabrication facilities specify ironless linear motors for wafer scanning applications.
Brushed architectures anchor the volume base while brushless configurations gain share at the steepest rate.
Application:
Margin structure inverts across these segments: automotive absorbs volume at compressed margins due to OEM procurement power, while robotics commands pricing premiums for torque precision below 1% ripple.
- Automotive:Traction motors and auxiliary drives displace belt-driven mechanical systems under NHTSA fuel economy standards. Detroit powertrain engineering teams specify hairpin-wound stators for axle integration in electric trucks.
- Robotics:Six-axis articulated arms and collaborative cobots demand frameless torque motors with hollow-shaft geometries. California's warehouse automation cluster in the Central Valley sources compact brushless platforms for pick-and-place cells.
- HVAC:Condenser fans and blower motors face DOE efficiency mandates accelerating replacement of shaded-pole induction with electronically commutated DC systems. Florida and Texas residential construction markets drive seasonal demand spikes.
- Industrial Machinery:Extruders, presses, and material handling equipment specify ruggedized DC drives for variable speed control. Pennsylvania steel processing facilities retrofit legacy DC mill motors with modern thyristor controls.
HVAC replacement cycles are shortening under regulatory pressure while robotics applications expand most quickly.
Power Rating:
Customer procurement authority fragments across these tiers: facility engineers specify low-power units directly, while high-power systems require capital committee approval extending sales cycles 6-12 months.
- Low Power:Fractional horsepower drives for small appliances and medical devices operate below 750W. Michigan medical device manufacturers specify coreless brushless motors for surgical handpieces.
- Medium Power:0.75-75kW ratings dominate industrial automation and commercial HVAC. Illinois packaging machinery OEMs integrate medium-power servo systems for motion control.
- High Power:Above 75kW traction and heavy machinery applications require liquid cooling and reinforced bearing systems. Nevada mining equipment operators specify high-torque DC drives for haul truck electrification retrofits.
- Precision:Ultra-low torque ripple and nanometer positioning accuracy command specialized magnetics and control algorithms. Massachusetts semiconductor equipment suppliers specify air-bearing spindle motors for wafer inspection systems.
Medium power ratings anchor the volume base while precision segments command the steepest margin expansion.
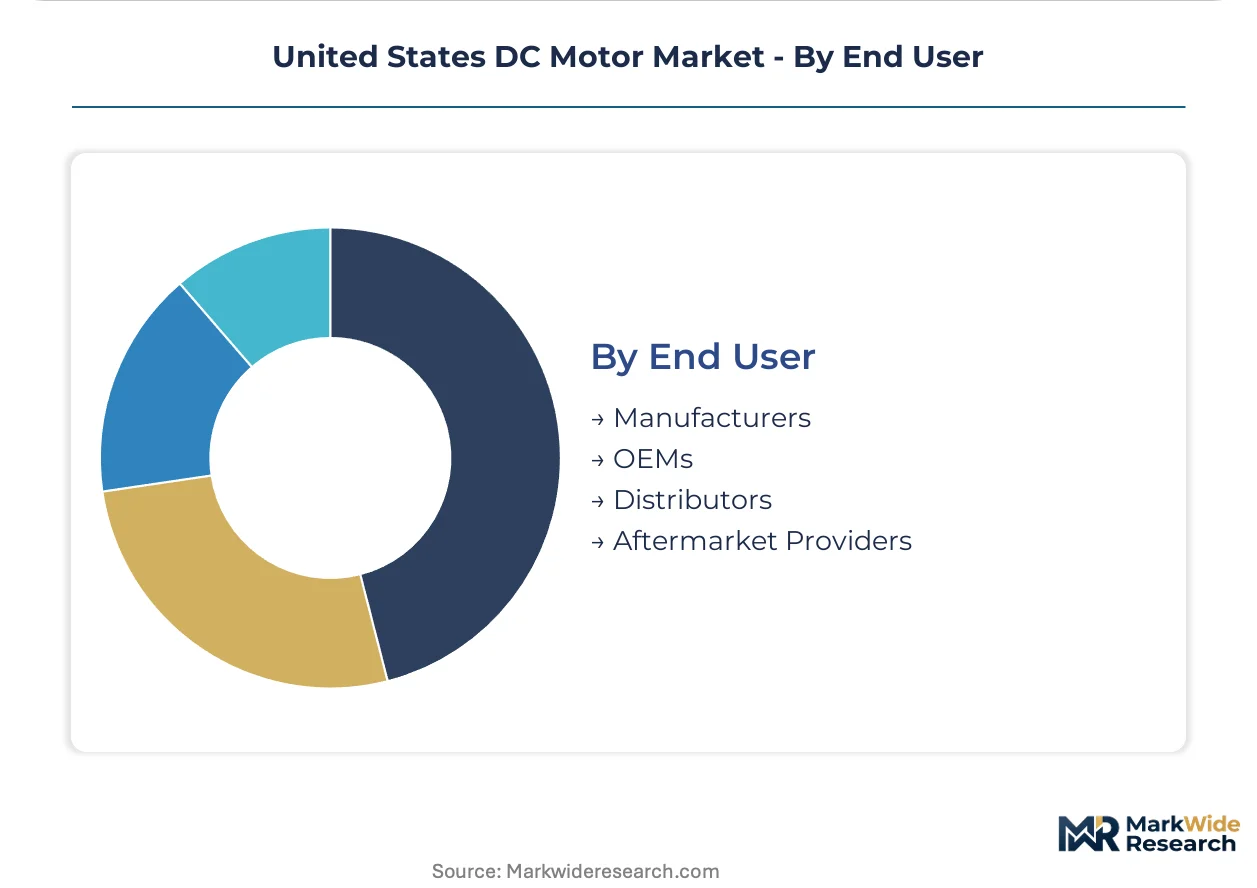
End User:
Channel economics determine service intensity: manufacturers demand engineering collaboration, while aftermarket providers prioritize inventory velocity and cross-reference compatibility.
- Manufacturers:In-house motor production for captive consumption, primarily Nidec and Siemens maintaining domestic winding operations. Ohio and Michigan facilities serve automotive and industrial captive demand.
- OEMs:Original equipment manufacturers integrate motors into downstream systems, specifying custom shaft geometries and connector configurations. Georgia HVAC OEMs source electronically commutated blower motors from regional suppliers.
- Distributors:W.W. Grainger and Rexel maintain stocked inventories for MRO procurement, emphasizing interchangeability and rapid fulfillment. Regional distribution centers in Dallas and Chicago optimize for 24-hour delivery radii.
- Aftermarket Providers:Repair shops and refurbishment specialists service installed base extending equipment life. California fleet operators contract aftermarket providers for electric bus motor rewinding and controller replacement.
OEMs anchor the volume base while aftermarket providers gain share at the steepest rate as installed base electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports wound-field DC motors to Texas oilfield service operators, while Michigan suppliers ship brushless traction platforms to California EV assembly plants. This cross-border trade corridor concentrates procurement authority in Detroit powertrain engineering teams and Houston energy equipment buyers.
Michigan
Automotive powertrain electrification absorbs high-torque brushless motors for electric truck axle integration. NHTSA Corporate Average Fuel Economy standards compress supplier qualification timelines to 18 months. Detroit's supplier belt hosts hairpin-wound stator production for Tier-1 OEM captive consumption.
California
Semiconductor equipment and warehouse automation corridors demand frameless torque motors with hollow-shaft geometries. California Air Resources Board zero-emission vehicle mandates cascade into transit authority procurement specifications. Silicon Valley robotics integrators source precision brushless platforms for cleanroom wafer-handling systems.
Texas
Oilfield electrification and renewable energy manufacturing create demand for explosion-proof DC motors in drilling automation. EPA energy star specifications constrain HVAC motor efficiency thresholds for residential construction markets. Houston energy equipment distributors maintain 24-hour fulfillment radii for Permian Basin operators.
Ohio
Legacy industrial machinery retrofit cycles sustain wound-field DC motor demand in steel processing and extrusion applications. DOE appliance efficiency regulations accelerate replacement of shaded-pole induction with electronically commutated systems. Cleveland-area aftermarket providers service installed base extending equipment life through rewinding operations.
Arizona
Chip fabrication facilities specify ironless linear motors and sealed IP65-rated brushless platforms for wafer scanning applications. OSHA machine safety directives constrain product design space for cleanroom motor systems. Phoenix-area automation integrators deploy integrated motor-drive systems eliminating separate inverter cabinets.
United States DC Motor Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Integrated motor-drive consolidation favors suppliers with embedded software capabilities, while discrete component vendors defend position through interchangeability and rapid fulfillment. Two strategic archetypes dominate: scale-driven platform suppliers and customized motion specialists. M&A activity concentrates winding and magnet assembly operations in Midwest supplier networks, while technology licensing agreements proliferate around silicon carbide inverter integration.
Among diversified industrial conglomerates, ABB Limited and Siemens AG occupy positions anchoring high-voltage systems for rail and heavy machinery through domestic manufacturing footprints. Nidec Corporation exemplifies the scale-driven archetype, leveraging precision brushless platforms for robotics and medical devices. These three entities represent the competitive spectrum from broad industrial coverage to specialized motion solutions.
| Leading Market Players |
|---|
| ABB Limited |
| Siemens AG |
| Nidec Corporation |
| Maxon |
| AMETEK Inc. |
| Allied Motion Inc. |
| Johnson Electric Holdings Limited |
| Regal Rexnord Corporation |
| Schneider Electric |
| Others |
Pricing and Supply Chain Analysis
Neodymium and dysprosium refining concentration in China feeds directly into permanent magnet motor cost structures, concentrating margin capture with magnet processors rather than winding houses or system integrators downstream. Brushless motor manufacturers absorb commodity volatility through long-term offtake contracts while passing efficiency premiums to automotive OEMs.
Pricing Analysis
Current-generation silicon carbide inverter-motor systems command substantial premiums over prior-generation IGBT-based platforms, while next-generation axial-flux topologies are entering pilot pricing. Three-tier pricing structure across premium certified-automotive, standard industrial-grade, and economy brushed-motor tiers reflects NHTSA ASIL-D certification costs versus commodity wound-field alternatives. Cost compression in economy brushed segments is intensifying because copper price cyclicality squeezes margin pools for price-sensitive Midwest industrial buyers. Automotive OEMs exhibit lowest price sensitivity due to regulatory compliance mandates, while HVAC aftermarket distributors face acute sensitivity from contractor procurement committees.
Supply Chain Analysis
Export controls on advanced magnet manufacturing equipment constrain rare earth processing capacity expansion outside China, tightening magnet supply for domestic motor producers. Winding copper draws from Chilean and Peruvian mining operations, while silicon carbide substrates source from Japan, Germany, and emerging US fabrication facilities. Single-source vulnerability concentrates in neodymium oxide refining, where geographic concentration creates tariff exposure and price volatility. Distribution runs through regional stocking distributors in Dallas and Chicago maintaining 24-hour fulfillment radii for MRO procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain electrification fragmentation creates specialist niches across torque density tiers, as NHTSA mandates splinter procurement specifications between light-duty, medium-duty, and heavy-duty vehicle classes. Tier-2 suppliers face compressed qualification timelines that favor focused engineering teams over diversified portfolios.
For Market Incumbents: Entrench position through captive magnet assembly operations in Ohio and Michigan supplier networks, insulating against rare earth supply volatility. Deepen backward integration into hairpin-wound stator production to defend margin pools from emerging axial-flux competitors. NHTSA ASIL-D certification timelines favor incumbents with established validation track records.
For New Entrants and Emerging Players: Pursue white-space opportunities in Texas oilfield electrification and Arizona semiconductor equipment corridors, where explosion-proof and cleanroom specifications create defensible positioning. Medical device miniaturization offers the most penetrable entry vector, with torque ripple below 0.5% requirements favoring coreless brushless architectures. Go-to-market through automation integrators rather than direct OEM sales accelerates reference customer acquisition.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with embedded software capabilities and silicon carbide inverter integration expertise. Long-term viability over the projection horizon rests on magnet-agnostic motor topologies that reduce rare earth dependency. Watch NHTSA heavy-duty truck electrification rulemaking velocity as the inflection signal for high-torque brushless demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Magnet Assembly Reshoring | IRA domestic content bonuses incentivize Ohio and Michigan winding operations expansion. |
| Silicon Carbide Inverter Integration | Tight motor-drive coupling eliminates separate cabinet procurement for Arizona cleanroom deployments. |
| Axial-Flux Topology Development | Pancake configurations enable wheel-hub packaging density for Detroit electric truck programs. |
| Medical Device Certification Pathway | FDA 510(k) clearance for surgical motor platforms opens premium pricing tiers. |
| Explosion-Proof Product Line Extension | Texas oilfield electrification absorbs hazardous-location DC motors for drilling automation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of NHTSA rulemaking dockets, DOE appliance efficiency filings, and SEC 10-K disclosures from publicly traded motor manufacturers. Primary interviews engaged Tier-1 automotive supplier procurement teams, industrial automation integrators, HVAC OEM engineering directors, and aftermarket distribution channel managers. Secondary validation drew from EIA manufacturing energy data, EPA Energy Star specifications, and customs trade records. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Forecast inputs include motor type substitution rates, powertrain electrification penetration curves, and regional manufacturing cluster development. Segmentation dimensions span motor topology, power rating tier, application vertical, and end-user channel. CAGRs derive from regression analysis against historical replacement cycle data and regulatory mandate implementation schedules. NHTSA fuel economy standard stringency and IRA clean energy incentive uptake serve as primary demand-side forecast anchors across the modeling period.
Sensitivities concentrate around rare earth magnet price volatility, copper commodity cyclicality, and NHTSA rulemaking acceleration or delay. Forecasts reflect assumptions on supplier qualification timeline compression and embedded software talent availability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Gear Motor Market
Industrial Motors
Vertical Gear Motor Market
Industrial Motors
Servo Motors and Drives Market
Industrial Motors
Fractional Horsepower Motor Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
Global Sliding Vane Air Motor Market
Industrial Motors
Spargers Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
HVAC Motors Market
Industrial Motors
United Kingdom AC Motors Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Seamless Steel Gas Cylinders Market
Industrial Motors
Food Grade Hydraulic Oil Market