
 North America Traffic Signal Recognition Market | 2026-2036
North America Traffic Signal Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
North America Traffic Signal Recognition Market Analytics
Fleet operator procurement is collapsing as automotive OEMs capture the dominant share of traffic signal recognition deployments. Mobileye anchors its position through integrated camera-computer vision stacks that reduce Tier 1 integration costs. Continental AG competes with sensor fusion platforms that combine radar validation with optical recognition. Aptiv differentiates through software-defined architectures that allow post-deployment algorithm updates across vehicle lifecycles.
Traffic signal recognition encompasses the real-time detection, classification, and state interpretation of roadway traffic control devices using camera-based imaging systems operating at 30-60 frames per second, typically paired with convolutional neural networks trained on region-specific signal geometries. The technology serves primarily to enable autonomous and assisted driving systems to respond appropriately to intersection controls without human intervention. Camera hardware and embedded algorithms represent the most mature revenue pools, while deep learning training software captures the fastest expansion as OEMs demand continuous model refinement against edge-case scenarios. Machine learning frameworks still occupy the largest installed base, though computer vision specialization is displacing general-purpose approaches in premium ADAS tiers.
NHTSA mandates shape functional safety requirements for forward-facing recognition systems, while Transport Canada enforces comparable performance standards under its own motor vehicle safety regulations. The Federal Communications Commission governs spectrum allocation for vehicle-to-infrastructure communication links that may eventually supplement optical recognition. Stakeholders must monitor whether NHTSA advances rulemaking on automated driving system performance metrics that would redefine minimum acceptable detection ranges and weather-condition operability.
Market Dynamics
Camera-computer vision stacks are consolidating control over traffic signal recognition deployment as automotive OEMs internalize Tier 1 integration functions previously outsourced to specialized suppliers.
Growth Catalysts
- NHTSA crash-avoidance standards:Updated functional safety requirements for forward-facing recognition systems mandate higher-resolution sensor architectures across vehicle platforms.
- Autonomous vehicle testing corridors:Dense deployment zones in Arizona and California generate sustained demand for real-time signal state interpretation at 30-60 frames per second.
- Convolutional neural networks:Region-specific training on southwestern United States signal geometries improves detection accuracy for Level 2+ ADAS platforms.
Market Restraints
- High-resolution sensor costs:CMOS image sensors and embedded processing units impose capital intensity on recognition system manufacturing.
- Weather-condition operability gaps:Optical recognition performance degrades under heavy precipitation and low-illumination scenarios that radar validation cannot fully compensate.
- Spectrum allocation uncertainty:FCC vehicle-to-infrastructure communication timelines remain undefined, delaying potential optical-radar fusion supplementation.
Strategic Opportunities
- Software-defined architectures:Post-deployment algorithm update capabilities extend revenue capture across vehicle lifecycles.
- Deep learning training software:Continuous model refinement against edge-case scenarios represents expanding service revenue pools.
- Sensor fusion platform integration:Radar validation combined with optical recognition opens premium ADAS tier positioning.
Industry Challenges
- Computer vision specialization talent scarcity:Embedded systems engineers with convolutional neural network optimization expertise command premium compensation.
- Multi-jurisdictional compliance complexity:NHTSA and Transport Canada maintain non-harmonized performance standards requiring dual certification pathways.
- Legacy machine learning framework migration:General-purpose approaches in installed base systems resist displacement by specialized computer vision stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Traffic Signal Recognition Market |
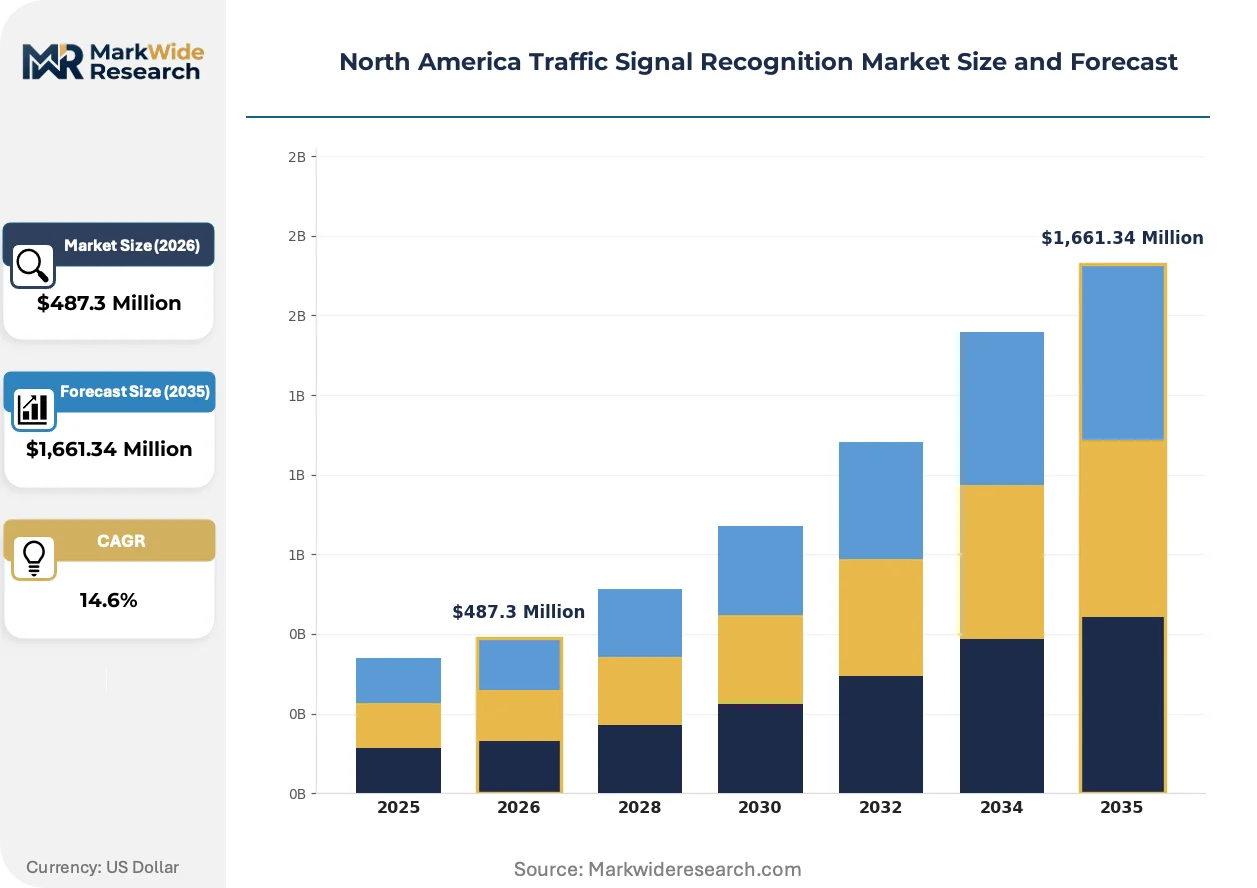
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Training Software, Algorithms, Sensors, Cameras Technology: Machine Learning, Computer Vision, Deep Learning, Image Processing End User: Automotive OEMs, Transport Authorities, Fleet Operators, Smart City Planners Application: Traffic Management, Autonomous Vehicles, Driver Assistance, Urban Mobility |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, HELLA GmbH & Co. KGaA, Mobileye, Toshiba Corporation, Aptiv, Valeo, Ford, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Traffic Signal Recognition Market Evolving Landscape
Recognition system architectures are pivoting from hardware-centric margins toward software-enabled recurring revenue as algorithm update capabilities reshape supplier-OEM relationships.
Specialized computer vision stacks are displacing general-purpose machine learning frameworks in premium ADAS tiers. Automotive OEMs deploying Level 2+ platforms demand embedded algorithms optimized for real-time intersection control interpretation. This displacement compresses Tier 1 supplier margins while expanding in-house engineering headcounts at vehicle manufacturers.
NHTSA rulemaking on automated driving system performance metrics is advancing detection range and weather-condition operability standards. The industrial consequence forces suppliers toward redundant sensor fusion architectures combining optical and radar validation. Southwestern United States testing corridors face the most immediate compliance pressure given existing autonomous vehicle concentration.
Fleet procurement concentration is collapsing as direct OEM-supplier relationships replace intermediary purchasing. Tier 1 integrators that previously aggregated component demand now face disintermediation by vertically integrated camera-computer vision providers. Arizona and California autonomous vehicle operators exemplify this channel compression through direct algorithm licensing arrangements.
North America Traffic Signal Recognition Market Segmentation
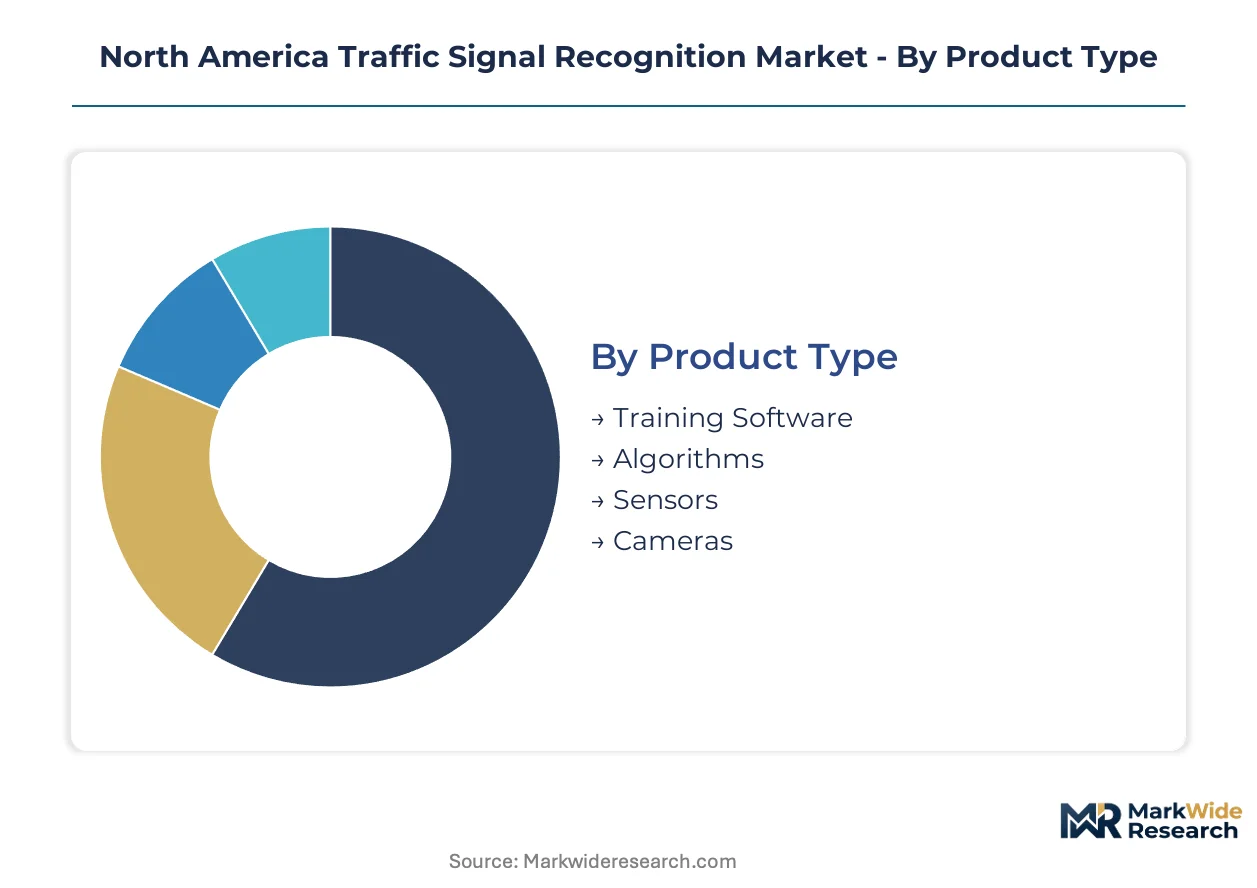
Traffic signal recognition deployment varies sharply by implementation layer, from embedded hardware through algorithmic software. Understanding these segment boundaries clarifies where automotive OEMs concentrate procurement versus where specialized suppliers retain pricing power.
Product Type:
Margin pools concentrate in software layers where recurring update revenue extends across vehicle lifecycles, while hardware components face commoditization pressure from CMOS sensor volume manufacturing.
- Training Software:Deep learning model refinement platforms process region-specific signal geometries and edge-case scenarios. Arizona and California autonomous vehicle operators drive concentrated demand for continuous dataset expansion against southwestern United States intersection controls.
- Algorithms:Embedded convolutional neural networks execute real-time state interpretation at 30-60 frames per second. NHTSA crash-avoidance standards push automotive OEMs toward higher-complexity detection architectures that validate classification confidence thresholds.
- Sensors:Radar and LiDAR validation modules supplement optical recognition under degraded weather conditions.
- Cameras:Forward-facing CMOS image sensors capture roadway traffic control device imagery for downstream processing.
The dominant share belongs to Cameras, while Training Software is closing the gap fastest.
Technology:
Technology selection determines whether recognition systems operate as general-purpose platforms or specialized embedded stacks optimized for automotive safety integrity levels.
- Machine Learning:Legacy statistical approaches retain installed base presence across early ADAS deployments but resist displacement by specialized computer vision architectures. Transport Canada and NHTSA maintain non-harmonized certification pathways that complicate framework migration timelines.
- Computer Vision:Purpose-built embedded stacks optimized for real-time intersection control interpretation displace general-purpose alternatives in premium ADAS tiers. Southwestern United States testing corridors generate sustained validation demand for region-specific signal geometry detection.
- Deep Learning:Convolutional neural network architectures enable end-to-end signal state classification without hand-engineered feature extraction.
- Image Processing:Preprocessing pipelines enhance raw sensor output for downstream algorithmic consumption.
Computer Vision commands the dominant revenue position, with Deep Learning expanding most quickly as automotive OEMs internalize Tier 1 integration functions.
End User:
Customer type segmentation reveals channel compression dynamics as direct OEM-supplier relationships displace intermediary procurement structures.
- Automotive OEMs:Vehicle manufacturers deploying Level 2+ ADAS platforms internalize previously outsourced Tier 1 integration. NHTSA updated functional safety requirements mandate direct supplier accountability for forward-facing recognition system performance.
- Transport Authorities:Municipal and state departments of transportation deploy infrastructure-mounted recognition for intersection monitoring and signal timing optimization. California and Arizona departments prioritize integration with autonomous vehicle testing corridor coordination systems.
- Fleet Operators:Commercial vehicle aggregators face collapsing procurement concentration as automotive OEMs capture dominant deployment share.
- Smart City Planners:Urban technology coordinators embed recognition within multimodal mobility management platforms.
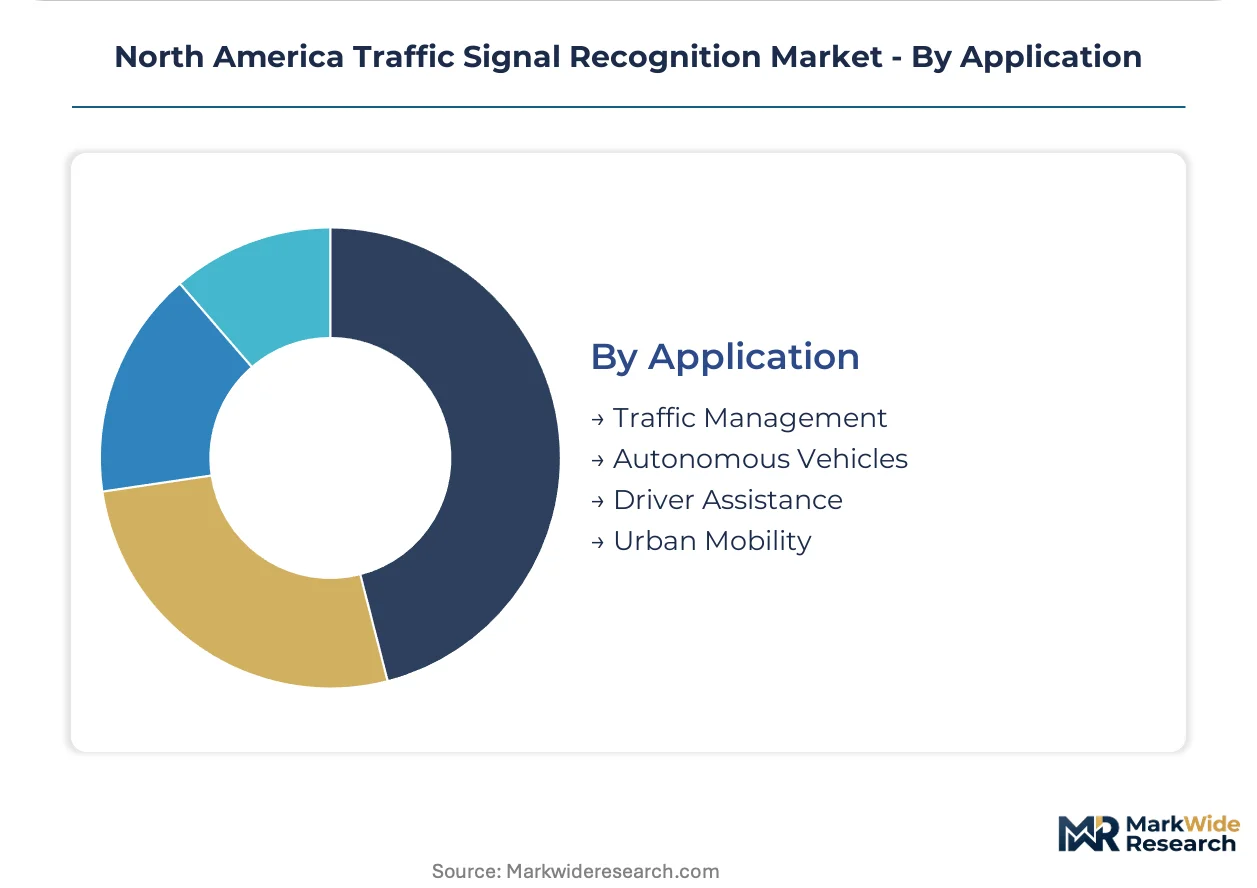
Automotive OEMs hold the dominant share, while Transport Authorities are gaining ground fastest through infrastructure-vehicle coordination mandates.
Application:
Application scope determines whether recognition systems serve human driver augmentation or full automation replacement functions.
- Autonomous Vehicles:Self-driving platforms require redundant signal state interpretation without human fallback. Dense deployment zones in Arizona and California generate sustained demand for real-time performance under diverse illumination and weather conditions.
- Driver Assistance:Level 2+ ADAS platforms augment human perception with warning or limited control intervention capabilities. NHTSA rulemaking on automated driving system performance metrics advances detection range and weather-condition operability standards.
- Traffic Management:Centralized systems optimize signal timing and congestion response across urban networks.
- Urban Mobility:Multimodal platforms coordinate pedestrian, cyclist, and vehicle flow through shared intersection controls.
Driver Assistance captures the dominant deployment volume, though Autonomous Vehicles is climbing the fastest as testing corridors expand operational design domains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 10 corridor underwrites southwestern United States dominance in traffic signal recognition deployment, connecting Arizona and California testing zones through high-capacity freight and passenger networks that demand autonomous vehicle interoperability.
United States
Arizona and California host the densest autonomous vehicle testing corridors, generating sustained procurement of camera-based recognition systems. NHTSA updated crash-avoidance standards mandate higher-resolution sensor architectures across Level 2+ ADAS platforms. Phoenix and Tucson metropolitan clusters concentrate validation facilities for convolutional neural networks trained on southwestern signal geometries.
Canada
Transport Canada enforces motor vehicle safety regulations comparable to NHTSA standards, creating dual certification pathways for cross-border suppliers. Ontario and Quebec automotive manufacturing corridors drive integration demand for forward-facing recognition systems. Toronto-Waterloo tech clusters host algorithm development for winter-condition operability enhancement.
Mexico
Automotive OEM assembly expansion in Nuevo León and Bajío Region generates tiered supplier demand for embedded vision systems. The Secretariat of Economy's automotive sector programs incentivize ADAS component localization. Mexico City Metro congestion management pilots deploy infrastructure-mounted recognition for signal timing optimization.
North America Traffic Signal Recognition Market Competitive Landscape
Concentration sits with integrated camera-computer vision providers that have absorbed Tier 1 integration functions previously outsourced to specialized suppliers. The vendor base compresses around three strategic archetypes: automotive OEMs with captive recognition development, Tier 1 sensor fusion specialists, and software-defined architecture providers. Dominant competitive moves include direct algorithm licensing arrangements that disintermediate traditional procurement channels and strategic partnerships between semiconductor foundries and embedded vision stack developers.
Among German-based automotive suppliers, Robert Bosch GmbH and Continental AG exemplify sensor fusion platform providers that combine optical recognition with radar validation. Mobileye anchors the integrated camera-computer vision archetype through reduced integration cost structures. These three companies occupy positions across the premium ADAS tier where specialized computer vision stacks displace general-purpose machine learning frameworks.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| HELLA GmbH & Co. KGaA |
| Mobileye |
| Toshiba Corporation |
| Aptiv |
| Valeo |
| Ford |
| Others |
Value Network & Pricing Analysis
CMOS sensor foundry capacity utilization above 85% in Taiwan and South Korea concentrates cost advantages among integrated camera-stack providers, compressing margins for modular component suppliers while establishing price floors for embedded vision systems serving NHTSA-mandated Level 2+ platforms.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Premium tiers command NHTSA compliance validation and radar-optical fusion capabilities, while economy tiers serve aftermarket retrofit markets. Cost compression in standard-tier camera modules is intensifying because automotive OEMs internalize Tier 1 integration functions. Fleet operators exhibit highest price sensitivity; captive OEM engineering teams show lowest.
Supply Chain Analysis
Inbound logistics costs through Los Angeles-Long Beach port complexes and cross-border maquiladora corridors feed into landed cost calculations for embedded processing units. Taiwan, South Korea, and Japan anchor CMOS image sensor supply. Germany and Mexico provide radar validation modules. Single-source vulnerability in advanced node semiconductor fabrication poses structural risk. Distribution runs through direct OEM procurement channels that disintermediate traditional Tier 1 aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM consolidation into direct supplier relationships has shifted buyer power decisively toward vehicle manufacturers, fragmenting procurement influence previously concentrated among fleet operators and Tier 1 integrators.
For Market Incumbents: Shield algorithmic IP through software-defined architecture investments that enable post-deployment update revenue capture. Deepen sensor fusion capabilities combining optical and radar validation to defend against pure-play computer vision entrants. Prioritize NHTSA certification pathway acceleration as regulatory compliance becomes the primary competitive moat. For New Entrants and Emerging Players: Differentiate on winter-condition operability algorithms addressing Transport Canada performance standards that incumbent southwestern United States training datasets underserve. Target Ontario and Quebec automotive manufacturing corridors where OEMs seek dual-certification suppliers. Pursue direct licensing arrangements with mid-tier OEMs bypassing established Tier 1 channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-defined architecture providers with post-deployment algorithm update capabilities. Five-to-ten year viability favors suppliers with captive training data pipelines from autonomous vehicle testing corridor relationships. Monitor NHTSA automated driving system performance metric rulemaking as inflection indicator for sensor fusion platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Architecture Investment | Post-deployment algorithm updates extend revenue capture across vehicle lifecycles under NHTSA evolving standards. |
| Sensor Fusion Platform Development | Radar-optical validation combinations address weather-condition operability gaps in Arizona and California testing corridors. |
| Dual-Certification Pathway Establishment | Parallel NHTSA and Transport Canada compliance opens cross-border procurement for Ontario and Quebec OEMs. |
| Training Data Pipeline Acquisition | Region-specific signal geometry datasets from southwestern United States corridors improve convolutional neural network accuracy. |
| Direct OEM Licensing Arrangement | Bypassing Tier 1 integrators captures margin compression from automotive OEM vertical integration trends. |
Research Methodology
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, autonomous vehicle testing corridor operators, and embedded vision algorithm developers provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against NHTSA regulatory filings, Transport Canada motor vehicle safety standards, FCC spectrum allocation dockets, vehicle production databases, and semiconductor foundry capacity disclosures. Bottom-up component demand modeling and top-down OEM deployment forecasts underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and application scope, with additional stratification by regional regulatory cluster and ADAS tier penetration. CAGRs derived from installed base growth rates and replacement cycle dynamics, incorporating convolutional neural network training software expansion curves and sensor fusion platform adoption trajectories as industry-specific inputs.
Material uncertainties — NHTSA rulemaking timing, FCC vehicle-to-infrastructure spectrum allocation decisions, and winter-condition algorithm performance validation — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and OEM internalization trends that sustained deviation would revise. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Thailand Ride Hailing Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Personal Transporter Market
Smart Transportation Solutions
Scooter Sharing Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Traffic Signal Controller Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Air Taxi Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Physical Internet (PI) Market