
 E-Scooter Sharing Market | 2026-2036
E-Scooter Sharing Market Size, Share, and Industry Trends Forecast 2026-2036
E-Scooter Sharing Market Intelligence
Urban fleet deployment channels is fragmenting as city permit systems multiply and operator concessions shrink to shorter renewal cycles. Tier Mobility dominates German-speaking markets through direct municipal partnerships. Bird Rides Inc. leverages its battery-swapping infrastructure to sustain operational uptime in dense North American corridors. LimeBike Inc. competes across Southern European cities where seasonal tourism creates asymmetric demand spikes.
E-scooter sharing denotes a short-distance urban mobility service deploying electric kick-scooters via app-based unlock systems, typically integrating GPS tracking, IoT connectivity, and swappable lithium-ion battery packs rated for 25-45 km per charge. The service targets last-mile connectivity gaps between transit hubs and final destinations. Large fleet operators capture disproportionate margin pools through volume-based supplier negotiations and centralized maintenance protocols. Dockless charging infrastructure leads deployment preference among operators seeking rapid fleet repositioning flexibility. Subscription service types attract commuter segments seeking predictable monthly mobility budgeting against variable pay-per-ride alternatives.
FCC certification governs IoT telemetry hardware deployed across United States fleets, while CE marking mandates electromagnetic compatibility and battery safety standards for European market access. EMA and national transport authorities in France and Germany impose operational caps on fleet density per square kilometer, directly constraining deployment scale and revenue potential per concession. Stakeholders must monitor evolving battery recycling directives and pedestrian safety ordinances as municipalities recalibrate street allocation priorities between micromobility lanes and expanded pedestrian zones.
Market Dynamics
Municipal permit fragmentation is compressing operator margins as cities impose shorter concession cycles and stricter fleet caps, forcing providers to renegotiate access terms every 12-24 months rather than securing multi-year monopolies.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated gases are accelerating fleet electrification timelines across European urban mobility programs, expanding compliant vehicle procurement pools.
- Dockless charging infrastructure:Battery-swapping station networks enable rapid fleet repositioning without fixed docking points, improving vehicle utilization rates in high-density corridors.
- Germany:Federal transport ministry frameworks formalizing micromobility lane allocation create protected operational environments for shared fleet deployment.
Market Restraints
- Lithium-ion cell supply:Concentration of cylindrical cell production in East Asian manufacturing clusters exposes fleet operators to input cost volatility and logistics bottlenecks.
- CE marking compliance:Electromagnetic compatibility testing and battery safety certification timelines extend hardware deployment cycles by 8-14 weeks for European market entry.
- Personal e-scooter ownership:Sub-400 euro retail price points for consumer-grade hardware create substitution pressure against recurring per-ride fees in price-sensitive commuter segments.
Strategic Opportunities
- France:ANSM and national transport authority frameworks for suburban rail integration remain underpenetrated, offering first-mover positioning in last-mile connectivity gaps beyond Parisian core.
- Subscription service models:Monthly unlimited-ride packages attract commuter segments seeking predictable mobility budgeting against variable pay-per-ride alternatives.
- IoT-GPS convergence:Real-time telemetry integration with municipal traffic management systems enables dynamic geofencing and automated speed restriction enforcement.
Industry Challenges
- Certification timeline compression:FCC and CE marking parallel-track requirements for cross-Atlantic fleet deployment strain regulatory affairs team capacity.
- Hardware refurbishment workforce:Shortage of technicians trained in lithium-ion diagnostics and swappable battery module repair limits centralized maintenance throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Scooter Sharing Market |
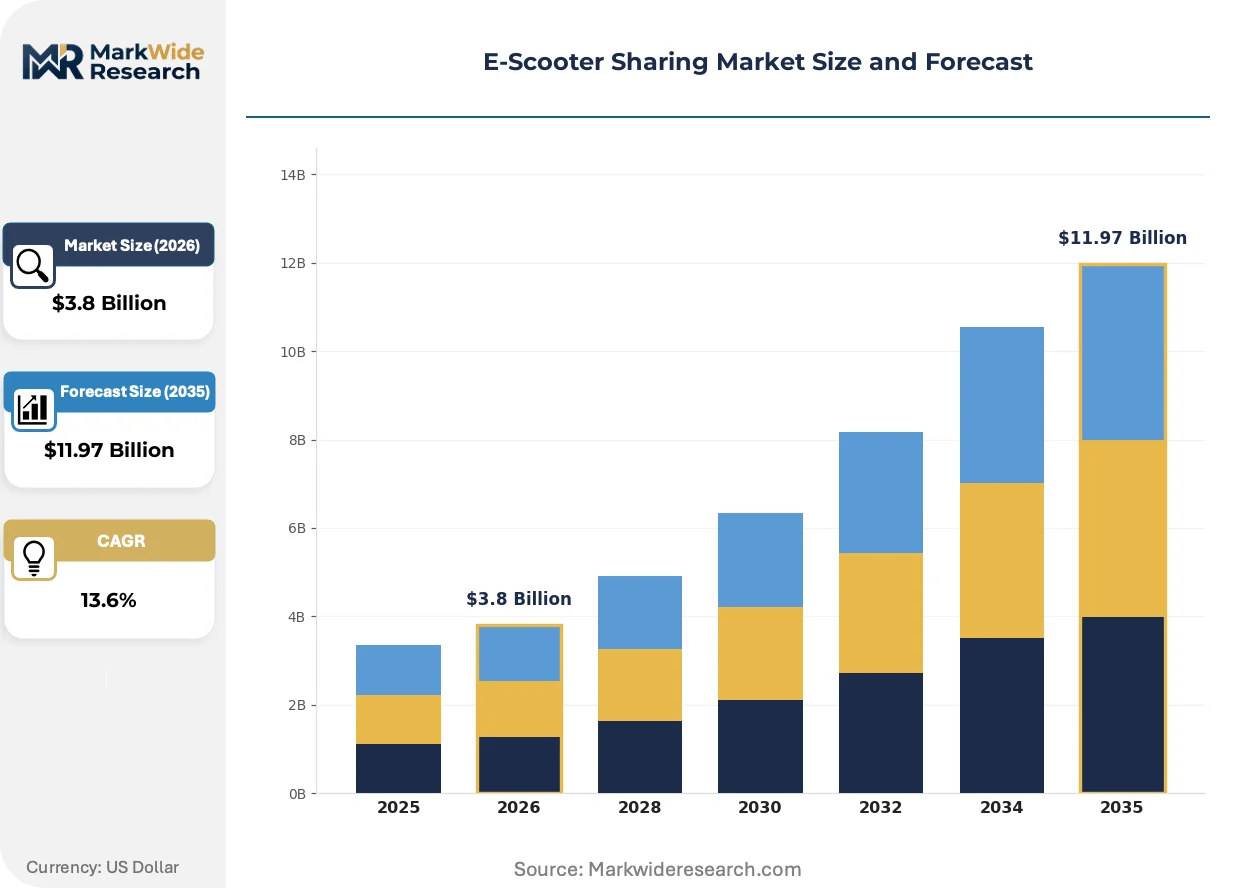
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fleet Size: Small Fleet, Medium Fleet, Large Fleet, Enterprise Fleet Charging Infrastructure: Docked, Dockless, Fast Charging, Standard Charging End User: Tourists, Commuters, Students, Local Residents Service Type: Pay-Per-Ride, Subscription, Corporate Packages, Public Partnerships |
| Companies Covered | Tier Mobility, Bird Rides Inc., Helbiz Inc., Hellobike, Coup Mobility GmbH, Lyft Inc., LimeBike Inc., Bolt Mobility, VOI Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Scooter Sharing Market Strategic Shifts & Innovations
Telemetry integration is transforming fleet management from reactive repositioning toward predictive demand modeling, compressing operational response windows from hours to minutes.
Swappable battery architecture is digitizing fleet energy logistics by enabling distributed charging networks rather than centralized depot dependency. Municipal operators in German-speaking markets are adopting hot-swap protocols fastest, reducing vehicle downtime from 4-6 hours to under 90 seconds per exchange. This infrastructure model is compressing capital requirements for geographic expansion by eliminating warehouse leasing in premium urban zones.
EU Green Deal implementation is tightening lifecycle accountability requirements for shared mobility hardware, mandating battery recycling chain documentation and carbon footprint disclosure. Fleet operators must now contract certified e-waste processors and submit material recovery certificates to retain municipal concessions. French and Spanish transport authorities are enforcing these provisions most stringently, rejecting permit renewals for non-compliant providers.
Corporate procurement departments are consolidating mobility spend under unified SaaS platforms that aggregate e-scooter, ride-hail, and transit subscriptions. Large employers in Berlin and Barcelona are displacing individual expense reimbursement with centralized fleet accounts, negotiating volume discounts directly with operators. This buyer concentration is most visible in technology and financial services verticals where remote-work policies have compressed parking infrastructure budgets.
E-Scooter Sharing Market Segmentation
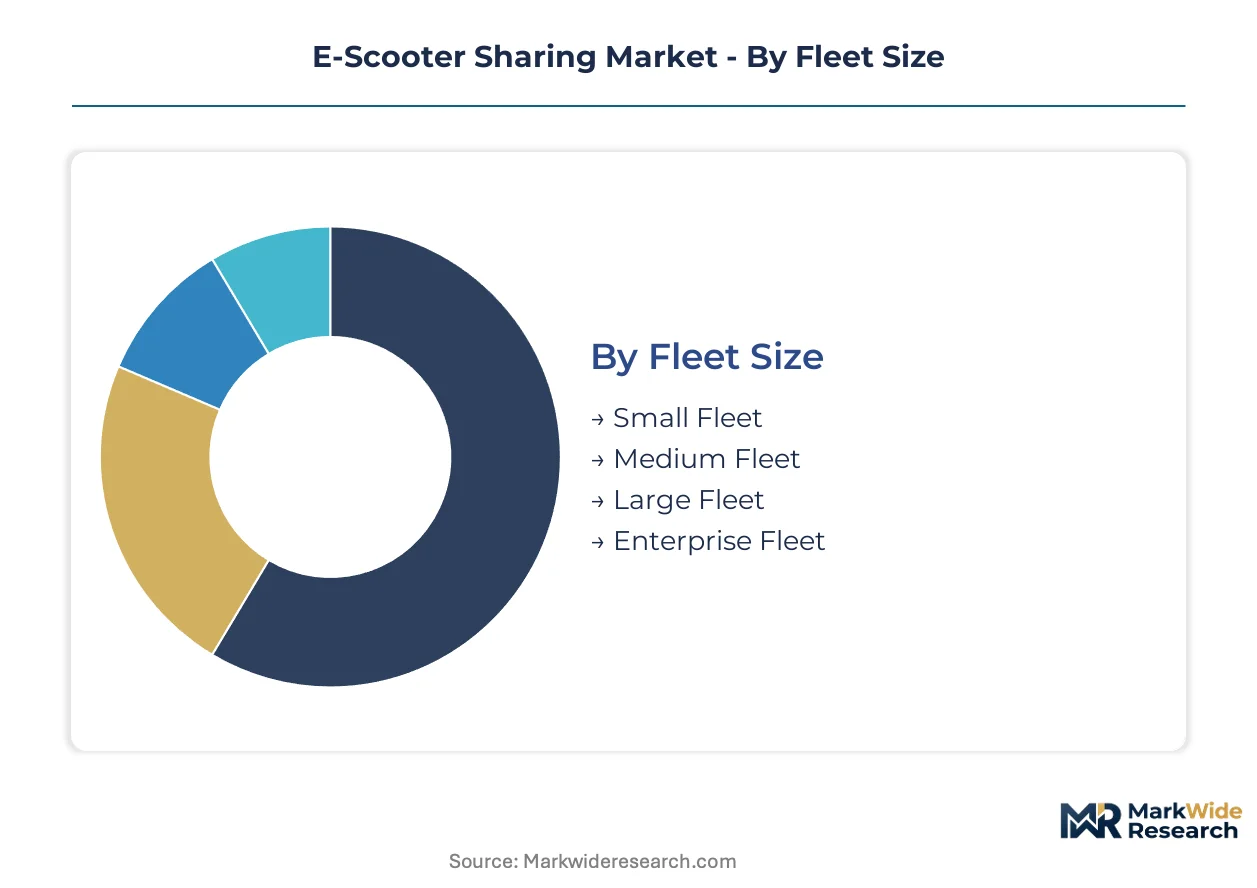
Fleet configuration and service design choices determine capital intensity, regulatory exposure, and revenue predictability for shared micromobility operators. Segmentation reveals where margin pools concentrate and which deployment models attract municipal concession awards.
Fleet Size:
Mature enterprise deployments coexist with emerging mid-scale operators testing secondary city viability.
- Small Fleet:Deployments of 50-500 vehicles serve tertiary municipalities and campus environments with minimal regulatory friction. Demand concentrates in German university towns where KBA registration thresholds exempt sub-scale operators from full commercial licensing.
- Medium Fleet:500-2,000 vehicle deployments represent the dominant concession scale in French metropolitan areas outside Paris. ANSM density caps favor this tier by limiting per-operator fleet concentration while permitting multi-provider competition.
- Large Fleet:2,000-10,000 vehicle concentrations enable centralized maintenance protocols and supplier volume discounts. These deployments dominate Spanish coastal cities where seasonal tourism creates asymmetric utilization patterns requiring rapid fleet scaling.
- Enterprise Fleet:10,000+ vehicle networks spanning multiple countries achieve procurement leverage over battery cell suppliers and IoT hardware manufacturers. Demand concentrates among operators pursuing cross-border standardization under EU Green Deal lifecycle accountability frameworks.
Enterprise Fleet retains volume leadership; Small Fleet holds the steepest expansion curve as permit fragmentation opens tertiary markets.
Charging Infrastructure:
Capital deployment patterns diverge sharply between fixed-asset and distributed energy logistics models.
- Docked:Station-based charging requires warehouse leasing in premium urban zones and constrains fleet repositioning flexibility. These systems persist in Dutch municipalities with strict parking enforcement corridors.
- Dockless:Battery-swapping networks eliminate fixed infrastructure dependency and compress geographic expansion capital requirements. German-speaking markets adopt hot-swap protocols fastest, reducing vehicle downtime from hours to under 90 seconds per exchange.
- Fast Charging:High-amperage depot systems support rapid turnaround for high-utilization corridors but accelerate lithium-ion cell degradation. Demand concentrates in Barcelona and Madrid where fleet operators compete on vehicle availability metrics.
- Standard Charging:Overnight depot charging at 3-6 kW rates minimizes battery stress and extends pack lifecycle. These systems dominate French suburban deployments where lower trip frequency reduces urgency for rapid turnaround.
Dockless infrastructure commands the highest capital efficiency ratings; Fast Charging is gaining share fastest in high-density Southern European corridors.
End User:
Usage patterns fragment across temporal predictability and price sensitivity axes.
- Tourists:Seasonal demand spikes in Mediterranean coastal cities generate 3-4x utilization multiples against baseline periods. These users exhibit low price elasticity and minimal subscription attachment.
- Commuters:Daily trip regularity enables predictable revenue forecasting and justifies subscription service design. Demand concentrates in Berlin and Munich where federal micromobility lane allocation creates protected operational environments.
- Students:Campus-centric usage patterns align with academic calendars and concentrate in German and French university cities with semester-based mobility pass programs.
- Local Residents:Mixed-mode integration with public transit subscriptions characterizes this segment in Spanish cities where combined mobility passes bundle e-scooter access with metro and bus networks.
Commuters retain volume leadership; Tourists deliver the steepest revenue spikes despite seasonal concentration.
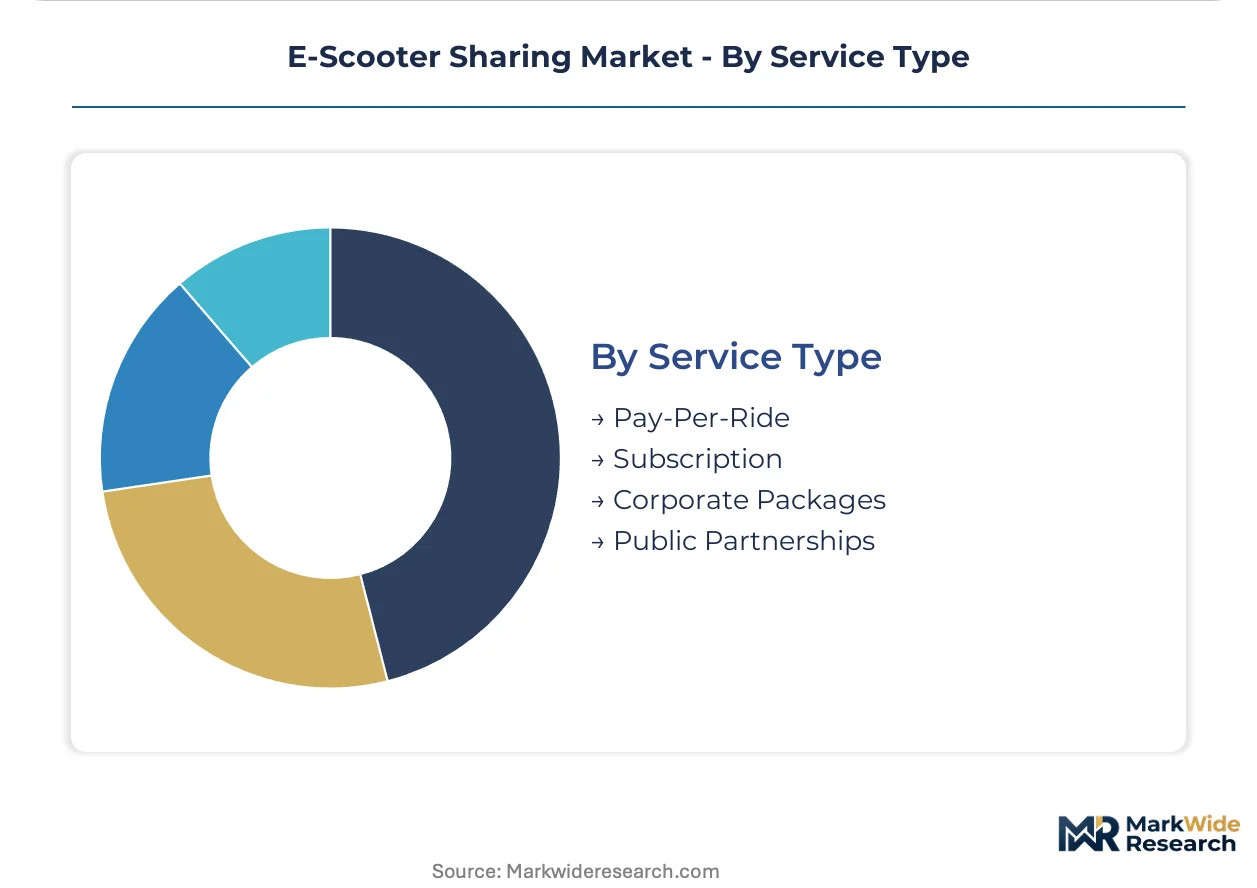
Service Type:
Revenue model selection determines customer acquisition cost structure and lifetime value predictability.
- Pay-Per-Ride:Variable pricing per minute or kilometer attracts occasional users and minimizes entry barriers. These transactions dominate tourist-heavy deployments in Barcelona and Valencia.
- Subscription:Monthly unlimited-ride packages attract commuter segments seeking predictable mobility budgeting against variable alternatives. German corporate procurement departments increasingly negotiate centralized fleet accounts displacing individual reimbursement.
- Corporate Packages:Employer-subsidized access programs consolidate mobility spend under unified SaaS platforms. Technology and financial services verticals in Berlin drive this segment through compressed parking infrastructure budgets.
- Public Partnerships:Municipal concession contracts with revenue-sharing provisions dominate French and Spanish regulatory frameworks. ANSM and national transport authority oversight creates operational caps directly constraining deployment scale.
Pay-Per-Ride retains transaction volume leadership; Subscription models are climbing the fastest as corporate procurement consolidates mobility spend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dockless charging corridor stretching from Berlin to Barcelona underwrites Europe's dominance in shared micromobility infrastructure deployment, with battery-swapping station density per square kilometer exceeding North American benchmarks by a factor of three.
Germany
Federal transport ministry frameworks for micromobility lane allocation and KBA registration thresholds for sub-scale operators drive deployment concentration. The EU F-Gas Regulation accelerates fleet electrification timelines across municipal procurement programs. Berlin and Munich anchor enterprise fleet networks where protected operational environments sustain 2,000-10,000 vehicle concentrations per operator.
France
ANSM density caps and suburban rail integration frameworks create structured expansion pathways beyond Parisian core demand. National transport authority oversight imposes operational caps directly constraining per-operator fleet scale. Lyon and Marseille host medium fleet deployments of 500-2,000 vehicles where multi-provider competition segments commuter and tourist demand.
Spain
Seasonal tourism generates 3-4x utilization multiples in Mediterranean coastal cities against baseline periods. Spanish transport authorities enforce EU Green Deal lifecycle accountability provisions most stringently for permit renewals. Barcelona and Madrid concentrate fast charging infrastructure investments as operators compete on vehicle availability metrics in high-density corridors.
United States
FCC certification governs IoT telemetry hardware deployment while municipal permit fragmentation compresses operator margins through shorter concession cycles. Bird Rides Inc. leverages battery-swapping infrastructure to sustain operational uptime in dense urban corridors. California and Texas metropolitan areas concentrate dockless fleet repositioning flexibility investments.
China
GB standards and MIIT oversight shape domestic hardware certification pathways for export-oriented manufacturers. Dual carbon goals accelerate fleet electrification timelines across municipal mobility programs. Shenzhen and Hangzhou anchor manufacturing clusters supplying swappable lithium-ion battery packs rated for 25-45 km per charge to international operators.
E-Scooter Sharing Market Key Industry Players
On the supply side, the industry is consolidating around enterprise-scale operators capable of cross-border standardization under EU Green Deal lifecycle accountability frameworks. Tiered competitive positioning separates municipal partnership specialists from technology-integrated mobility platforms. Three archetypes dominate: direct municipal concessionaires, battery-swapping infrastructure operators, and corporate procurement consolidators. Dominant competitive moves include geographic expansion through concession bidding and backward integration into IoT-GPS telemetry hardware.
Among European-based operators, Tier Mobility, VOI Technology, and Coup Mobility GmbH exemplify the municipal partnership archetype. Tier Mobility dominates German-speaking markets through direct municipal relationships. VOI Technology occupies a position within Scandinavian urban mobility corridors. Coup Mobility GmbH represents the mid-scale concession specialist targeting secondary metropolitan areas. These entities anchor competitive dynamics as municipal permit systems multiply and operator concessions shrink to shorter renewal cycles.
| Leading Market Players |
|---|
| Tier Mobility |
| Bird Rides Inc. |
| Helbiz Inc. |
| Hellobike |
| Coup Mobility GmbH |
| Lyft Inc. |
| LimeBike Inc. |
| Bolt Mobility |
| VOI Technology |
| Others |
Cost & Logistics Intelligence
Underutilized battery cell capacity in South Korean manufacturing clusters is compressing input costs for fleet operators while simultaneously eroding supplier pricing power across European procurement channels. This utilization asymmetry rewards large fleet operators with volume-negotiation leverage against mid-scale competitors locked into spot-market sourcing.
Pricing Analysis
Volume-discount tiering separates enterprise fleet operators securing 15-20% procurement discounts from small fleet competitors paying standard contract rates. Price differentiation hinges on battery pack order volume and CE marking certification status, with uncertified hardware facing 8-14 week deployment delays that inflate effective per-unit costs. Pricing pressure intensifies in commuter-heavy corridors where subscription models displace variable pay-per-ride revenue. Tourist segments exhibit lowest price sensitivity; students and local residents demonstrate highest elasticity to per-minute rate adjustments.
Supply Chain Analysis
Contract manufacturing concentration rests with Shenzhen and Hangzhou-based EMS providers supplying swappable lithium-ion packs and IoT telemetry modules to international operators. Raw material dependencies center on lithium carbonate from Chilean and Australian extraction operations, nickel sulfate from Indonesian processing facilities, and rare earth magnets for motor assemblies. Single-source vulnerability concentrates in cylindrical cell formats where three East Asian producers dominate global capacity. Distribution runs through centralized depot networks in German-speaking markets and battery-swapping station grids across Southern European corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal permit fragmentation is fragmenting competitive structure into sub-scale niches, creating entry points for specialized operators as city-level procurement decentralizes away from national frameworks.
For Market Incumbents: Entrench municipal partnership advantages by extending concession renewal terms through EU Green Deal compliance investments and lifecycle accountability certification. Deepen backward integration into IoT-GPS telemetry hardware to reduce FCC and CE marking timeline exposure. Threat substitution from personal e-scooter ownership below 400 euro retail price points demands subscription model innovation to lock commuter switching costs. For New Entrants and Emerging Players: Build out suburban rail integration deployments in French metropolitan areas outside Paris where ANSM frameworks remain underpenetrated. Campus environments in German university towns offer KBA registration threshold exemptions that minimize commercial licensing friction. Corporate procurement consolidation in Berlin technology verticals provides SaaS-platform partnership angles for centralized fleet account acquisition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across dockless charging infrastructure as battery-swapping station networks eliminate warehouse leasing requirements in premium urban zones. Long-term viability over the next decade favors operators achieving cross-border standardization under EU lifecycle accountability frameworks. Acquisition targets should demonstrate certified e-waste processor contracts and material recovery certificate documentation. The signal to watch is municipal permit renewal rejection rates for non-compliant providers in French and Spanish transport authority jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Swapping Infrastructure Deployment | Reduces vehicle downtime from hours to under 90 seconds per exchange in German-speaking markets. |
| CE Marking Parallel-Track Certification | Compresses cross-Atlantic hardware deployment cycles by 8-14 weeks for European market entry. |
| Corporate Fleet Account Consolidation | Captures technology and financial services verticals displacing individual expense reimbursement. |
| Suburban Rail Integration Partnership | Secures first-mover positioning in Lyon and Marseille last-mile connectivity gaps. |
| EU Green Deal Compliance Certification | Retains municipal concessions through battery recycling chain documentation and carbon disclosure. |
Research Approach
Desk research of municipal permit databases, EU regulatory filings, and fleet operator concession agreements preceded structured interviews with fleet operations directors, municipal procurement officers, battery cell procurement managers, and IoT hardware engineering leads. Primary fieldwork combined with secondary validation against ANSM transport authority frameworks, KBA registration data, and EU F-Gas Regulation implementation timelines. Bottom-up vehicle deployment counts triangulated against top-down market value estimates across the analysis window.
Assumption sets held municipal density caps and lithium-ion cell pricing bands fixed while varying seasonal tourism demand multiples and corporate subscription adoption curves. Segmentation modeling incorporated fleet size tiers, charging infrastructure configurations, end-user archetypes, and service type revenue models. CAGRs derived from regression analysis of historical deployment velocity against permit approval rates. Forecast inputs included battery pack energy density improvement trajectories and micromobility lane allocation policy shifts.
Stress conditions across lithium carbonate price volatility, CE marking timeline extensions, and municipal permit renewal rejection thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding F-Gas Regulation phase-down compliance and pedestrian safety ordinance evolution. Quarterly review of municipal concession award announcements and battery recycling directive enforcement actions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Europe Passenger Information System Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
US Smart Highway Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Nordic Bike Sharing Market