
 Smart Parking Technologies Market | 2026-2036
Smart Parking Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Parking Technologies Market Outlook
Asset-light parking-as-a-service leasing is rewriting competitive entry barriers for municipal operators and commercial landlords. Siemens AG leverages its industrial automation heritage to anchor large-scale automated parking deployments across European transit hubs. Flowbird competes through integrated payment-terminal networks that control street-level meter infrastructure in multiple national markets. Robert Bosch GmbH differentiates via sensor-hardware specialization, extending its automotive MEMS expertise into ultrasonic and camera-based space-detection modules.
Smart parking technologies encompass sensor networks, mobile connectivity platforms, and cloud-based management systems that detect vehicle occupancy, guide drivers to available spaces, and process automated payments with latency thresholds below five seconds for real-time guidance. These systems reduce urban congestion, cut emissions from circling vehicles, and maximize revenue capture for asset owners. Sensor-based solutions dominate hardware spend as ultrasonic and magnetic detectors achieve sub-meter accuracy at declining unit cost. Cloud computing platforms represent the fastest-expanding segment because municipalities and mall operators prioritize centralized fleet management and predictive maintenance dashboards over on-premise server deployments.
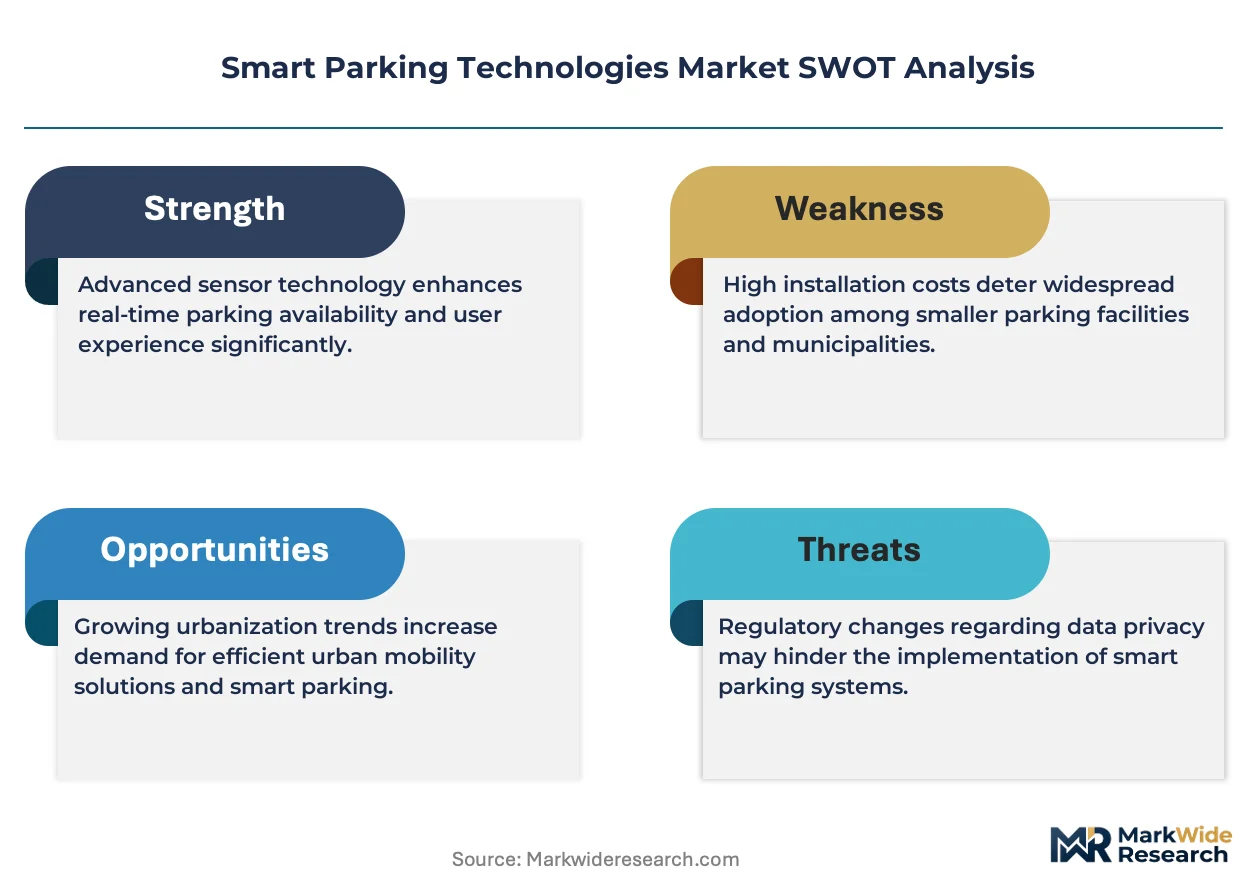
EU Green Deal urban-mobility frameworks and F-Gas Regulation standards for sensor refrigerants shape product design and procurement eligibility across European deployments. The US Department of Transportation and EPA coordinate on smart-city infrastructure grants that tie funding to emissions-reduction verification, directing municipal demand toward integrated parking-transit platforms. Stakeholders must monitor how evolving data-localization requirements under GDPR and emerging national AI-surveillance statutes reshape cloud-architecture choices and cross-border platform licensing.
Market Dynamics
Municipal transportation agencies in Germany are expanding procurement of automated parking infrastructure under EU Green Deal urban mobility directives, compressing deployment timelines and forcing legacy system replacements across European transit hubs.
Growth Catalysts
- EU Green Deal urban-mobility frameworks:These directives mandate emissions-reduction verification for smart-city infrastructure grants, directing municipal demand toward integrated parking-transit platforms in Germany and France.
- Sensor-based solutions:Ultrasonic and magnetic detectors achieving sub-meter accuracy at declining unit cost dominate hardware spend across commercial complexes and airport terminals.
- Cloud computing platforms:Centralized fleet management and predictive maintenance dashboards are displacing on-premise server deployments as municipalities and mall operators prioritize operational visibility.
Market Restraints
- GDPR data-localization requirements:Evolving cross-border platform licensing rules reshape cloud-architecture choices, adding compliance friction for multi-national deployments.
- Sensor refrigerant standards:F-Gas Regulation compliance for space-detection modules limits supplier eligibility and extends certification timelines for European procurements.
- Legacy infrastructure lock-in:Existing parking meter networks and proprietary payment terminals create switching costs that slow municipal upgrade cycles.
Strategic Opportunities
- Asset-light parking-as-a-service leasing:This model rewrites competitive entry barriers for municipal operators and commercial landlords seeking to avoid capital-intensive ownership.
- China airport terminal deployments:Demand concentrates in sensor-based solutions at high-traffic transportation nodes where real-time guidance delivers measurable congestion relief.
- AI-surveillance statute convergence:Emerging national regulations on automated vehicle detection create standardization pressure that favors platforms with pre-built compliance architectures.
Industry Challenges
- Five-second latency thresholds:Real-time guidance systems require sub-second payment processing and space-detection synchronization, demanding specialized edge-computing expertise scarce among traditional parking operators.
- Integration complexity with proprietary payment terminals:Street-level meter infrastructure from incumbent vendors resists API standardization, forcing custom middleware development for unified platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Parking Technologies Market |
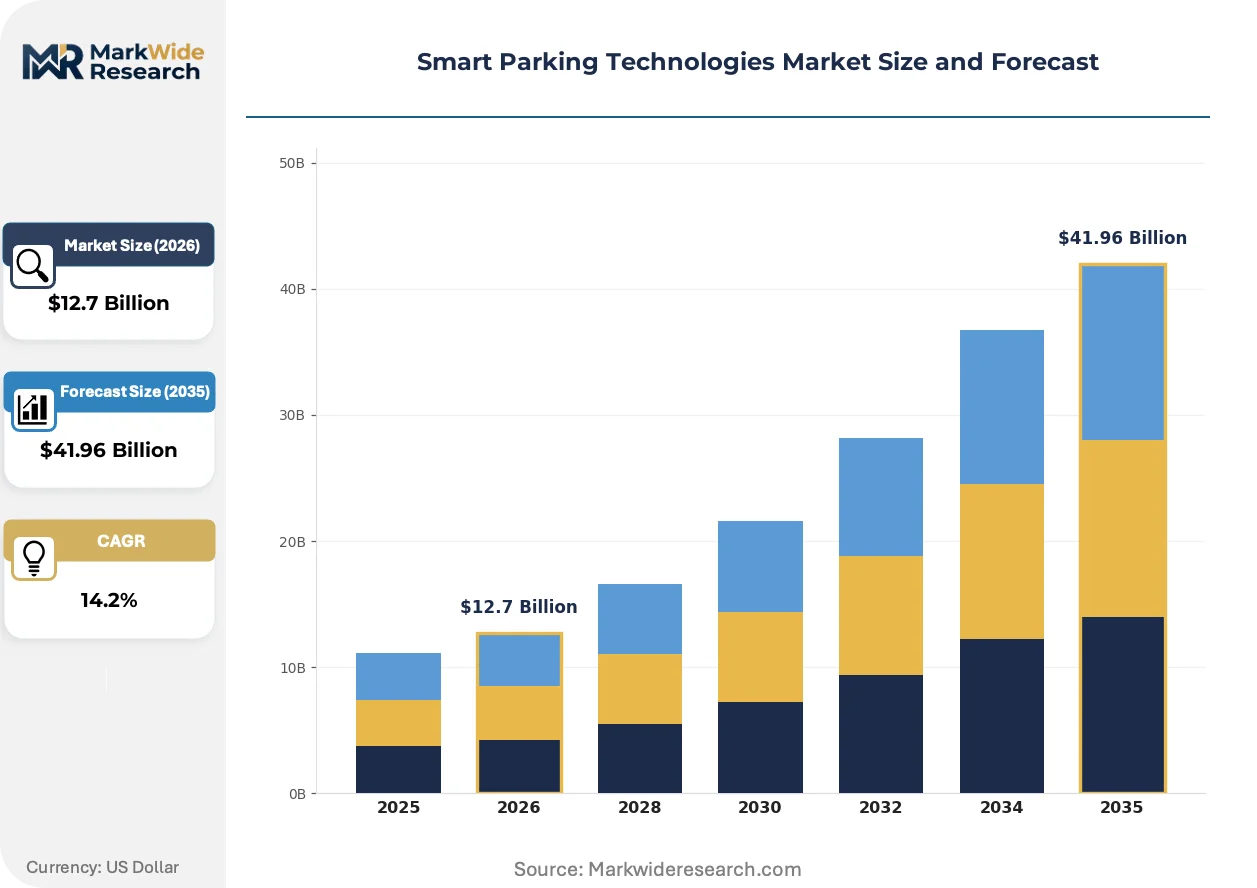
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Sensor-Based Solutions, Mobile Apps, Cloud Computing, Data Analytics Application: Residential Areas, Shopping Malls, Airports, Commercial Complexes End User: Municipalities, Businesses, Mall Operators, Transportation Agencies Solution: Valet Parking Systems, Automated Parking Solutions, Reservation Systems, Real-Time Information Systems |
| Companies Covered | ParkMobile, LLC, IPS Group, Smart Parking Ltd., Flowbird, Parkopedia, Siemens AG, Robert Bosch GmbH, Cisco Systems, Inc., SKIDATA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Parking Technologies Market Strategic Shifts
Digital infrastructure is compressing the boundary between physical parking assets and software-defined service layers, enabling new operating models that separate asset ownership from customer-facing platform control.
Edge-computing nodes deployed at garage entry points are virtualizing the traditional centralized server architecture. Airport operators in the United States and Germany are adopting these distributed processing units to achieve sub-second payment authorization. This virtualization is compressing the cost structure for real-time guidance systems while reducing dependency on continuous cloud connectivity.
REACH and F-Gas Regulation standards for sensor refrigerants are reshaping hardware procurement eligibility across European deployments. Manufacturers must reformulate ultrasonic and camera-based detection modules to eliminate restricted substances. Sensor-hardware specialists with automotive MEMS heritage are capturing municipal contracts by pre-certifying compliant product lines.
Municipal procurement patterns are fragmenting as transportation agencies unbundle parking management from integrated smart-city contracts. Mid-size commercial landlords in China and Germany now source space-detection hardware separately from payment processing platforms. This unbundling is concentrating demand among specialized vendors with modular API architectures rather than end-to-end system integrators.
Smart Parking Technologies Market Segmentation
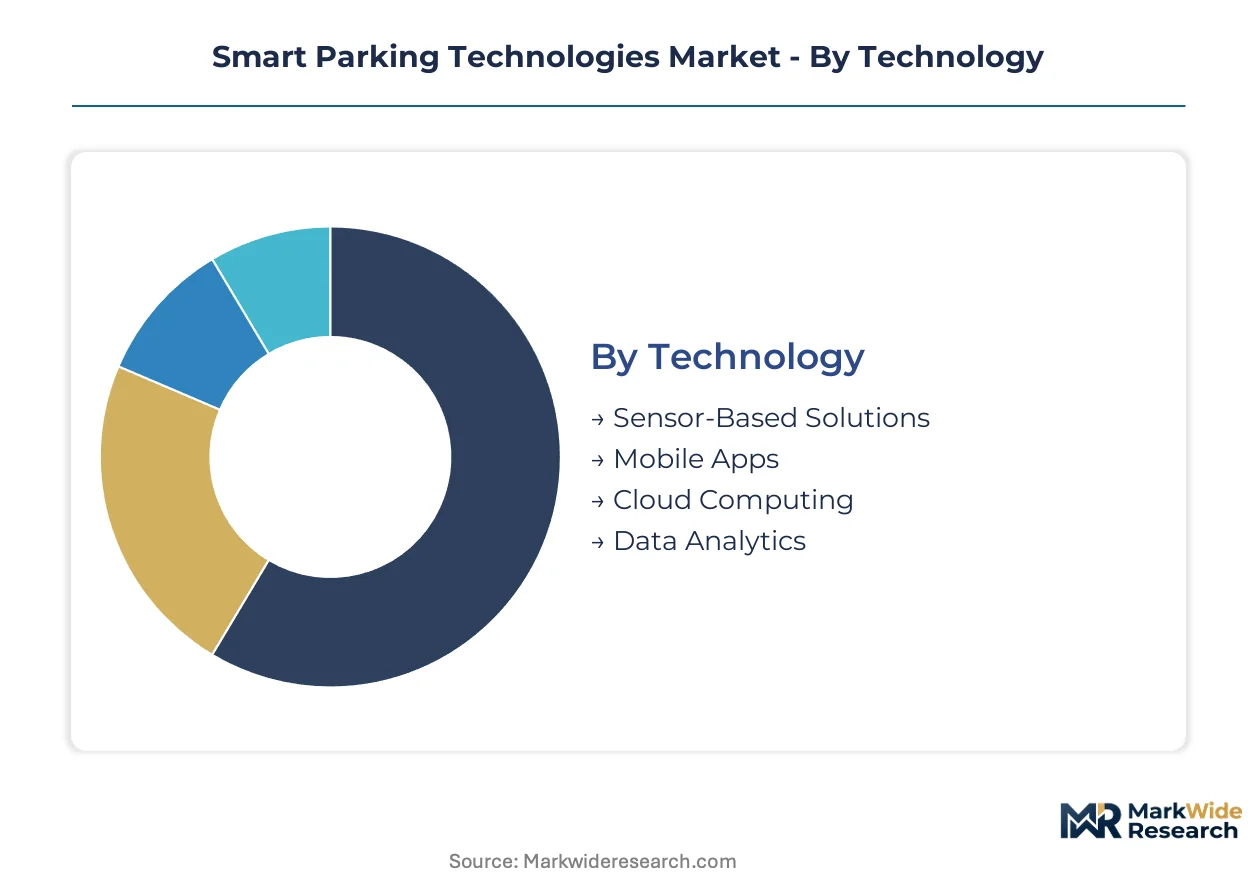
Smart parking technologies fragment across hardware, software, and service layers with diverging replacement cycles and margin profiles. Understanding segment velocity helps vendors allocate R&D and sales resources across municipal, commercial, and transportation verticals.
Technology:
Sensor-based hardware turns over every 5-7 years as accuracy standards tighten, while cloud platforms refresh on 18-24 month software cycles.
- Sensor-Based Solutions:Ultrasonic and magnetic detectors achieve sub-meter vehicle detection accuracy. Procurement concentrates in Germany and China airport terminals where EU Green Deal emissions verification mandates drive infrastructure replacement.
- Cloud Computing:Centralized fleet management platforms process occupancy data with sub-five-second latency. Mall operators in the United States prioritize predictive maintenance dashboards over on-premise server deployments, accelerating subscription revenue models.
- Mobile Apps:Consumer-facing guidance interfaces integrate payment processing and navigation. Municipal transportation agencies bundle these with transit apps to meet federal smart-city grant requirements.
- Data Analytics:Predictive algorithms optimize pricing and space allocation. Commercial landlords deploy these tools to maximize revenue per parking asset across mixed-use developments.
Sensor-based solutions dominate installed base. Cloud computing is where expansion concentrates.
Application:
Cost tiers separate high-complexity transportation hubs from standardized residential deployments with minimal integration requirements.
- Airports:High-traffic terminals demand real-time guidance with sub-second payment authorization. United States and German operators adopt edge-computing nodes to reduce cloud dependency and achieve latency thresholds.
- Commercial Complexes:Mixed-use developments integrate parking with retail analytics. Sensor networks feed foot-traffic data to tenant revenue optimization systems.
- Shopping Malls:Mid-tier deployments balance guidance accuracy against capital constraints. Operators lease hardware through parking-as-a-service models to avoid ownership risk.
- Residential Areas:Lower-complexity installations prioritize cost per space over advanced features. Homeowners associations favor magnetic loop detectors for their durability and minimal maintenance.
Commercial complexes anchor current revenue. Airports deliver the steepest expansion trajectory.
End User:
Customer type determines procurement sophistication, with transportation agencies running formal tenders and mall operators favoring speed-to-deployment.
- Transportation Agencies:German municipal operators expand automated parking procurement under EU Green Deal urban mobility directives. Compliance documentation requirements compress vendor qualification timelines.
- Mall Operators:Revenue-maximizing landlords prioritize integrated payment-terminal networks. These stakeholders unbundle space detection from processing platforms, favoring modular API architectures.
- Municipalities:City governments balance emissions-reduction targets against legacy meter infrastructure lock-in. Federal smart-city grants tie funding to verified congestion relief metrics.
- Businesses:Corporate campus operators deploy reservation systems for employee parking allocation. These installations emphasize software-defined access control over hardware density.
Transportation agencies control the largest project scale. Mall operators are expanding most quickly.
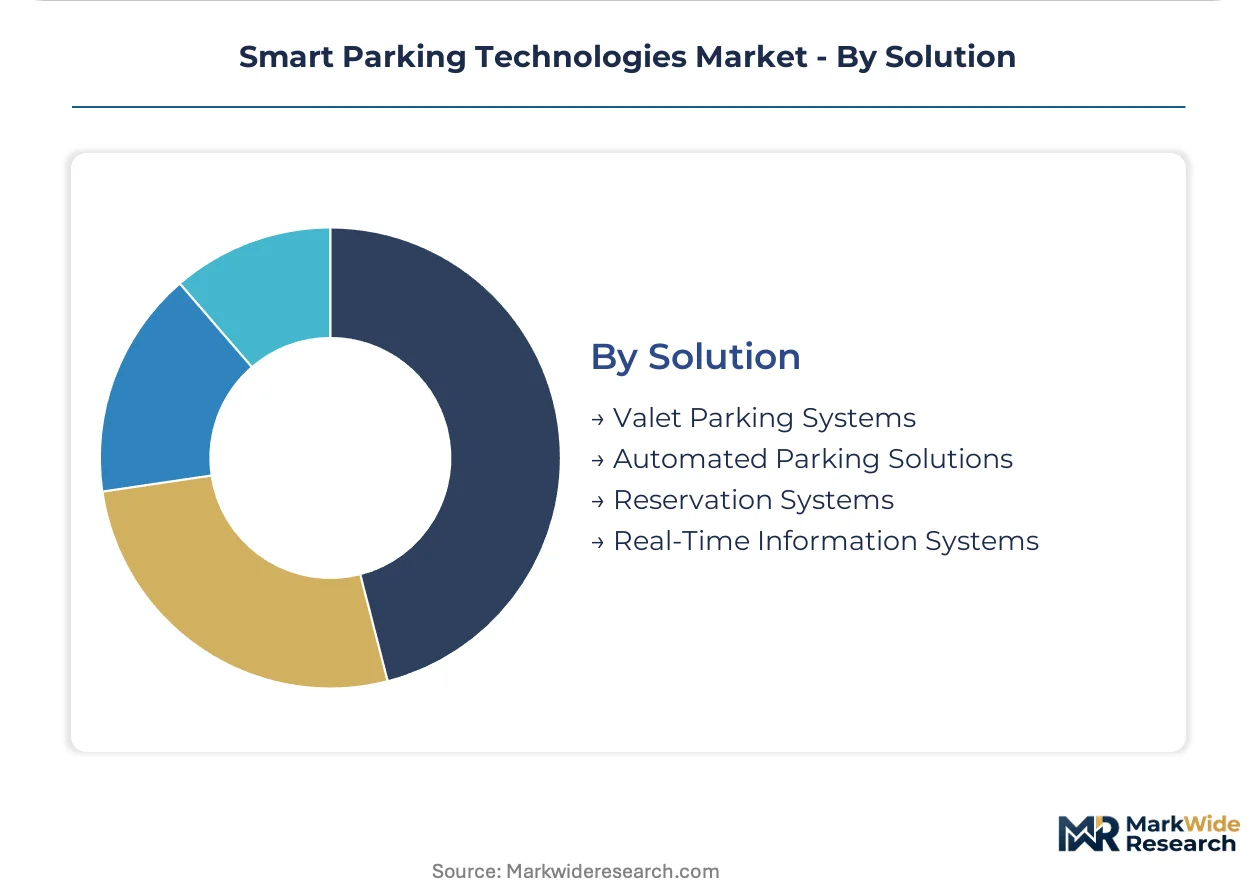
Solution:
Maturity gradients separate established guidance systems from emerging automated parking with unproven reliability at commercial scale.
- Real-Time Information Systems:Digital signage and mobile interfaces guide drivers to available spaces. These solutions achieve fastest deployment in China airport terminals where congestion relief delivers measurable ROI.
- Automated Parking Solutions:Robotic vehicle storage systems maximize density in constrained urban sites. European transit hubs pilot these installations under compressed timelines forced by infrastructure replacement mandates.
- Reservation Systems:Pre-booking platforms guarantee space availability and enable dynamic pricing. Corporate campuses and event venues adopt these to reduce arrival uncertainty.
- Valet Parking Systems:Human-assisted or semi-automated services maintain relevance in luxury hospitality. These solutions resist full automation due to liability and customer preference factors.
Real-time information systems dominate deployment volume. Automated parking solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipal operators extract pricing premiums for EU Green Deal-compliant installations while Chinese airport authorities compress procurement costs through volume aggregation. This asymmetry reshapes vendor margin structures across deployment geographies.
United States
Department of Transportation smart-city grants tie funding to EPA-verified emissions reduction, directing municipal demand toward integrated parking-transit platforms. Federal infrastructure legislation channels capital toward real-time guidance systems in high-traffic metropolitan zones. Dallas-Fort Worth and Atlanta airport authorities deploy edge-computing nodes to achieve sub-second payment authorization thresholds.
Germany
Municipal transportation agencies accelerate automated parking procurement under compressed EU Green Deal urban mobility timelines. KBA certification requirements for sensor hardware extend vendor qualification periods. Bavarian transit hubs in Munich and Nuremberg pilot robotic vehicle storage systems under infrastructure replacement mandates.
China
Airport terminal operators aggregate sensor-based solution procurement across Beijing Capital, Shanghai Pudong, and Guangzhou Baiyun to compress unit costs. MIIT standards for IoT device interoperability shape platform architecture requirements. Yangtze River Delta municipal clusters unbundle space detection from payment processing, favoring modular API vendors.
Japan
METI urban congestion reduction targets drive adoption of real-time guidance systems in Tokyo and Osaka commercial districts. JIS standards for electromagnetic compatibility constrain foreign hardware eligibility. Kansai region airport operators prioritize predictive maintenance dashboards over on-premise server deployments.
United Kingdom
Transport for London procurement frameworks prioritize GDPR-compliant cloud architectures for cross-border data flows. CSRD disclosure requirements extend to parking asset emissions reporting for commercial landlords. Southeast England mall operators lease hardware through parking-as-a-service models to avoid capital ownership risk.
Smart Parking Technologies Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream capturing margin on sensor density and edge-computing modules. Market structure concentrates around three strategic archetypes: industrial automation conglomerates with transit infrastructure heritage, payment-terminal network operators with street-level meter control, and automotive sensor specialists extending MEMS expertise into ultrasonic detection. Competitive moves center on API unbundling to capture modular procurement demand and pre-certification of hardware lines to compress European tender timelines.
Among European industrial automation conglomerates, Siemens AG occupies a position exemplifying large-scale automated parking deployment capability. Flowbird represents the payment-terminal network archetype with integrated street-level infrastructure control. Robert Bosch GmbH anchors the sensor-hardware specialist tier, extending automotive MEMS heritage into space-detection modules for municipal contracts.
| Leading Market Players |
|---|
| ParkMobile, LLC |
| IPS Group |
| Smart Parking Ltd. |
| Flowbird |
| Parkopedia |
| Siemens AG |
| Robert Bosch GmbH |
| Cisco Systems, Inc. |
| SKIDATA GmbH |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Taiwanese MEMS foundries for ultrasonic sensor cores determines both tiered pricing spreads across EU Green Deal-compliant and non-compliant hardware lines and supply chain shape favoring regional assembly partnerships over full vertical integration.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on F-Gas Regulation certification grade and volume scale, with EU-compliant sensor modules commanding premiums against uncertified alternatives. Cost compression in the economy tier is intensifying because Chinese airport operators aggregate procurement across multiple terminals. Municipal transportation agencies in Germany exhibit lowest price sensitivity due to compressed EU Green Deal timelines, while residential homeowners associations remain most price-sensitive.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for edge-computing hardware. Component manufacturing concentrates in China, Germany, and South Korea, drawing from silicon wafers, rare-earth magnets, and specialized refrigerants for sensor modules. Single-source vulnerability in automotive-grade MEMS production creates procurement chokepoints. Distribution runs through systems integrators who bundle hardware with cloud platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement unbundling across municipal and commercial buyer segments fragments vendor selection criteria, creating specialized niches for component specialists alongside integrated platform providers.
For Market Incumbents: Entrench market position through pre-certification of F-Gas Regulation-compliant sensor lines to compress European tender timelines, and deepen backward integration into edge-computing module production to defend margins against modular API competitors. Threat substitution from payment-terminal network operators extending into guidance systems demands channel control investments in street-level meter infrastructure. For New Entrants and Emerging Players: Japanese commercial districts outside Tokyo present underpenetration for real-time guidance systems where METI congestion targets create procurement urgency. White-space targets include predictive maintenance dashboards for Kansai region airport operators and parking-as-a-service leasing models for Southeast England mall operators. A go-to-market angle emphasizing GDPR-compliant cloud architectures accelerates access to Transport for London procurement frameworks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors sensor-hardware specialists with automotive MEMS heritage and modular API platforms. Long-term viability over a multi-year window hinges on capturing municipal contracts tied to emissions-verification mandates. The signal to watch is unbundling velocity in Chinese municipal clusters, where separation of space detection from payment processing indicates platform commoditization risk.| Strategic Initiative | Industry Significance |
|---|---|
| API Unbundling | Captures modular procurement demand from mall operators separating detection from processing. |
| F-Gas Pre-Certification | Compresses vendor qualification timelines for EU Green Deal municipal tenders in Germany. |
| Edge-Computing Localization | Reduces cloud dependency for US airport operators targeting sub-second payment authorization. |
| Parking-as-a-Service Leasing | Rewrites capital barriers for commercial landlords avoiding hardware ownership risk. |
| Transit Platform Integration | Meets federal smart-city grant requirements tying funding to emissions-reduction verification. |
Study Parameters
Operator-level perspectives from municipal transportation planners, mall facility managers, airport operations directors, and sensor hardware procurement leads anchored the qualitative base. These primary inputs combined with secondary validation from EU Green Deal implementation reports, KBA certification databases, MIIT IoT standards documentation, and SEC filings of listed industrial automation conglomerates. Bottom-up unit economics triangulated against top-down market sizing across deployment geographies.
Scenario-bracketing framed the analytical approach across the projection horizon. Segmentation dimensions modeled include technology layer, application complexity tier, end-user procurement sophistication, and solution maturity gradient. CAGRs derived from installed base turnover cycles and replacement velocity curves, incorporating edge-computing adoption rates and cloud platform subscription renewal patterns as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in infrastructure stimulus allocation or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Smart Ports Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
North America Passenger Information System Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Europe Electronic Toll Collection Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Smart Rail Suite Solutions Market
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Global Smart Commute Market
Smart Transportation Solutions
Global Parking Management Software Market
Smart Transportation Solutions
Smart Mobility Market
Smart Transportation Solutions
Vertical Mobility Market