
 Automotive Vehicle to Everything (V2X) Market | 2026-2036
Automotive Vehicle to Everything (V2X) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Vehicle to Everything (V2X) Market Insights
Modular bundling of roadside units with cloud-based service platforms is realigning how infrastructure providers evaluate procurement. Qualcomm leverages its cellular modem portfolio to anchor integrated chipset-roadside unit offerings. Continental competes through manufacturing scale in antenna and sensor modules for dual-mode DSRC-C-V2X configurations. NXP Semiconductors specializes in secure element integration for vehicle-to-network authentication protocols.
Automotive Vehicle to Everything (V2X) denotes a wireless communication ecosystem enabling direct data exchange between vehicles, infrastructure, pedestrians, and networks using dedicated short-range communications or cellular-based protocols operating in the 5.9 GHz ITS band with sub-100 millisecond latency requirements. The architecture serves collision avoidance, traffic signal prioritization, and cooperative perception for autonomous navigation. C-V2X technology leads deployment momentum where cellular infrastructure density supports cost-effective rollout, while DSRC retains installed-base relevance in early-adopter corridors. Application demand clusters around traffic management systems where public authorities fund intersection intelligence, with autonomous driving integration representing the highest-margin long-term segment. On-board units currently dominate component value capture, though service platforms are displacing hardware-centric margin pools as software-defined updates become standard.
The FCC governs spectrum allocation and equipment authorization for V2X deployments in the United States, while the European Commission's delegated regulation on cooperative intelligent transport systems mandates interoperability standards across member states. Japan's METI coordinates 5G-V2X convergence trials with domestic automotive manufacturers. China's MIIT issues network access licenses for connected vehicle terminals and roadside equipment. Stakeholders must monitor spectrum policy divergence between cellular-based and direct-communication architectures when committing to multi-year infrastructure contracts.
Market Dynamics
Spectrum reallocation mandates in the United States and delegated regulations in Europe are forcing infrastructure providers to dual-source DSRC and C-V2X chipsets, compressing procurement timelines and inflating compliance costs across roadside unit deployments.
Growth Catalysts
- China's MIIT pilot zone expansion:Network access licenses for connected vehicle terminals in designated corridors are accelerating roadside infrastructure procurement by municipal authorities seeking smart city certification.
- 5.9 GHz ITS band harmonization:Regulatory alignment across transportation authorities in Germany, Japan, and the United States is reducing chipset certification friction for dual-mode equipment suppliers.
- Autobahn digitization programs:Federal highway operators in Germany are bundling roadside units with cloud-based traffic management platforms, creating multi-year service revenue streams for infrastructure vendors.
Market Restraints
- Silicon supply concentration:Secure element fabrication for V2X authentication protocols depends on a limited foundry base in Taiwan, exposing procurement timelines to geopolitical disruption.
- FCC spectrum reallocation friction:The 2020 decision to reassign portions of the 5.9 GHz band has stranded early DSRC investments and forced municipal buyers into costly technology refresh cycles.
- Cellular infrastructure dependency:C-V2X deployment viability requires dense 4G/5G coverage that remains uneven in rural corridors across the United States and Australia, limiting addressable route mileage.
Strategic Opportunities
- Pedestrian protection mandates:Japan's METI coordination of 5G-V2X convergence trials with domestic automakers is creating specification pull for vulnerable road user detection systems.
- Software-defined roadside units:Over-the-air update capabilities are enabling infrastructure-as-a-service models where public authorities subscribe to intersection intelligence rather than capitalizing hardware.
- EU delegated regulation tailwinds:Interoperability mandates across member states are consolidating procurement specifications, favoring vendors with pre-certified dual-mode product portfolios.
Industry Challenges
- Cybersecurity certification complexity:Vehicle-to-network authentication protocols require Common Criteria evaluation that extends product launch timelines by 12-18 months for new chipset entrants.
- Legacy traffic signal integration:Municipal traffic management systems built on proprietary protocols demand costly middleware development to enable V2X message translation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Vehicle to Everything (V2X) Market |
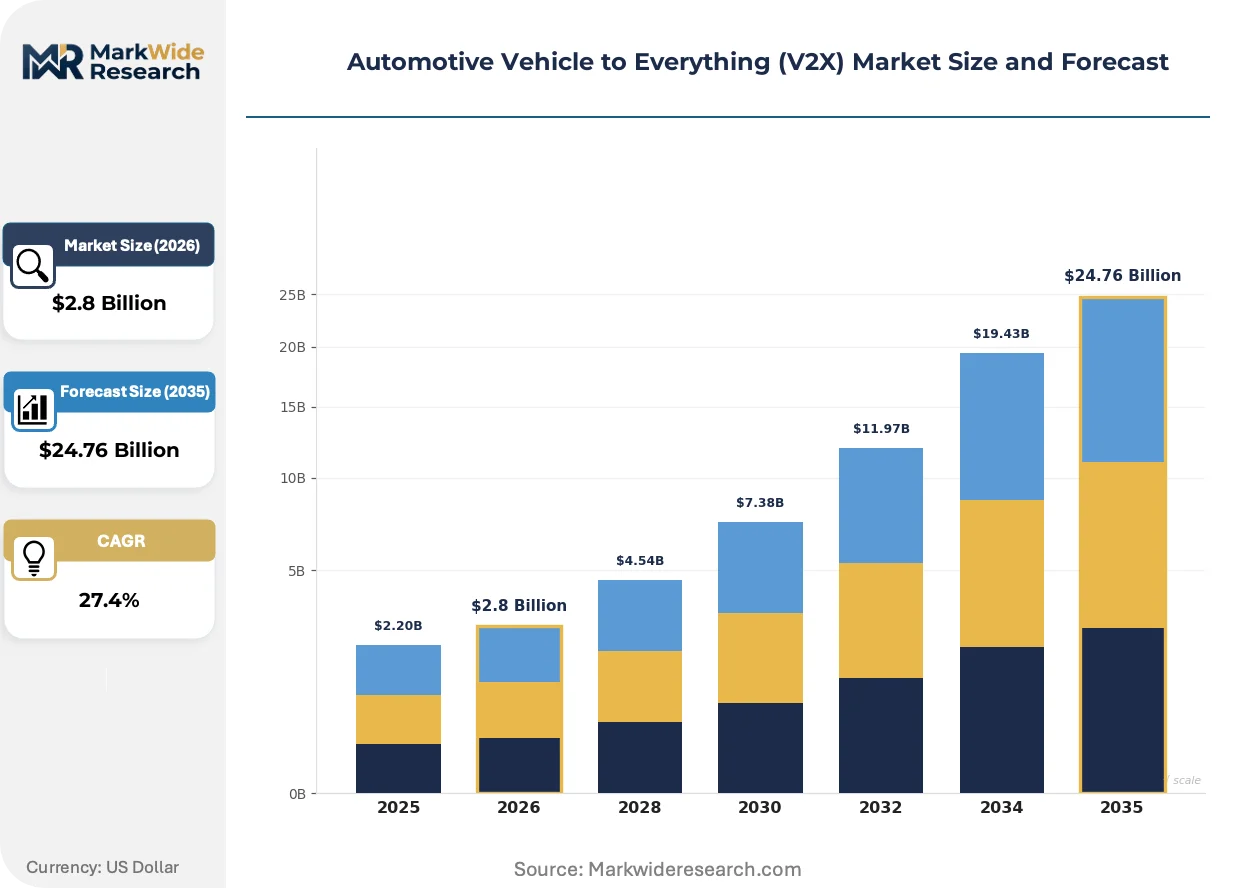
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $24.76 Billion |
| CAGR (2026 – 2036) | 27.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DSRC, C-V2X, 5G, Wi-Fi Component: On-board Units, Roadside Units, Service Platforms, Control Centers Application: Traffic Management, Emergency Response, Autonomous Driving, Fleet Management End User: Public Authorities, Automotive OEMs, Fleet Operators, Infrastructure Providers |
| Companies Covered | Qualcomm, Continental, Harman International, Autotalks, Denso, NXP Semiconductors, Robert Bosch, LG Innotek, Infineon Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Vehicle to Everything (V2X) Market Trends and Innovations
Edge computing migration is compressing latency requirements for cooperative perception applications, while regulatory mandates are hardening cybersecurity specifications for vehicle-to-network authentication protocols.
Multi-access edge computing (MEC) deployment at cellular base stations is automating real-time object fusion for autonomous navigation. Tier 1 automotive suppliers are integrating MEC-compliant roadside units into highway pilot corridors in Germany and China. This architecture is automating the shift from centralized cloud processing to distributed intersection intelligence, reducing end-to-end latency below 20 milliseconds for collision avoidance applications.
The FCC's 5.9 GHz reallocation order and subsequent waiver processes have fragmented equipment authorization pathways in the United States. Infrastructure providers must now maintain parallel certification tracks for DSRC and C-V2X variants of identical hardware. Municipal procurement teams in California and Michigan are responding by specifying dual-mode compatibility as a mandatory evaluation criterion, effectively disqualifying single-technology vendors from contested bids.
Public authorities are consolidating roadside infrastructure procurement through multi-year service contracts that bundle hardware, installation, and cloud-based traffic analytics. State departments of transportation in Texas and Florida are displacing capital expenditure models with availability-based payment structures tied to intersection uptime metrics. This reconfiguration is most visible in Sun Belt metropolitan areas where rapid suburban expansion demands scalable deployment of connected corridor infrastructure.
Automotive Vehicle to Everything (V2X) Market Segmentation
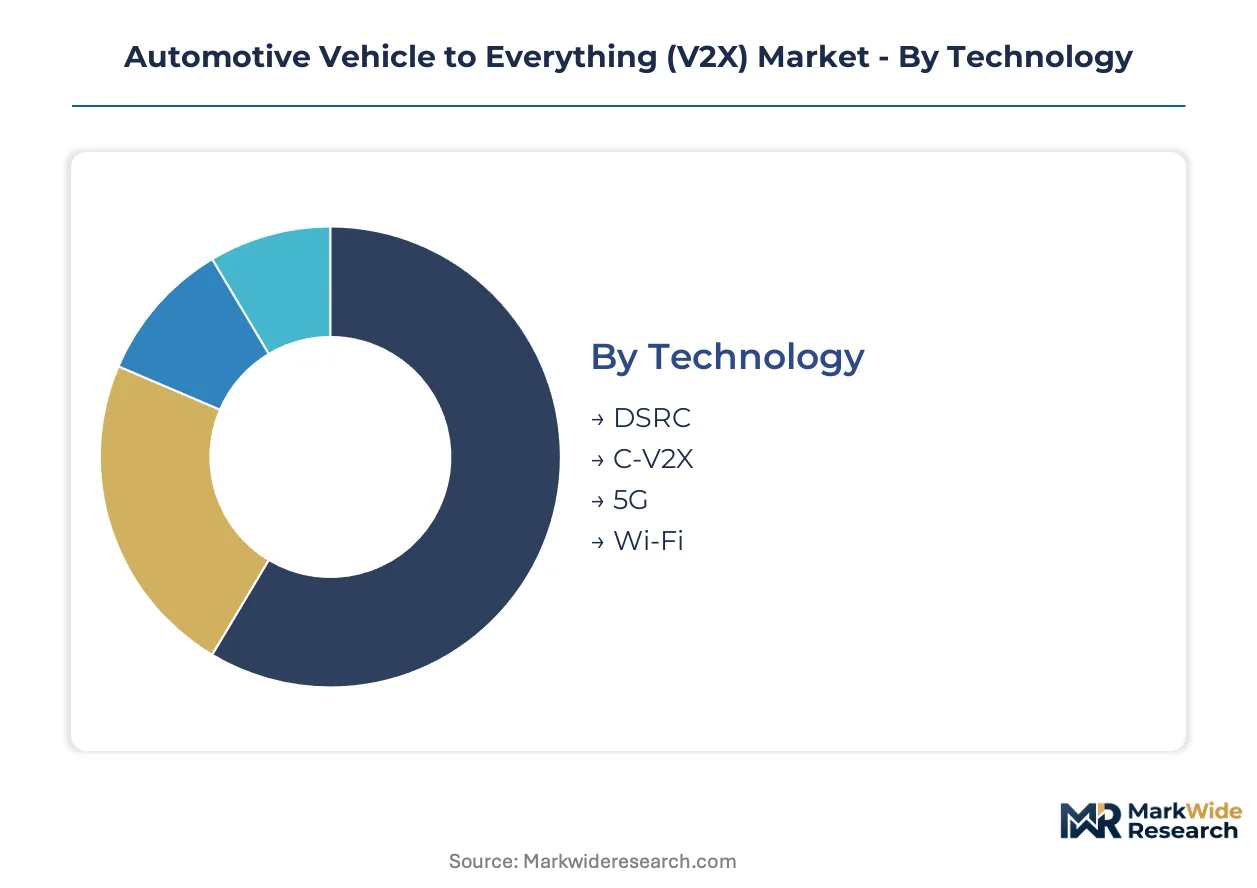
V2X procurement decisions fragment across technology generations, hardware-software bundles, and operator business models. Each segmentation axis reveals distinct margin structures and regulatory compliance burdens that reshape vendor competitive positioning.
Technology:
Standardization pressure intensifies at the DSRC-C-V2X boundary where spectrum reallocation mandates dual-source procurement strategies.
- C-V2X:Cellular-based protocols leverage existing 4G/5G infrastructure density to reduce roadside deployment costs in urban corridors. China's MIIT pilot zones and Germany's autobahn digitization programs concentrate procurement volume here, though rural coverage gaps in Australia and the United States constrain route mileage expansion.
- DSRC:Dedicated short-range communications deliver sub-100 millisecond latency through direct vehicle-to-vehicle broadcasts without cellular dependency. Early-adopter corridors in Michigan and California retain installed-base relevance, but FCC spectrum reallocation has stranded municipal investments and compressed equipment refresh cycles.
- 5G:Ultra-reliable low-latency communication slices enable cooperative perception with sub-20 millisecond end-to-end performance for autonomous navigation.
- Wi-Fi:IEEE 802.11p derivatives persist in legacy traffic signal integration projects requiring backward compatibility with proprietary municipal protocols.
Leading the category by volume: C-V2X. Expanding most quickly: 5G.
Component:
Margin capture migrates from capital hardware toward recurring service revenue as software-defined updates displace static equipment sales.
- On-board Units:Vehicle-integrated transceivers with secure element authentication dominate current component value capture. Automotive OEMs in Germany and Japan specify dual-mode DSRC-C-V2X configurations to hedge regulatory divergence, though silicon supply concentration in Taiwan exposes procurement timelines to geopolitical disruption.
- Service Platforms:Cloud-based traffic analytics and over-the-air update capabilities enable infrastructure-as-a-service subscription models. Texas and Florida departments of transportation now contract for intersection uptime metrics rather than capitalizing hardware, displacing traditional margin pools fastest.
- Roadside Units:Antenna and sensor modules for intersection intelligence bundle with edge computing compliance for multi-access edge computing architectures.
- Control Centers:Centralized traffic management integration requires costly middleware development to translate legacy proprietary signal protocols into V2X message formats.
Hardware concentration: On-board Units. Steepest expansion trajectory: Service Platforms.
Application:
Public funding availability and autonomous vehicle integration timelines segment addressable demand by margin profile.
- Traffic Management:Signal prioritization and congestion optimization attract sustained municipal investment through smart city certification programs. China's connected vehicle pilot zones and Germany's federal highway operators bundle roadside units with cloud platforms, creating multi-year service revenue visibility.
- Autonomous Driving:Cooperative perception for collision avoidance commands premium pricing where latency requirements compress below 20 milliseconds. Edge computing migration at cellular base stations automates real-time object fusion, positioning this segment for highest-margin long-term capture.
- Emergency Response:Preemption systems for ambulance and fire services leverage dedicated spectrum slices in Japan's METI-coordinated 5G-V2X convergence trials.
- Fleet Management:Commercial vehicle platooning and route optimization concentrate demand among logistics operators in designated freight corridors.
Current revenue concentration: Traffic Management. Gaining share fastest: Autonomous Driving.
End User:
Procurement authority and capital structure differentiate customer segments by contract duration and payment modality.
- Public Authorities:State and municipal departments of transportation control intersection infrastructure deployment through availability-based payment structures. FCC equipment authorization fragmentation and EU delegated regulation interoperability mandates force dual-mode specification requirements that disqualify single-technology vendors.
- Infrastructure Providers:Private concessionaires and toll road operators consolidate multi-year service contracts bundling hardware, installation, and cloud analytics. Sun Belt metropolitan expansion in Texas and Florida drives scalable connected corridor procurement through operational expenditure models.
- Automotive OEMs:Vehicle manufacturers integrate on-board units with secure element fabrication for Common Criteria cybersecurity certification.
- Fleet Operators:Commercial logistics and transit agencies specify fleet-wide V2X compliance for corridor access privileges in designated zones.
Contract volume leadership: Public Authorities. Fastest procurement model shift: Infrastructure Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates V2X infrastructure manufacturing while the United States and Germany drive consumption through smart corridor deployments. Taiwan anchors secure element fabrication for authentication protocols. Japan and South Korea accelerate 5G-V2X convergence trials.
United States
Municipal procurement in California and Michigan concentrates demand for dual-mode roadside units. The FCC's 5.9 GHz spectrum reallocation has stranded early DSRC investments and compressed equipment refresh cycles. Texas and Florida departments of transportation now contract for intersection uptime metrics through availability-based payment structures.
Germany
Federal highway operators bundle roadside units with cloud-based traffic management platforms, creating multi-year service revenue streams. The EU's delegated regulation on cooperative intelligent transport systems mandates interoperability standards across member states. Autobahn digitization programs in Bavaria and Baden-Württemberg drive scalable connected corridor deployment.
China
MIIT pilot zone expansion accelerates network access licenses for connected vehicle terminals in designated corridors. Municipal authorities seek smart city certification through roadside infrastructure procurement. Connected vehicle pilot zones in the Yangtze River Delta and Pearl River Delta concentrate deployment volume.
Japan
METI coordinates 5G-V2X convergence trials with domestic automotive manufacturers, creating specification pull for vulnerable road user detection systems. Preemption systems for emergency services leverage dedicated spectrum slices. Kanto and Kansai industrial corridors anchor testing infrastructure for cooperative perception applications.
Taiwan
Foundry concentration for secure element fabrication exposes procurement timelines to geopolitical disruption. Silicon supply bottlenecks affect authentication protocol chipsets for vehicle-to-network security. Hsinchu Science Park anchors semiconductor manufacturing for V2X component supply.
Automotive Vehicle to Everything (V2X) Market Competitive Landscape
The competitive structure tilts toward integrated chipset-roadside unit offerings. Semiconductor specialists and Tier 1 automotive suppliers dominate procurement channels. Two strategic archetypes prevail: cellular modem portfolio anchors and manufacturing-scale antenna module producers. Competitive moves center on dual-mode DSRC-C-V2X certification tracks and cloud-based service platform bundling.
Within the semiconductor archetype, Qualcomm, NXP Semiconductors, and Infineon Technologies occupy positions spanning secure element integration and authentication protocol specialization. Continental and Robert Bosch represent the Tier 1 automotive supplier tier with manufacturing-scale capabilities. Denso exemplifies the Japan-based industrial conglomerate model coordinating with METI trial programs. These groupings reflect how vendor selection criteria now mandate pre-certified dual-mode product portfolios under EU delegated regulation and FCC equipment authorization pathways.
| Leading Market Players |
|---|
| Qualcomm |
| Continental |
| Harman International |
| Autotalks |
| Denso |
| NXP Semiconductors |
| Robert Bosch |
| LG Innotek |
| Infineon Technologies |
| Others |
Pricing and Supply Chain Analysis
Cellular modem integration into dual-mode roadside units is compressing hardware margins while concentrating procurement leverage among semiconductor foundries with 5G-V2X certification capabilities. This technology transition simultaneously elevates service-platform recurring revenue and exposes municipal buyers to silicon supply bottlenecks in Taiwan.
Pricing Analysis
Cost compression in roadside hardware accelerates because FCC dual-certification requirements inflate R&D amortization across smaller production runs. Three-tier pricing structure across premium, standard, and economy levels separates edge-computing-enabled units from basic signal-transmission models, with certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from municipal procurement teams in Texas and Florida specifying availability-based payment structures that shift capital expenditure to operational expenditure. Public authorities demonstrate highest price sensitivity due to budget cycle constraints, while autonomous vehicle developers accept premium tiers for sub-20 millisecond latency guarantees.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Germany's autobahn digitization programs and China's MIIT pilot zones, bypassing traditional distribution intermediaries. Component fabrication concentrates in Taiwan for secure element authentication chipsets, South Korea for cellular modem silicon, and Germany for antenna module assembly. Raw material dependencies include gallium nitride substrates for high-frequency transmission, automotive-grade epoxy resins for roadside unit housing, and rare earth elements for antenna magnetics. Single-source vulnerability in Taiwan's foundry base exposes procurement timelines to geopolitical disruption. Distribution runs through Tier 1 automotive supplier networks for on-board unit integration and cloud service provider partnerships for platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
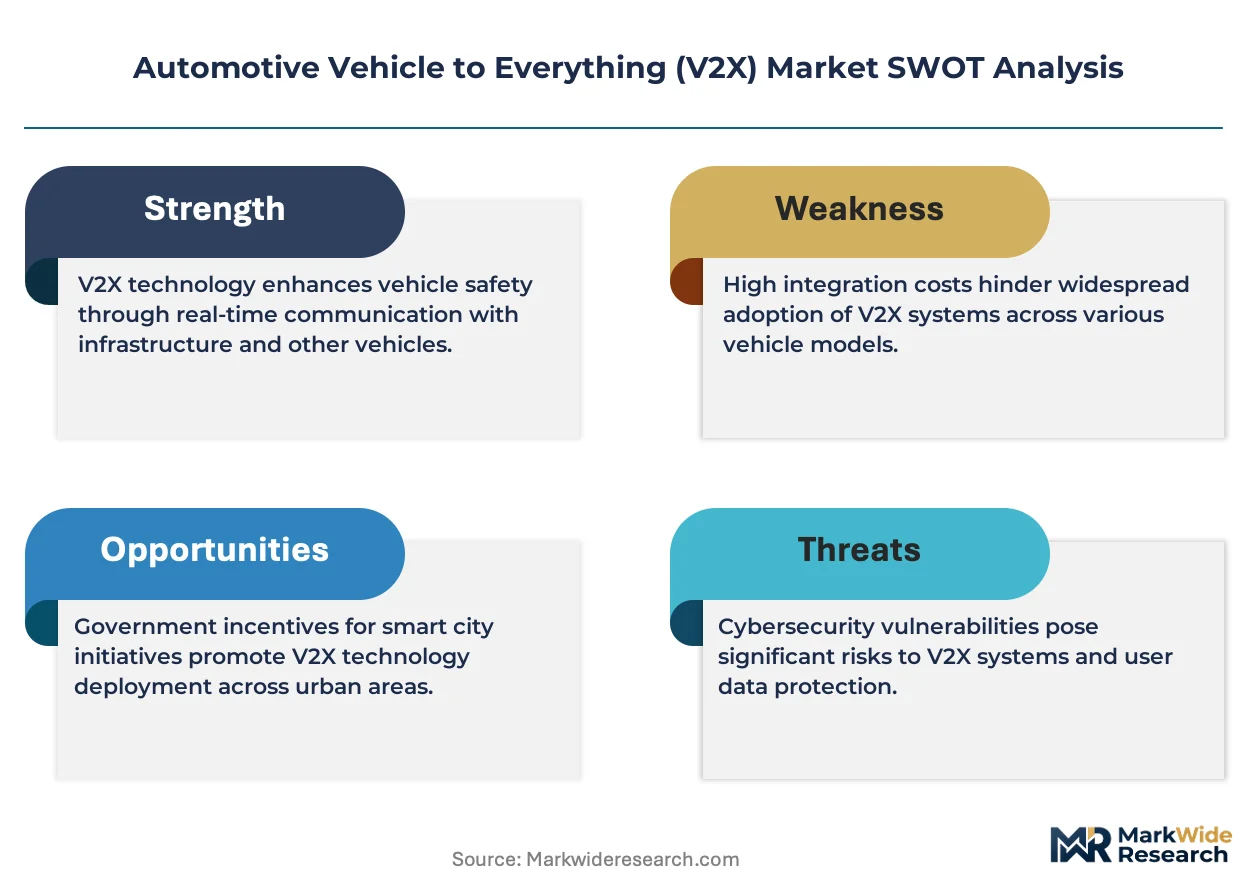
This market consolidates around vendors with pre-certified dual-mode portfolios as EU delegated regulation and FCC equipment authorization fragmentation eliminate single-technology competitors.
For Market Incumbents: Anticipate margin compression in hardware-only segments by accelerating software-defined roadside unit deployment with over-the-air update capabilities. Secure captive supply of secure element fabrication capacity through foundry partnerships in Taiwan to mitigate geopolitical disruption risk. Reinforce position in Germany's autobahn digitization programs through cloud-based traffic management platform bundling that locks in multi-year service revenue streams. For New Entrants and Emerging Players: Cloud-native service platforms offer the most penetrable entry vector, targeting municipal authorities in Sun Belt metropolitan areas seeking subscription-based intersection intelligence rather than capital expenditure procurement. Focus initial deployment on Texas and Florida departments of transportation with availability-based payment structures. Pursue partnership routes with existing Tier 1 automotive suppliers to bypass lengthy Common Criteria cybersecurity certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor specialists with dual-mode DSRC-C-V2X certification tracks and established foundry relationships. Long-term viability favors vendors with integrated chipset-roadside unit offerings that capture margin migration from hardware to service platforms. Monitor FCC waiver processing velocity for C-V2X equipment authorization as inflection indicator for technology roadmap consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Mode Certification Investment | FCC and EU delegated regulation compliance secures eligibility for municipal procurement contracts in California and Germany. |
| Cloud Platform Integration | Texas and Florida departments of transportation now mandate over-the-air update capabilities in service contracts. |
| Secure Element Supply Agreement | Taiwan foundry partnerships mitigate authentication protocol chipset shortages affecting vehicle-to-network security. |
| Edge Computing Deployment | Multi-access edge computing compliance enables sub-20 millisecond latency for autonomous navigation applications. |
| Pedestrian Protection System Development | Japan's METI 5G-V2X convergence trials create specification pull for vulnerable road user detection capabilities. |
Research Methodology
Multi-period observation of roadside infrastructure procurement volumes, spectrum policy filings, and municipal contract awards anchored the trend analysis, supplemented by interviews with Tier 1 automotive supplier procurement directors, OEM platform engineers, state department of transportation planning officers, and cloud service provider account executives. Secondary validation drew from FCC equipment authorization databases, EU delegated regulation implementation notices, MIIT network access license registries, and vehicle production databases. Bottom-up triangulation across municipal contract values and top-down validation against semiconductor shipment data ensured cross-source consistency.
Input-output matrices modeled relationships between cellular infrastructure density, chipset certification timelines, and service-platform adoption rates across the projection horizon. Segmentation dimensions included technology generation, component type, application function, and end-user procurement authority. CAGRs were derived from regression analysis of historical deployment trajectories in Germany's autobahn corridors and China's pilot zones, with elasticity adjustments for spectrum reallocation policy shocks.
The model holds under stable regulatory frameworks for 5.9 GHz ITS band utilization; deviation in FCC waiver processing timelines or EU interoperability mandate enforcement would shift equipment refresh cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Fleet Management Software Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market
Smart Transportation Solutions
Vietnam Ride-Hailing Market
Smart Transportation Solutions
Car E-Hailing Market
Smart Transportation Solutions
Global Intelligent Traffic Management System Market
Smart Transportation Solutions
Europe Smart Parking Market
Smart Transportation Solutions
Intermodal Corridor Performance Monitoring Dashboards Market
Smart Transportation Solutions
Road Asset Management Software Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Closed Platform Screen Doors Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Smart Parking Technologies Market