
 Ride-Hailing Market | 2026-2036
Ride-Hailing Market Size, Share, and Industry Trends Forecast 2026-2036
Ride-Hailing Market Analysis
India's driver-partner network expansion is reconfiguring how platforms allocate supply across dense urban corridors. Uber Technologies Inc. leverages its mapping infrastructure to optimize pickup times in congested metros. Didi Chuxing anchors its position through deep integration with local payment ecosystems. Bolt Technology OÜ competes on price-transparent commissions in European and African cities.
Ride-hailing denotes digitally intermediated on-demand passenger transport where algorithms match private vehicle operators with riders via GPS-tracked, cashless mobile applications. The system relies on real-time demand forecasting, dynamic surge pricing, and two-sided marketplace liquidity to minimize wait times below five minutes in optimal conditions. Shared Ride services now absorb disproportionate volume growth as cost-conscious commuters split fares across pooled routes. Electric Vehicle deployment within fleet segments attracts platform subsidies and municipal preferential lane access, concentrating margin improvement potential. Luxury Ride categories sustain premium pricing power through consistent vehicle quality standards and trained driver protocols.
FAA guidelines govern aerial ride-hailing trials in the United States, while the EU AI Act imposes algorithmic transparency requirements on dispatch systems across member states. India's CEA and state transport authorities enforce EV fleet mandates and driver background verification protocols that shape market entry costs. Stakeholders must monitor how biometric identity standards and carbon accounting rules reshape platform liability and capital allocation priorities.
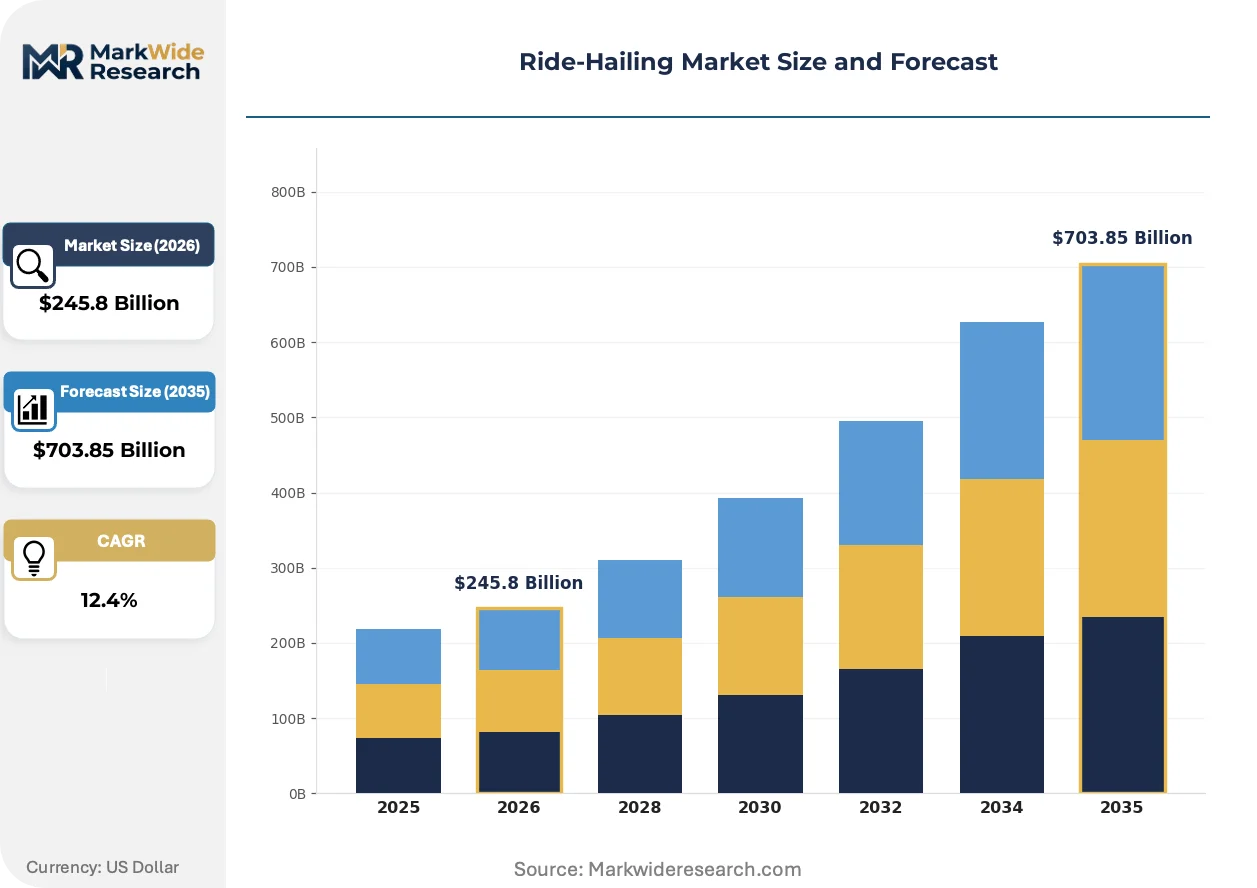
Market Dynamics
Fleet electrification mandates and algorithmic dispatch optimization are compressing unit economics while expanding addressable trip volumes in dense urban corridors. The EU Green Deal and local zero-emission zones are accelerating platform capital reallocation toward EV infrastructure.
Growth Catalysts
- EU Green Deal fleet mandates:Zero-emission zone designations in Amsterdam, Brussels, and Paris force platform EV procurement, creating guaranteed demand for electric vehicle manufacturers and charging network operators.
- Smartphone penetration in emerging economies:India, Brazil, and Indonesia exhibit informal transport substitution patterns where unregulated auto-rickshaws and motorcycle taxis convert to platform-mediated trips.
- Dynamic surge pricing algorithms:Real-time demand forecasting models reduce deadheading and improve driver utilization rates during peak congestion windows.
Market Restraints
- Driver supply concentration risk:Megacity corridors in São Paulo and Mumbai exhibit driver-partner clustering that creates localized supply gluts and earnings volatility.
- EV charging infrastructure gaps:Battery range limitations and sparse fast-charging networks in secondary Indian and Indonesian cities constrain fleet electrification timelines.
- Regulatory classification friction:Labor reclassification rulings in California, the United Kingdom, and the Netherlands impose benefit cost structures that compress platform margins.
Strategic Opportunities
- Intercity corridor expansion:Underpenetrated routes connecting Indian tier-2 cities present white space for scheduled shared-ride services with fixed pricing.
- Micromobility convergence:Integration of electric scooters and bicycles with ride-hailing apps creates multimodal trip chaining in European and Latin American urban cores.
- Corporate mobility contracts:Enterprise account structures with Fortune 500 firms generate predictable demand volumes and reduce customer acquisition costs.
Industry Challenges
- Driver retention and earnings optimization:Platform algorithms must balance supply incentives with fare affordability, requiring continuous recalibration of take rates and bonus structures.
- Biometric identity verification compliance:India's CEA and state transport authority protocols mandate real-time driver background checks that increase onboarding friction and operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ride-Hailing Market |
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $703.85 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Traditional Taxi, Luxury Ride, Shared Ride, Motorcycle Taxi Customer Type: Business Travelers, Commuters, Tourists, Students Technology: Mobile App, Web-Based Platform, GPS Tracking, Cashless Payment Vehicle Type: Sedan, SUV, Minivan, Electric Vehicle |
| Companies Covered | Lyft Inc., Ola Electric Mobility Pvt. Ltd., Uber Technologies Inc., inDrive (SUOL Innovations Ltd), Gett, Didi Chuxing, Bolt Technology OÜ, BlaBlaCar, Grab Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ride-Hailing Market Emerging Trajectories
Autonomous vehicle testing and aerial mobility pilots are fragmenting the competitive landscape beyond ground transport. Platform operators now face capital allocation decisions across multiple mobility modalities.
Autonomous ride-hailing fleets are rendering obsolete the two-sided marketplace model dependent on human driver supply. Waymo and Baidu Apollo scale robotaxi deployments in Phoenix and Wuhan. The structural consequence compresses per-mile operating costs while eliminating driver earnings as a platform expense.
The EU AI Act imposes algorithmic transparency requirements on dispatch systems across member states. Ride-hailing platforms must document decision logic for surge pricing and driver assignment. French and German operators face the steepest compliance timelines given existing data protection precedent under CNIL and BDSG frameworks.
Corporate procurement departments now unbundle ground transport from traditional fleet management contracts. Subscription-based mobility budgets replace vehicle allowances in London, Singapore, and San Francisco technology sectors. This shift concentrates buyer power among enterprise procurement teams while pressuring per-trip margins.
Ride-Hailing Market Segmentation
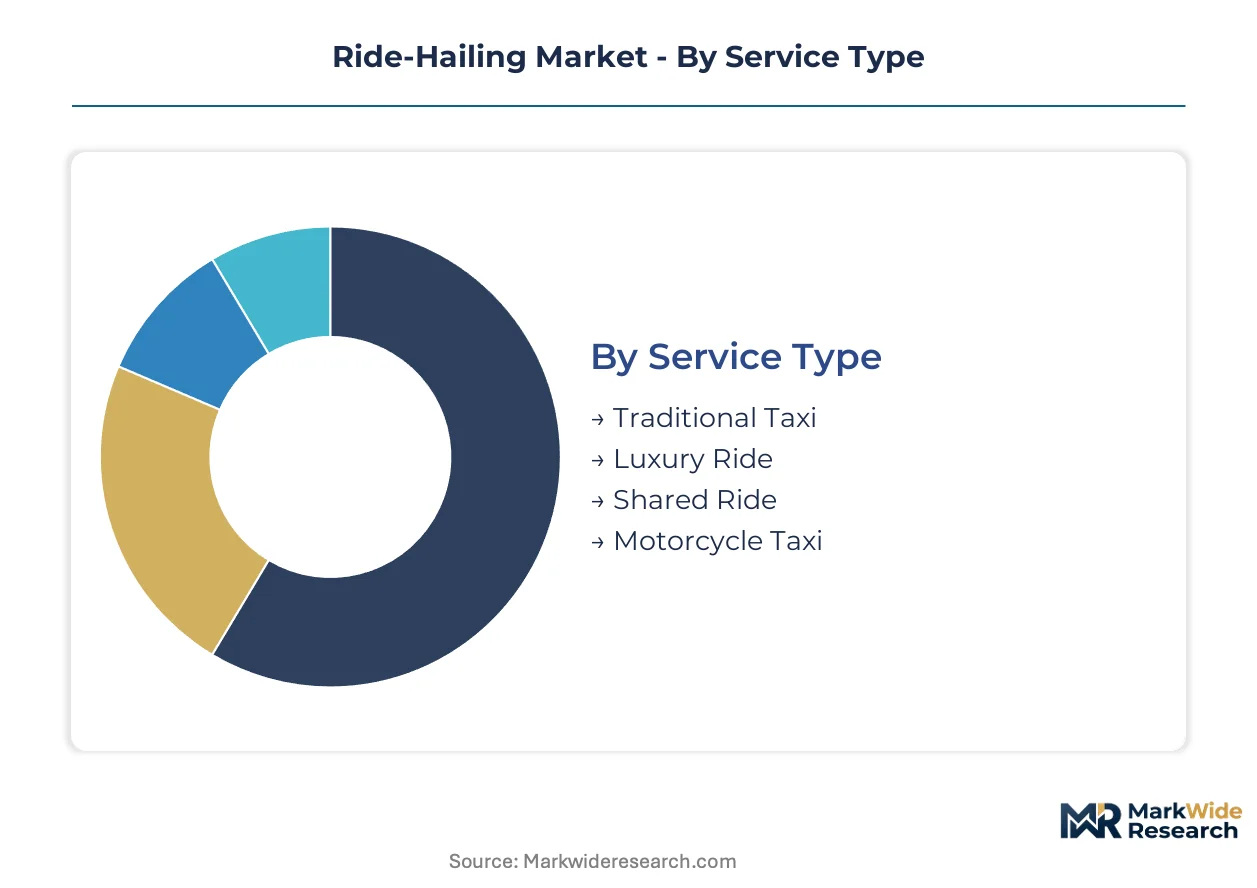
Ride-hailing platforms calibrate supply allocation algorithms differently across service tiers, with Shared Ride turnover compressing to sub-90-second matching cycles while Luxury Ride maintains deliberate scarcity. Customer behavioral patterns and vehicle capital intensity create divergent margin profiles that reshape platform investment priorities.
Service Type:
Shared Ride cycles fastest through demand-supply matching, while Luxury Ride maintains the longest driver wait tolerance windows. Traditional Taxi occupies intermediate velocity with regulated dispatch protocols.
- Traditional Taxi:Digitally intermediated licensed cab services operating under municipal fare regulations with mandatory meter integration. Demand concentrates in European capitals where Paris and Berlin enforce fleet age standards that accelerate platform compliance costs.
- Luxury Ride:Premium vehicle categories with trained chauffeur protocols and guaranteed interior quality specifications. High-net-worth commuter corridors in London and Dubai sustain pricing power through consistent service standardization.
- Shared Ride:Pooled route matching algorithms split fares across multiple passenger pickups with dynamic routing optimization. Cost-conscious Indian and Indonesian urban corridors absorb disproportionate volume expansion.
- Motorcycle Taxi:Two-wheeler dispatch services optimized for hyper-congested Southeast Asian and Latin American urban cores with sub-three-minute pickup guarantees.
Traditional Taxi dominates installed base across regulated metropolitan markets. Shared Ride is where expansion concentrates.
Customer Type:
Commuters generate predictable recurring revenue with lower acquisition expenditure, while Tourists exhibit seasonal volatility with elevated per-trip spending.
- Business Travelers:Corporate account-linked riders requiring receipt automation and scheduled reliability guarantees. Enterprise procurement teams in Singapore and San Francisco negotiate fixed-rate contracts that reduce platform margin variability.
- Commuters:Daily recurring trip patterns with subscription pass adoption and route memorization algorithms. Dense Indian megacity corridors exhibit highest frequency-per-user metrics globally.
- Tourists:Intermittent high-value trips concentrated around airport corridors and hospitality districts with multilingual driver matching requirements.
- Students:Price-sensitive demographic with promotional code sensitivity and off-peak utilization patterns concentrated near university clusters.
Commuters anchor recurring revenue stability. Business Travelers is where premium pricing expansion concentrates.
Technology:
Mobile App deployment cycles accelerate with OS update compatibility requirements, while Cashless Payment infrastructure matures slowly in emerging market corridors.
- Mobile App:Native iOS and Android applications with real-time GPS matching and push notification dispatch. Brazilian and Nigerian markets exhibit fastest feature adoption velocity for in-app safety toolkits.
- Web-Based Platform:Browser-accessible booking interfaces targeting occasional users and corporate administrator dashboards. Enterprise procurement integration in German manufacturing sectors sustains niche demand.
- GPS Tracking:Real-time vehicle location telemetry enabling ETA prediction and route optimization algorithms. Regulatory mandates in Indian metro regions require continuous location transmission to transport authorities.
- Cashless Payment:Digital wallet integration with local banking rails and buy-now-pay-later options. Indonesian and Vietnamese corridors retain hybrid cash-digital models due to banking penetration gaps.
Mobile App dominates active user interface deployment. Cashless Payment is where financial inclusion expansion concentrates.
Vehicle Type:
Sedan fleet turnover accelerates with platform depreciation schedules, while Electric Vehicle procurement extends capital replacement cycles due to battery warranty structures.
- Sedan:Four-door passenger vehicles optimized for single-to-dual rider efficiency with standardized trunk capacity. Indian and Mexican urban corridors maintain highest sedan-to-SUV ratios due to fuel economy priorities.
- SUV:Higher-capacity vehicles commanding fare premiums for airport transfers and group travel with luggage requirements. Middle Eastern and Australian markets exhibit sustained SUV preference for climate and terrain adaptation.
- Minivan:Multi-passenger configurations targeting Shared Ride density and accessibility compliance with wheelchair ramp specifications.
- Electric Vehicle:Battery-electric powertrains qualifying for municipal preferential lane access and zero-emission zone entry. Amsterdam and Brussels regulatory mandates force accelerated fleet conversion timelines.
Sedan dominates current fleet composition. Electric Vehicle is where regulatory-driven replacement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India converts unregulated auto-rickshaws into platform-mediated trips at scale, while Brazil and Indonesia exhibit similar informal transport substitution patterns. The United States concentrates autonomous vehicle testing corridors. Europe enforces zero-emission zone mandates that reconfigure fleet procurement timelines.
United States
Corporate mobility contracts and airport corridor density drive platform revenue concentration. FAA guidelines govern aerial ride-hailing trials in urban air mobility corridors. Phoenix anchors Waymo's robotaxi deployment at scale, while San Francisco technology firms unbundle ground transport from traditional fleet management.
India
Smartphone penetration and motorcycle taxi conversion absorb disproportionate trip volume expansion. The CEA and state transport authorities enforce EV fleet mandates and driver background verification protocols. Mumbai and Bengaluru megacity corridors exhibit driver-partner clustering that creates localized supply dynamics.
Brazil
Informal transport substitution patterns convert unregulated services into platform-mediated trips. ANVISA and municipal regulators shape operational compliance frameworks. São Paulo exhibits driver supply concentration risk in dense urban corridors with earnings volatility pressures.
Germany
Enterprise procurement integration and premium service tier demand sustain pricing power. The EU AI Act imposes algorithmic transparency requirements on dispatch systems; BDSG frameworks steepen compliance timelines. Berlin enforces fleet age standards that accelerate platform compliance costs.
Indonesia
Banking penetration gaps sustain hybrid cash-digital payment models alongside motorcycle taxi optimization. The country's national transport regulator mandates real-time location transmission to authorities. Jakarta and Surabaya urban cores concentrate two-wheeler dispatch services with sub-three-minute pickup guarantees.
Ride-Hailing Market Vendor Landscape
Capability concentration sits with mapping infrastructure and algorithmic dispatch specialists; scale advantage sits with network-effect platforms that have achieved liquidity in dense urban corridors. The structure fragments across three strategic archetypes: global network operators with multimodal integration, regional price-competitive challengers, and autonomous fleet developers. Dominant competitive moves include strategic partnerships with local payment ecosystems and portfolio diversification into micromobility convergence.
Among North American network operators, Lyft Inc. and Uber Technologies Inc. occupy positions anchored by mapping infrastructure and enterprise contract penetration. Didi Chuxing represents the regional integration archetype through deep payment ecosystem embedding. Within the autonomous development tier, technology-focused entities exemplify capital reallocation toward eliminating driver supply dependency.
| Leading Market Players |
|---|
| Lyft Inc. |
| Ola Electric Mobility Pvt. Ltd. |
| Uber Technologies Inc. |
| inDrive (SUOL Innovations Ltd) |
| Gett |
| Didi Chuxing |
| Bolt Technology OÜ |
| BlaBlaCar |
| Grab Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Shanghai-Ningbo port freight corridors transmit cost volatility into driver earnings structures, compressing take rates while amplifying price differentiation between EV-compliant and legacy fleet tiers. Platform algorithms translate supply concentration in battery manufacturing hubs into dynamic surge premiums that vary by vehicle certification status.
Pricing Analysis
Mumbai-São Paulo fare spreads exceed 40% for equivalent distances when accounting for local fuel subsidies and platform commission structures. Three-tier pricing structure across premium, standard, and economy levels anchors on vehicle age thresholds and driver training certification tiers. Pricing pressure stems from driver supply gluts in megacity corridors where earnings volatility triggers churn. Students and price-sensitive commuters exhibit highest elasticity, while corporate account riders absorb premium tiers with minimal attrition.
Supply Chain Analysis
BIS and DGFT export-control classifications on lithium-ion cell technology constrain battery procurement flows for Indian and Indonesian platform operators. Supply concentration centers on China, South Korea, and Japan for cell manufacturing, with copper busbars and thermal management systems as critical tier-2 dependencies. Single-source vulnerability in NMC cathode chemistry exposes fleet electrification timelines to commodity price swings. Distribution runs through OEM-direct procurement contracts with volume commitments and warranty service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ride-hailing operates as a high-growth disruption where autonomous vehicle deployment and EU AI Act algorithmic mandates constitute simultaneous technological and regulatory inflection points reshaping capital allocation priorities.
For Market Incumbents: Entrench mapping infrastructure advantage through proprietary HD map refresh cycles in dense urban corridors where Waymo and Baidu Apollo threaten dispatch optimization moats. Secure backward integration into EV charging networks in Amsterdam and Brussels zero-emission zones to lock in preferential lane access. Deepen driver retention algorithms before robotaxi scale eliminates human supply dependency. For New Entrants and Emerging Players: Tier-2 Indian city intercity corridors represent the most penetrable entry point for scheduled shared-ride services with fixed pricing and reduced driver acquisition costs. Indonesian motorcycle taxi white space outside Jakarta-Surabaya cores offers sub-three-minute pickup guarantees with lower platform liquidity requirements. Partner with local payment ecosystem providers to bypass incumbent wallet integration barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEM mobility subsidiaries where fleet management divisions face stranded asset risk from electrification mandates. Long-term viability hinges on autonomous fleet transition timelines and regulatory capture in zero-emission zone designations. Watch for FAA aerial ride-haling certification milestones as signal for urban air mobility capital redeployment.| Strategic Initiative | Industry Significance |
|---|---|
| EV Fleet Conversion Partnership | Brussels and Amsterdam zero-emission mandates force accelerated procurement from CATL and BYD supply lines. |
| Algorithmic Transparency Compliance | EU AI Act documentation requirements for surge pricing logic impose CNIL and BDSG audit timelines on French and German operators. |
| Intercity Scheduled Service Launch | Indian tier-2 corridor expansion captures informal transport substitution with fixed-fare predictability. |
| Micromobility Integration | Electric scooter chaining in São Paulo and Mexico City reduces first-last-mile friction and trip abandonment. |
| Corporate Mobility Contract Expansion | Fortune 500 procurement teams in San Francisco and Singapore negotiate predictable volume commitments reducing CAC volatility. |
Methodological Framework
A spread of perspectives from platform operations executives, fleet procurement managers, driver-partner network coordinators, and municipal transport authority regulators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings, EU regulatory submissions, Indian CEA mandate documentation, and vehicle registration databases. Bottom-up trip volume modeling and top-down GDP-elasticity approaches triangulated on segment-level outputs.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with service tier, vehicle type, customer segment, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from historical trajectory analysis and driver-partner growth elasticity coefficients. Forecast inputs incorporated EV fleet mandate compliance timelines and autonomous vehicle deployment corridor density.
Macroeconomic conditions sit as an overlay; deviation in fuel price volatility and central bank digital payment adoption curves would shift the trajectory. Forecasts reflect documented assumptions on driver retention algorithms and battery cost depreciation curves. Material shifts in FAA aerial ride-hailing certification timelines or EU AI Act enforcement severity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Global Ridesharing Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Rail Freight Digital Transformation Market
Smart Transportation Solutions
Shared Mobility Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
Semi Height Platform Screen Door Market
Smart Transportation Solutions
Vertical Mobility Market
Smart Transportation Solutions
Middle East and Africa Passenger Information System Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Platform Screen Doors Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Smart Fleet-On-Board Devices Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Mobility Technologies Market