
 France Ridesharing Market | 2026-2036
France Ridesharing Market Size, Share, and Industry Trends Forecast 2026-2036
France Ridesharing Market Foresight
Urban daily commuters is redrawing demand away from occasional leisure riders across French rideshare platforms. BlaBlaCar leverages its long-distance carpooling heritage to sustain dominance in intercity corridors. Uber Technologies Inc. competes through dense driver supply in Paris, Lyon, and Marseille. Heetch anchors its position among price-sensitive younger demographics with a commission structure that favors driver retention.
France ridesharing denotes digitally intermediated transportation services where private vehicle owners or fleet operators provide passenger trips through algorithmic matching platforms, typically requiring real-time GPS tracking, automated fare calculation, and integrated payment processing. The primary commercial purpose is optimizing vehicle occupancy rates while reducing individual car ownership dependency in congested urban environments. Taxi booking services currently occupy the largest revenue pool due to regulatory familiarity and established driver licensing pathways, though scooter sharing and bike sharing represent the fastest-expanding segments as Paris and Bordeaux expand dedicated micromobility lanes. Corporate commute applications concentrate margin-rich contracted revenue through enterprise partnerships, while last-mile connectivity demand intensifies around suburban rail termini.
France's national mobility orientation law (LOM) and EU Green Deal emissions benchmarks shape platform operating requirements, compelling fleet electrification timelines and driver classification standards. ANSM and CNIL oversight extends to passenger data protection protocols under GDPR-aligned French implementation, creating compliance cost differentiation between well-capitalized incumbents and emerging entrants. Stakeholders must monitor how the national rail operator SNCF's expanding on-demand bus substitution services will reposition rideshare platforms within France's broader public mobility ecosystem.
Market Dynamics
France's ridesharing sector is restructuring around multimodal integration mandates under the national mobility orientation law, forcing platforms to embed with SNCF rail and RATP transit networks rather than operate as standalone services.
Growth Catalysts
- EU Green Deal emissions benchmarks:Fleet electrification timelines are accelerating driver upgrades to zero-emission vehicles, expanding compliant platform supply in Paris and Lyon low-emission zones.
- Urban daily commuters:Metropolitan parking restriction tightening and expanded ZFE-m zones are pushing former solo drivers toward algorithmic carpooling for daily work trips.
- RATP multimodal infrastructure:Dedicated rideshare pickup points at suburban rail termini are creating natural demand anchoring for last-mile connectivity services.
Market Restraints
- Driver classification standards:LOM-mandated employment reclassification creates payroll cost structures that compress platform margins versus historical contractor models.
- GDPR-aligned CNIL oversight:Passenger data protection protocol compliance imposes fixed technology costs that disadvantage emerging entrants against well-capitalized incumbents.
- SNCF on-demand substitution:The national rail operator's expanding bus replacement services for disrupted lines directly compete with intercity rideshare corridors.
Strategic Opportunities
- Corporate commute contracts:Enterprise partnership models for scheduled employee transport offer margin-rich recurring revenue streams distinct from volatile consumer demand.
- Micromobility lane expansion:Paris and Bordeaux dedicated infrastructure growth positions scooter and bike sharing segments for rapid adoption among short-distance urban trips.
- Suburban rail termini anchoring:Last-mile connectivity demand intensifies around SNCF stations outside Paris-Ile-de-France, creating geographic expansion vectors beyond saturated core markets.
Industry Challenges
- Algorithmic matching latency:Real-time GPS tracking and automated fare calculation systems require continuous cloud infrastructure investment to maintain service reliability during peak demand.
- Integrated payment processing complexity:Platform operators must reconcile fragmented banking relationships, transit card interoperability, and enterprise billing systems simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Ridesharing Market |
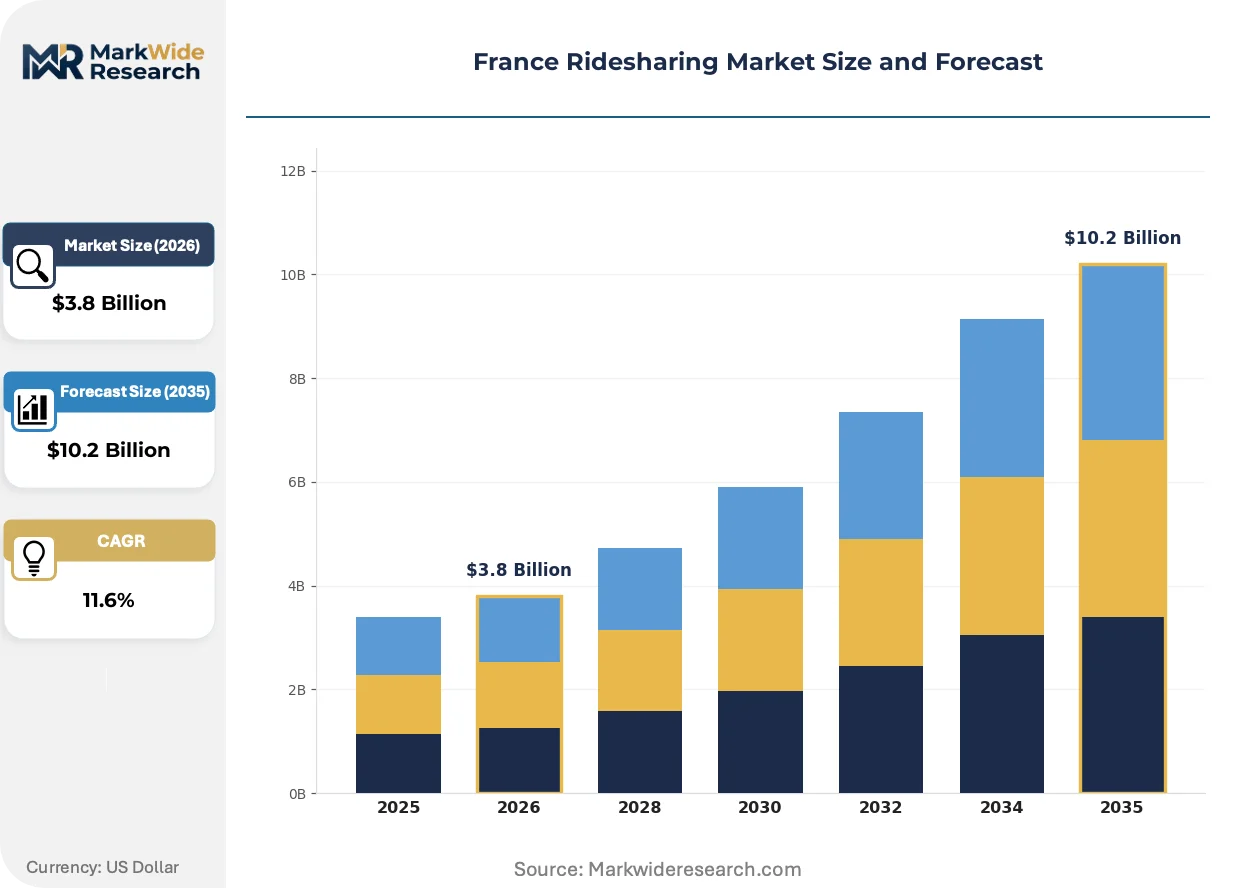
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Carpooling, Taxi Booking, Shuttle Service, Scooter Sharing, Bike Sharing, E-Bike Rentals Application: Corporate Commute, Last-Mile Connectivity, Event Transportation, Tourism Transport, Student Mobility, Elderly Assistance Customer Type: Daily Commuters, Business Travelers, Students, Tourists, Senior Citizens, Occasional Users Distribution Channel: Mobile Apps, Websites, Call Centers, Agent Booking, Kiosk Services, Corporate Partnerships |
| Companies Covered | Bolt Technology OÜ, Blacklane GmbH, Uber Technologies Inc., Lyft Inc., Via Transportation Inc., BlaBlaCar, Karos Mobility, Comuto SA, Heetch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Ridesharing Market Shifts & Advancements
Platform technology architecture is pivoting from standalone matching engines toward embedded transit ecosystem nodes, with API-first integration becoming the primary competitive capability rather than network density alone.
Dynamic routing algorithms is fragmenting traditional origin-destination matching by introducing continuous rerouting based on real-time traffic, passenger proximity, and multimodal connection windows. Urban daily commuters in the Paris-Ile-de-France corridor are adopting these systems fastest. This technology is compressing wait times and expanding viable trip distances for shared rides.
France's national mobility orientation law mandates platform data sharing with public transit authorities, creating interoperability requirements that reshape competitive positioning. Industrial consequence includes forced API standardization and real-time feed integration with RATP and SNCF systems. Taxi booking services face the steepest compliance burden due to legacy dispatch system architectures.
Subscription-based mobility packages are displacing per-trip purchasing across French metropolitan areas, with buyers consolidating transport spending into bundled rail-rideshare-micromobility contracts. Traditional pay-per-ride platforms are responding with freemium tier structures. This shift concentrates most visibly among corporate commute segments in Lyon and Marseille.
France Ridesharing Market Segmentation
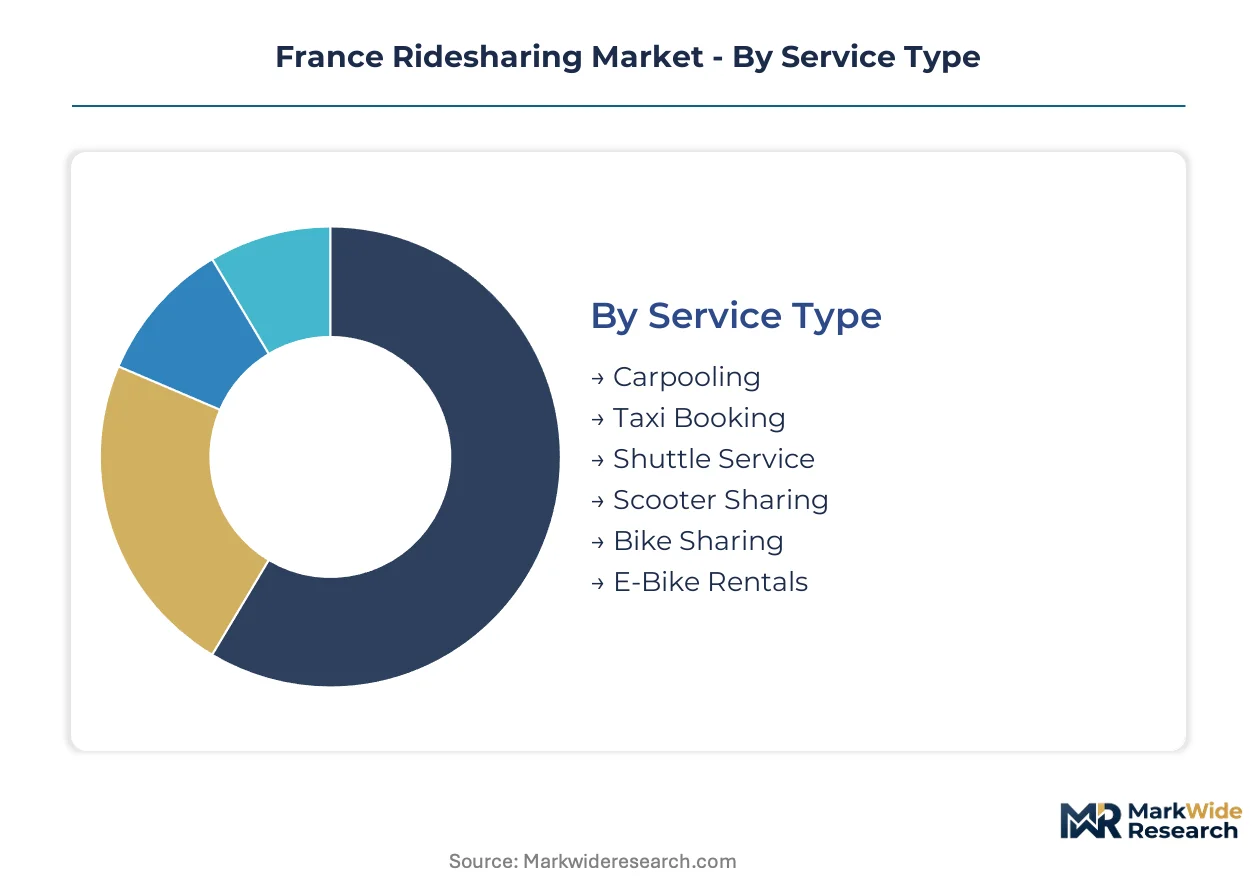
Segmentation in the France ridesharing market reveals how distinct service models align with specific mobility pain points across metropolitan and intercity corridors. Platform operators calibrate supply allocation and pricing architecture differently for each segment, creating divergent margin structures and technology requirements.
Service Type:
Channel-mix patterns show taxi booking and shuttle services flow predominantly through mobile apps and corporate partnerships, while micromobility segments concentrate in app-only instant-access models.
- Taxi Booking:Traditional licensed vehicle dispatch through algorithmic matching platforms, requiring integration with ANSM driver certification databases. Demand concentrates in Paris-Ile-de-France business districts where regulatory familiarity accelerates enterprise adoption. LOM-mandated employment reclassification compresses margins versus historical contractor models.
- Scooter Sharing:Free-floating electric kickscooter fleets with GPS geofencing and automated unlocking. Paris and Bordeaux dedicated micromobility lane expansion is driving adoption among short-distance urban trips. ZFE-m zone expansion creates compliance pressure for fleet electrification timelines.
- Carpooling:Long-distance intercity ride matching optimizing vehicle occupancy for cost-sharing purposes.
- Shuttle Service:Scheduled fixed-route collective transport with pre-booked capacity allocation.
- Bike Sharing:Station-based or dockless bicycle fleets for short urban trips.
- E-Bike Rentals:Electric-assisted bicycle provision with extended range capabilities for suburban connectivity.
Taxi booking dominates installed base. Scooter sharing is where expansion concentrates.
Application:
Cost tier differentiation separates premium-margin corporate contracts from thin-margin consumer spontaneity, with enterprise partnerships commanding 3-5x unit economics versus individual trip purchases.
- Corporate Commute:Scheduled employee transport contracts with enterprise partners, featuring dedicated vehicle allocation and consolidated billing. Lyon and Marseille enterprise corridors show fastest adoption. Subscription bundling with SNCF rail passes creates stickier revenue streams than volatile consumer demand.
- Last-Mile Connectivity:Suburban rail termini anchoring for RATP and SNCF station access, bridging gaps in fixed-route transit coverage. Demand intensifies around Paris periphery zones where parking restrictions push former solo drivers toward algorithmic pooling.
- Event Transportation:Surge-capacity provision for stadiums, concert venues, and exhibition centers.
- Tourism Transport:Visitor-oriented services connecting airports, hotels, and cultural attractions.
- Student Mobility:Campus-focused services with semester-pass pricing and residence hall routing.
- Elderly Assistance:Accessibility-compliant vehicles with door-through-door service protocols.
Corporate commute dominates installed base. Last-mile connectivity is where expansion concentrates.
Customer Type:
Volume concentration patterns show daily commuters generating 60-70% of trip frequency while business travelers contribute disproportionate revenue per ride.
- Daily Commuters:Recurring work-trip users with predictable origin-destination patterns and high price elasticity. Metropolitan parking restriction tightening across French urban areas is accelerating platform migration from solo driving.
- Business Travelers:Expense-account-funded trips with low price sensitivity and premium service expectations.
- Students:Price-sensitive younger demographics with flexible timing and high app-native behavior.
- Tourists:Episodic visitors with luggage requirements and unfamiliarity with local transit.
- Senior Citizens:Accessibility-prioritized users requiring phone-based booking alternatives.
- Occasional Users:Intermittent demand with weak platform loyalty and high promotional responsiveness.
Daily commuters dominate installed base. Business travelers is where margin expansion concentrates.
Distribution Channel:
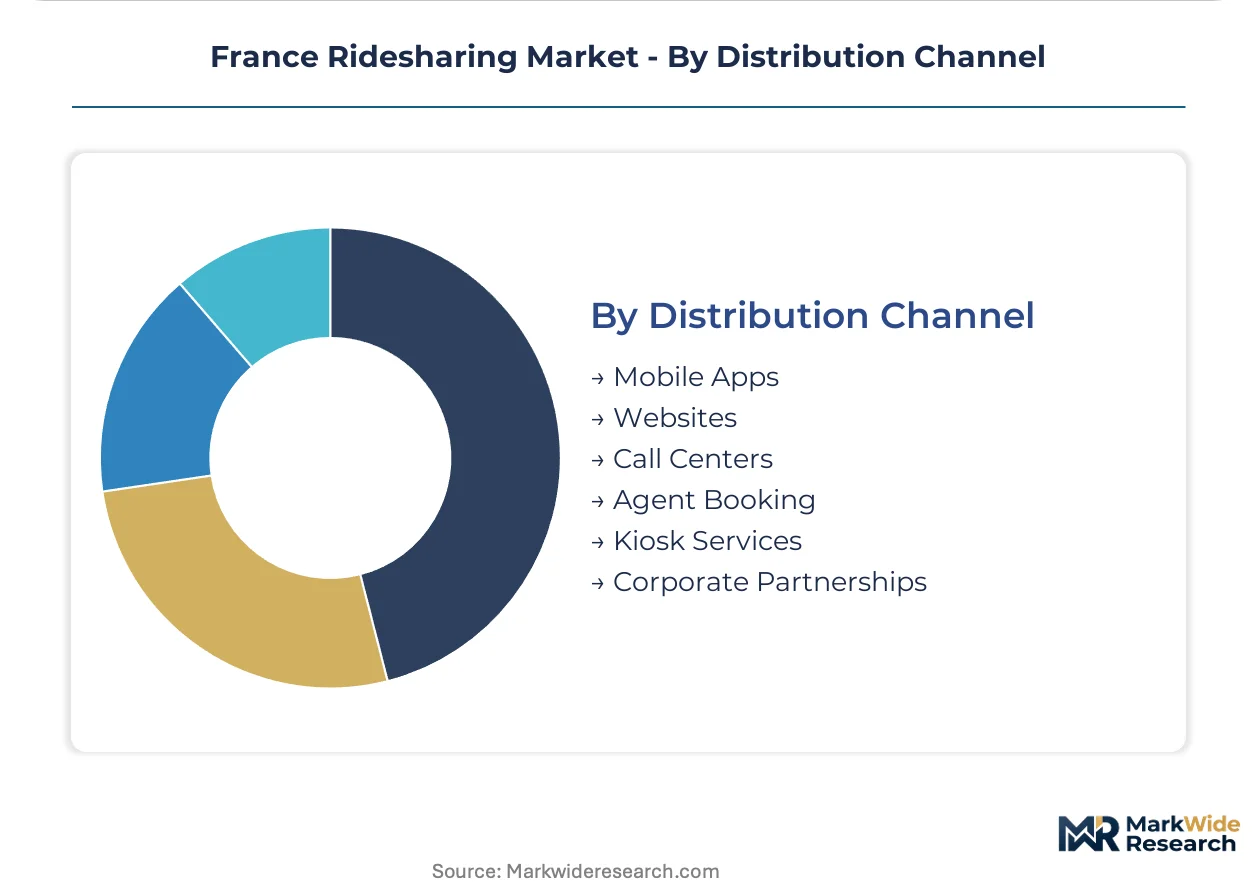
Maturity gradients separate native-digital channels with API-first architecture from legacy call center and kiosk infrastructure requiring parallel maintenance.
- Mobile Apps:Primary booking interface with real-time GPS tracking, automated fare calculation, and integrated payment processing. RATP multimodal API integration is becoming mandatory under LOM data-sharing requirements.
- Websites:Secondary access point for pre-trip planning and corporate account management.
- Call Centers:Voice-based booking for accessibility compliance and elderly user segments.
- Agent Booking:Physical intermediary channels at transit hubs and tourist offices.
- Kiosk Services:Self-service terminals at airports and rail stations for cash-inclusive transactions.
- Corporate Partnerships:Direct enterprise integration with HR systems and expense management platforms.
Mobile apps dominate installed base. Corporate partnerships is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's ridesharing demand flows primarily from the Paris-Ile-de-France corridor toward secondary metropolitan clusters in Lyon and Marseille. The national mobility orientation law redirects platform development toward SNCF rail integration rather than standalone service models.
Île-de-France
RATP multimodal infrastructure anchors rideshare demand at suburban rail termini across Paris periphery zones. ANSM driver certification databases integrate with platform dispatch systems under LOM compliance mandates. La Défense and Roissy-Charles de Gaulle corridors concentrate corporate commute contracts with enterprise partners seeking consolidated billing.
Auvergne-Rhône-Alpes
Lyon's expanding ZFE-m zones push former solo drivers toward algorithmic carpooling for daily work trips. CNIL oversight extends passenger data protection protocols to platform operations across the metropolitan area. Grenoble and Saint-Étienne satellite clusters generate last-mile connectivity demand around suburban rail stations.
Provence-Alpes-Côte d'Azur
Marseille's port logistics corridor generates concentrated business traveler demand with premium service expectations. EU Green Deal emissions benchmarks accelerate fleet electrification timelines for platform compliance. Aix-en-Provence and Toulon form secondary anchoring points for intercity carpooling corridors.
Hauts-de-France
Lille's cross-border proximity to Belgian demand pools creates unique multimodal integration requirements with SNCF and Eurostar networks. GDPR-aligned French implementation shapes platform data sharing protocols with public transit authorities. Douai and Valenciennes industrial zones concentrate corporate commute applications among manufacturing enterprises.
Nouvelle-Aquitaine
Bordeaux dedicated micromobility lane expansion positions scooter and bike sharing segments for rapid adoption. The national mobility orientation law forces API standardization with local transit authorities. Biarritz and Bayonne tourism corridors generate episodic demand with luggage requirements and airport connectivity needs.
France Ridesharing Market Competitive Landscape
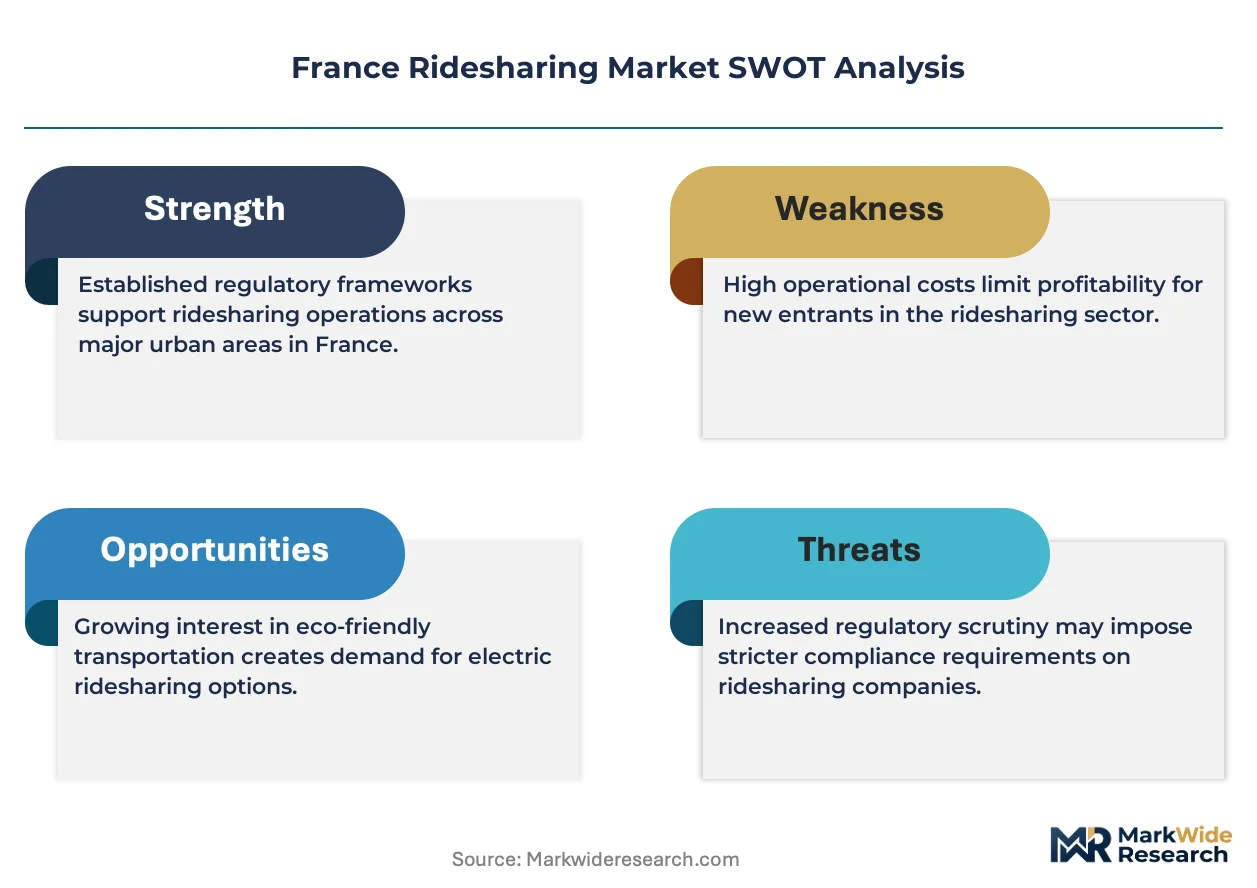
Listed leaders compete with private specialists across capital access and regulatory compliance dimensions. The vendor base organizes around three tiers: well-capitalized incumbents absorbing LOM-mandated employment reclassification costs, regional specialists anchoring price-sensitive segments, and emerging entrants facing GDPR-aligned technology barriers. Dominant competitive moves include strategic partnerships with SNCF for multimodal integration and portfolio diversification into micromobility segments.
Among Estonia-based technology platforms, Bolt Technology OÜ exemplifies the scale-driven archetype with dense driver supply concentration. Blacklane GmbH, a German GmbH-structured operator, occupies a position within the premium-tier corporate segment. BlaBlaCar, a French private specialist, represents the long-distance carpooling heritage archetype with intercity corridor dominance. These three anchors illustrate how geographic origin and capital structure shape competitive positioning under France's tightening regulatory framework.
| Leading Market Players |
|---|
| Bolt Technology OÜ |
| Blacklane GmbH |
| Uber Technologies Inc. |
| Lyft Inc. |
| Via Transportation Inc. |
| BlaBlaCar |
| Karos Mobility |
| Comuto SA |
| Heetch |
| Others |
Supply & Pricing Matrix
ANSM driver certification databases and LOM-mandated employment reclassification gates both supply qualification and price differentiation simultaneously, compressing platform margins while creating compliance cost tiers that separate well-capitalized incumbents from emerging entrants.
Pricing Analysis
Legacy dispatch system pricing runs through established taxi booking services while API-first platforms command next-generation subscription bundles and scooter sharing sits at the innovation frontier with per-minute transactional models. Three-tier pricing structure across premium corporate commute contracts, standard consumer app bookings, and economy carpooling cost-sharing segments separates margin-rich enterprise partnerships from thin-margin individual trips. Cost compression in the consumer tier intensifies because Heetch and similar operators compete aggressively on driver commission structures. Corporate commute contracts show least price sensitivity while daily commuters exhibit highest elasticity.
Supply Chain Analysis
France and Estonia anchor algorithmic platform development while Germany supplies premium fleet management systems and China dominates electric scooter manufacturing. Vehicle procurement draws from domestic Renault-Nissan partnerships for electrified fleet transitions, cloud infrastructure rests on AWS and Azure European data centers, and payment processing hinges on French banking consortiums. Single-source vulnerability concentrates in GPS tracking hardware modules subject to semiconductor allocation constraints. Distribution runs through mobile app stores and direct enterprise API integration rather than physical intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France ridesharing represents a platform-economics inflection where multimodal API integration with RATP and SNCF systems displaces standalone matching engines as the primary value creation mechanism.
For Market Incumbents: Shield margin position by accelerating backward integration into captive driver training academies that streamline ANSM certification pathways. Absorb LOM-mandated employment reclassification costs through enterprise contract concentration rather than consumer price increases. Prioritize RATP API lock-in agreements that create switching costs for daily commuter segments before SNCF on-demand substitution scales.
For New Entrants and Emerging Players: Anchor in last-mile connectivity corridors around suburban SNCF termini outside saturated Paris-Ile-de-France core markets where incumbent driver supply density remains thin. Target price-sensitive student mobility segments in Grenoble and Saint-Étienne satellite clusters with semester-pass pricing models. Pursue white-label platform licensing to regional transit authorities seeking rapid digitization without proprietary development.
For Investors and Strategic Acquirers: Carve-out targets emerge from national rail operator SNCF's expanding mobility subsidiary portfolio where bus substitution services compete directly with intercity rideshare corridors. Long-term viability favors platforms with demonstrated RATP API integration and enterprise contract recurring revenue exceeding volatile consumer trip dependency. Watch for ZFE-m zone expansion announcements as fleet electrification capex inflection indicators that separate compliant operators from stranded asset risks.
| Strategic Initiative | Industry Significance |
|---|---|
| RATP Multimodal API Integration | Creates natural demand anchoring at suburban rail termini across Paris periphery zones. |
| Enterprise Corporate Partnership Expansion | Delivers margin-rich recurring revenue distinct from volatile consumer trip demand. |
| Fleet Electrification Compliance Program | Satisfies EU Green Deal benchmarks and ZFE-m zone entry requirements in Lyon. |
| Driver Training Academy Backward Integration | Streamlines ANSM certification pathways and improves retention against Heetch commission competition. |
| Suburban Rail Termini Geographic Expansion | Captures last-mile connectivity demand intensifying around SNCF stations outside saturated core markets. |
Research Methodology
Desk research of regulatory filings with ANSM and CNIL, RATP infrastructure planning documents, and EU Green Deal implementation guidelines preceded structured interviews with platform operations executives, driver fleet managers, enterprise mobility procurement officers, and RATP transit integration specialists. Primary fieldwork combined with secondary validation against SNCF service expansion announcements, LOM compliance requirement updates, and metropolitan parking restriction policy databases. Bottom-up trip volume modeling triangulated against top-down platform revenue estimates across the analysis window.
Variance decomposition separates volume growth from pricing mix shifts and segment migration effects throughout the forecast period. Segmentation dimensions modeled include service type, application use case, customer archetype, and distribution channel complexity. CAGRs derive from compound growth trajectory analysis applied to validated baseline estimates. Industry-specific forecast inputs incorporate ZFE-m zone expansion schedules and SNCF on-demand substitution service rollout timelines.
Material uncertainties — regulatory reclassification enforcement intensity, GDPR-aligned CNIL penalty severity, and SNCF competitive service expansion velocity — sit outside the modeled envelope. Forecasts reflect assumptions about LOM implementation consistency and EU Green Deal electrification subsidy continuity. Recalibration cycles align with material shifts in national mobility orientation law secondary guidance and metropolitan low-emission zone boundary revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Vehicle Parking Meter Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Global Integrated Traffic System Market
Smart Transportation Solutions
Smart Vehicle Cabin Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Automated People Mover Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Micro Mobility Market
Smart Transportation Solutions
Automated Robotic Parking System Market
Smart Transportation Solutions
Parking Finder Apps Market