
 Global Parking Management Software Market | 2026-2036
Global Parking Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Parking Management Software Market Outlook
ISO 27001 certification is redrawing competitive boundaries in parking technology procurement. SKIDATA leverages its European installed base to sustain long-term operator contracts across airport and municipal verticals. Amano McGann anchors North American market presence through hardware-software integration for off-street garages. Scheidt and Bachmann competes on transit-adjacent parking ecosystems, extending platform capabilities into multimodal mobility hubs.
Parking management software encompasses systems that automate space allocation, payment collection, enforcement, and analytics for structured and curbside parking assets. Core functional parameters include real-time occupancy detection accuracy, sub-second transaction processing latency, and API interoperability with municipal transit APIs. Cloud-based deployment leads segment economics by shifting capital expenditure to operational models, while license plate recognition technology captures the fastest expansion as cities retrofit enforcement infrastructure. Mobile applications concentrate margin pools through transaction fee architectures that scale with payment volume rather than license count.
FCC equipment authorization governs wireless sensor deployments in US curb management programs, while GDPR and EUs AI Act constrain automated vehicle identification systems in European deployments. Japans METI promotes smart city standards that integrate parking data into broader urban mobility platforms. Stakeholders must monitor how fragmented national data localization requirements reshape cross-border platform architectures and vendor qualification criteria.
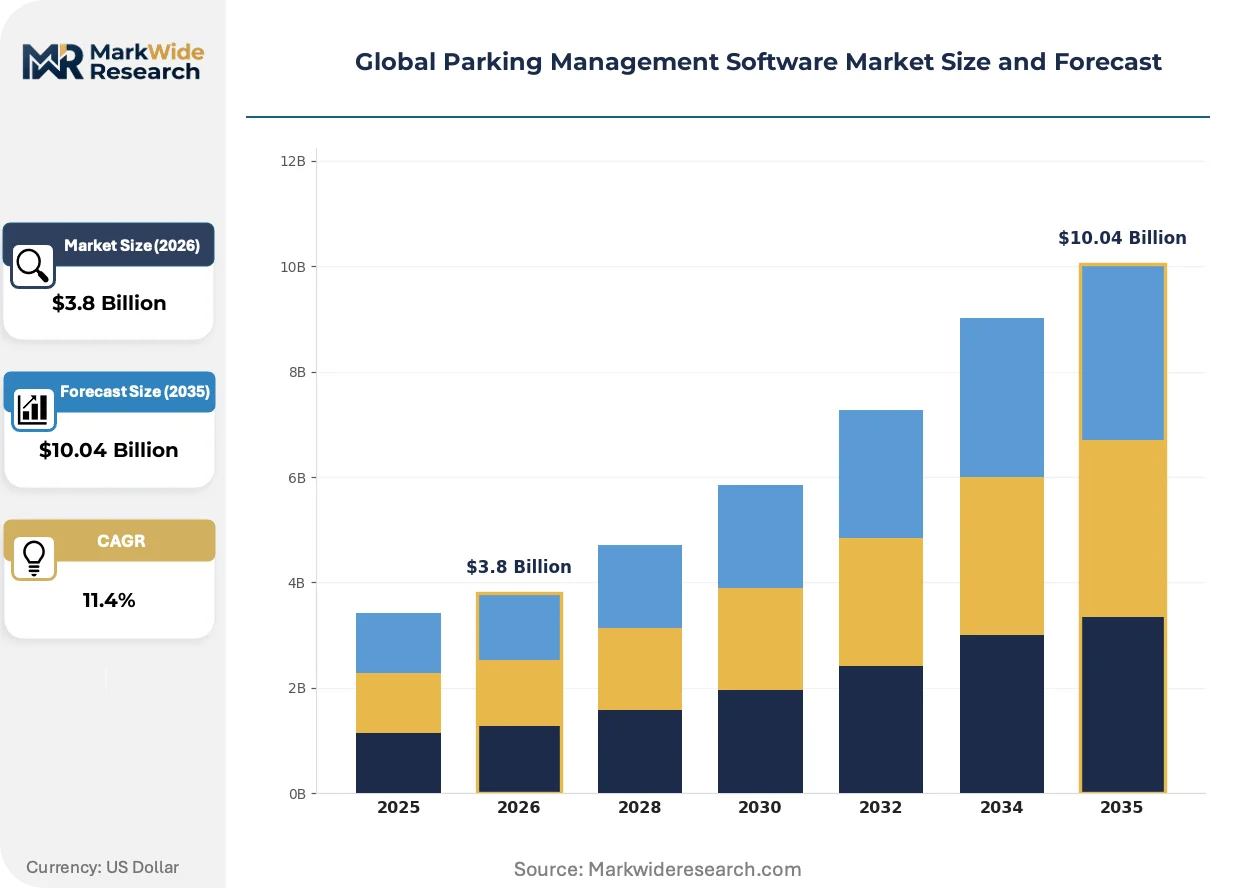
Market Dynamics
Cloud migration is compressing capital cycles across municipal and commercial parking portfolios, forcing incumbent hardware vendors to restructure pricing architectures around recurring software revenue streams.
Growth Catalysts
- License Plate Recognition Deployment:German municipalities are procuring automated enforcement systems under GDPR-aligned data frameworks, accelerating retrofit programs in Stuttgart, Munich, and Hamburg.
- FCC Equipment Authorization:Wireless sensor networks for curb management in US cities gain regulatory clearance, lowering deployment barriers for real-time occupancy monitoring.
- METI Smart City Integration:Japan's industrial ministry mandates parking data feeds into urban mobility platforms, creating standardized API demand across Tokyo, Osaka, and Fukuoka.
Market Restraints
- GDPR Compliance Cost Burden:EU AI Act constraints on automated vehicle identification impose data localization requirements that fragment platform architectures.
- Semiconductor Supply Concentration:Edge computing hardware for on-street sensors depends on concentrated Asian foundry capacity, creating procurement volatility.
- Legacy System Entrenchment:Parkeon and Amano McGann hardware installed bases in North American garages create switching friction for cloud-native alternatives.
Strategic Opportunities
- India Urban Agglomeration:Smart city missions in Bangalore, Hyderabad, and Pune lack integrated parking systems, presenting greenfield deployment potential.
- Multimodal Mobility Convergence:Transit-adjacent parking platforms are integrating with MaaS applications, creating data monetization layers beyond transaction fees.
- ISO 27001 Certification Arbitrage:Security-conscious airport operators in Dubai, Singapore, and Sydney are mandating certified vendors, disqualifying uncertified competitors.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for sub-second transaction processing competes with automotive and aerospace sectors for specialized labor.
- Cross-Border Data Architecture Complexity:Fragmented national localization rules force vendors to maintain separate instance configurations for German, French, and Japanese deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Parking Management Software Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: On-Street Solutions, Off-Street Solutions, Mobile Applications, Payment Processing Software End User: Municipalities, Parking Operators, Commercial Properties, Event Venues Deployment: Cloud-Based, On-Premise, Hybrid, SaaS Technology: IoT Integration, AI Analytics, Mobile Payment, License Plate Recognition |
| Companies Covered | SKIDATA, Amano McGann, Scheidt and Bachmann, Passport Labs, ParkMobile, Flowbird Group, FlashParking, SWARCO AG, T2 Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Parking Management Software Market Strategic Shifts
Edge AI inference is redistributing computational load from centralized clouds to on-premise parking hardware, enabling sub-100-millisecond enforcement decisions without persistent connectivity.
Computer vision hardware is miniaturizing. Sony and Ambarella chipsets now deliver LPR accuracy in palm-sized enclosures. Airport operators in Denver, Frankfurt, and Changi are retrofitting existing gantry infrastructure rather than replacing it. Component shrinkage is compressing installation timelines from weeks to days while reducing civil engineering coordination.
EU AI Act risk classification rules treat automated license plate recognition as high-risk AI. Municipal procurement departments in Rotterdam, Milan, and Vienna now require algorithmic impact assessments and human-in-the-loop override capabilities. Vendors are rearchitecting enforcement workflows to embed manual review queues before penalty issuance.
Subscription pricing for parking management platforms is displacing perpetual license models. US hospital systems and university campuses in Texas, California, and Massachusetts are consolidating vendor relationships under multi-year SaaS agreements. Finance departments prefer operational expenditure treatment for technology assets, shifting vendor compensation toward usage-based transaction fees rather than upfront deployment charges.
Global Parking Management Software Market Segmentation
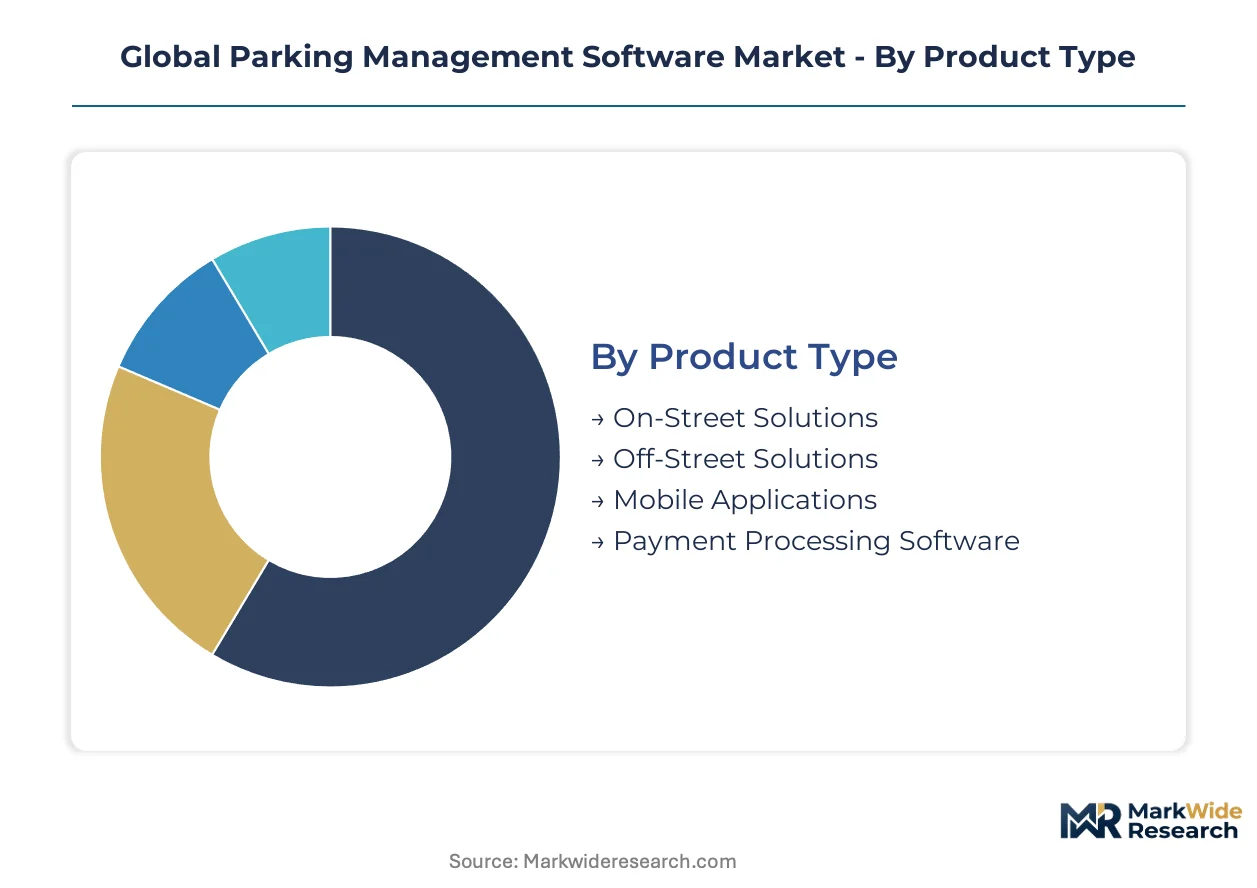
Parking management software segments diverge sharply in procurement channels and margin structures. Cloud deployment and mobile applications concentrate through SaaS channels, while on-street hardware solutions flow through municipal RFP processes with extended sales cycles.
Product Type:
Channel economics split sharply between capital-intensive hardware deployments and recurring software revenue streams.
- On-Street Solutions:Curb management platforms integrate wireless sensors, enforcement cameras, and dynamic pricing engines into unified command centers. German municipalities in Stuttgart and Hamburg are procuring these systems under GDPR-aligned data frameworks, with FCC equipment authorization governing parallel US deployments.
- Off-Street Solutions:Garage automation systems manage entry/exit control, space guidance, and revenue reconciliation across multi-level structures. Amano McGann anchors North American presence here through hardware-software integration, while SKIDATA sustains European airport contracts.
- Mobile Applications:Transaction fee architectures scale with payment volume rather than license count.
- Payment Processing Software:Sub-second latency requirements dominate procurement specifications.
By volume, Off-Street Solutions leads. By growth pace, Mobile Applications is climbing the fastest.
End User:
Customer procurement sophistication varies from municipal compliance mandates to commercial ROI thresholds.
- Municipalities:Public agencies prioritize regulatory alignment over feature depth. EU AI Act risk classification rules now require algorithmic impact assessments for automated enforcement in Rotterdam, Milan, and Vienna.
- Parking Operators:Multi-site portfolio managers demand centralized dashboards across distributed assets. Scheidt and Bachmann competes here on transit-adjacent parking ecosystems extending into multimodal mobility hubs.
- Commercial Properties:Hospital systems and university campuses in Texas, California, and Massachusetts are consolidating vendor relationships under multi-year SaaS agreements.
- Event Venues:Surge pricing capabilities and rapid deployment flexibility dominate selection criteria.
By revenue concentration, Municipalities anchor procurement volume. By margin expansion, Commercial Properties are gaining share fastest.
Deployment:
Finance department preference for operational expenditure treatment is compressing capital cycles across all customer tiers.
- Cloud-Based:Elastic infrastructure scales with transaction peaks without permanent capacity overbuild. Demand concentrates across the United States, Germany, and Japan.
- On-Premise:Air-gapped installations persist where data sovereignty requirements override cost considerations. Legacy Parkeon and Amano McGann hardware installed bases in North American garages create switching friction.
- Hybrid:Edge computing for real-time decisions with cloud analytics for pattern recognition.
- SaaS:Subscription pricing displaces perpetual license models, shifting vendor compensation toward usage-based transaction fees.
By installed base, On-Premise retains legacy dominance. By new contract velocity, Cloud-Based shows the steepest expansion trajectory.
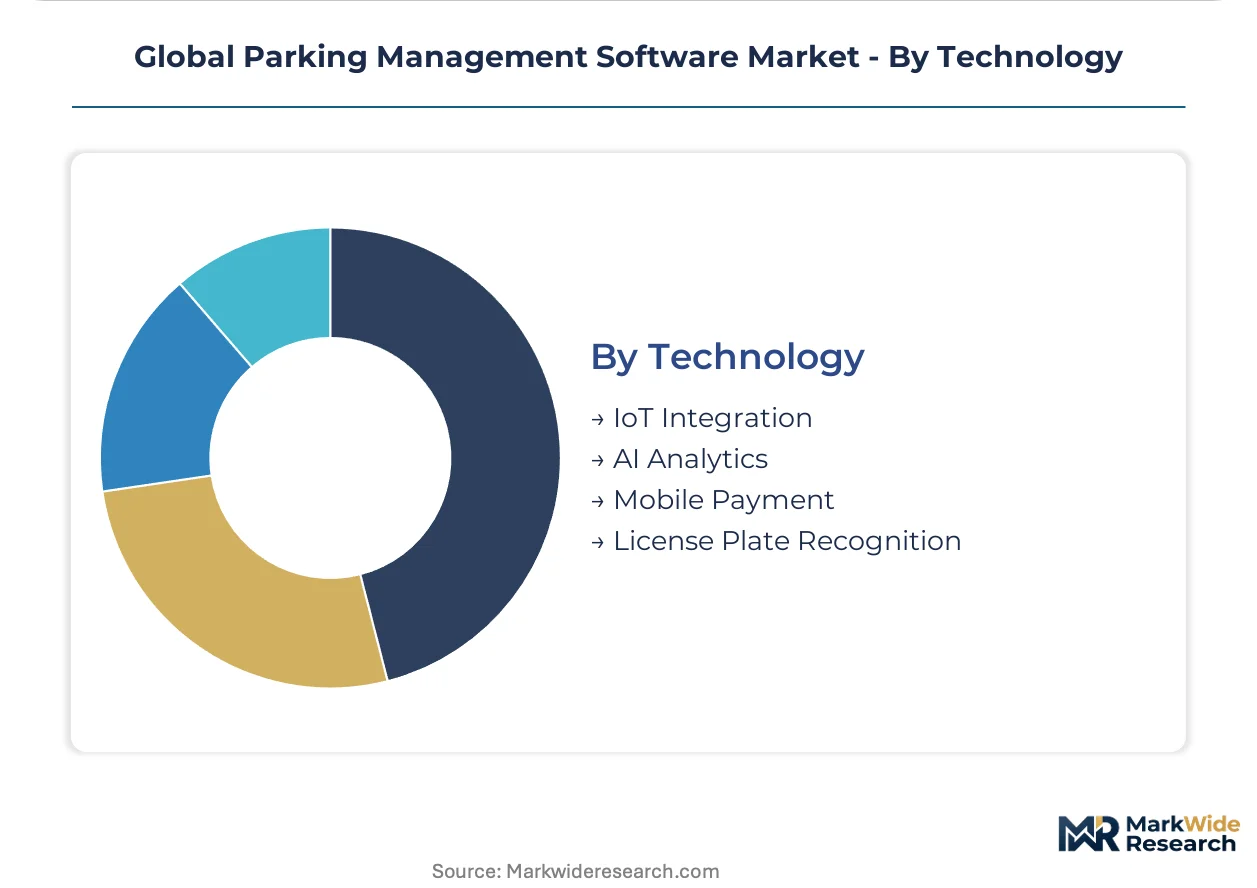
Technology:
Component miniaturization and edge AI inference are redistributing computational architectures across the technology stack.
- IoT Integration:Wireless sensor networks for real-time occupancy monitoring gain FCC equipment authorization in US curb management programs. Semiconductor supply concentration in Asian foundries creates procurement volatility.
- AI Analytics:Pattern recognition for demand forecasting and dynamic pricing optimization. EU AI Act constraints on automated vehicle identification impose data localization requirements that fragment platform architectures.
- Mobile Payment:NFC and QR-code transaction rails disintegrate hardware payment terminal dependencies.
- License Plate Recognition:Sony and Ambarella chipsets now deliver accuracy in palm-sized enclosures. Airport operators in Denver, Frankfurt, and Changi are retrofitting existing gantry infrastructure rather than replacing it.
By deployment maturity, IoT Integration leads. By investment intensity, License Plate Recognition is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal procurement departments and commercial portfolio managers drive regional demand concentration. Cloud migration preferences vary sharply by regulatory environment and legacy infrastructure density. Deployment economics favor operational expenditure treatment in finance-mature markets.
United States
FCC equipment authorization governs wireless sensor networks for curb management programs in cities including Los Angeles and Chicago. Hospital systems and university campuses in Texas, California, and Massachusetts consolidate vendor relationships under multi-year SaaS agreements. Denver International Airport exemplifies retrofit-driven LPR deployment using existing gantry infrastructure.
Germany
Municipalities in Stuttgart, Munich, and Hamburg procure automated enforcement systems under GDPR-aligned data frameworks. KBA vehicle registration databases integrate with parking enforcement platforms. SKIDATA leverages its European installed base to sustain long-term operator contracts across Frankfurt Airport and municipal verticals.
Japan
METI smart city standards mandate parking data feeds into urban mobility platforms across Tokyo, Osaka, and Fukuoka. Edge AI inference requirements for sub-100-millisecond enforcement decisions align with domestic semiconductor manufacturing capabilities. Transit-adjacent parking ecosystems concentrate in the Kanto and Kansai metropolitan corridors.
India
Smart city missions in Bangalore, Hyderabad, and Pune lack integrated parking systems, presenting greenfield deployment potential. BIS standards for IoT device interoperability remain under development. Ministry of Housing and Urban Affairs procurement guidelines favor domestic manufacturing content in municipal technology tenders.
United Arab Emirates
Dubai and Abu Dhabi airport operators mandate ISO 27001 certification, disqualifying uncertified competitors from security-conscious procurement processes. MOHAP data localization requirements influence platform architecture decisions. NEOM urban development plans incorporate multimodal mobility hub integration from initial design phases.
Global Parking Management Software Market Competitive Environment
Player mix skews toward integrated hardware-software vendors with established municipal relationships. Market structure concentrates around three tiers: legacy equipment incumbents with installed base advantages, cloud-native challengers with SaaS pricing models, and transit-specialist platforms extending into multimodal ecosystems. Dominant competitive moves include portfolio diversification beyond parking into broader mobility services, and strategic partnerships with municipal transit authorities for data integration contracts.
Within the integrated-systems tier, SKIDATA and Amano McGann exemplify contrasting geographic anchoring strategies. SKIDATA represents the European airport-municipal complex, sustaining long-term operator contracts through hardware-software integration depth. Amano McGann occupies a parallel position in North American off-street garage automation. Scheidt and Bachmann sits within the transit-adjacent specialist archetype, extending platform capabilities into multimodal mobility hubs where parking data converges with public transportation APIs.
| Leading Market Players |
|---|
| SKIDATA |
| Amano McGann |
| Scheidt and Bachmann |
| Passport Labs |
| ParkMobile |
| Flowbird Group |
| FlashParking |
| SWARCO AG |
| T2 Systems |
| Others |
Value Chain & Pricing Dynamics
ISO 27001 certification gates both vendor qualification and price differentiation simultaneously, with uncertified suppliers excluded from Dubai and Singapore airport procurement while certified vendors command premium positioning in security-conscious segments.
Pricing Analysis
Cost-plus contracts with semiconductor indexation govern hardware procurement for on-street sensor networks. Subscription SaaS tiers separate enterprise municipal deployments from mid-market commercial properties. Price differentiation rests on GDPR compliance depth and edge-AI processing latency specifications. Cost compression in hardware tiers is intensifying because foundry capacity constraints have compressed component availability. Municipal buyers exhibit highest price sensitivity due to public procurement transparency mandates, while airport operators prioritize certification over unit cost.
Supply Chain Analysis
Inbound logistics costs from Asian foundries through Los Angeles and Rotterdam ports have elevated landed costs for edge-computing hardware. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan. Sony and Ambarella chipsets for license plate recognition draw from concentrated wafer supply. Single-source vulnerability in advanced-node manufacturing creates procurement volatility. Distribution runs through municipal RFP channels with extended qualification cycles and direct OEM relationships for airport verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a defensive-moat story anchored in regulatory entrenchment, where GDPR compliance depth and ISO 27001 certification create switching costs that protect incumbent positions from cloud-native challengers.
For Market Incumbents: Consolidate municipal relationships by embedding deeper into transit authority data integration contracts, countering the threat from MaaS platform entrants. Pursue backward integration into edge-AI chip design to reduce foundry dependency. Invest in algorithmic impact assessment capabilities to meet EU AI Act procurement requirements in Rotterdam, Milan, and Vienna.
For New Entrants and Emerging Players: Differentiate on greenfield smart city deployments in Indian urban agglomerations where legacy hardware entrenchment is absent. Target Bangalore, Hyderabad, and Pune municipal corporations with cloud-native SaaS positioning. Pursue partnership-led entry through system integrators already embedded in Ministry of Housing and Urban Affairs procurement channels.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-deployment sub-segments as recurring revenue models displace hardware-heavy capital cycles. Long-term viability favors vendors with transit-authority data integration contracts and multimodal platform extensibility. Monitor ISO 27001 certification velocity as an inflection indicator for competitive disqualification rates in airport and healthcare verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Transit authority API convergence in Stuttgart and Hamburg creates data monetization layers beyond transaction fees. |
| Geographic Expansion | Greenfield deployment in Indian smart city missions bypasses legacy switching friction entrenched in North American garages. |
| Strategic Partnership | METI-mandated mobility platform integration in Tokyo and Osaka standardizes API demand for compliant vendors. |
| Acquisition of Specialist Firm | Edge-AI firmware engineering capability scarcity in automotive-competitive labor markets favors targeted capability purchases. |
| Product Launch | Palm-sized LPR enclosures using Sony chipsets compress installation timelines for Denver and Changi airport retrofits. |
Study Parameters
Operator-level perspectives from municipal parking directors, airport technology procurement officers, transit authority data integration leads, and commercial property portfolio managers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings, municipal RFP documentation, FCC equipment authorization records, and EU AI Act implementation guidance. Bottom-up deployment volume estimates triangulated against top-down market sizing from cloud infrastructure spending disclosures and foundry capacity allocation reports.
Sensitivity analysis tested forecast robustness across GDPR enforcement intensity scenarios and semiconductor supply disruption assumptions. Segmentation dimensions modeled include deployment architecture, end-user procurement sophistication, technology integration depth, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves across the projection horizon. Edge-AI inference latency specifications and API interoperability standards served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained cloud-migration preference and stable foundry capacity assumptions; material deviation would warrant model refresh. Recalibration cycles align with material shifts in EU AI Act enforcement patterns and METI smart city standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Off-Street Parking Management System Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
B2C Mobility Sharing Market
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Automated Parking Systems Market
Smart Transportation Solutions
Traffic Monitoring Market
Smart Transportation Solutions
Smart Transportation Solution Market
Smart Transportation Solutions
Smart Bus Shelters Market
Smart Transportation Solutions
Mobility Technologies Market
Smart Transportation Solutions
Europe Bike Sharing Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Smart Parking Systems Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Temperature-Controlled Last-Mile Delivery Services Market