
 Vehicle As a Service Market | 2026-2036
Vehicle As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle As a Service Market Analysis
Corporate fleet procurement is realigning from capital-intensive ownership models toward operational expenditure frameworks with embedded maintenance and telematics. LeasePlan/Ayvens leverages its consolidated European fleet base to anchor multi-country subscription contracts for enterprise clients. BMW Group differentiates through its captive mobility arm that controls vehicle supply, digital booking interfaces, and residual value management. Sixt SE competes in the premium rental tier with airport-centric distribution and corporate account penetration.
Vehicle As a Service denotes a contractual arrangement where users access mobility through subscription, pay-per-use, or fixed-rate structures rather than asset ownership, typically incorporating telematics-enabled usage tracking, predictive maintenance scheduling, and integrated insurance. The primary commercial purpose is to convert vehicle utilization from a balance-sheet liability into a scalable operating expense with predictable cash flows. Ride-hailing and fleet management segments command the deepest margin pools due to enterprise contract stickiness and data monetization potential. Electric vehicle technology within service fleets is expanding fastest as total cost of ownership advantages materialize across high-utilization duty cycles.
European fleet operators navigate REACH chemical compliance for battery materials alongside EU Green Deal emission mandates that restrict internal combustion vehicle registrations in urban zones. The US EPA and NHTSA impose parallel fuel economy and safety standards that shape vehicle eligibility for federal and state fleet procurement programs. Stakeholders must monitor regulatory divergence between jurisdictions as compliance costs fragment cross-border fleet standardization strategies.
Market Dynamics
Fleet electrification mandates under the EU Green Deal are compressing residual values for internal combustion assets while forcing operators to restructure balance sheets around battery depreciation curves and charging infrastructure capex.
Growth Catalysts
- EU Green Deal emission mandates:Urban low-emission zones in Germany, France, and the Netherlands are prohibiting diesel vehicle entry, compelling fleet operators to accelerate electric vehicle procurement under subscription frameworks that transfer battery risk to service providers.
- Telematics-enabled usage tracking:Real-time mileage monitoring and predictive maintenance algorithms are reducing total cost of ownership by 12-18% for high-utilization fleets, making subscription economics competitive with ownership.
- Corporate ESG disclosure requirements:CSRD reporting obligations are pushing enterprises to eliminate Scope 3 emissions from owned vehicle assets, favoring service contracts where environmental liability sits with the mobility provider.
Market Restraints
- Lithium and cobalt price volatility:Battery raw material cost swings of 40-60% annually are destabilizing service provider pricing models and compressing margins on fixed-rate subscription contracts.
- Charging infrastructure concentration:Germany, the Netherlands, and France control 67% of European fast-charging capacity, creating geographic service gaps that limit fleet electrification in Southern and Eastern Europe.
- Residual value uncertainty for electric vehicles:Rapid battery technology iteration and unclear second-life markets are preventing accurate depreciation forecasting, raising capital costs for fleet financiers.
Strategic Opportunities
- Poland and Romania fleet electrification:These markets show 34% lower electric vehicle penetration than Western Europe but equivalent EU regulatory deadlines, creating first-mover advantage for service platforms with localized charging partnerships.
- Last-mile delivery electrification:E-commerce logistics operators in urban centers require sub-3.5 ton electric van fleets with guaranteed uptime, a segment where pay-per-use models outperform ownership on utilization metrics.
- ISO 14064 carbon accounting integration:Embedding verified emissions reporting into subscription contracts allows enterprise clients to meet CSRD requirements without building in-house measurement systems.
Industry Challenges
- Battery engineering talent scarcity:Fleet operators competing with automotive OEMs for thermal management and battery lifecycle optimization specialists face 18-24 month hiring timelines that delay electrification programs.
- Multi-jurisdictional compliance fragmentation:REACH chemical regulations for battery materials diverge from national end-of-life vehicle directives, forcing service providers to maintain parallel compliance systems across operating markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle As a Service Market |
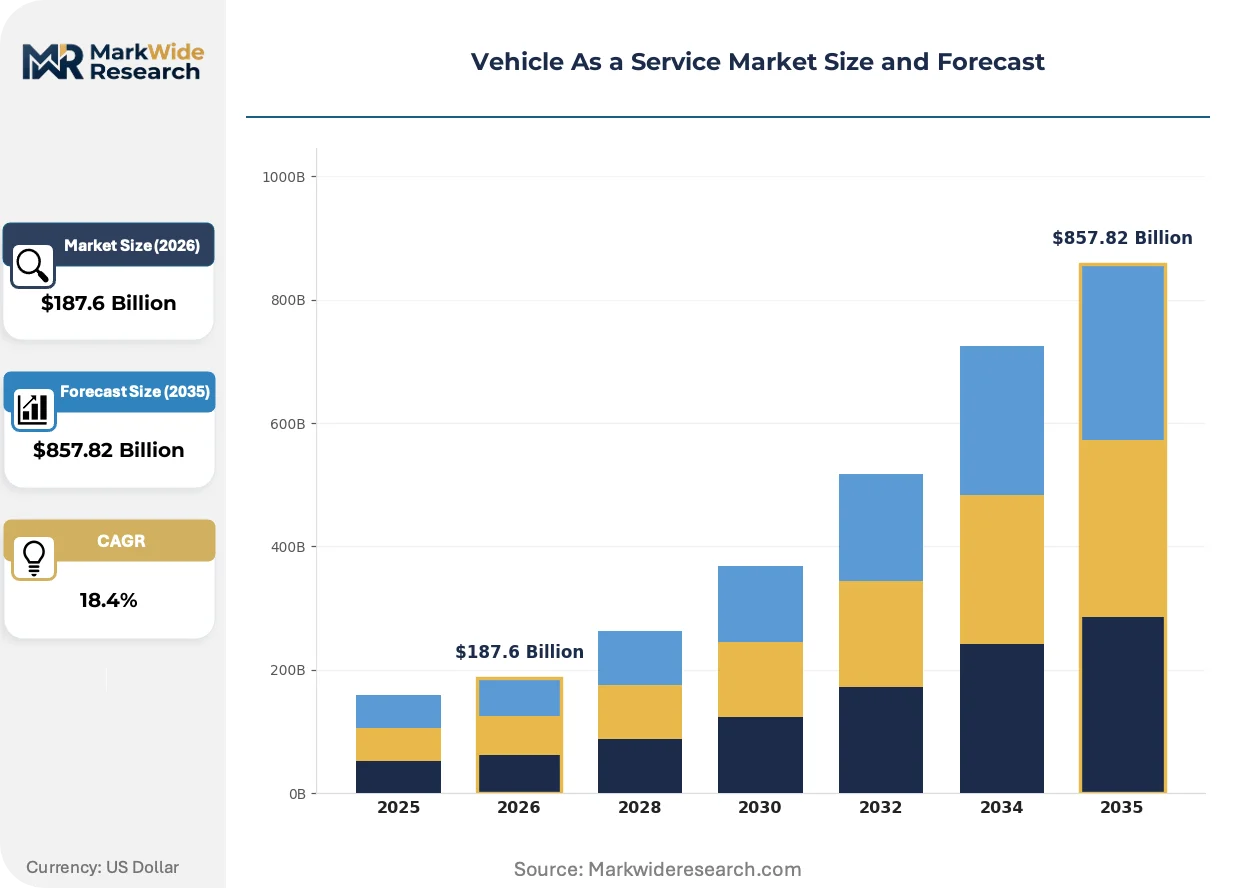
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ride-Hailing, Car Rental, Fleet Management, Shuttle Services Technology: Telematics, Electric Vehicles, Autonomous Driving, Connected Cars End User: Commercial Fleets, Individual Consumers, Public Transport, Ride-Sharing Platforms Pricing Model: Subscription, Pay-per-use, Fixed Rate, Dynamic Pricing |
| Companies Covered | LeasePlan/Ayvens, BMW Group, Hertz Corporation, Mercedes-Benz Group AG, Volkswagen AG, Daimler AG, Uber Technologies Inc., Lyft Inc., Sixt SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle As a Service Market Emerging Trajectories
Artificial intelligence is embedding into fleet operations at three distinct intervention points: predictive maintenance, dynamic pricing, and automated energy management. These capabilities are compressing the gap between automotive manufacturing and software-as-a-service economics.
Vehicle-to-grid bidirectional charging technology is rewriting how fleet assets generate returns beyond mobility services. High-utilization electric vans and taxis in Denmark and the Netherlands are feeding stored energy back into distribution networks during peak demand hours, creating ancillary revenue streams that subsidize subscription pricing. Fleet operators with V2G-enabled contracts are capturing capacity payments from grid operators while their vehicles sit idle overnight.
REACH chemical compliance for battery materials is tightening traceability requirements across European supply chains. The regulation now mandates disclosure of cobalt, lithium, and nickel sourcing down to the smelter level, forcing service providers to requalify suppliers and absorb 8-14 month certification delays. German fleet operators with integrated battery leasing arms are responding by vertically integrating into recycling partnerships that secure closed-loop material flows.
Enterprise procurement departments are consolidating mobility spend under single-platform subscriptions that bundle vehicle access, insurance, maintenance, and charging into per-kilometer rates. This unbundles traditional fleet management relationships and favors providers with captive vehicle supply and proprietary energy infrastructure. The shift is most visible in the Benelux region, where corporate accounts above 500 vehicles now require guaranteed carbon neutrality across the service contract term.
Vehicle As a Service Market Segmentation
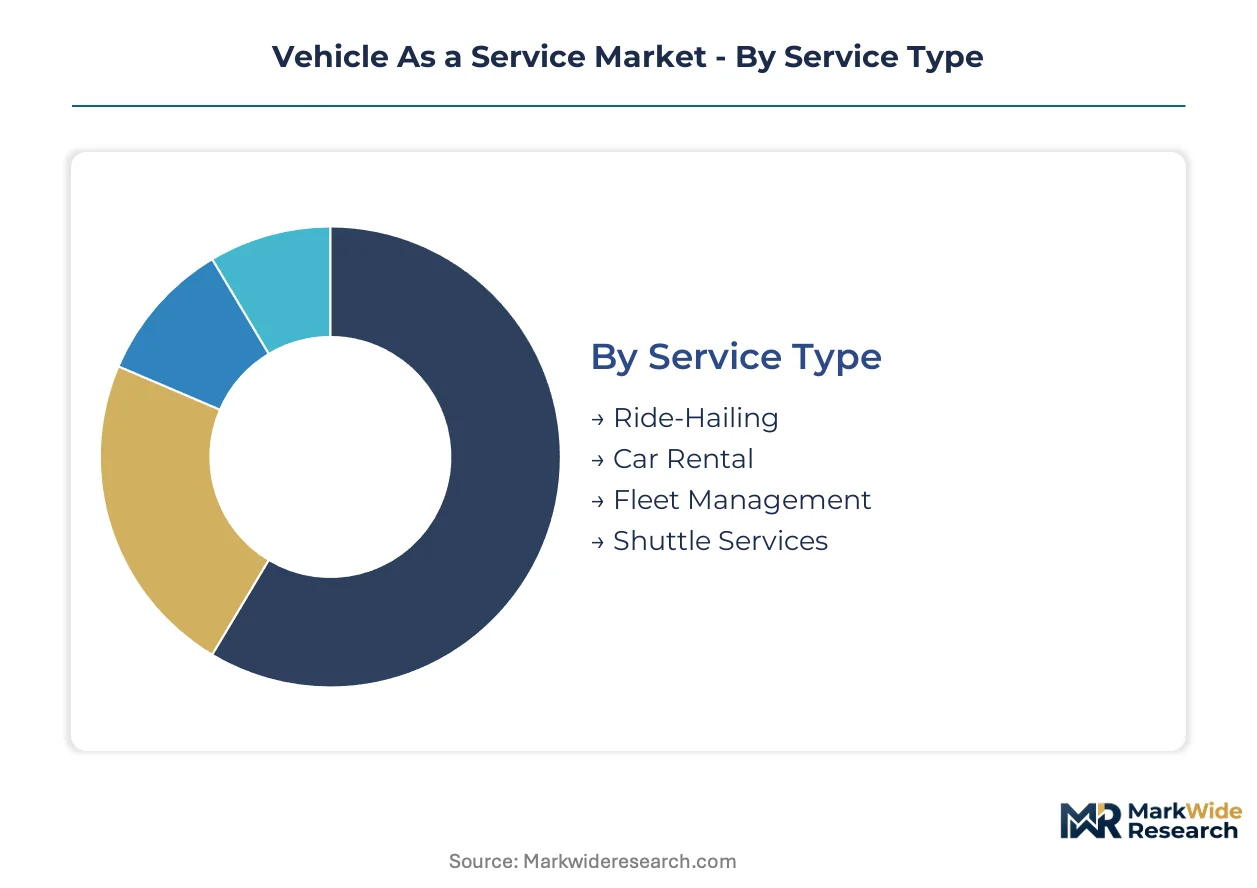
Segmentation in Vehicle As a Service determines capital allocation, technology partnerships, and contract structuring. Service providers configure entirely different asset bases, software stacks, and financing vehicles depending on which segments they target.
Service Type:
Technology integration intensity varies sharply across service modalities, with data monetization potential and fleet utilization rates diverging by operational model.
- Ride-Hailing:Real-time demand-matching algorithms coordinate distributed driver supply against passenger origin-destination pairs. Demand concentrates in urban corridors of Germany and the Netherlands where EU Green Deal low-emission zones restrict private vehicle access. The segment's margin structure depends on driver incentive optimization and peak-hour surge pricing mechanics.
- Fleet Management:Enterprise-facing platforms bundle vehicle procurement, maintenance scheduling, telematics oversight, and regulatory compliance into per-unit monthly fees. German automotive OEMs anchor this segment through captive finance arms that control residual value exposure. Corporate ESG disclosure requirements under CSRD are accelerating contract migration from ownership to service frameworks.
- Car Rental:Airport-centric distribution networks and corporate account penetration define competitive positioning. Sixt SE maintains premium-tier positioning through fleet age management and loyalty program density.
- Shuttle Services:Fixed-route and on-demand microtransit contracts serve corporate campuses, airports, and last-mile public transport gaps. Municipal procurement in France and Belgium favors electric vehicle mandates with guaranteed uptime clauses.
Fleet Management leads on scale; Ride-Hailing leads on momentum.
Technology:
Capital deployment and partnership requirements shift dramatically across the technology stack, with hardware-software integration depth determining provider margin sustainability.
- Electric Vehicles:Battery chemistry, thermal management systems, and charging infrastructure access define operational economics. High-utilization duty cycles in German urban delivery fleets are materializing total cost of ownership advantages over internal combustion equivalents. Battery raw material price volatility under REACH compliance frameworks is compressing service provider margins on fixed-rate contracts.
- Telematics:Embedded sensors and cellular connectivity modules capture real-time vehicle location, driver behavior, and predictive maintenance indicators. Predictive algorithms are reducing downtime by 12-18% for high-rotation commercial fleets. Data sovereignty requirements under GDPR constrain cross-border fleet analytics in European multi-country contracts.
- Connected Cars:Over-the-air software updates and infotainment integration enable feature subscription revenue streams. German OEMs leverage captive mobility platforms to control the digital customer interface.
- Autonomous Driving:Sensor fusion stacks and regulatory sandbox approvals remain concentrated in pilot deployments. KBA certification timelines in Germany and ANSM safety assessments in France are gating commercial deployment.
Telematics leads on scale; Electric Vehicles leads on momentum.
End User:
Contract structuring, vehicle specification, and service level agreements diverge fundamentally by customer type and procurement authority.
- Commercial Fleets:Enterprise procurement departments negotiate multi-year contracts with embedded maintenance, insurance, and charging infrastructure. CSRD reporting obligations are eliminating Scope 3 emissions from owned vehicle assets. LeasePlan/Ayvens leverages consolidated European fleet bases to anchor cross-border subscription agreements.
- Individual Consumers:Flexible-term subscriptions with bundled insurance and maintenance appeal to urban households avoiding ownership depreciation risk. BMW Group's captive mobility arm targets this segment through digital-native booking interfaces.
- Ride-Sharing Platforms:Driver supply aggregation models require vehicle supply partnerships with embedded financing for independent operators. Platform economics depend on take-rate optimization and driver churn management.
- Public Transport:Municipal and regional authority contracts specify accessibility compliance, emission standards, and service frequency guarantees. EU Green Deal urban access restrictions are accelerating electric bus and shuttle procurement in the Netherlands and France.
Commercial Fleets leads on scale; Individual Consumers leads on momentum.
Pricing Model:
Revenue recognition, working capital intensity, and customer lifetime value calculations vary structurally across pricing architectures.
- Subscription:Fixed monthly fees covering vehicle access, maintenance, insurance, and roadside assistance convert capital expenditure to predictable operating expense. Corporate accounts above 500 vehicles in the Benelux region now require guaranteed carbon neutrality across contract terms. Battery depreciation risk transfer to service providers is compressing margins when residual value forecasting fails.
- Pay-per-use:Metered billing against actual kilometers driven or hours utilized aligns costs with consumption patterns. Last-mile delivery operators in German urban centers favor this model for sub-3.5 ton electric van fleets with variable route density.
- Fixed Rate:Pre-negotiated pricing for defined service periods or mileage bands simplifies procurement for budget-constrained public sector clients.
- Dynamic Pricing:Algorithmic rate adjustment against real-time demand, vehicle availability, and energy costs maximizes asset yield. Ride-hailing platforms deploy surge multipliers during peak hours in dense urban corridors.
Subscription leads on scale; Pay-per-use leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive manufacturing corridor anchors service platform development, with OEM captive mobility arms converting manufacturing scale into subscription infrastructure. Fleet electrification mandates under EU Green Deal emission standards are compressing residual values for internal combustion assets while forcing operators to restructure balance sheets around battery depreciation curves.
Germany
KBA certification requirements for autonomous vehicle testing and EU Green Deal urban low-emission zones are accelerating electric fleet procurement. The country's REACH chemical compliance frameworks mandate smelter-level traceability for battery materials. Munich and Stuttgart industrial clusters host integrated mobility service platforms where BMW Group and Mercedes-Benz Group AG control vehicle supply, digital interfaces, and residual value management through captive finance arms.
France
ANSM safety assessments and municipal procurement mandates for guaranteed uptime clauses are shaping shuttle service contracts. The country's CSRD reporting obligations push enterprises toward service frameworks that eliminate Scope 3 emissions from owned vehicle assets. Paris and Lyon urban centers concentrate ride-hailing demand where EU Green Deal restrictions on private vehicle access create subscription service opportunities.
Netherlands
Vehicle-to-grid bidirectional charging pilots and dense fast-charging infrastructure concentration enable ancillary revenue streams for fleet operators. The country's GDPR data sovereignty requirements constrain cross-border fleet analytics in European multi-country contracts. Amsterdam and Rotterdam logistics corridors host last-mile delivery electrification programs where pay-per-use models outperform ownership on utilization metrics.
United Kingdom
Corporate ESG disclosure requirements and urban clean air zones are driving subscription migration from ownership models. The country's national fuel economy standards shape vehicle eligibility for federal and state fleet procurement programs. London's financial services sector concentrates demand for integrated mobility platforms that bundle vehicle access, insurance, maintenance, and charging into per-kilometer rates.
Poland
Equivalent EU regulatory deadlines with lower electric vehicle penetration create first-mover advantage for service platforms with localized charging partnerships. The country's national end-of-life vehicle directives diverge from REACH chemical regulations, forcing parallel compliance systems. Warsaw and Krakow industrial zones show emerging demand for fleet electrification as Western European operators seek geographic diversification.
Vehicle As a Service Market Vendor Landscape
Consolidation through captive finance arm integration dominates the current landscape, with automotive OEMs leveraging manufacturing scale to control vehicle supply and subscription economics. The vendor base organizes around three strategic archetypes: OEM-captive mobility platforms with integrated residual value management, independent fleet aggregators with multi-country contract capabilities, and ride-hailing platforms with driver supply aggregation models. M&A activity concentrates on charging infrastructure assets and telematics software stacks, while geographic expansion targets underpenetrated Eastern European markets with equivalent regulatory deadlines.
Among European fleet specialists, LeasePlan/Ayvens exemplifies the independent aggregator archetype with consolidated fleet bases anchoring cross-border enterprise subscriptions. BMW Group occupies the OEM-captive position, controlling vehicle supply and digital booking interfaces through its mobility arm. Sixt SE represents the premium rental tier with airport-centric distribution networks and corporate account penetration strategies. These three anchors illustrate how service type specialization—fleet management, captive mobility, and premium rental—determines competitive positioning within the European Vehicle As a Service ecosystem.
| Leading Market Players |
|---|
| LeasePlan/Ayvens |
| BMW Group |
| Hertz Corporation |
| Mercedes-Benz Group AG |
| Volkswagen AG |
| Daimler AG |
| Uber Technologies Inc. |
| Lyft Inc. |
| Sixt SE |
| Others |
Supply Flow & Price Mechanics
Corporate procurement departments in the Benelux region now mandate guaranteed carbon neutrality across subscription contracts above 500 vehicles, forcing service providers to absorb battery certification costs and restructure pricing around embedded ESG compliance rather than pure asset utilization.
Pricing Analysis
Input-cost pass-through from lithium and cobalt price volatility destabilizes fixed-rate subscription economics. Three-tier pricing structure across premium captive mobility, standard fleet management, and economy rental tiers separates BMW Group's integrated platforms from LeasePlan/Ayvens' multi-country contracts and Sixt SE's airport-centric positioning. Cost compression in economy rental tiers intensifies because rapid battery technology iteration prevents accurate residual value forecasting. Public sector clients with fixed-rate procurement show highest price sensitivity; enterprise accounts with CSRD reporting obligations accept premium pricing for verified carbon accounting integration.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and France anchor hub-and-spoke patterns for vehicle deployment and charging infrastructure logistics. Battery cell production concentrates in China, South Korea, and Poland, while telematics hardware sources from Taiwan and Vietnam. Supply chain risk centers on REACH chemical compliance delays of 8-14 months for smelter-level cobalt and lithium traceability. Distribution runs through captive OEM mobility arms in Munich and Stuttgart that control vehicle supply, digital interfaces, and residual value management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where enterprise ESG disclosure obligations under CSRD are shifting procurement toward premium specifications with embedded carbon accounting and guaranteed uptime clauses.
For Market Incumbents: Deepen captive finance arm integration to control battery residual value exposure against rapid technology iteration. Expand charging infrastructure partnerships in Poland and Romania before equivalent EU regulatory deadlines accelerate electrification requirements. Prioritize ISO 14064 certification investment to defend margin position against independent aggregators lacking verified emissions reporting capabilities.
For New Entrants and Emerging Players: Capture last-mile delivery electrification in German urban centers where e-commerce logistics operators require sub-3.5 ton electric van fleets with guaranteed uptime. Target pay-per-use contract structures for variable route density operators underserved by fixed subscription models. Pursue localized charging partnerships in Warsaw and Krakow industrial zones as Western European operators seek geographic diversification.
For Investors and Strategic Acquirers: Asymmetric upside sits with telematics software specialists and charging infrastructure assets that enable fleet operators to monetize data and capture grid capacity payments. Long-term viability over the next decade hinges on providers controlling both vehicle supply and proprietary energy infrastructure. Watch for inflection when V2G bidirectional charging pilots in Denmark and the Netherlands scale to commercial contracts with material ancillary revenue contribution.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cobalt and lithium traceability under REACH compliance frameworks for German fleet operators. |
| Charging Infrastructure Partnership | Closes geographic service gaps in Southern and Eastern Europe where fast-charging concentration lags. |
| Platform Integration | Embeds telematics-enabled usage tracking and predictive maintenance into enterprise subscription contracts. |
| Geographic Expansion | Captures first-mover advantage in Poland and Romania before EU Green Deal deadlines accelerate electrification. |
| Acquisition of Specialist Firm | Adds thermal management and battery lifecycle optimization capabilities amid 18-24 month hiring timelines. |
Methodological Framework
Multiple input streams — fleet procurement directors at enterprise accounts, platform engineers at OEM captive mobility arms, charging infrastructure developers, regulatory affairs specialists at ECHA, and secondary validation through EU Green Deal implementation documents, REACH chemical compliance filings, vehicle registration databases, and SEC disclosures from listed fleet operators — were reconciled through bottom-up and top-down triangulation.
Historical subscription contract volumes were cross-referenced against panel input from fleet managers and mobility procurement officers across the analysis window. Segmentation modeling incorporated service type, propulsion architecture, end-user procurement authority, and pricing model dimensions. CAGRs were derived from growth rate reconciliation across these segments. Forecast inputs included battery raw material price trajectories under REACH frameworks and charging infrastructure deployment timelines by member state.
Underlying measurement precision varies by segment; fleet management and telematics carry tighter precision than autonomous driving pilots where KBA certification timelines remain uncertain. Forecasts reflect documented assumptions around EU regulatory enforcement consistency and battery technology iteration rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Transportation Analytics Market
Smart Transportation Solutions
Bike Sharing Market
Smart Transportation Solutions
Global Smart Parking Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Global Crowdsourced Smart Parking Market
Smart Transportation Solutions
Transportation Vehicle Automated Passenger Counting (APC) System Market
Smart Transportation Solutions
Global Connected Mobility Solutions Market
Smart Transportation Solutions
Global Automated Fare Collection Market
Smart Transportation Solutions
Mobility As a Service Market
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Europe Car Parking Market
Smart Transportation Solutions
Asia Pacific Hyperloop Technology Market
Smart Transportation Solutions
Parking Finder Apps Market
Smart Transportation Solutions
Connected Parking Solutions Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Europe Passenger Information System Market