
 Global Myopia and Presbyopia Treatment Market | 2026-2036
Global Myopia and Presbyopia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Myopia and Presbyopia Treatment Market Foresight
Ophthalmologist training capacity is rotating toward refractive surgery subspecialties across major tertiary centers, tightening availability for conventional vision therapy delivery. EssilorLuxottica leverages its integrated lens-manufacturing and retail network to dominate premium spectacle distribution in Western Europe. Johnson & Johnson Vision anchors daily disposable contact lens supply through proprietary silicone hydrogel platforms. Alcon competes across surgical and pharmaceutical modalities, sustaining dual-channel revenue diversification.
Myopia and presbyopia treatment encompasses optical correction, surgical intervention, and pharmacological management of refractive errors characterized by axial elongation or loss of accommodative amplitude, typically measured in diopter power and treated through devices calibrated to 0.25-diopter precision. Spectacles retain the largest installed base across all age demographics due to low barrier to entry and minimal regulatory burden, while pharmacological therapy represents the fastest-expanding margin pool as atropine formulations and presbyopia eye drops advance through regulatory pipelines. Refractive surgery occupies a mature, high-value niche concentrated among private ophthalmologists and specialized hospitals with capital-intensive excimer and femtosecond laser platforms.
FDA oversight of presbyopia pharmacological therapies and EMA's MDR classification for surgical ophthalmic devices jointly elevate clinical evidence requirements for market access, compressing timelines for smaller developers. China's NMPA and Japan's PMDA maintain distinct bioequivalence standards for low-dose atropine formulations, fragmenting regional approval pathways. Stakeholders must monitor regulatory divergence between North American and Asian pharmacological approval frameworks to prioritize pipeline allocation and partnership structuring.
Market Dynamics
Axial elongation measurement protocols are shifting from cycloplegic refraction to optical biometry, compressing diagnostic timelines and forcing equipment upgrades across outpatient ophthalmology chains.
Growth Catalysts
- China's childhood myopia control mandates:National screening programs in Shanghai and Beijing primary schools drive spectacle procurement at scale, creating institutional demand channels distinct from retail.
- EMA MDR surgical device classification:Elevated clinical evidence requirements for excimer laser platforms filter out marginal competitors, consolidating viable supplier pools.
- Silicone hydrogel material science:Enhanced oxygen permeability in daily disposable contact lenses extends wearing hours, capturing presbyopic professionals seeking alternatives to reading spectacles.
Market Restraints
- Femtosecond laser capital intensity:Platform acquisition costs exceed two million dollars per installation, restricting refractive surgery capacity to metropolitan tertiary centers.
- Atropine API supply concentration:Bulk pharmaceutical chemical manufacturing clusters in Zhejiang province create single-geography vulnerability for low-dose formulation supply.
- Accommodative restoration ceiling:Pharmacological presbyopia therapies achieve limited near-vision improvement compared to optical correction, constraining premium pricing power.
Strategic Opportunities
- Rural India optometry penetration:Tier-three and Tier-four cities lack refractive error screening infrastructure, presenting white-space deployment for mobile diagnostic units.
- Tele-optometry channel emergence:Remote refraction and prescription verification platforms unlock access for presbyopic patients in suburban Japan and South Korea.
- FDA-EU presbyopia pharmacological convergence:Aligned bioequivalence standards between Washington and Brussels reduce duplicate clinical trial burdens for novel miotic formulations.
Industry Challenges
- Corneal refractive surgery fellowship scarcity:Training program slots fail to match excimer laser platform deployment rates, creating surgeon bottleneck.
- ISO 10993 biocompatibility testing backlog:Extended timelines for silicone hydrogel contact lens certification delay product launches by twelve to eighteen months.
- Legacy electronic health record integration:Optical biometry data formats lack standardization with hospital information systems, fragmenting patient record continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Myopia and Presbyopia Treatment Market |
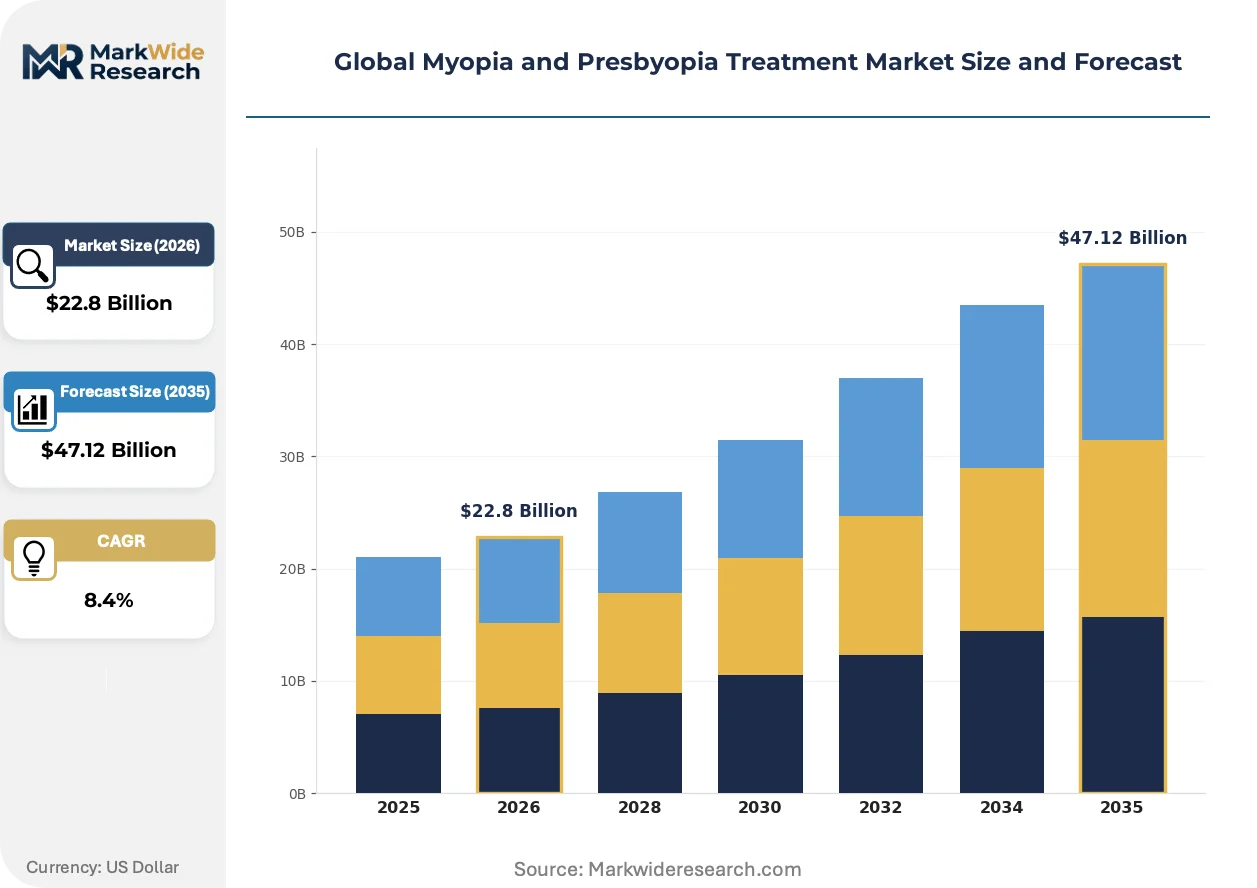
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Spectacles, Contact Lenses, Refractive Surgery, Pharmacological Therapy, Vision Therapy Application: Mild Myopia, High Presbyopia, Progressive Myopia, Early Presbyopia, Post-Surgical Correction End User: Optical Clinics, Eye Care Centers, Specialized Hospitals, Private Ophthalmologists Distribution Channel: Online Retailers, Optical Stores, Hospital Pharmacies, Eye Care Distributors |
| Companies Covered | EssilorLuxottica, NIDEK CO., LTD., Johnson & Johnson Vision, Ziemer Ophthalmic Systems AG, Topcon Corporation, Alcon, Carl Zeiss, Hoya Corporation, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Myopia and Presbyopia Treatment Market Shifts & Advancements
Wavefront-guided ablation algorithms and low-dose atropine protocols are redrawing the boundary between surgical and pharmaceutical myopia management, with diagnostic equipment vendors capturing value from both modalities.
Extended-depth-of-focus intraocular lens designs are fragmenting the premium presbyopia correction landscape. Cataract surgeons in Germany and Spain are adopting these platforms at accelerating pace, displacing traditional monofocal lenses in private-pay segments. The technology is fragmenting surgeon training curricula and compressing average selling prices for conventional multifocal alternatives.
EMA's Medical Device Regulation (MDR) implementation for ophthalmic surgical equipment elevates post-market surveillance obligations. Manufacturers must maintain clinical follow-up registries for excimer laser outcomes, increasing compliance overhead. The regulation most affects mid-sized European laser platform developers seeking CE marking renewals, driving consolidation toward established players with dedicated regulatory affairs functions.
Subscription-based contact lens replenishment models are displacing retail pharmacy purchasing among presbyopic urban professionals. Direct-to-consumer channels in Tokyo, Seoul, and Sydney bypass traditional optometry practices, unbundling the eye examination from product procurement. This behavioral shift concentrates volume with integrated lens manufacturers operating proprietary e-commerce infrastructure.
Global Myopia and Presbyopia Treatment Market Segmentation
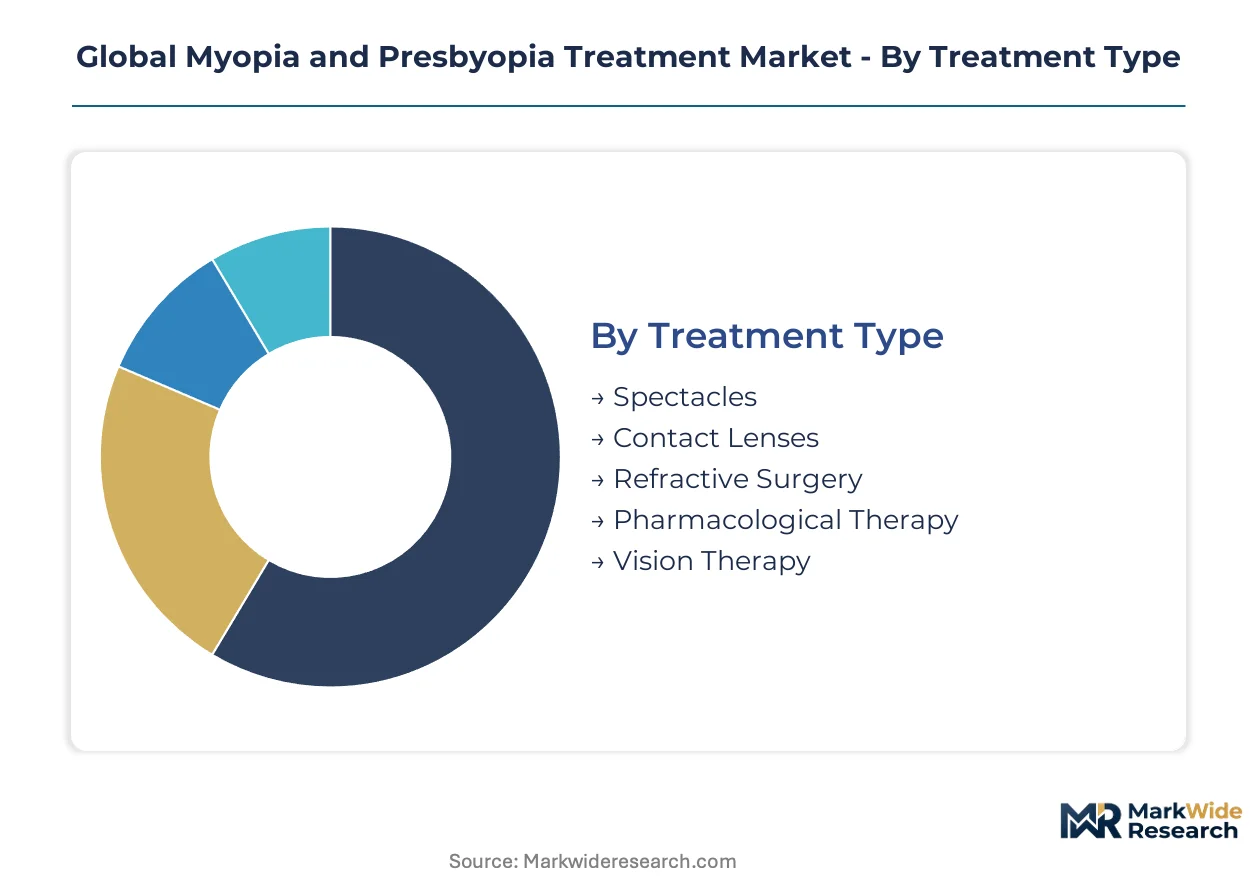
Refractive error treatment markets fragment across intervention intensity, from passive optical correction to invasive surgical modification. Substitution dynamics between spectacles, contact lenses, and pharmacological options reshape competitive boundaries within each patient demographic. Understanding where patients trade between modalities clarifies revenue vulnerability and white-space opportunity for equipment and pharmaceutical suppliers.
Treatment Type:
Pharmacological therapy exerts the strongest substitution pressure on optical correction, particularly where low-dose atropine protocols delay surgical intervention in pediatric progressive myopia.
- Spectacles:Polycarbonate and high-index resin lenses calibrated to 0.25-diopter precision dominate installed base across all age brackets. China's national childhood screening mandates in Shanghai and Beijing primary schools institutionalize bulk procurement channels distinct from retail optometry.
- Contact Lenses:Silicone hydrogel daily disposables with enhanced oxygen permeability extend wearing hours for presbyopic professionals seeking alternatives to reading spectacles. Johnson & Johnson Vision anchors supply through proprietary material platforms.
- Refractive Surgery:Excimer and femtosecond laser platforms target axial elongation correction in high myopia.
- Pharmacological Therapy:Low-dose atropine formulations and presbyopia miotic eye drops advance through FDA and EMA regulatory pipelines.
- Vision Therapy:Orthoptic exercises and accommodative training address convergence insufficiency.
Spectacles retain volume leadership; pharmacological therapy holds the steepest expansion curve.
Application:
Cost tier stratification separates premium surgical candidates from economy spectacle users, with presbyopia correction commanding higher per-patient spend than pediatric myopia management.
- Mild Myopia:Single-vision minus lenses between -0.50 and -3.00 diopters address the largest addressable population. Optical clinics across East Asia expand screening capacity to capture this segment at diagnosis.
- High Presbyopia:Near-vision deficits exceeding +2.50 diopters drive premium intraocular lens and pharmacological trial enrollment. Extended-depth-of-focus designs fragment surgeon preference in Germany and Spain.
- Progressive Myopia:Axial elongation exceeding -6.00 diopters or 26mm axial length triggers atropine protocol initiation.
- Early Presbyopia:Initial near-vision difficulty in patients aged 40-45 favors multifocal contact lens adoption.
- Post-Surgical Correction:Enhancement procedures and regression management follow initial refractive surgery.
Mild myopia captures the widest patient base; high presbyopia generates the highest revenue per intervention.
End User:
Geographic concentration of excimer laser platforms in metropolitan tertiary centers concentrates high-value surgical volume, while optical clinics fragment across suburban and rural catchments.
- Optical Clinics:Independent and chain-affiliated practices handle refraction, spectacle dispensing, and contact lens fitting. East Asian networks expand pediatric screening capacity to address surging myopia caseloads.
- Eye Care Centers:Dedicated refractive surgery facilities with femtosecond laser platforms command premium pricing.
- Specialized Hospitals:Tertiary ophthalmology departments train corneal refractive surgery fellows.
- Private Ophthalmologists:Solo practitioners and small group practices deliver personalized care.
Optical clinics serve the broadest patient flow; specialized hospitals concentrate the most capital-intensive interventions.
Distribution Channel:
Subscription-based replenishment models are displacing retail pharmacy purchasing among presbyopic urban professionals in Tokyo, Seoul, and Sydney.
- Online Retailers:Direct-to-consumer platforms bypass traditional optometry practices, unbundling eye examination from product procurement. Integrated lens manufacturers operating proprietary e-commerce infrastructure capture this volume concentration.
- Optical Stores:Brick-and-mortar locations with in-house optometrists dominate spectacle fitting and adjustment services.
- Hospital Pharmacies:Institutional procurement channels fulfill atropine prescriptions and post-surgical medication regimens.
- Eye Care Distributors:Wholesale intermediaries supply independent optical clinics and small ophthalmology practices.
Online retailers are gaining share fastest; optical stores retain the largest transaction volume for initial fittings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA regulatory frameworks for low-dose atropine bioequivalence anchor China's dominant position in pediatric myopia management. Divergent approval standards between Washington, Brussels, and Beijing fragment pharmaceutical pipeline allocation across the major markets.
China
Shanghai and Beijing primary school screening programs institutionalize bulk spectacle procurement through municipal health bureaus. NMPA maintains distinct bioequivalence standards for low-dose atropine formulations, complicating multinational pharmaceutical entry. Zhejiang province concentrates bulk pharmaceutical chemical manufacturing for API supply, creating single-geography vulnerability for formulation production.
United States
FDA oversight of presbyopia pharmacological therapies accelerates novel miotic formulation trials among urban ophthalmology practices. The agency's convergence with EMA on bioequivalence standards reduces duplicate clinical trial burdens for developers. Metropolitan tertiary centers in California and New York concentrate femtosecond laser platform deployment, restricting surgical capacity to coastal hubs.
Germany
EMA's MDR classification for surgical ophthalmic devices elevates post-market surveillance obligations for excimer laser manufacturers. Extended-depth-of-focus intraocular lens designs fragment surgeon preference in private-pay cataract segments. Bavaria and Baden-Württemberg host concentrated ophthalmic device engineering clusters serving European certification requirements.
Japan
PMDA distinct standards for low-dose atropine formulations parallel China's regulatory fragmentation, delaying multinational product harmonization. Tele-optometry platforms unlock suburban and rural presbyopia access outside Tokyo and Osaka metropolitan corridors. Kanto region optical chains expand subscription-based contact lens replenishment models among urban professionals.
India
Tier-three and tier-four cities lack refractive error screening infrastructure, presenting white-space deployment for mobile diagnostic units. CDSCO oversight of imported ophthalmic devices creates regulatory bottlenecks for laser platform installation. Maharashtra and Karnataka tertiary centers train limited corneal refractive surgery fellows, creating surgeon supply constraints relative to equipment deployment rates.
Global Myopia and Presbyopia Treatment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the treatment modality spectrum. Integrated lens-manufacturing and retail networks dominate premium spectacle distribution, while specialized surgical equipment vendors capture high-value refractive procedure revenue. Three archetypes define competitive positioning: vertically integrated optical conglomerates, dedicated ophthalmic device engineering houses, and pharmaceutical-contact lens hybrid suppliers. M&A activity concentrates manufacturing scale, while strategic partnerships bridge regulatory approval gaps across fragmented geographic markets.
Among integrated optical conglomerates, EssilorLuxottica anchors premium spectacle distribution through captive retail networks. Johnson & Johnson Vision and Alcon exemplify pharmaceutical-contact lens hybrid archetypes, spanning daily disposable silicone hydrogel supply and presbyopia pharmacological pipelines. These three entities occupy positions across multiple treatment modalities, complicating pure-play competitor targeting.
| Leading Market Players |
|---|
| EssilorLuxottica |
| NIDEK CO., LTD. |
| Johnson & Johnson Vision |
| Ziemer Ophthalmic Systems AG |
| Topcon Corporation |
| Alcon |
| Carl Zeiss |
| Hoya Corporation |
| Bausch + Lomb |
| Others |
Supply & Pricing Matrix
Silicone hydrogel material substitution for conventional hydrogel lenses is redrawing procurement geography toward East Asian polymer synthesis clusters while compressing per-unit margins through commoditized oxygen permeability specifications. This input transition simultaneously elevates FDA biocompatibility testing costs and fragments supplier pricing power between integrated manufacturers and specialized chemical converters.
Pricing Analysis
Price spreads between German and Indian optical markets exceed threefold for equivalent refractive correction platforms, reflecting divergent labor cost structures and regulatory compliance burdens. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993 certification tier and after-sales service bundling, with premium tiers commanding substantial brand premiums from EssilorLuxottica and Johnson & Johnson Vision. Cost compression in economy spectacle lenses is intensifying because Chinese municipal bulk procurement channels bypass traditional retail markups. Pediatric myopia screening programs exhibit lowest price sensitivity due to institutional mandate funding, while presbyopic urban professionals demonstrate highest elasticity toward subscription contact lens replenishment models.
Supply Chain Analysis
Strategic stockpiling of low-dose atropine active pharmaceutical ingredients dominates inventory strategy among formulation developers, driven by Zhejiang province concentration risk and NMPA bioequivalence testing backlogs. API manufacturing clusters in China and India anchor global supply, with silicone hydrogel monomer synthesis concentrated in Japan and South Korea. Bulk pharmaceutical chemical supply rests on single-geography concentration in Zhejiang, creating vulnerability to environmental regulatory enforcement or export restriction. Distribution runs through hospital pharmacies for atropine formulations and proprietary e-commerce infrastructure for daily disposable contact lens replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacological presbyopia therapy adoption sits at early-cycle expansion, with FDA-EMA regulatory convergence accelerating miotic formulation pipeline advancement beyond historical optical correction substitution timelines.
For Market Incumbents: Fortify regulatory affairs capabilities to navigate EMA MDR post-market surveillance obligations for excimer laser platforms, which filter out marginal competitors and consolidate viable supplier pools. Deepen backward integration into silicone hydrogel polymer synthesis to offset raw material cost volatility and secure ISO 10993 certification timelines. Prioritize captive e-commerce infrastructure investment to defend against direct-to-consumer channel disintermediation in Tokyo, Seoul, and Sydney metropolitan corridors.
For New Entrants and Emerging Players: Differentiate on tele-optometry platform architecture to capture presbyopic patient access in suburban Japan and South Korea, where traditional optometry penetration remains sparse. Target rural India tier-three and tier-four cities with mobile diagnostic unit deployment, leveraging absence of refractive error screening infrastructure as white-space entry point. Pursue hospital pharmacy distribution partnerships for low-dose atropine formulation access rather than retail optical channel competition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ophthalmic device engineering houses in Bavaria and Baden-Württemberg confronting EMA MDR compliance overhead and CE marking renewal consolidation pressure. Five-to-ten year viability hinges on regulatory capacity maintenance and surgeon training program scalability. Acquisition candidates with dedicated clinical follow-up registries and established NMPA-PMDA dual-track approval pathways present defensive positioning. Monitor femtosecond laser platform deployment rates versus corneal refractive surgery fellowship slot expansion as surgeon bottleneck inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Compliance Investment | Post-market surveillance registries for excimer laser outcomes filter marginal competitors and consolidate viable supplier pools. |
| Silicone Hydrogel Backward Integration | Captive polymer synthesis secures oxygen permeability specifications and compresses ISO 10993 certification timelines. |
| Tele-Optometry Platform Launch | Remote refraction unlocks presbyopic patient access in suburban Japan and South Korea beyond metropolitan corridors. |
| Mobile Diagnostic Unit Deployment | Tier-three and tier-four Indian city penetration addresses refractive error screening infrastructure absence. |
| FDA-EMA Dual-Track Regulatory Strategy | Aligned bioequivalence standards reduce duplicate clinical trial burdens for novel miotic formulations. |
Research Methodology
Initial hypotheses were tested against primary input from ophthalmology department heads, optical chain procurement directors, regulatory affairs specialists at contact lens manufacturers, and GPO contracts managers at tertiary hospital systems, and refined through secondary validation against FDA 510(k) filings, EMA MDR technical documentation, NMPA drug approval databases, and customs trade records for ophthalmic device imports. Bottom-up patient flow modeling across treatment modalities triangulated with top-down market sizing from excimer laser installation counts and spectacle lens volume data.
Variance decomposition across treatment type, application severity tier, end-user facility category, and regional regulatory cluster anchored the analytical framework over the projection horizon. CAGRs were derived from installed base expansion rates, substitution elasticity between optical and pharmacological modalities, and equipment replacement cycles. Forecast inputs incorporated NMPA atropine formulation approval timelines, femtosecond laser platform deployment rates, and subscription contact lens replenishment adoption curves.
Forecasts assume regulatory continuity in FDA, EMA, and NMPA oversight regimes; material policy shifts would require re-modeling. Specific risks include atropine API supply disruption from Zhejiang environmental enforcement, ISO 10993 biocompatibility testing backlog extension, and surgeon training program slot constraints relative to laser platform deployment. Revision becomes warranted when femtosecond laser installation growth-to-fellowship ratio crosses sustainability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Spinal and Bulbar Muscular Atrophy Treatment Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Quadriplegia Treatment Market
Specialty Medicine
Genital Warts (Condyloma Acuminatum) Market
Specialty Medicine
Cutaneous Radiation Injury Treatment Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Malignant Pleural Effusion Market
Specialty Medicine
Dry Eye Disease Market
Specialty Medicine
Triple X Syndrome Management Market
Specialty Medicine
HPV Associated Disorders Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Molybdenum Cofactor Deficiency Type-A (Mocod-A) Treatment Market
Specialty Medicine
Peptide Receptor Radionuclide Therapy (PRRT) Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market