
 Pituitary Stalk Interruption Syndrome Treatment Market | 2026-2036
Pituitary Stalk Interruption Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pituitary Stalk Interruption Syndrome Treatment Market Analytics
The gap between premium biologic hormone therapies and commodity synthetic alternatives is realigning procurement patterns across treatment centers. Novo Nordisk leverages its recombinant growth hormone portfolio to sustain dominance in pediatric endocrinology clinics across North America and Europe. Pfizer Inc. anchors its position through manufacturing scale and established distribution networks for somatropin products. Hoffmann-La Roche Limited differentiates via R&D intensity in novel delivery mechanisms for pituitary hormone replacement.
Pituitary Stalk Interruption Syndrome encompasses congenital or acquired structural defects of the pituitary stalk resulting in hypopituitarism, diagnosed through MRI pituitary imaging revealing absent or thin stalk anatomy alongside ectopic posterior pituitary bright spot. The condition requires lifelong hormone replacement with recombinant human growth hormone typically initiated at doses of 0.16–0.24 mg/kg weekly in pediatric patients to restore linear growth and metabolic homeostasis. Hormone Replacement Therapy occupies the largest value share given chronic administration requirements across decades of patient life. Subcutaneous delivery mode leads volume utilization due to patient and caregiver familiarity with injection protocols in home care settings. Growth Hormone Deficiency application segment concentrates the majority of clinical prescriptions and reimbursement pathways.
FDA oversees biologic licensing and pharmacovigilance for recombinant hormone products, while EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across European member states. Both regulators mandate rigorous immunogenicity monitoring and batch consistency protocols that elevate manufacturing compliance costs for market participants. Stakeholders must monitor evolving biosimilar interchangeability guidelines and national reimbursement negotiations that will determine competitive positioning between originator and follow-on hormone therapies.
Market Dynamics
The recombinant growth hormone biosimilar wave is compressing originator pricing power while expanding therapeutic access across pediatric endocrinology networks, fundamentally restructuring procurement negotiations between hospital systems and hormone manufacturers.
Growth Catalysts
- FDA Biosimilar Pathway Expansion:The abbreviated approval framework under the Biologics Price Competition and Innovation Act accelerates market entry for follow-on somatropin products, broadening patient access to hormone replacement therapy.
- Pediatric Endocrinology Infrastructure:Tertiary hospital investments in dedicated pituitary disorder clinics across the United States, Germany, and Japan shorten diagnostic delays and expand the addressable patient pool.
- Long-Acting Formulation Development:Novel delivery mechanisms reducing injection frequency from daily to weekly or monthly intervals improve pediatric adherence and caregiver compliance in home care settings.
Market Restraints
- Recombinant Protein Manufacturing Concentration:Active pharmaceutical ingredient production for biosimilar somatropin clusters among a limited set of contract manufacturing organizations, creating single-source vulnerability.
- EMA Immunogenicity Surveillance Mandates:Batch-level consistency testing and post-market antibody monitoring requirements elevate compliance costs disproportionately for smaller biosimilar entrants.
- Oral Peptide Delivery Substitution Threat:Transdermal and oral growth hormone secretagogue research programs threaten to displace injectable recombinant products in adolescent patient segments.
Strategic Opportunities
- Home Care Channel Expansion:Direct-to-patient distribution models bypassing hospital pharmacy intermediaries capture margin and improve refill adherence in chronic hormone replacement.
- AI-Enabled Dosing Optimization:Machine learning algorithms integrating growth velocity data with pharmacokinetic modeling personalize somatropin dosing beyond weight-based protocols.
- Japan Rare Disease Incentive Framework:PMDA's orphan drug designation and priority review vouchers accelerate regulatory timelines for novel pituitary hormone formulations.
Industry Challenges
- Pediatric Endocrinologist Workforce Scarcity:Fellowship program bottlenecks in the United States and Germany limit diagnostic capacity despite expanding clinic infrastructure.
- Cold Chain Integrity Complexity:Recombinant growth hormone stability requirements mandate continuous temperature monitoring across multi-node distribution to home injection sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pituitary Stalk Interruption Syndrome Treatment Market |
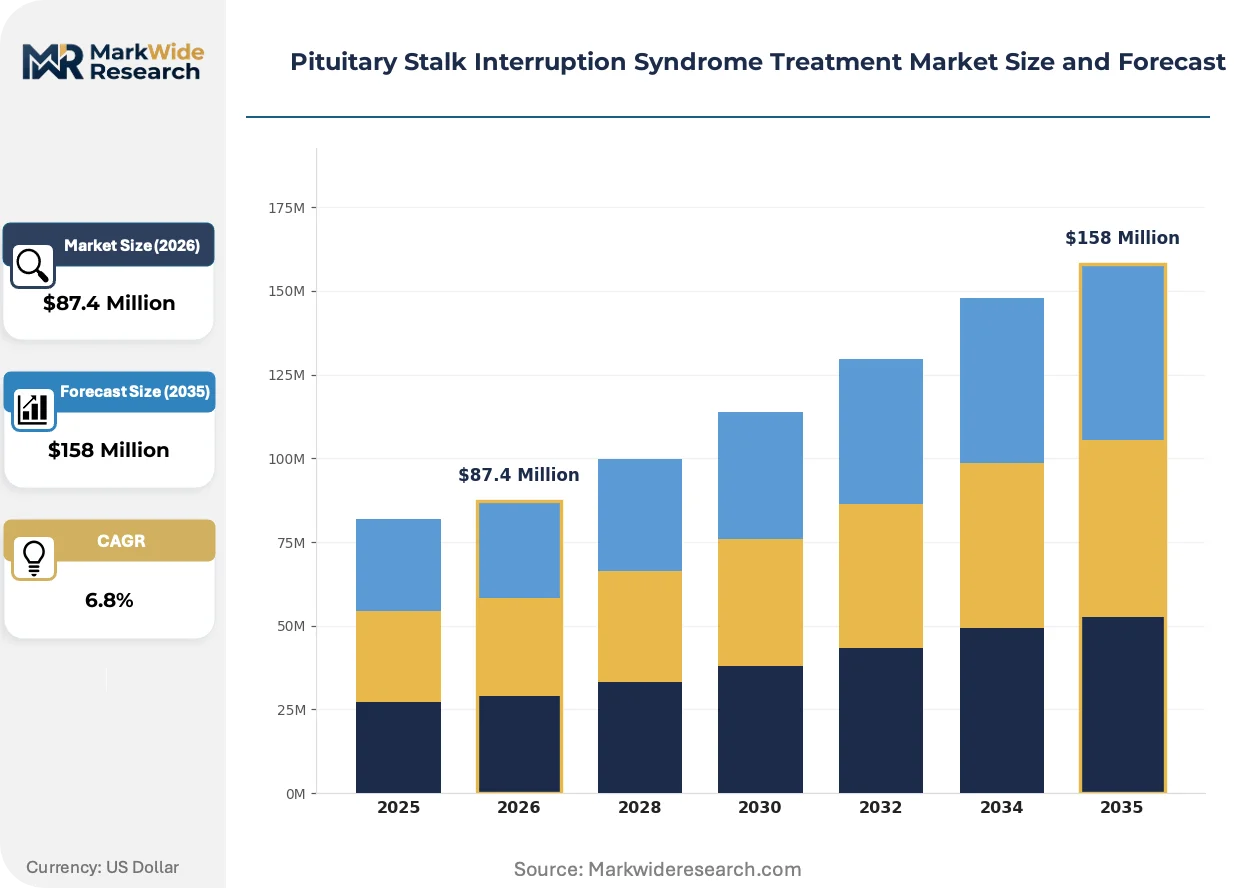
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormone Replacement Therapy, Surgical Intervention, Medication, Supportive Care End User: Pediatric Hospitals, Endocrinology Clinics, Research Institutions, Home Care Settings Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation Application: Growth Hormone Deficiency, Hypopituitarism, Obesity Management, Monitoring |
| Companies Covered | AnkeBio Co., Ltd, Hoffmann-La Roche Limited, Novo Nordisk, JenaValve Technology Inc., TTK Healthcare Ltd, Lepu Medical, Teva Pharmaceutical Industries Ltd, Pfizer Inc., Apotex Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pituitary Stalk Interruption Syndrome Treatment Market Evolving Landscape
Needle-free delivery technologies and real-world evidence generation are converging to reshape how hormone replacement therapies reach pediatric patients and demonstrate long-term value to payers.
Electronic auto-injector devices with dose logging and Bluetooth connectivity are absorbing patient adherence data directly into clinical workflows. Pediatric endocrinology departments in Boston and Paris are piloting these systems to replace conventional syringe-and-vial protocols. The resulting data streams enable outcome-based contracting discussions with public insurers that were previously impossible under paper-based monitoring.
EMA's revised guideline on clinical investigation of medicinal products in the treatment of growth hormone deficiency now mandates long-term cardiovascular safety follow-up. This regulatory tightening extends trial timelines by eighteen to twenty-four months for novel somatropin formulations. European biotechnology sponsors are responding by embedding registry-based observational studies into post-authorization commitments rather than prospective trial extensions.
Hospital procurement consortia in the United States are consolidating hormone therapy purchasing across multi-state children's hospital networks. These buying groups extract volume discounts that individual academic medical centers cannot achieve independently. The phenomenon concentrates contract awards among manufacturers with manufacturing scale sufficient to serve million-dollar annual commitments.
Pituitary Stalk Interruption Syndrome Treatment Market Segmentation
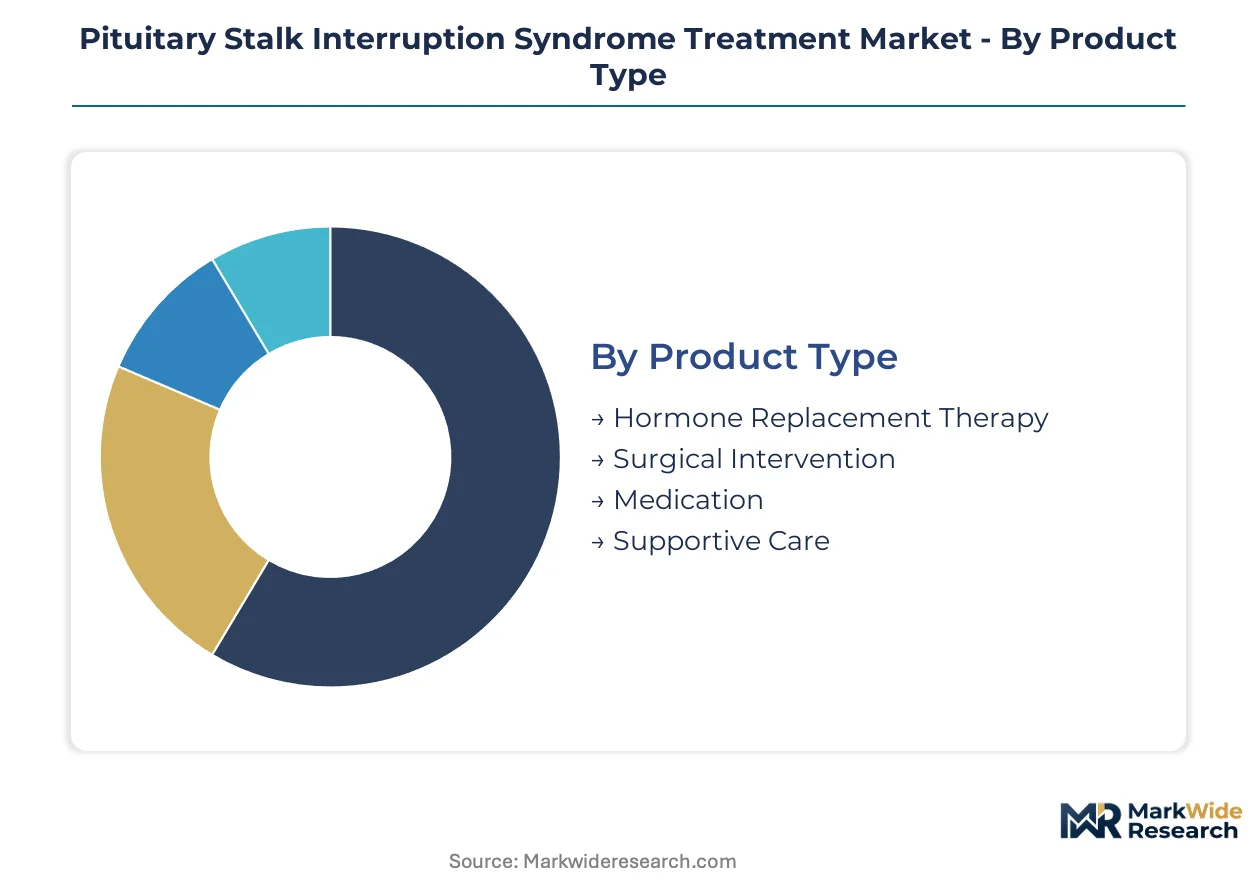
Treatment modality selection for Pituitary Stalk Interruption Syndrome hinges on anatomical defect severity, hormone deficit patterns, and patient age at diagnosis. Segmentation reveals how chronic hormone replacement dominates commercial value while surgical and supportive interventions address acute complications and long-term comorbidity management.
Product Type:
Recombinant protein engineering and synthetic hormone chemistry define the therapeutic technology landscape.
- Hormone Replacement Therapy:Recombinant human growth hormone and pituitary hormone analogs administered chronically to restore endocrine function. Demand concentrates in tertiary pediatric endocrinology departments across the United States, Germany, and Japan where MRI diagnostic protocols enable early intervention. Reimbursement frameworks in these markets support decades-long therapy continuation.
- Surgical Intervention:Transsphenoidal approaches address compressive lesions or structural anomalies requiring mechanical decompression. Deployment clusters in academic medical centers with dedicated pediatric neurosurgical units capable of managing hypothalamic-pituitary region anatomy.
- Medication:Adjunctive pharmaceutical agents managing specific endocrine sequelae including thyroid hormone, corticosteroids, and sex steroids. Prescription patterns follow endocrinologist protocol preferences.
- Supportive Care:Nutritional optimization, psychological counseling, and metabolic monitoring services. Growth is accelerating in multidisciplinary clinic models integrating endocrinology with allied health disciplines.
Mature deployment sits with Hormone Replacement Therapy. Newer deployment is concentrated in Supportive Care.
End User:
Site-of-care economics and reimbursement pathways shape institutional purchasing authority.
- Pediatric Hospitals:Tertiary academic centers with dedicated pituitary disorder clinics managing complex diagnostic workups and initial therapy initiation. Volume concentrates where MRI capacity and subspecialist density overlap.
- Endocrinology Clinics:Outpatient settings handling chronic hormone titration and growth velocity monitoring. These facilities absorb the majority of follow-up visit volume after hospital-based diagnosis.
- Research Institutions:Sites conducting natural history studies and novel formulation trials. PMDA's orphan drug framework in Japan accelerates investigator-initiated protocols at these locations.
- Home Care Settings:Patient and caregiver administration of subcutaneous injections with remote clinical oversight. Expansion is fastest where electronic auto-injector devices with adherence tracking penetrate family-managed care models.
Established patient volume rests with Pediatric Hospitals. Steepest expansion trajectory belongs to Home Care Settings.
Delivery Mode:
Pharmacokinetic requirements and patient compliance tolerances determine route selection.
- Subcutaneous:Primary administration route for recombinant growth hormone using conventional syringes or electronic auto-injector devices. Familiarity among pediatric caregivers sustains dominance despite injection burden.
- Intravenous:Reserved for acute hormone replacement in perioperative or critical care contexts requiring rapid pharmacological effect.
- Oral:Limited applicability for peptide hormones due to gastrointestinal degradation; relevant for small-molecule hormone analogs and supportive medications.
- Inhalation:Investigational delivery mechanism for select pituitary hormones with formulation stability challenges.
Dominant utilization clusters with Subcutaneous delivery. Development investment flows toward Oral peptide formulations seeking to displace injectable protocols.
Application:
Clinical indication severity and treatment duration establish prescription value hierarchies.
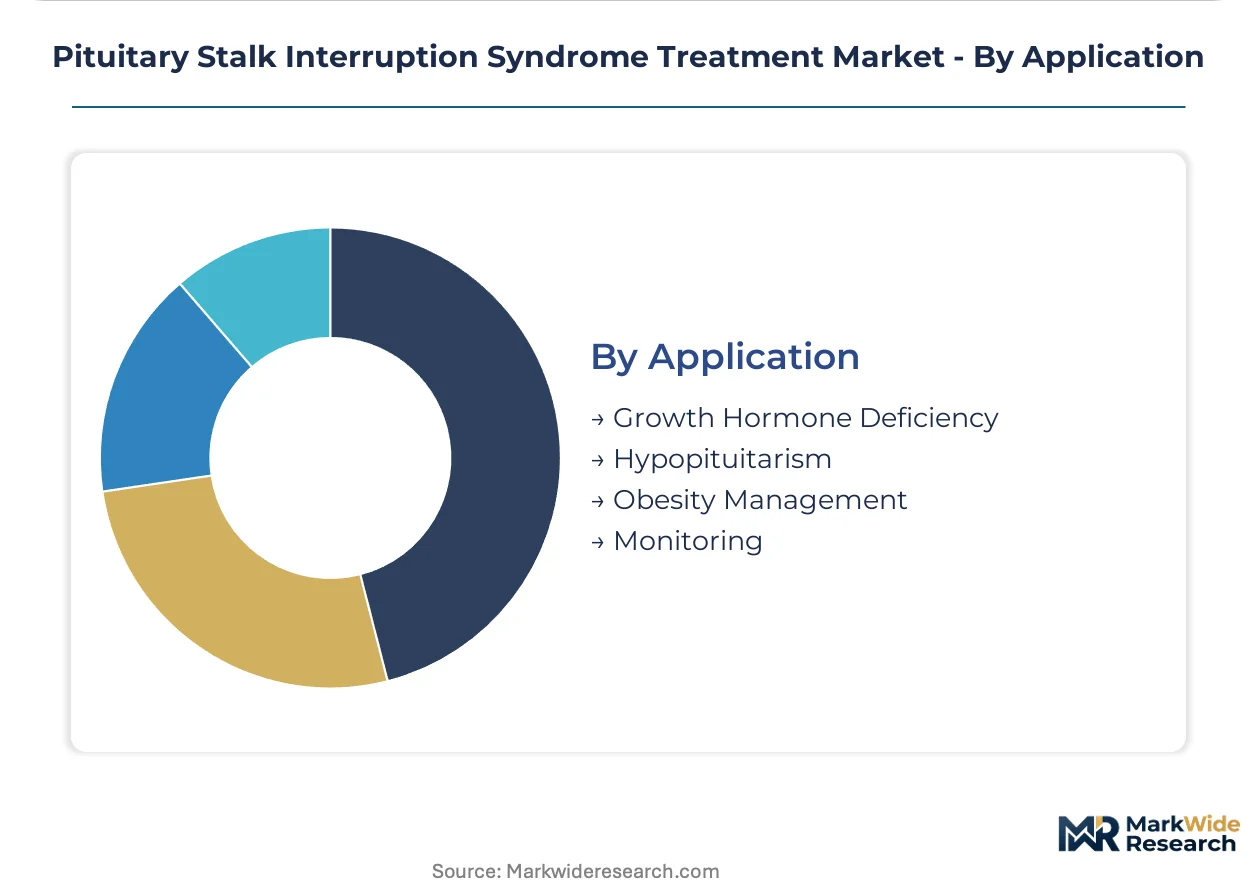
- Growth Hormone Deficiency:Core indication driving somatropin prescriptions with weight-based dosing protocols and decades-long treatment horizons. FDA and EMA pharmacovigilance mandates shape prescribing patterns.
- Hypopituitarism:Pan-hormonal deficiency requiring multi-hormone replacement strategies with complex drug interaction management.
- Obesity Management:Metabolic complications of hypothalamic dysfunction addressed through integrated endocrine and nutritional interventions.
- Monitoring:Surveillance protocols tracking treatment response, bone age progression, and cardiovascular risk markers.
Revenue concentration aligns with Growth Hormone Deficiency. Emerging clinical focus is shifting toward Obesity Management as metabolic syndrome recognition expands in pediatric endocrinology practice.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors specialized pediatric endocrinology infrastructure for pituitary disorder diagnosis and management. Tertiary hospital clusters in this corridor drive hormone replacement therapy protocols adopted across North American academic medical centers.
United States
Pediatric endocrinology fellowship programs at Boston Children's Hospital and Children's Hospital of Philadelphia expand diagnostic capacity for congenital hypopituitarism. FDA's Biologics Price Competition and Innovation Act accelerates somatropin biosimilar approvals, broadening therapeutic access. Hospital procurement consortia across multi-state children's networks consolidate purchasing power for recombinant growth hormone products.
Germany
Heidelberg University Hospital and Charité Berlin operate dedicated pituitary disorder clinics with integrated MRI diagnostic protocols. EMA's Committee for Medicinal Products for Human Use mandates rigorous immunogenicity surveillance for hormone replacement therapies, elevating compliance requirements. The Rhine-Main metropolitan cluster concentrates pharmaceutical distribution infrastructure serving Central European pediatric endocrinology networks.
Japan
PMDA's orphan drug designation framework accelerates regulatory timelines for novel pituitary hormone formulations targeting rare congenital defects. Tokyo Women's Medical University and Osaka University Hospital lead investigator-initiated trials for long-acting somatropin delivery mechanisms. The Kanto region's dense specialist hospital network supports early diagnosis protocols for pituitary stalk anomalies detected through newborn screening expansions.
United Kingdom
Great Ormond Street Hospital and Birmingham Children's Hospital manage complex pan-hormonal deficiency cases requiring multi-disciplinary care coordination. MHRA post-Brexit regulatory autonomy maintains alignment with EMA pharmacovigilance standards for biologic hormone products. The Oxford-Cambridge-London golden triangle concentrates pediatric endocrinology research funding and clinical trial infrastructure.
Canada
The Hospital for Sick Children in Toronto anchors national referral pathways for congenital hypopituitarism diagnosis and management. Health Canada maintains stringent cold chain integrity requirements for recombinant growth hormone distribution to remote northern communities. Provincial drug formularies negotiate biosimilar interchangeability agreements that reshape procurement patterns across pediatric hospital networks.
Pituitary Stalk Interruption Syndrome Treatment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across manufacturing scale and regulatory compliance capabilities. The market structures around three archetypes: multinational biopharmaceutical firms with established somatropin portfolios, emerging biosimilar specialists leveraging abbreviated approval pathways, and regional distributors capturing last-mile delivery to home care settings. Dominant competitive moves include strategic partnerships with contract manufacturing organizations for active pharmaceutical ingredient supply security, and geographic expansion into Japan's rare disease incentive framework through PMDA orphan drug designations.
Among Danish and Swiss biopharmaceutical incumbents, Novo Nordisk and Hoffmann-La Roche Limited occupy positions exemplifying the premium-tier archetype through decades-long pediatric endocrinology presence. Pfizer Inc. represents the scale-driven multinational model with manufacturing infrastructure serving consolidated hospital procurement consortia. These three entities anchor competitive dynamics as biosimilar entrants from Teva Pharmaceutical Industries Ltd and Apotex Inc. challenge originator pricing power through FDA and EMA abbreviated approval frameworks.
| Leading Market Players |
|---|
| AnkeBio Co., Ltd |
| Hoffmann-La Roche Limited |
| Novo Nordisk |
| JenaValve Technology Inc. |
| TTK Healthcare Ltd |
| Lepu Medical |
| Teva Pharmaceutical Industries Ltd |
| Pfizer Inc. |
| Apotex Inc |
| Others |
Value Network & Pricing Analysis
Multi-state children's hospital procurement consortia in the United States are consolidating annual hormone therapy purchasing into million-dollar commitments, forcing manufacturers to absorb volume discount pressure while maintaining cold chain integrity across extended distribution networks. This buyer concentration is compressing margins for biosimilar entrants lacking manufacturing scale to serve consolidated contracts.
Pricing Analysis
Outcome-based contracting anchored to growth velocity metrics and electronic adherence data is displacing conventional per-unit pricing in pediatric endocrinology networks. Pricing stratifies across originator biologics, FDA-designated interchangeable biosimilars, and non-interchangeable follow-on products differentiated by immunogenicity surveillance bundling. Cost compression in the biosimilar tier is intensifying as EMA batch-testing mandates elevate compliance overhead disproportionately for smaller entrants. Hospital pharmacy directors at tertiary academic centers exhibit lowest price sensitivity given formulary protocol rigidity, while regional endocrinology clinics face highest sensitivity due to thin reimbursement margins.
Supply Chain Analysis
Cold chain freight costs for recombinant growth hormone stability requirements consume disproportionate share of landed product cost, particularly for distribution to remote northern communities in Canada and rural catchment areas in Germany. Active pharmaceutical ingredient production clusters in Denmark, Switzerland, and the United States, with fill-finish operations drawing from contract manufacturing organizations in Ireland and Singapore. Single-source vulnerability in sterile injectable capacity creates structural risk for supply continuity during facility inspection delays. Distribution runs through hospital pharmacy intermediaries for initial therapy initiation, with direct-to-patient channels capturing refill volume in established home care settings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recombinant protein manufacturing concentration among limited contract manufacturing organizations creates a supply-constrained environment that props pricing for incumbents with captive capacity while threatening margin collapse for entrants dependent on third-party supply.
For Market Incumbents: Deepen backward integration into active pharmaceutical ingredient production to secure supply continuity against CMO inspection delays and single-source vulnerability. Lock in multi-year exclusive supply agreements with tertiary pediatric hospital networks before biosimilar interchangeability guidelines expand, while accelerating long-acting formulation R&D to defend against oral peptide secretagogue substitution threats. For New Entrants and Emerging Players: Direct-to-patient digital pharmacy platforms offer the most penetrable route to bypass consolidated hospital procurement consortia and capture margin in chronic refill management. Target home care settings in Japan's Kanto region and Germany's Rhine-Main cluster where PMDA orphan incentives and EMA pharmacovigilance requirements respectively create whitespace for novel delivery mechanism differentiation. For Investors and Strategic Acquirers: The window for entry favors mid-cap biosimilar specialists with demonstrated FDA interchangeability designations and established cold chain distribution infrastructure. Watch for PMDA priority review voucher awards and EMA centralized marketing authorization timelines as inflection indicators for regulatory pathway efficiency that will determine competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Formulation Development | Reduces injection frequency from daily to weekly intervals, improving pediatric adherence and caregiver compliance in home settings. |
| AI-Enabled Dosing Optimization | Machine learning algorithms integrating growth velocity data personalize somatropin dosing beyond conventional weight-based protocols. |
| Home Care Channel Expansion | Direct-to-patient distribution models bypass hospital pharmacy intermediaries and improve refill adherence tracking. |
| Orphan Drug Designation Pursuit | PMDA's priority review vouchers accelerate regulatory timelines for novel pituitary hormone formulations in Japan. |
| Electronic Auto-Injector Integration | Bluetooth-connected devices with dose logging enable outcome-based contracting discussions with public insurers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, supplemented by structured interviews with pediatric endocrinologists, hospital pharmacy directors, regulatory affairs specialists at hormone manufacturers, and payer formulary managers. Primary fieldwork combined with FDA pharmacovigilance databases, EMA centralized authorization records, ClinicalTrials.gov entries, and hospital procurement contract disclosures enabled bottom-up patient population sizing and top-down market value reconciliation.
Reconciliation of prescription volume data, pricing intelligence from national reimbursement negotiations, and manufacturing capacity disclosures generated consistent outputs across the projection horizon. Segmentation modeling incorporated treatment modality, delivery mechanism, patient age cohort, and regional regulatory cluster dimensions. CAGRs were derived from patient incidence trends, biosimilar penetration assumptions, and long-acting formulation adoption curves, with sensitivity testing around pediatric endocrinologist workforce expansion rates.
The model holds under stable immunogenicity surveillance requirements and continued biosimilar interchangeability designations; deviation in oral peptide delivery clinical trial outcomes or manufacturing facility regulatory actions would shift competitive positioning and value distribution. Stakeholders should weight assumptions against their own operating context and local reimbursement negotiation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Allergic Rhinitis Market
Specialty Medicine
Global Cancer Therapy Market
Specialty Medicine
Brain Metastasis Therapeutics Market
Specialty Medicine
Histamine Toxicity Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Mitochondrial Disorders Treatment Market
Specialty Medicine
Cholangitis Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Bacteriophages Therapy Market
Specialty Medicine
Kinase Inhibitor in Autoimmune Diseases Market
Specialty Medicine
Global Pheochromocytoma Market
Specialty Medicine
Allergic Conjunctivitis Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Diverticulitis Disease Market
Specialty Medicine
Vertebral Radiculopathy Market