
 Olanzapine API Market | 2026-2036
Olanzapine API Market Size, Share, and Industry Trends Forecast 2026-2036
Olanzapine API Market Insights
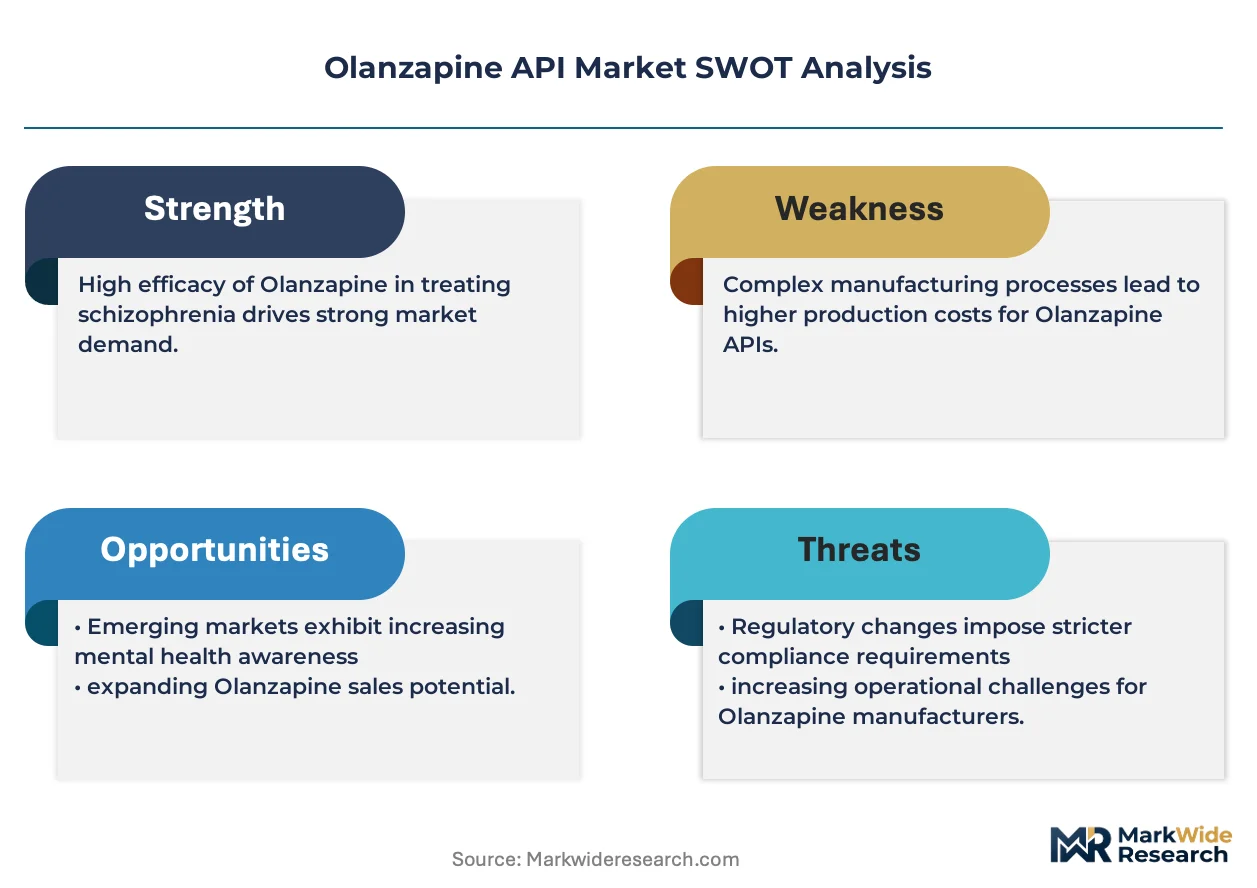
ICH Q7 compliance certification is reorganizing the competitive landscape for Olanzapine API suppliers. Teva Pharmaceutical Industries Limited leverages its integrated manufacturing footprint across multiple geographies to sustain cost advantages in bulk API production. Dr. Reddy's Laboratories anchors its position through dedicated R&D facilities focused on process chemistry optimization for complex psychotropic molecules. Sun Pharmaceutical Industries Limited differentiates via backward integration into key starting materials, reducing dependency on external raw material vendors.
Olanzapine API refers to the chemically synthesized active pharmaceutical ingredient, a thienobenzodiazepine derivative with molecular formula C17H20N4S, used as the pharmacological basis for atypical antipsychotic medications targeting schizophrenia and bipolar disorder. Manufacturing proceeds through multi-step organic synthesis involving condensation, cyclization, and purification stages to achieve pharmacopeial-grade purity exceeding 99.5%. The oral formulation segment commands the dominant share of volume demand, driven by established bioequivalence profiles and patient compliance advantages in long-term psychiatric management. Injectable formulations represent the fastest-growing category, reflecting hospital preference for rapid-acting administration in acute agitation episodes where immediate-release tablets prove insufficient.
FDA inspections of overseas API facilities, EMA's heightened emphasis on supply chain transparency under the Falsified Medicines Directive, and India's CDSCO strengthened good manufacturing practice enforcement collectively elevate compliance costs for market participants. These regulatory pressures favor manufacturers with dedicated quality assurance infrastructure and documented process validation histories over opportunistic traders. Stakeholders must monitor evolving pharmacopeial monograph revisions and inspection deficiency trends to anticipate which suppliers will retain active source status in tender-dependent procurement systems.
Market Dynamics
ICH Q7 good manufacturing practice enforcement is compressing supplier qualification timelines and redistributing procurement power toward integrated manufacturers with documented process validation histories. FDA inspection frequency at overseas API facilities has intensified, forcing generic pharmaceutical producers to requalify source networks and absorb elevated compliance audit costs.
Growth Catalysts
- CDSCO strengthened GMP enforcement:India's tightened pharmaceutical manufacturing standards are accelerating consolidation toward certified bulk producers capable of supporting international tender contracts.
- Long-acting injectable (LAI) formulations:Extended-release depot preparations for schizophrenia maintenance therapy are expanding addressable patient populations beyond oral-compliant cohorts.
- Southeast Asia government tenders:National health procurement systems in Vietnam, Indonesia, and the Philippines are scaling volume commitments for atypical antipsychotic essential medicines.
Market Restraints
- Starting material concentration:Key thienobenzodiazepine intermediates originate from a narrow base of Chinese chemical manufacturers, exposing downstream API producers to supply interruption risk.
- FDA import alert exposure:Warning letter issuance against overseas facilities triggers automatic detention without physical examination, freezing commercial shipments for 12-18 months.
- Substitution by aripiprazole:Metabolic side-effect profiles favoring lower weight gain liability are displacing olanzapine in first-line bipolar disorder protocols at certain formulary committees.
Strategic Opportunities
- Brazil ANVISA prequalification pathway:Latin America's largest pharmaceutical market offers expedited registration for APIs with existing FDA or EMA approvals, reducing time-to-market for qualified suppliers.
- Continuous flow chemistry adoption:Process intensification technologies are enabling 40-60% yield improvements in cyclization steps, compressing unit economics for high-volume tenders.
- Hospital-administered acute agitation protocols:Rapid-acting intramuscular formulations are penetrating emergency psychiatry departments as alternatives to physical restraint.
Industry Challenges
- Analytical method transfer complexity:Pharmacopeial monograph revisions between USP, EP, and IP specifications require redundant validation studies, extending release testing timelines.
- Genotoxic impurity control:ICH M7 guideline compliance for nitrosamine and sulfonate ester surveillance demands specialized LC-MS/MS capability that smaller contract manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Olanzapine API Market |
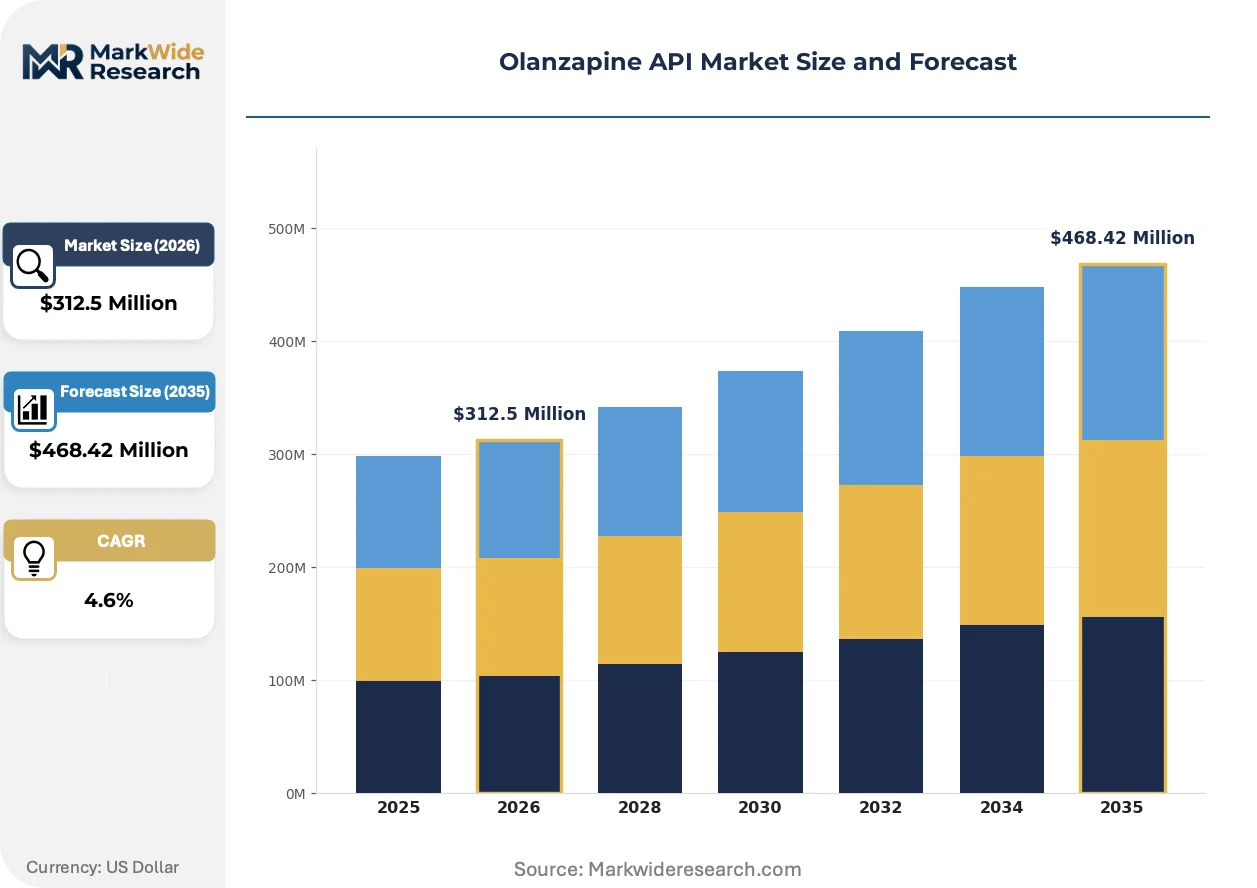
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $468.42 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Tablets, Injection Formulation: Oral, Injectable, Extended-release, Immediate-release End User: Pharmaceutical Companies, Clinics, Distributors, Research Institutions Supply Chain: Raw Material Suppliers, Manufacturers, Wholesalers, Retail Pharmacies |
| Companies Covered | Teva Pharmaceutical Industries Limited, Dr. Reddy's Laboratories, Sun Pharmaceutical Industries Limited, Aurobindo Pharma Limited, Solara Active Pharma Sciences, Jubilant Pharmova Limited, Cadila Pharmaceuticals, Jiangsu Hansoh Pharmaceutical Group, Inke S.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Olanzapine API Market Trends and Innovations
Process analytical technology and real-time release testing are displacing traditional batch-wise quality control, enabling leaner inventory positions at formulation sites. These shifts are compressing working capital requirements while elevating technical capability thresholds for API suppliers.
Continuous manufacturing platforms for high-potency psychotropic APIs are decomposing the economics of batch-scale production. Generic manufacturers in India are piloting modular flow reactors for olanzapine cyclization steps, reducing solvent volumes and crystallization cycle times. This technology is compressing capital intensity requirements and enabling geographic redistribution of production capacity toward markets with lower utility costs.
EMA's Falsified Medicines Directive serialization mandates are forcing API-to-finished-dose traceability system investments. European formulation contractors now require supplier integration with their verification databases, raising IT infrastructure costs for export-oriented manufacturers. Oral solid dosage producers serving EU tender markets are consolidating procurement toward API suppliers with pre-integrated track-and-trace capabilities.
Hospital formulary committees are compressing switching cycles between antipsychotic agents based on real-world evidence submissions. Procurement officers at integrated delivery networks in the United States are unbundling API sourcing from finished dose contracting, creating direct purchasing relationships with bulk manufacturers. This disintermediation is most visible in academic medical center consortiums managing schizophrenia population health contracts.
Olanzapine API Market Segmentation
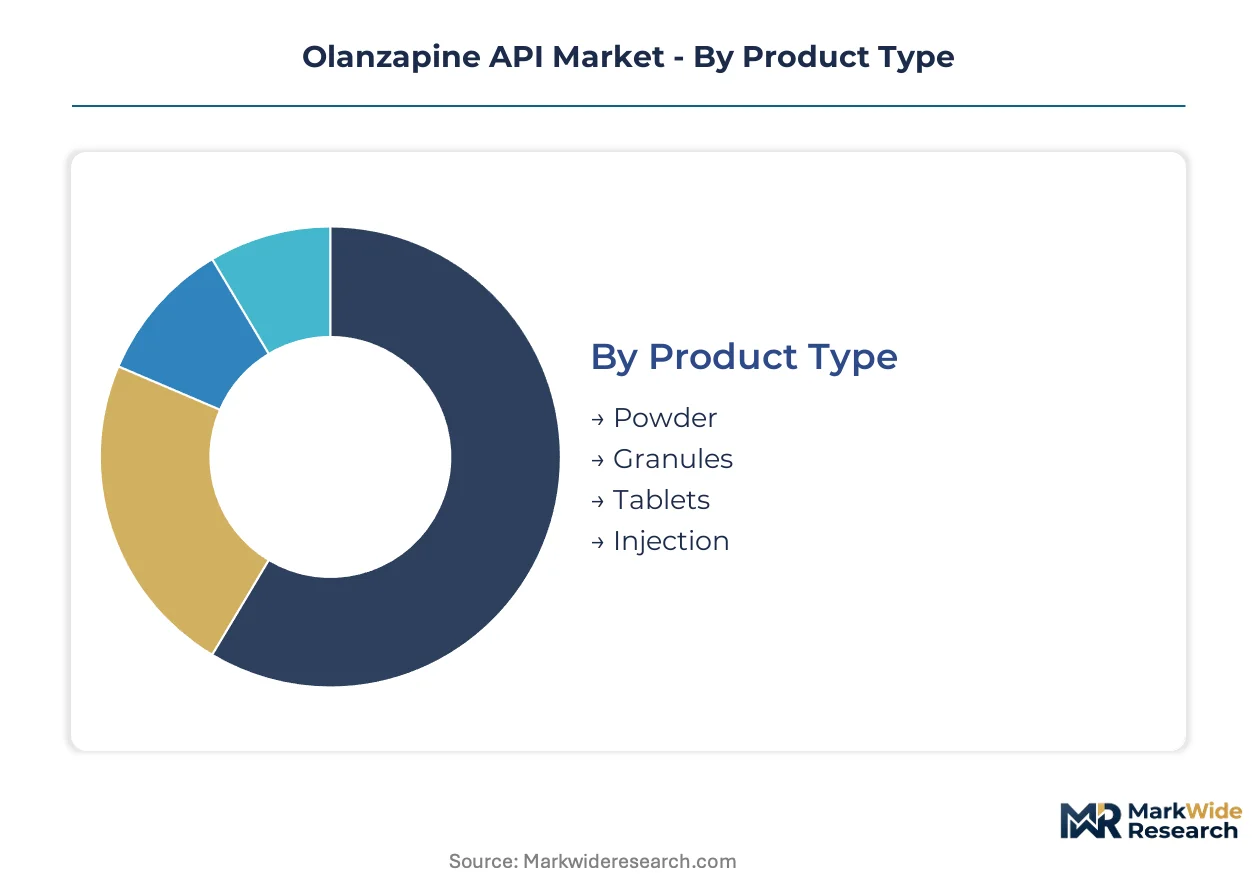
Olanzapine API procurement patterns diverge sharply across physical forms and delivery systems, with substitution risk from aripiprazole and long-acting injectable alternatives reshaping volume allocation. Pharmaceutical tender systems prioritize bioequivalence documentation and supply security over unit cost alone, compressing vendor pools differently by segment.
Product Type:
Powder and granule segments face intensifying substitution pressure from pre-formulated intermediates that shorten downstream processing timelines for generic manufacturers.
- Powder:Bulk crystalline API with particle size distribution specifications between 10-100 microns serves high-volume tablet compressors in India and China. CDSCO-certified facilities in Hyderabad and Ahmedabad dominate procurement for Southeast Asian government tenders where dissolution profile matching determines contract awards.
- Granules:Pre-processed agglomerated particles reduce dust exposure and improve flow properties for direct compression lines. European formulation contractors favor this grade for high-speed rotary tablet presses, paying premiums for validated supply chains with ICH Q7 documentation.
- Tablets:Finished dose forms containing olanzapine API at 2.5mg, 5mg, 7.5mg, and 10mg strengths target psychiatric hospital formularies and retail pharmacy chains in Brazil and Mexico.
- Injection:Lyophilized or solution formulations for intramuscular administration address acute agitation protocols in emergency departments, with ANVISA registration requirements filtering supplier eligibility for Latin American procurement.
Powder retains volume leadership; Injection holds the steepest expansion curve.
Formulation:
Cost tier stratification separates commodity oral generics from premium depot formulations, with manufacturing complexity determining margin structure and regulatory burden.
- Oral:Immediate-release tablets and orally disintegrating formulations constitute the baseline demand layer, with bioequivalence studies against Eli Lilly's reference product mandatory for FDA tentative approval. Indian generic producers in Vadodara and Visakhapatnam supply this segment for US Medicaid and Medicare formularies.
- Injectable:Short-acting intramuscular solutions for rapid sedation in acute psychiatric episodes require sterile manufacturing suites and endotoxin control beyond standard API facilities. Hospital procurement in the United States is shifting toward this modality to reduce physical restraint incidents.
- Extended-release:Long-acting injectable depots using poly(lactic-co-glycolic acid) microspheres or similar polymer matrices extend dosing intervals to 2-4 weeks. This formulation commands the highest API purity specifications and specialized aseptic processing capabilities.
- Immediate-release:Conventional tablet and capsule formats for chronic maintenance therapy face pricing pressure from centralized procurement in Indonesia, Vietnam, and Philippines national health systems.
Oral formulations dominate current volume; Injectable formats are expanding most quickly.
End User:
Customer type concentration clusters around integrated manufacturers versus fragmented intermediaries, with procurement power consolidating toward direct API purchasers.
- Pharmaceutical Companies:Vertically integrated generic producers and contract development manufacturing organizations source bulk API for internal formulation or toll manufacturing arrangements. Sun Pharmaceutical, Dr. Reddy's, and Teva anchor demand through captive consumption and third-party supply contracts.
- Clinics:Outpatient psychiatric practices and community mental health centers purchase finished dose products through group purchasing organizations, with limited direct API exposure except in compounding pharmacy exceptions.
- Distributors:Regional pharmaceutical wholesalers in São Paulo, Mumbai, and Jakarta manage inventory buffers between API manufacturers and formulation sites, absorbing working capital requirements and documentation transfer complexity.
- Research Institutions:Academic medical centers and contract research organizations procure reference standards and small-scale API batches for bioequivalence studies and pharmacokinetic investigations.
Pharmaceutical companies absorb the majority of API volume; Research institutions generate the highest per-kilogram margins.
Supply Chain:
Upstream concentration in thienobenzodiazepine intermediate production creates vulnerability nodes that downstream participants must hedge through dual-sourcing or inventory positioning.
- Raw Material Suppliers:Chinese chemical manufacturers in Zhejiang and Jiangsu provinces produce 2-methyl-4-nitroaniline and cyclization precursors, with environmental compliance inspections periodically disrupting availability.
- Manufacturers:API synthesis facilities with ICH Q7 certification and FDA establishment registration perform multi-step organic chemistry, crystallization, and micronization to pharmacopeial specifications.
- Wholesalers:Specialized pharmaceutical ingredient distributors manage customs clearance, cold chain where required, and batch documentation transfer between manufacturing geographies and formulation sites.
- Retail Pharmacies:Community and hospital pharmacies represent the terminal demand node for finished olanzapine products, with generic substitution laws in the United States and Brazil accelerating conversion to lowest-cost therapeutically equivalent options.
Manufacturers capture the value-added margin; Raw material suppliers face the greatest price volatility exposure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for pharmaceutical manufacturing is redirecting API investment toward certified bulk facilities. CDSCO enforcement actions are disqualifying marginal producers from export eligibility. Brazil's ANVISA prequalification pathway is shortening registration timelines for qualified suppliers.
United States
FDA import alert exposure concentrates procurement risk among overseas suppliers. Hospital formulary committees at academic medical centers are unbundling API sourcing from finished dose contracts. New Jersey and Pennsylvania host integrated delivery networks managing schizophrenia population health agreements.
India
Hyderabad and Ahmedabad clusters anchor CDSCO-certified API synthesis capacity for Southeast Asian tenders. CDSCO strengthened GMP enforcement is accelerating facility consolidation toward ICH Q7-compliant producers. Gujarat's Vadodara corridor supplies Medicaid and Medicare formularies through FDA-registered establishments.
China
Zhejiang and Jiangsu provinces manufacture thienobenzodiazepine intermediates with periodic environmental compliance disruptions. NMPA alignment with ICH guidelines is elevating documentation standards for export-oriented API facilities. Shanghai-headquartered producers are piloting continuous flow chemistry for cyclization step yield improvements.
Brazil
ANVISA prequalification for APIs with existing FDA or EMA approvals reduces registration timelines. São Paulo-based distributors manage inventory buffers between Asian manufacturers and domestic formulation sites. Government procurement for atypical antipsychotic essential medicines is scaling volume commitments under national health programs.
Germany
EMA's Falsified Medicines Directive serialization mandates require API-to-finished-dose traceability integration. North Rhine-Westphalia formulation contractors are consolidating procurement toward suppliers with pre-integrated verification databases. German hospital pharmacies are accelerating generic substitution to lowest-cost therapeutically equivalent options.
Olanzapine API Market Competitive Landscape
Player mix skews toward vertically integrated generic pharmaceutical manufacturers with captive API consumption. The supplier base concentrates among Indian and Chinese producers with ICH Q7 certification and documented FDA inspection histories. Two strategic archetypes dominate: integrated multinational generics with multi-continent manufacturing footprints, and specialized Indian API houses with backward integration into key starting materials. Competitive moves center on continuous manufacturing technology licensing and dual-source qualification of thienobenzodiazepine intermediate suppliers.
Among Israeli and Indian-based integrated manufacturers, Teva Pharmaceutical Industries Limited, Dr. Reddy's Laboratories, and Sun Pharmaceutical Industries Limited occupy positions exemplifying the scale-driven and backward-integrated archetypes. Teva represents the multi-continental manufacturing model with cost advantages across geographies. Dr. Reddy's exemplifies dedicated process chemistry optimization for complex psychotropic molecules. Sun Pharmaceutical anchors the backward integration strategy, reducing external raw material dependency. These three collectively illustrate how compliance infrastructure and supply chain control separate qualified tender suppliers from opportunistic traders.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries Limited |
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries Limited |
| Aurobindo Pharma Limited |
| Solara Active Pharma Sciences |
| Jubilant Pharmova Limited |
| Cadila Pharmaceuticals |
| Jiangsu Hansoh Pharmaceutical Group |
| Inke S.A |
| Others |
Pricing and Supply Chain Analysis
Aripiprazole displacement in bipolar disorder protocols is simultaneously redrawing API procurement geography and compressing pricing economics for olanzapine suppliers. This substitution dynamic forces manufacturers toward cost-competitive Indian and Chinese production clusters while squeezing margins on oral solid dosage forms destined for Southeast Asian government tenders.
Pricing Analysis
Certification level (FDA establishment registration versus CDSCO-only compliance) creates the primary spread between premium and commodity API tiers. Three-tier pricing structure across ICH Q7-certified, CDSCO-certified, and non-certified grades separates hospital formulary suppliers from tender-driven generic producers. Cost compression in the CDSCO tier is intensifying because of rising FDA inspection frequency and requalification expenses. Government procurement officers in Vietnam and Indonesia exhibit the highest price sensitivity, while European formulation contractors purchasing granule grades show the least.
Supply Chain Analysis
China and India anchor thienobenzodiazepine intermediate and finished API production respectively. Zhejiang and Jiangsu provinces supply 2-methyl-4-nitroaniline and cyclization precursors; Hyderabad and Ahmedabad clusters perform final synthesis and micronization. Single-source vulnerability concentrates in Chinese environmental compliance disruptions that periodically freeze starting material availability. Distribution runs through specialized pharmaceutical ingredient wholesalers managing customs clearance and batch documentation transfer between Asian manufacturing sites and Latin American formulation facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Long-acting injectable formulation platforms are creating ecosystem interoperability requirements that favor suppliers with integrated sterile manufacturing and polymer microsphere capabilities.
For Market Incumbents: Secure dual-source qualification for thienobenzodiazepine intermediates to hedge against Chinese environmental enforcement disruptions. Lock in continuous flow chemistry licensing for cyclization step yield improvements. FDA import alert exposure represents the primary threat to revenue continuity; backward integration into key starting materials provides the strongest defensive lever. For New Entrants and Emerging Players: ANVISA prequalification fast-tracks offer the most penetrable pathway into Latin American government tenders. Target Brazilian distributors serving hospital pharmacy chains with existing FDA or EMA documentation. White-space exists in rapid-acting intramuscular formulation supply for emergency psychiatry departments. Go-to-market positioning should emphasize ICH M7 genotoxic impurity control capabilities that smaller contract manufacturers lack. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian API houses that consolidated during CDSCO enforcement waves but lack forward integration into finished dose. Five-to-ten year viability hinges on continuous manufacturing technology adoption and LAI formulation capability buildout. The signal to watch is hospital formulary committee unbundling of API sourcing from finished dose contracting at academic medical center consortiums.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Process intensification enables 40-60% yield improvements in cyclization steps for cost-competitive tender supply. |
| ANVISA Prequalification Pathway | Expedited Brazilian registration for FDA-approved APIs reduces time-to-market in Latin America's largest pharmaceutical market. |
| Long-Acting Injectable Formulation Development | PLGA microsphere depot technology extends dosing intervals and commands premium API purity specifications. |
| Dual-Source Intermediate Qualification | Redundancy in thienobenzodiazepine precursor supply hedges against Chinese environmental compliance disruptions. |
| EMA Serialization Integration | Pre-integrated track-and-trace capabilities meet Falsified Medicines Directive mandates for European tender eligibility. |
Research Methodology
Initial hypotheses were tested against primary input from regulatory affairs leads at Indian API manufacturers, hospital procurement managers at US academic medical centers, formulary directors at Brazilian integrated delivery networks, and chemical procurement specialists at European formulation contractors, then refined through secondary validation against FDA establishment registration databases, EMA inspection deficiency records, CDSCO GMP compliance lists, and import alert histories. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand projections derived from national essential medicines procurement data.
Variance decomposition across the projection horizon isolates volume drivers by dosage form, regulatory certification tier, and regional tender system. The analytical framework models oral versus injectable versus extended-release segments alongside patient population stratification and regional regulatory cluster differentiation. CAGRs were derived from regression analysis of historical procurement volumes against tender award patterns and substitution dynamics. Forecast inputs incorporate ICH Q7 compliance diffusion rates and continuous manufacturing technology adoption curves specific to psychotropic API synthesis.
Underlying assumptions cover sustained FDA inspection intensity at overseas facilities, CDSCO enforcement continuity, and aripiprazole substitution velocity in bipolar disorder protocols, with deviation risk concentrated in Chinese environmental policy shifts and hospital formulary committee restructuring. Recalibration cycles align with material shifts in regulatory inspection deficiency trends and pharmacopeial monograph revision schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmacology
Anti Inflammatory Therapeutics Market
Pharmacology
Alzheimer's Therapeutics Market
Pharmacology
Medication Adherence Market
Pharmacology
Anti-Obesity Therapeutics Market
Pharmacology
Alexipharmic Drugs Market
Pharmacology
Intranasal Drug and Vaccine Delivery Market
Pharmacology
Global Migraine Therapeutics Market
Pharmacology
Drug Repurposing Market
Pharmacology
Antithrombotic Drugs Market
Pharmacology
Antihyperlipidemic Drugs Market
Pharmacology
Huoxiang Zhengqi Drug Market
Pharmacology
Anti-Hypertensive Drugs Market
Pharmacology
Semaglutide API Market
Pharmacology
Hyperkalemia Drugs Market
Pharmacology
Aspirin API Market
Pharmacology
Apixaban Market