
 Global Chronic Idiopathic Constipation Market | 2026-2036
Global Chronic Idiopathic Constipation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chronic Idiopathic Constipation Market Foresight
Market Context
North American pharmaceutical manufacturing is broadening its capacity for guanylate cyclase-C agonists and chloride channel activators. Sanofi leverages its established gastroenterology franchise to sustain formulary access across integrated delivery networks. Ironwood Pharmaceuticals anchors the prescription segment through its specialized focus on linaclotide and related pipeline assets. AbbVie competes in the same therapeutic class with differentiated messaging around patient-reported outcomes.
Technical Definition and Structural Segments
Chronic idiopathic constipation denotes a functional bowel disorder characterized by infrequent defecation, hard stools, and incomplete evacuation persisting for at least three months without identifiable structural or biochemical cause, typically assessed via the Rome IV criteria and Bristol Stool Scale. The condition serves primary commercial purpose as an addressable indication for prescription pharmacotherapy when dietary fiber and over-the-counter laxatives fail. Secretagogues and prokinetic agents command the most favorable reimbursement profiles among prescription categories, while fiber supplements and stool softeners occupy the high-volume, lower-margin over-the-counter tier. Hospital pharmacies and specialty clinics concentrate the highest-value transactions, whereas online pharmacies are capturing incremental volume from recurring prescription refills.
Regulatory Frame and Outlook
The FDA, EMA, and Japan's PMDA each maintain distinct evidentiary standards for functional bowel disorder trials, with the FDA emphasizing patient-reported outcome instruments and the EMA requiring broader European site representation. These divergent pathways shape development costs and launch sequencing for new molecular entities. Stakeholders must monitor how the FDA's upcoming guidance on digital therapeutics for gastrointestinal conditions intersects with traditional drug approval frameworks.
Market Dynamics
Prescription pharmacotherapy is displacing fiber-first protocols as gastroenterologists prioritize Rome IV-validated outcomes over empirical dietary interventions, tightening formulary control around guanylate cyclase-C agonists.
Growth Catalysts
- EMA's functional bowel disorder guidance:The agency's emphasis on European site representation accelerates trial enrollment across Germany, France, and Italy, compressing development timelines for new molecular entities.
- Specialty clinic expansion:Gastrointestinal service lines at ambulatory surgery centers are capturing referrals from primary care, concentrating high-value prescription transactions.
- Direct-to-consumer diagnostics:Patient identification campaigns in the United States elevate screening rates among undiagnosed populations, expanding the addressable pool for prescription therapy.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient manufacturing for linaclotide analogs clusters in select Chinese and Indian facilities, exposing sponsors to single-source risk.
- Reimbursement compression:Medicare Part D formularies in the United States impose step-therapy requirements that delay access to secretagogues until OTC failure is documented.
- Generic laxative substitution:Polyethylene glycol and lactulose formulations retain preference in cost-sensitive health systems, constraining prescription upgrade rates.
Strategic Opportunities
- Japan's aging demographic:METI-targeted healthcare infrastructure investments create favorable reimbursement conditions for novel prokinetic agents in Tokyo and Osaka metropolitan markets.
- Digital therapeutic convergence:FDA's emerging guidance on gastrointestinal digital therapeutics opens parallel approval pathways combining biofeedback apps with pharmacotherapy.
- Online pharmacy channel:Recurring prescription refill platforms capture patient loyalty through subscription models, bypassing traditional retail pharmacy intermediaries.
Industry Challenges
- Patient-reported outcome standardization:Discordance between FDA-preferred instruments and EMA-accepted endpoints forces sponsors to run separate validation studies, inflating trial costs.
- Legacy EHR integration:Rome IV criteria implementation requires workflow reconfiguration in hospital systems still operating on ICD-10-CM diagnostic frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chronic Idiopathic Constipation Market |
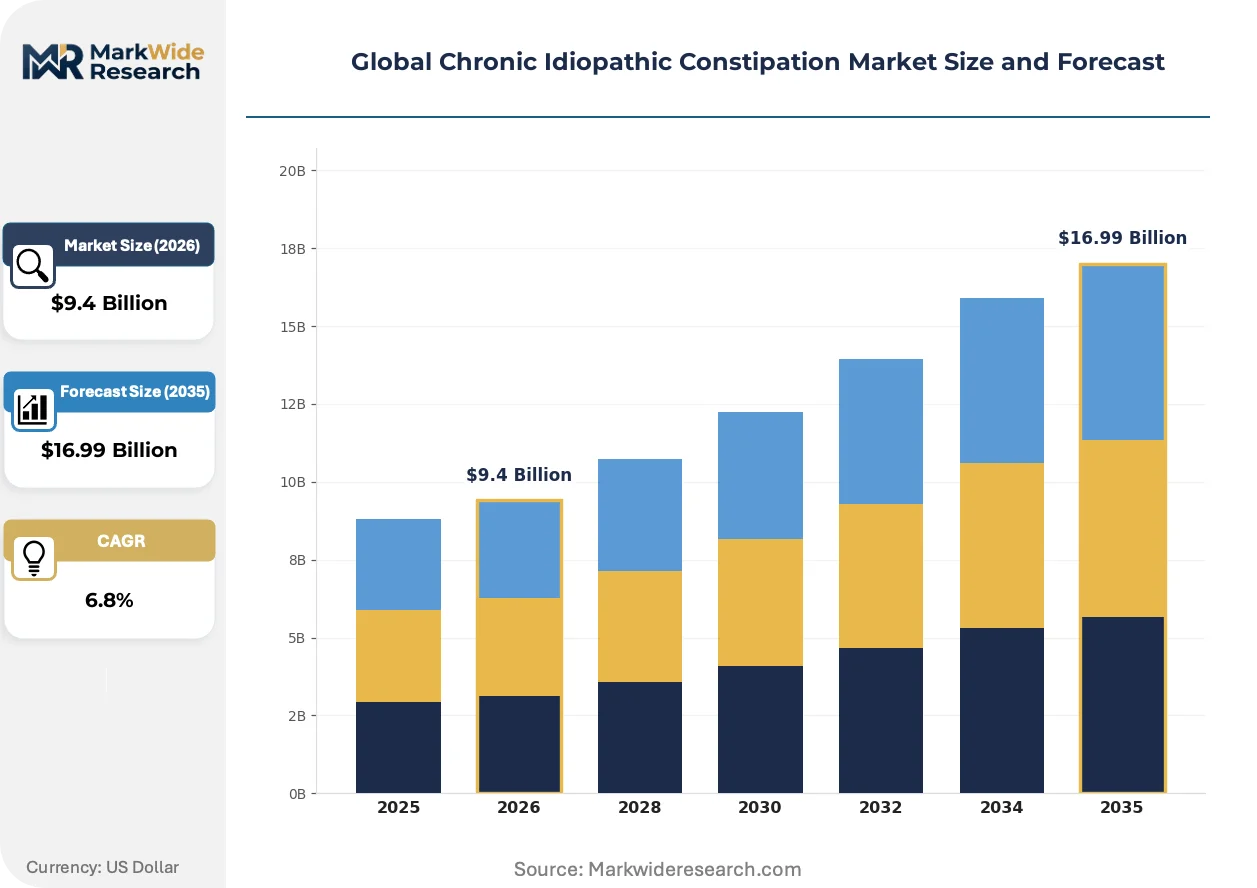
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laxatives, Prokinetic Agents, Secretagogues, Fiber Supplements, Stool Softeners Therapy Area: Gastrointestinal Disorders, Functional Bowel Disorders, Motility Disorders, Neurogenic Causes, Metabolic Causes End User: Hospitals, Ambulatory Care Centers, Specialty Clinics, Home Healthcare Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Drug Stores |
| Companies Covered | Sanofi, Astellas Pharma, Ironwood Pharmaceuticals, Cosmo Pharmaceuticals, Novartis, AbbVie, Bayer AG, Salix Pharmaceuticals, Takeda Pharmaceutical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chronic Idiopathic Constipation Market Shifts & Advancements
Biomarker-guided patient stratification is replacing empirical prescribing as sponsors invest in transit-time imaging and stool microbiome profiling to identify responders prior to therapy initiation.
Guanylate cyclase-C receptor agonists are integrating sustained-release formulations that flatten plasma concentration curves, reducing abdominal cramping incidence. Specialty clinics in the United States are adopting these modified-release versions at twice the rate of standard formulations. This technology is integrating outcome-based contracting with payers, tying reimbursement to twelve-week responder rates.
REACH compliance requirements for excipient purity are forcing reformulation of chloride channel activators across European manufacturing sites. The regulation's industrial consequence is a 24-month lag for legacy products seeking re-registration. Hospital pharmacies in Germany and the Netherlands are responding by consolidating procurement around suppliers with pre-validated supply chains.
Diagnostic-led prescribing is compressing the interval between symptom onset and prescription initiation as Bristol Stool Scale apps integrate with telehealth platforms. Primary care networks in the United Kingdom are replacing referral-based gastroenterology access with direct-to-specialist digital triage. This shift is most visible in NHS Integrated Care Systems, where wait-time metrics now govern prescribing authority distribution.
Global Chronic Idiopathic Constipation Market Segmentation
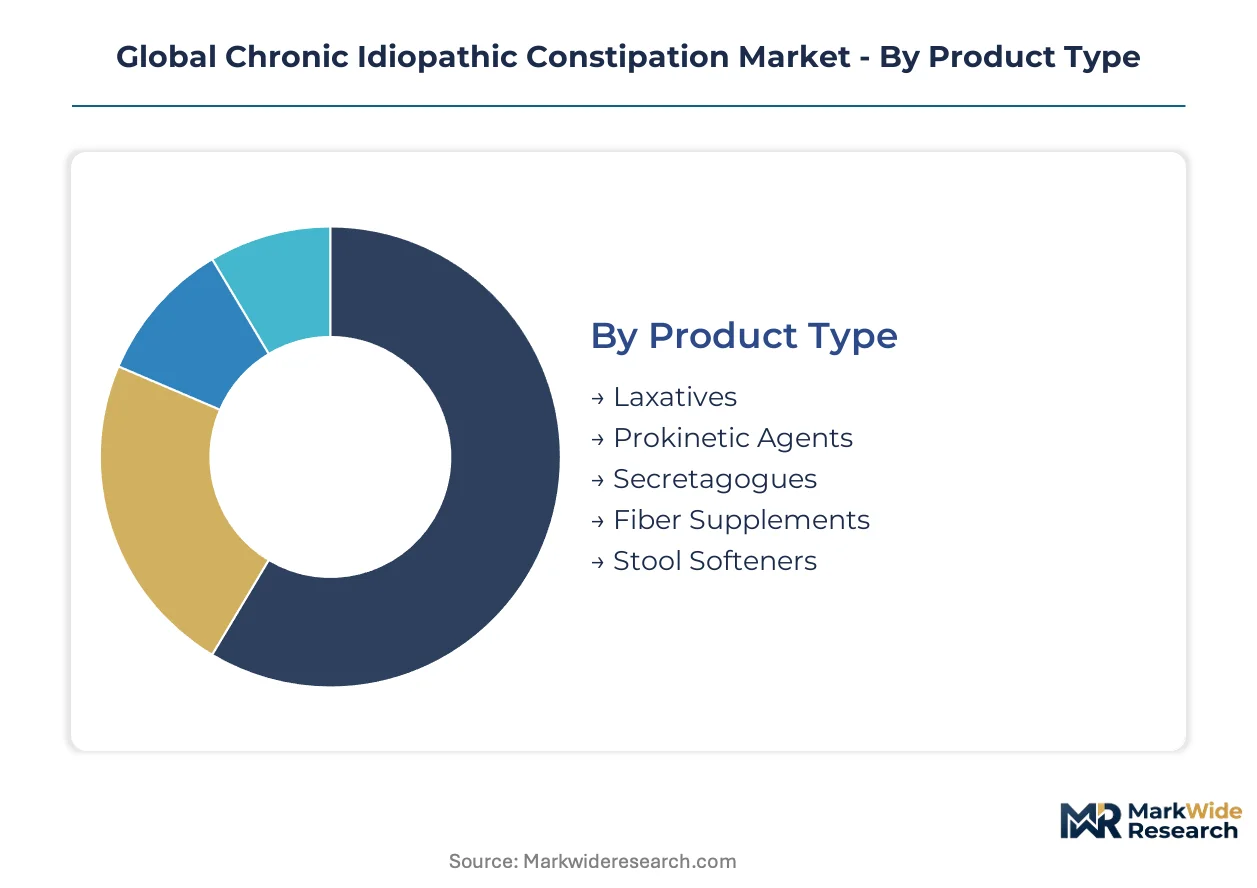
Segmentation in chronic idiopathic constipation markets reveals where capital deployment meets clinical utility. Product categories differ sharply in manufacturing complexity, while distribution channels determine patient access speed and formulary control.
Product Type:
Capital intensity peaks with secretagogue manufacturing, where peptide synthesis and controlled-release formulation require specialized facilities. Laxatives and fiber supplements demand lower upfront investment but compete on scale economies.
- Secretagogues:Guanylate cyclase-C agonists require multi-step solid-phase peptide synthesis with purity thresholds above 99.5%. Demand concentrates in United States specialty clinics where Rome IV-validated outcomes justify premium reimbursement. FDA oversight of excipient quality adds compliance costs that barrier entry.
- Prokinetic Agents:Serotonin receptor agonists and dopamine antagonists target motility dysfunction through distinct neural pathways. Germany and Japan show concentrated prescribing as gastroenterologists prioritize gastric emptying metrics over empirical fiber trials. Manufacturing scales through contract development organizations with validated bioequivalence protocols.
- Laxatives:Osmotic and stimulant formulations dominate high-volume, low-margin retail channels.
- Fiber Supplements:Bulk-forming agents occupy the OTC tier with minimal regulatory burden.
- Stool Softeners:Surfactant-based products serve cost-sensitive health systems and pediatric populations.
Most installed capacity flows through laxatives. Expansion is steepest in secretagogues.
Therapy Area:
Application focus determines trial design complexity and endpoint validation requirements. Functional bowel disorder indications command the longest development timelines but yield the most defensible market positions.
- Functional Bowel Disorders:Rome IV criteria define patient selection, requiring centralized adjudication and patient-reported outcome instruments. The United Kingdom and United States concentrate trial enrollment where diagnostic infrastructure supports protocol compliance. EMA's emphasis on European site representation accelerates Germany and Italy participation.
- Gastrointestinal Disorders:Broad diagnostic coding permits faster recruitment but invites heterogeneous responder populations. Japan's PMDA requires localized pharmacokinetic studies, extending launch timelines for Tokyo and Osaka markets.
- Motility Disorders:Transit-time imaging endpoints add diagnostic cost but improve payer negotiation leverage.
- Neurogenic Causes:Parkinson's and multiple sclerosis comorbidities create specialized prescriber segments.
- Metabolic Causes:Diabetes and hypothyroidism associations drive endocrinology co-prescribing patterns.
Functional bowel disorders absorb the largest development budgets. Motility disorders are gaining share fastest.
End User:
Customer type shapes procurement authority and reimbursement pathway complexity. Institutional buyers negotiate volume contracts, while home healthcare channels prioritize patient adherence packaging.
- Specialty Clinics:Gastroenterology service lines at ambulatory surgery centers capture referrals from primary care, concentrating high-value prescription transactions. United States integrated delivery networks steer volume through owned specialty assets. Staff gastroenterologists control formulary placement through clinical pathway committees.
- Hospitals:Inpatient constipation management focuses on opioid-induced overlap and post-surgical ileus. Germany's hospital pharmacies consolidate procurement around REACH-compliant suppliers with validated supply chains.
- Ambulatory Care Centers:Same-day surgical settings require rapid bowel preparation protocols.
- Home Healthcare:Long-term care facilities and visiting nurse services manage chronic regimens.
Specialty clinics concentrate the highest-value transactions. Home healthcare shows the steepest expansion trajectory.
Distribution Channel:
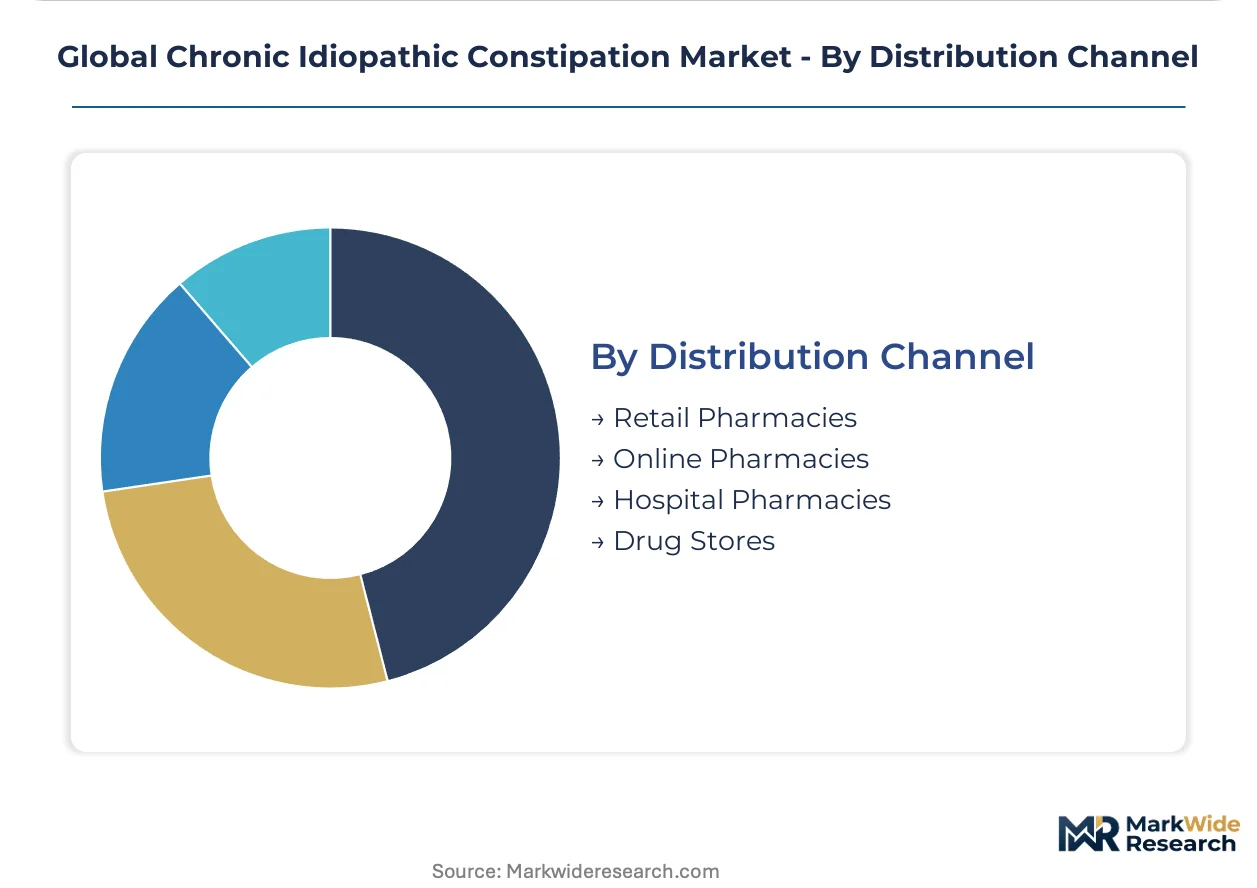
Channel selection determines patient touchpoint frequency and data capture potential. Recurring prescription models favor platforms with subscription infrastructure and adherence tracking.
- Online Pharmacies:Recurring refill platforms capture patient loyalty through subscription models, bypassing traditional retail pharmacy intermediaries. United States platforms integrate with telehealth providers for diagnostic-led prescribing. Data assets enable outcome-based contracting with payers.
- Hospital Pharmacies:Captive dispensing within integrated delivery networks enforces formulary compliance. Netherlands and Germany sites prioritize REACH-validated excipient documentation.
- Retail Pharmacies:Community locations handle acute OTC demand and initial prescription fulfillment.
- Drug Stores:Convenience-focused formats compete on fiber supplement and stool softener accessibility.
Hospital pharmacies process the highest prescription value. Online pharmacies are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States prescription volumes outpace German per-capita utilization by a factor of three, while Japan's aging population is accelerating demand for prokinetic alternatives to fiber-first protocols.
United States
Direct-to-consumer diagnostic campaigns and Rome IV criteria adoption are elevating patient identification rates among undiagnosed populations. FDA guidance on opioid-induced constipation therapies is reshaping prescription pathways for idiopathic indications. Specialty clinic expansion across Texas, Florida, and California is concentrating high-value transactions in ambulatory surgery center gastroenterology service lines.
Germany
Hospital pharmacies are consolidating procurement around REACH-compliant suppliers with validated supply chains for excipient purity. EMA functional bowel disorder guidance emphasizing European site representation is accelerating trial enrollment across Berlin, Munich, and Hamburg clinical research organizations. North Rhine-Westphalia's integrated care networks are implementing Rome IV workflow reconfigurations ahead of national ICD-10-CM transitions.
Japan
METI-targeted healthcare infrastructure investments are creating favorable reimbursement conditions for novel prokinetic agents in Tokyo and Osaka metropolitan markets. PMDA requirements for localized pharmacokinetic studies are extending launch timelines but securing defensible market positions. Kansai region specialty clinics are adopting sustained-release guanylate cyclase-C formulations at twice the rate of standard versions.
United Kingdom
NHS Integrated Care Systems are replacing referral-based gastroenterology access with direct-to-specialist digital triage governed by wait-time metrics. Bristol Stool Scale app integration with telehealth platforms is compressing intervals between symptom onset and prescription initiation. London and Manchester primary care networks are piloting outcome-based contracting models tying reimbursement to twelve-week responder rates.
India
CDSCO regulatory pathways for functional bowel disorder therapies are attracting contract manufacturing investments from multinational sponsors seeking cost-efficient bioequivalence validation. Maharashtra and Gujarat pharmaceutical clusters are expanding API production capacity for peptide-based secretagogues. Bangalore's clinical research organizations are enrolling Rome IV-compliant trials for European and Japanese market access.
Global Chronic Idiopathic Constipation Market Competitive Landscape
United States-based developers anchor the prescription pharmacotherapy tier; European and Japanese specialists hold positions in prokinetic and sustained-release formulation segments. The market structure concentrates around three strategic archetypes: established gastroenterology franchises with integrated delivery network formulary control, pure-play secretagogue developers with specialized pipeline focus, and diversified pharmaceutical conglomerates leveraging patient-reported outcome differentiation. Competitive dynamics center on M&A activity targeting late-stage clinical assets and strategic partnerships combining digital therapeutic platforms with traditional drug approval frameworks.
Within the gastroenterology franchise tier, Sanofi exemplifies integrated delivery network penetration through established formulary relationships. Ironwood Pharmaceuticals and AbbVie occupy positions representing contrasting approaches to guanylate cyclase-C agonist commercialization—specialized focus versus diversified therapeutic area messaging. Takeda Pharmaceutical Company anchors the Japan-origin specialist segment with METI-aligned reimbursement strategies.
| Leading Market Players |
|---|
| Sanofi |
| Astellas Pharma |
| Ironwood Pharmaceuticals |
| Cosmo Pharmaceuticals |
| Novartis |
| AbbVie |
| Bayer AG |
| Salix Pharmaceuticals |
| Takeda Pharmaceutical Company |
| Others |
Supply & Pricing Matrix
Sustained-release formulation technology is compressing manufacturing cost curves for guanylate cyclase-C agonists while concentrating production capability among sponsors with validated peptide synthesis facilities. This shift simultaneously elevates quality premiums for REACH-compliant excipients and exposes cost-sensitive health systems to supply bottlenecks when single-source API facilities face regulatory scrutiny.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for peptide-based secretagogues as contract manufacturers compete on bioequivalence validation speed. Pricing stratifies across premium, standard, and economy tiers, with FDA-validated patient-reported outcome instruments commanding brand premiums while generic laxative substitution intensifies cost compression in the OTC tier. Medicare Part D step-therapy requirements are driving pricing softness in United States institutional channels. Hospital pharmacies show lowest price sensitivity; retail drug stores face highest substitution pressure.
Supply Chain Analysis
Direct-to-specialist channels handle high-value prescription transactions through integrated delivery networks, bypassing traditional retail intermediaries. API manufacturing for linaclotide analogs concentrates in India, China, and select European facilities. Finished dose production draws from specialized peptide synthesis sites with 99.5% purity thresholds and REACH-validated excipient documentation. Single-source vulnerability in Chinese API clusters exposes sponsors to regulatory inspection delays. Distribution runs through hospital pharmacies, specialty clinic dispensaries, and subscription-based online platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic idiopathic constipation market functions as a regulatory compounder, with FDA guidance on opioid-induced constipation therapies reshaping prescription pathways and expanding addressable demand for idiopathic indications.
For Market Incumbents: Hedge against biosimilar entry by deepening captive supply of peptide synthesis capacity in Maharashtra and Gujarat clusters. Lock in formulary control through outcome-based contracting with United States integrated delivery networks, tying reimbursement to twelve-week responder rates validated by Rome IV criteria.
For New Entrants and Emerging Players: The gap between premium secretagogue pricing and economy laxative tiers offers white-space entry through digital therapeutic convergence. Target Japan's Tokyo and Osaka metropolitan markets where METI-aligned reimbursement creates favorable conditions for novel prokinetic agents. Pursue direct-to-consumer diagnostic partnerships to compress patient identification timelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play secretagogue developers with late-stage pipeline assets and established European site representation. Five-to-ten year viability hinges on FDA digital therapeutic guidance integration. Watch for inflection where Bristol Stool Scale app adoption crosses threshold into NHS Integrated Care Systems procurement mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA's European site representation requirement accelerates Germany and Italy enrollment timelines. |
| Regulatory Approval Pathway | FDA guidance on gastrointestinal digital therapeutics opens parallel pharmacotherapy-plus-app combinations. |
| Manufacturing Scale-Up | REACH-compliant excipient validation creates 24-month lag for legacy product re-registration. |
| Pipeline Diversification | Sustained-release guanylate cyclase-C formulations reduce abdominal cramping incidence and improve adherence. |
| Reimbursement Strategy | Outcome-based contracting with United States payers ties payment to Rome IV-validated responder rates. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population estimates and top-down pharmaceutical expenditure trends were triangulated to anchor market sizing.
Segment-weighted modeling distributed value across product type, therapy area, end user, and distribution channel dimensions throughout the forecast period. CAGRs were derived from fitted growth curves applied to prescription volume and pricing trajectories, with inputs including Rome IV diagnostic adoption rates, specialty clinic expansion pipelines, and reimbursement policy shifts across United States, European, and Japanese markets.
Caveats apply where regulatory guidance revisions, API supply disruptions, or digital therapeutic approval pathway changes could materially shift the outlook. Forecasts reflect assumptions about patient identification campaign effectiveness and formulary control durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Atrial Septal Defect Market
Specialty Medicine
Myasthenia Gravis Market
Specialty Medicine
Vascular Dementia Treatment Market
Specialty Medicine
Global Glaucoma Therapeutics Market
Specialty Medicine
Hairy Cell Leukemia Therapeutics Market
Specialty Medicine
Middle East and Africa Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Phenylketonuria Therapeutics Market
Specialty Medicine
Liver Fibrosis Treatment Market
Specialty Medicine
Cubital Tunnel Syndrome Market
Specialty Medicine
Pseudobulbar Treatment Market
Specialty Medicine
Latin America Liver Cancer Treatment Market
Specialty Medicine
Blastomycosis Treatment Market
Specialty Medicine
Toxic Epidermal Neurolysis Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Primary Immunodeficiency Market