
 Schizophrenia Market | 2026-2036
Schizophrenia Market Size, Share, and Industry Trends Forecast 2026-2036
Schizophrenia Market Intelligence
North American clinical trial infrastructure is reshaping how pharmaceutical developers sequence their schizophrenia pipelines. Johnson & Johnson leverages its long-acting injectable franchise to anchor maintenance therapy protocols across institutional formularies. Eli Lilly and Company competes through differentiated receptor-binding profiles in its next-generation antipsychotic candidates. Otsuka Pharmaceutical extends its presence through digital therapeutics paired with pharmacological intervention, a combination few rivals replicate.
Schizophrenia constitutes a chronic, severe mental disorder characterized by disruptions in thought perception, emotional responsiveness, and social functioning, with diagnostic criteria requiring persistent positive symptoms such as hallucinations or delusions alongside functional decline for minimum durations. Antipsychotics remain the pharmacological backbone, with second-generation agents modulating dopamine and serotonin receptor activity to reduce symptom burden while limiting extrapyramidal side effects. Oral formulations still occupy the largest volume share in product type segmentation, though injectable administration routes command premium positioning due to adherence monitoring advantages and reduced relapse rates. Homecare settings represent the fastest-growing end user category as payers push for deinstitutionalization and community-based management models.
The FDA governs new molecular entity approvals through psychopharmacology division standards requiring placebo-controlled efficacy and long-term safety databases, while the DEA schedules controlled substances that cross into dual-diagnosis populations. EMA's centralized procedure demands European pediatric investigation plans even for adult-indication antipsychotics, adding development cost layers that filter market entrants. Stakeholders must monitor how CMS reimbursement policy for long-acting injectables evolves relative to oral generic substitution pressure, as this payment dynamic will determine which formulation investments yield sustainable returns.
Market Dynamics
Long-acting injectable formulations are compressing relapse rates and reshaping maintenance therapy economics, forcing developers to rebalance R&D portfolios between oral generics and depot administration technologies.
Growth Catalysts
- FDA Accelerated Approval:The psychopharmacology division's streamlined pathways for novel mechanisms reduce Phase III duration, pulling investment toward glutamatergic and trace amine-associated receptor targets.
- Homecare Administration:Community-based nursing protocols for depot antipsychotics extend therapy reach into rural and underserved catchment areas previously dependent on institutional visits.
- Digital Therapeutics Integration:Smartphone-based cognitive behavioral therapy adjuncts paired with pharmacological regimens create reimbursement codes that expand addressable patient populations.
Market Restraints
- Generic Oral Substitution:Post-patent expiry of second-generation antipsychotics drives payer-mandated step therapy protocols that displace branded maintenance therapies regardless of adherence profiles.
- EMA Pediatric Investigation Plans:Mandatory juvenile toxicology studies for adult-indication compounds add development cost layers that filter smaller developers from pipeline competition.
- Reimbursement Compression:CMS Medicare Part D coverage gap mechanics and Medicaid best-price calculations compress net pricing power for novel formulations entering crowded therapeutic classes.
Strategic Opportunities
- Dual-Diagnosis Populations:Schizophrenia-spectrum patients with comorbid substance use disorders represent an underserved segment where integrated pharmacological and psychosocial protocols command premium positioning.
- Biomarker-Stratified Trials:CNS drug development is migrating from symptom-based endpoints to neuroimaging and peripheral biomarker stratification, enabling smaller, faster efficacy demonstrations in defined responder populations.
- Long-Acting Injectable Expansion:Six-month and twelve-month depot formulations under development promise to compress the adherence monitoring burden and shift site-of-care economics toward outpatient administration.
Industry Challenges
- Placebo Response Variability:Schizophrenia trials face escalating placebo response rates that demand larger enrollment and longer duration to demonstrate statistical separation, inflating per-patient costs.
- Specialized Psychiatry Recruitment:Principal investigator scarcity in CNS indications extends site activation timelines and concentrates trial execution among a limited network of academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Schizophrenia Market |
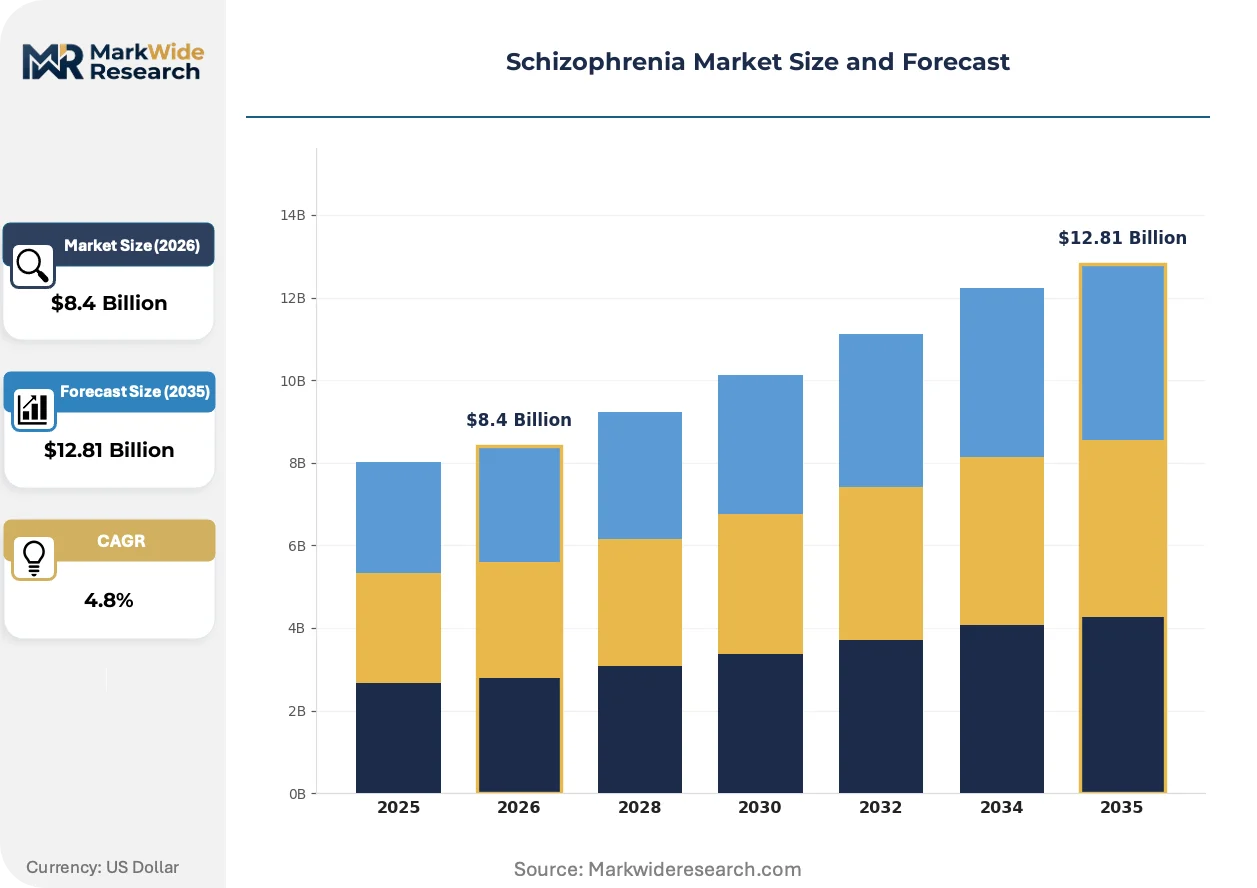
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $12.81 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antipsychotics, Mood Stabilizers, Anti-anxiety Medications, Cognitive Enhancers Administration Route: Oral, Injectable, Transdermal, Intranasal End User: Hospitals, Clinics, Homecare Settings, Rehabilitation Centers Formulation: Tablet, Injectable Solution, Patch, Sublingual Film |
| Companies Covered | Johnson & Johnson, Eli Lilly and Company, Pfizer, AstraZeneca, Otsuka Pharmaceutical, AbbVie, Alkermes, Novartis, Bristol-Myers Squibb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Schizophrenia Market Strategic Shifts & Innovations
Novel receptor targets and administration technologies are fragmenting the historical dopamine-antagonist consensus, creating parallel development tracks for treatment-resistant populations and first-episode intervention.
Trace amine-associated receptor 1 (TAAR1) agonism is migrating from preclinical validation into Phase III programs as a mechanism addressing positive symptoms without direct dopamine blockade. Hospital psychiatry departments in the United States are prioritizing these candidates for formulary inclusion based on extrapyramidal side effect profiles. The structural consequence is a bifurcation between legacy D2-occupancy models and next-generation mechanisms that compress the therapeutic index advantage of established atypicals.
EMA's centralized procedure now mandates real-world evidence submissions alongside traditional randomized controlled trials for CNS indications. This policy shift forces developers to pre-position European observational study infrastructure before regulatory filing. Companies with existing patient registry partnerships in Germany and France are responding by accelerating data collection timelines to meet parallel-track submission requirements.
Payers in the United States are unbundling medication management from institutional psychiatric services, creating standalone reimbursement codes for community nursing administration of long-acting injectables. This behavioral shift disrupts hospital-based psychiatry departments that historically captured both drug and service revenue. The transformation is most visible in Medicaid-managed care populations where state agencies prioritize total cost-of-care reduction over site-of-care neutrality.
Schizophrenia Market Segmentation
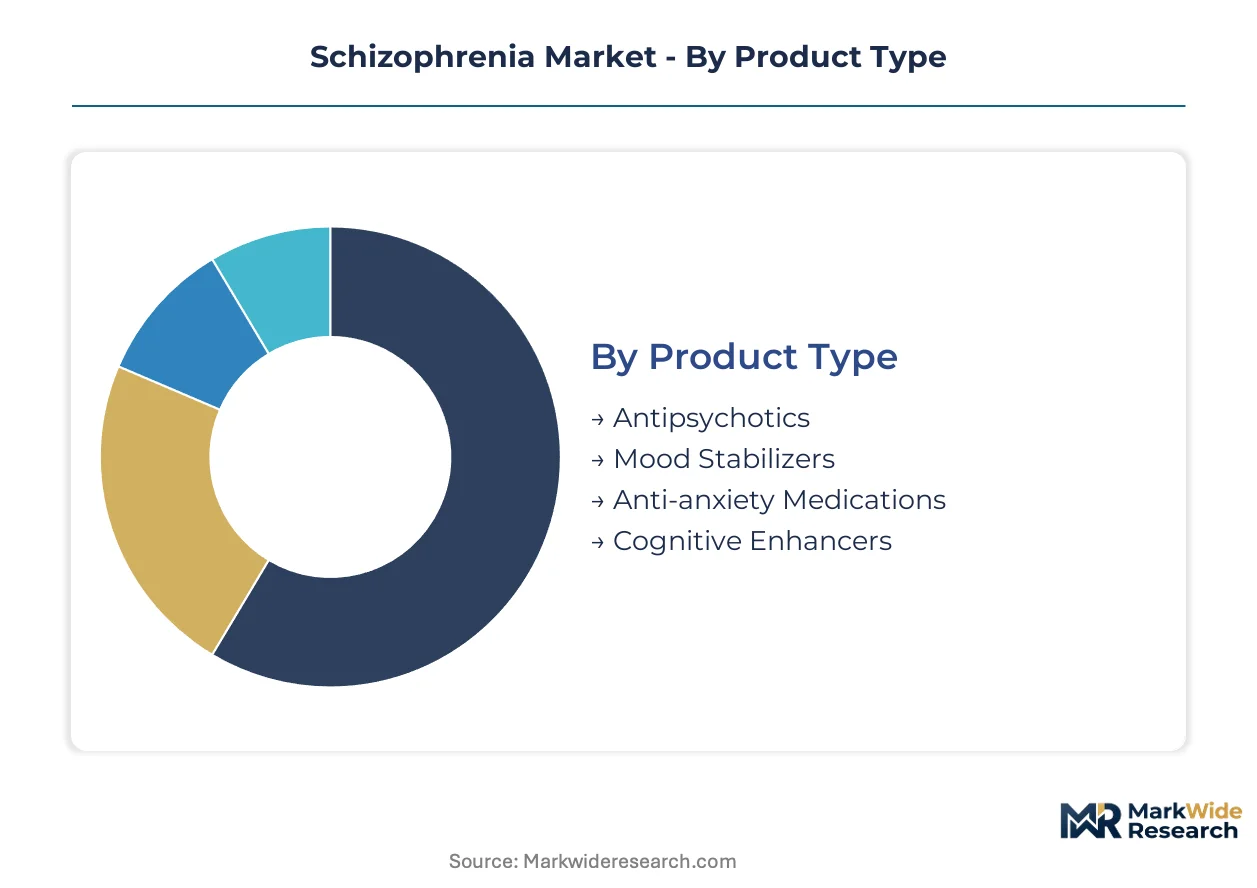
Segmentation in the schizophrenia market determines reimbursement pathways, site-of-care economics, and adherence monitoring investments. Each dimension carries distinct regulatory, clinical, and commercial implications that shape portfolio allocation decisions.
Product Type:
After-sales service intensity concentrates around patient monitoring programs and relapse prevention infrastructure, with each therapeutic class demanding differentiated clinical support.
- Antipsychotics:First and second-generation agents modulating dopamine receptor activity constitute the pharmacological backbone. Demand clusters in United States maintenance therapy protocols where long-acting formulations command premium reimbursement. FDA psychopharmacology division standards require extensive safety databases that filter development pipelines toward established mechanisms.
- Mood Stabilizers:Lithium compounds and anticonvulsant derivatives address affective dysregulation in schizoaffective presentations. Concentrated prescribing occurs in European hospital psychiatry departments where EMA centralized procedures govern formulary inclusion. Lithium's narrow therapeutic index necessitates specialized monitoring infrastructure that shapes service delivery models.
- Anti-anxiety Medications:Benzodiazepine and non-benzodiazepine anxiolytics manage comorbid anxiety symptoms. DEA scheduling requirements constrain distribution channels for controlled substances.
- Cognitive Enhancers:Cholinesterase inhibitors and glutamate modulators target negative symptoms and functional impairment. Emerging reimbursement codes in German outpatient psychiatry programs signal commercial traction.
Antipsychotics hold the largest share; momentum sits with cognitive enhancers.
Administration Route:
Cost tier stratification separates institutional administration from community-based delivery, with formulation technology driving price positioning.
- Oral:Tablet and liquid formulations dominate prescription volume through pharmacy dispensing channels. Medicaid best-price calculations compress net margins for branded oral agents facing generic substitution pressure.
- Injectable:Depot and long-acting formulations enable adherence monitoring with administration intervals extending from two weeks to six months. United States payers unbundle medication management from institutional services, creating standalone reimbursement for community nursing administration.
- Transdermal:Patch delivery systems bypass first-pass metabolism for patients with gastrointestinal absorption variability. Limited commercial penetration reflects formulation stability challenges.
- Intranasal:Rapid-onset delivery for acute agitation episodes targets emergency psychiatry settings. Development pipelines concentrate on ketamine-derived mechanisms for treatment-resistant populations.
Injectable routes claim premium positioning; oral formulations maintain volume leadership.
End User:
Customer type determines procurement sophistication, with institutional buyers leveraging formulary control against dispersed community prescribing.
- Hospitals:Inpatient psychiatry units and emergency departments manage acute exacerbations and medication initiation. United States academic medical centers concentrate Phase III trial execution and early formulary adoption of novel mechanisms.
- Clinics:Outpatient mental health centers provide maintenance therapy and medication management. French regional health agencies coordinate procurement across public psychiatry networks.
- Homecare Settings:Community nursing services administer long-acting injectables in patient residences. This segment expands most quickly as state Medicaid programs prioritize total cost-of-care reduction.
- Rehabilitation Centers:Residential and day programs focus on functional recovery and social integration. Reimbursement fragmentation across federal and state funding streams constrains medication access.
Hospitals anchor institutional volume; homecare settings gain share fastest.
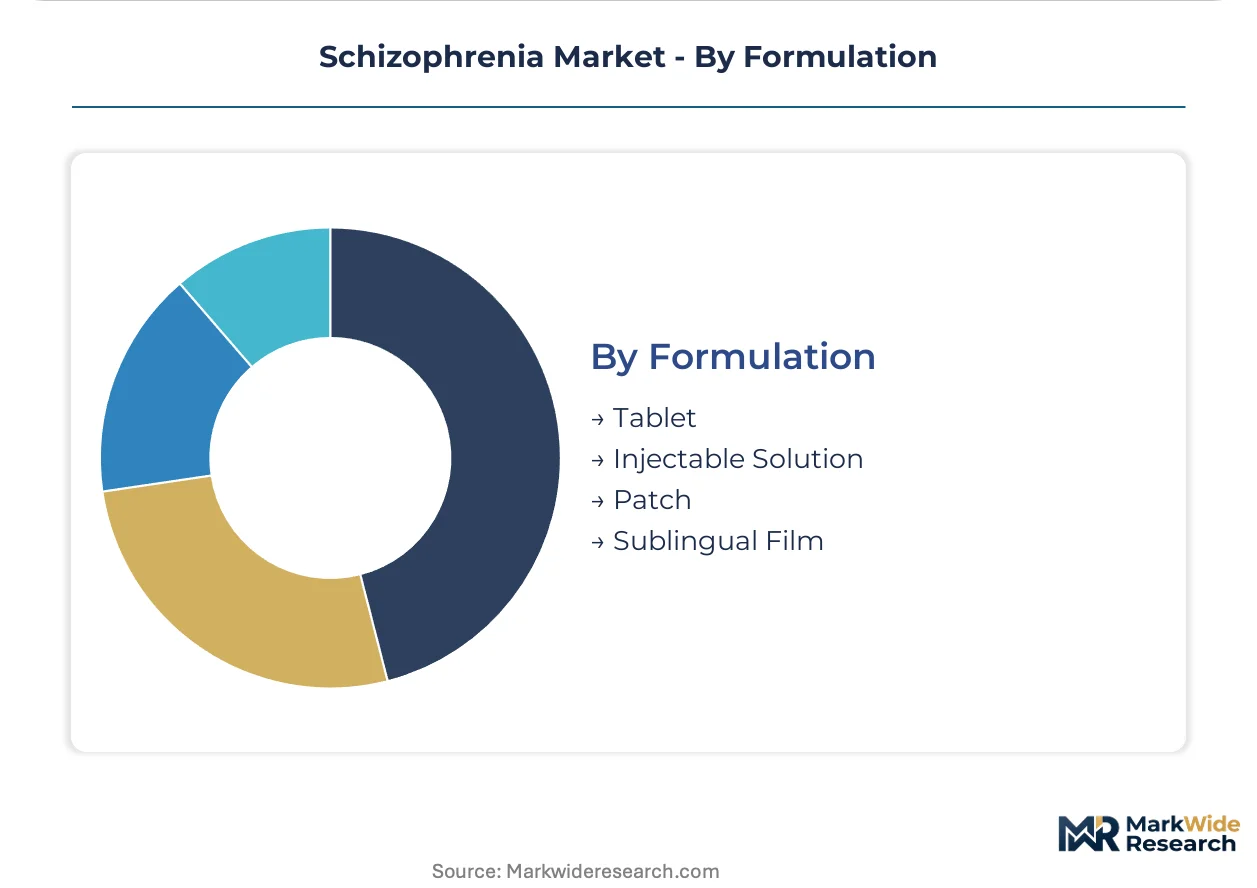
Formulation:
Supply concentration in manufacturing technology creates barriers, with complex delivery systems requiring specialized production infrastructure.
- Tablet:Compressed solid dosage forms dominate oral antipsychotic dispensing. Indian and Chinese contract manufacturers supply active pharmaceutical ingredients to branded and generic finished dose producers.
- Injectable Solution:Aqueous and oil-based suspensions enable depot release kinetics. Lyophilization and aseptic filling capabilities concentrate among European and North American specialty manufacturers.
- Patch:Matrix and reservoir transdermal systems require adhesive formulation expertise and skin permeation optimization. Limited commercial availability reflects development cost barriers.
- Sublingual Film:Rapid-dissolving polymer matrices improve bioavailability and patient acceptance. Otsuka Pharmaceutical's asenapine formulation established precedent for orodispersible antipsychotic delivery.
Tablets command volume leadership; injectable solutions concentrate value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States schizophrenia patients receive long-acting injectables at rates threefold higher than German or Japanese cohorts, reflecting divergent payer incentives and site-of-care economics across major markets.
United States
Medicaid-managed care programs drive depot antipsychotic uptake through total cost-of-care contracts. FDA psychopharmacology division standards for novel mechanisms attract Phase III trial concentration. Massachusetts General Hospital and Stanford Medicine anchor academic psychiatry networks that validate formulary adoption.
Germany
Regional health agencies coordinate procurement across public psychiatry networks with preference for oral generics. EMA centralized procedures mandate pediatric investigation plans that extend development timelines. Heidelberg and Berlin academic medical centers concentrate biomarker-stratified trial infrastructure.
Japan
PMDA review standards emphasize long-term safety databases for maintenance therapy approvals. METI industrial policy supports digital therapeutics integration with pharmacological regimens. Tokyo and Osaka metropolitan areas concentrate hospital psychiatry capacity and early formulary access.
United Kingdom
NHS England commissioning frameworks prioritize community-based administration of long-acting injectables. NICE technology appraisals set reimbursement thresholds for novel antipsychotic mechanisms. London and Manchester academic networks dominate CNS trial execution.
Switzerland
Swissmedic approval pathways attract European headquarters for specialty psychiatry developers. Cantonal health insurance models enable premium pricing for adherence-optimized formulations. Basel and Zurich clusters concentrate pharmaceutical R&D investment.
Schizophrenia Market Key Industry Players
Capability concentration sits with large-cap pharmaceutical developers possessing established psychiatry franchises; scale advantage sits with mid-cap specialists focused on formulation technology and administration innovation. The market structure divides between diversified conglomerates with institutional formulary relationships and focused players with depot delivery expertise. Two strategic archetypes dominate: long-acting injectable platform holders and next-generation mechanism developers. Competitive moves concentrate on portfolio expansion through in-licensing of late-stage assets and geographic extension of patient support infrastructure.
Among diversified pharmaceutical conglomerates, Johnson & Johnson and Eli Lilly and Company exemplify the institutional-formulary archetype with established maintenance therapy protocols. Otsuka Pharmaceutical occupies a distinct position through its integration of digital therapeutics with pharmacological intervention, representing a combination approach few rivals replicate.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Eli Lilly and Company |
| Pfizer |
| AstraZeneca |
| Otsuka Pharmaceutical |
| AbbVie |
| Alkermes |
| Novartis |
| Bristol-Myers Squibb |
| Others |
Cost & Logistics Intelligence
Single-source dependency on Indian and Chinese active pharmaceutical ingredient suppliers determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of finished dose manufacturing. Formulation complexity and regulatory compliance tiering create price spreads that compress when generic oral substitution intensifies.
Pricing Analysis
United States Medicaid best-price calculations generate spreads threefold wider than German regional health agency procurement for equivalent molecules. Pricing stratifies across premium, standard, and economy tiers based on formulation technology and adherence-monitoring service bundling. Cost compression in oral generic tiers is intensifying because payer-mandated step therapy protocols displace branded maintenance therapies. Community nursing administration of long-acting injectables commands lowest price sensitivity; oral tablet dispensaries face highest.
Supply Chain Analysis
Tariff exposure between United States and Chinese chemical intermediate suppliers dominates supply chain risk assessments for second-generation antipsychotic production. API manufacturing concentrates in India, China, and Italy, drawing from specialized precursor chemicals and lyophilization equipment. Single-source vulnerability in aseptic filling capacity for depot formulations feeds from European and North American contract manufacturing organization concentration. Distribution runs through institutional pharmacy networks and specialty distributors with cold-chain capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient monitoring programs and relapse prevention infrastructure represent the fastest-expanding recurring-revenue layer, outpacing pharmaceutical product margins as payers unbundle medication management from drug reimbursement.
For Market Incumbents: Harden formulary anchoring through six-month and twelve-month depot formulation pipelines that compress generic substitution vulnerability. Deepen backward integration into peptide and polymer excipient supply to secure manufacturing slots at European aseptic filling contractors. FDA psychopharmacology division standards for novel mechanisms demand pre-positioned safety databases that filter competitors. For New Entrants and Emerging Players: Establish a beachhead in community nursing administration protocols for long-acting injectables where institutional incumbents lack service infrastructure. Target Medicaid-managed care populations in United States states prioritizing total cost-of-care reduction over site-of-care neutrality. Digital therapeutics integration with pharmacological regimens offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion for glutamatergic and trace amine-associated receptor targets reshapes the acquisition landscape toward Phase II-stage mechanism developers. Long-term viability across the projection horizon rests on biomarker-stratified trial infrastructure that enables smaller, faster efficacy demonstrations. Watch EMA real-world evidence submission requirements as the inflection signal for European market access cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Acting Injectable Pipeline Advancement | Six-month depot formulations compress adherence monitoring burden and shift site-of-care economics toward outpatient administration. |
| Digital Therapeutics Integration | Smartphone-based cognitive behavioral therapy adjuncts create standalone reimbursement codes that expand addressable patient populations. |
| Biomarker-Stratified Trial Infrastructure | Neuroimaging and peripheral biomarker validation enables smaller efficacy demonstrations in defined responder populations. |
| Community Nursing Network Expansion | Homecare administration protocols extend therapy reach into rural catchment areas previously dependent on institutional visits. |
| Regulatory Real-World Evidence Positioning | Pre-positioned European observational study infrastructure meets EMA parallel-track submission requirements before filing. |
Research Approach
The analysis maps antipsychotic formulation technologies, mood stabilizer procurement channels, and cognitive enhancer reimbursement pathways, each validated through formulary directors, regulatory affairs leads, and payer access specialists. Primary interviews with hospital psychiatry department heads and community nursing service administrators combine with secondary validation from FDA filings, EMA centralized procedure documents, ClinicalTrials.gov registries, and CMS Medicare Part D coverage data. Bottom-up prescription volume modeling and top-down therapeutic class revenue triangulation cross-validate segment-level estimates.
Fixed assumptions across the modeling period include FDA psychopharmacology division standards for novel mechanisms, CMS reimbursement policy evolution for long-acting injectables, and EMA pediatric investigation plan requirements. Segmentation dimensions span product type, administration route, end user category, and formulation technology. CAGRs derive from patient population prevalence trends, treatment rate trajectories, and pricing elasticity by payer channel. Forecast inputs incorporate long-acting injectable adoption curves and digital therapeutics reimbursement code expansion.
Sensitivities concentrate around generic oral substitution velocity, FDA accelerated approval pathway utilization rates, and CMS Medicare Part D coverage gap mechanics. Forecasts reflect documented assumptions about regulatory timelines and payer behavior patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Seasonal Affective Disorder (SAD) Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Schizoaffective Disorders Treatment Market
Mental Health Services
US Workplace Stress Management Market
Mental Health Services
Agoraphobia Treatment Market
Mental Health Services
AI-Powered Mental Health Solutions Market
Mental Health Services
Agoraphobia Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
China Post-Traumatic Stress Disorder Treatment Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Mental Health Market
Mental Health Services
Postpartum Depression (PPD) Treatment Market