
 Blastomycosis Treatment Market | 2026-2036
Blastomycosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Blastomycosis Treatment Market Insights
Multi-source API procurement for azole antifungals is realigning supply security priorities among contract manufacturers. Pfizer Inc. leverages decades of amphotericin B production scale to sustain hospital channel dominance. Gilead Sciences, Inc. anchors its position through specialized lipid formulation expertise. Sun Pharmaceutical Industries Ltd. competes on cost-engineered generic itraconazole supply to outpatient clinics.
Blastomycosis treatment encompasses pharmaceutical interventions targeting systemic dimorphic fungal infection caused by Blastomyces dermatitidis, with amphotericin B serving as the standard induction therapy for severe pulmonary or disseminated disease due to its fungicidal mechanism against yeast-phase organisms. The primary clinical purpose centers on reducing mortality in immunocompromised patients and preventing CNS dissemination through sustained azole consolidation therapy. Azoles command the largest share of maintenance-phase prescriptions, while intravenous administration retains priority in intensive care settings where oral bioavailability is compromised. The disseminated infection application segment carries the highest therapeutic urgency and corresponding reimbursement intensity.
FDA orphan drug designations and EPA environmental monitoring protocols jointly shape antifungal development incentives and endemic region public health investment. CDC blastomycosis surveillance requirements drive diagnostic testing standardization across state health departments. Stakeholders must monitor how climate-driven expansion of Blastomyces habitat ranges reshapes geographic prescribing patterns and formulary prioritization decisions.
Market Dynamics
Hospital formulary committees are consolidating antifungal procurement around single-source lipid amphotericin B contracts, compressing vendor diversity and reshaping competitive access pathways across endemic regions.
Growth Catalysts
- Orphan drug incentives:FDA streamlined pathways for rare fungal indications accelerate clinical trial enrollment and reduce development timelines for novel azole formulations targeting severe blastomycosis.
- Environmental surveillance expansion:EPA monitoring protocols in the Ohio and Mississippi River valleys drive earlier case detection and expand addressable patient pools through state health department screening programs.
- Immunocompromised population growth:Solid organ transplant centers and oncology infusion clinics generate sustained demand for prophylactic and therapeutic antifungal protocols.
Market Restraints
- API supply concentration:Azole active pharmaceutical ingredient production clusters in select Asian contract manufacturing sites, exposing formulators to single-point disruption risks.
- Reimbursement compression:CMS bundled payment models for inpatient fungal infections limit per-dose pricing flexibility for branded lipid formulations.
- Diagnostic latency:Blastomyces antigen cross-reactivity with Histoplasma delays definitive diagnosis, prolonging inappropriate empiric therapy and reducing targeted treatment initiation rates.
Strategic Opportunities
- Point-of-care molecular diagnostics:PCR-based Blastomyces species identification at regional hospitals enables same-day targeted therapy initiation, shortening time-to-treatment versus culture-based methods.
- Outpatient oral consolidation protocols:Extended-spectrum azole maintenance regimens shift treatment volume from infusion centers to retail pharmacy channels, opening formulary access for generic itraconazole suppliers.
- Climate-driven range expansion:Northward migration of Blastomyces habitat into the Great Lakes region creates first-mover advantage for establishing diagnostic and therapeutic infrastructure in newly endemic counties.
Industry Challenges
- Specialized mycology training gaps:Clinical microbiology laboratories face shortages of certified fungal diagnosticians capable of distinguishing Blastomyces from morphologically similar dimorphic pathogens.
- Cold-chain lipid formulation logistics:Amphotericin B liposome stability requirements demand continuous temperature monitoring through hospital pharmacy distribution, elevating operational complexity and spoilage risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blastomycosis Treatment Market |
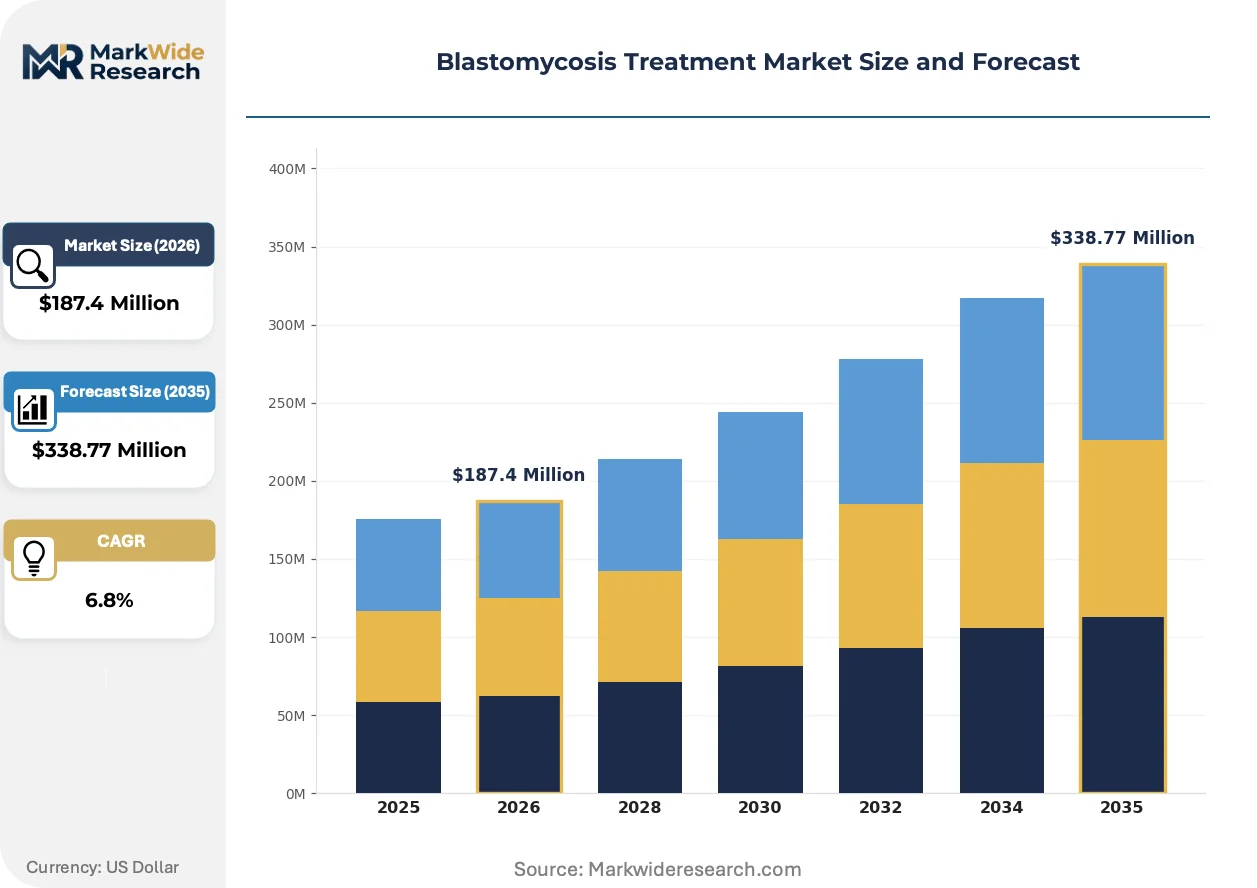
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Azoles, Amphotericin B, Itraconazole, Others Route of Administration: Oral, Intravenous, Topical, Inhalation End User: Hospitals, Clinics, Homecare, Research Labs Application: Pulmonary Infection, Disseminated Infection, Central Nervous System Infection, Cutaneous Infection |
| Companies Covered | Novartis AG, Gilead Sciences, Inc., Pfizer Inc., Sun Pharmaceutical Industries Ltd., Scynexis Inc., Merck & Co., Inc., Bristol-Myers Squibb Company, Abbott Laboratories, Astellas Pharma Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blastomycosis Treatment Market Trends and Innovations
Antifungal development is pivoting toward targeted delivery mechanisms and diagnostic-therapeutic integration, reducing empiric broad-spectrum exposure while improving outcomes in disseminated disease.
Liposomal nanocarrier technology is unifying drug delivery and toxicity reduction in severe blastomycosis treatment. Intensive care units and transplant centers are adopting these formulations as first-line induction therapy for renal-sparing protocols. This convergence is compressing the market share of conventional amphotericin B deoxycholate in high-acuity settings.
EMA orphan drug designation pathways for invasive fungal infections are harmonizing with FDA incentives, creating dual-approval strategies for developers targeting systemic mycoses. European reference pricing mechanisms for hospital-administered antifungals are pressuring manufacturers to demonstrate mortality benefit versus standard-of-care azoles. Oncology and hematology wards in Germany and France are responding by demanding head-to-head clinical data for formulary inclusion.
Integrated diagnostic-therapeutic protocols are replacing empiric antifungal initiation in pulmonary infectious disease services. Hospital-based stewardship programs now mandate antigen or PCR confirmation before authorizing lipid amphotericin B for suspected blastomycosis, displacing prolonged empiric coverage. This behavioral shift is most pronounced in Wisconsin and Minnesota health systems with established endemic disease surveillance infrastructure.
Blastomycosis Treatment Market Segmentation
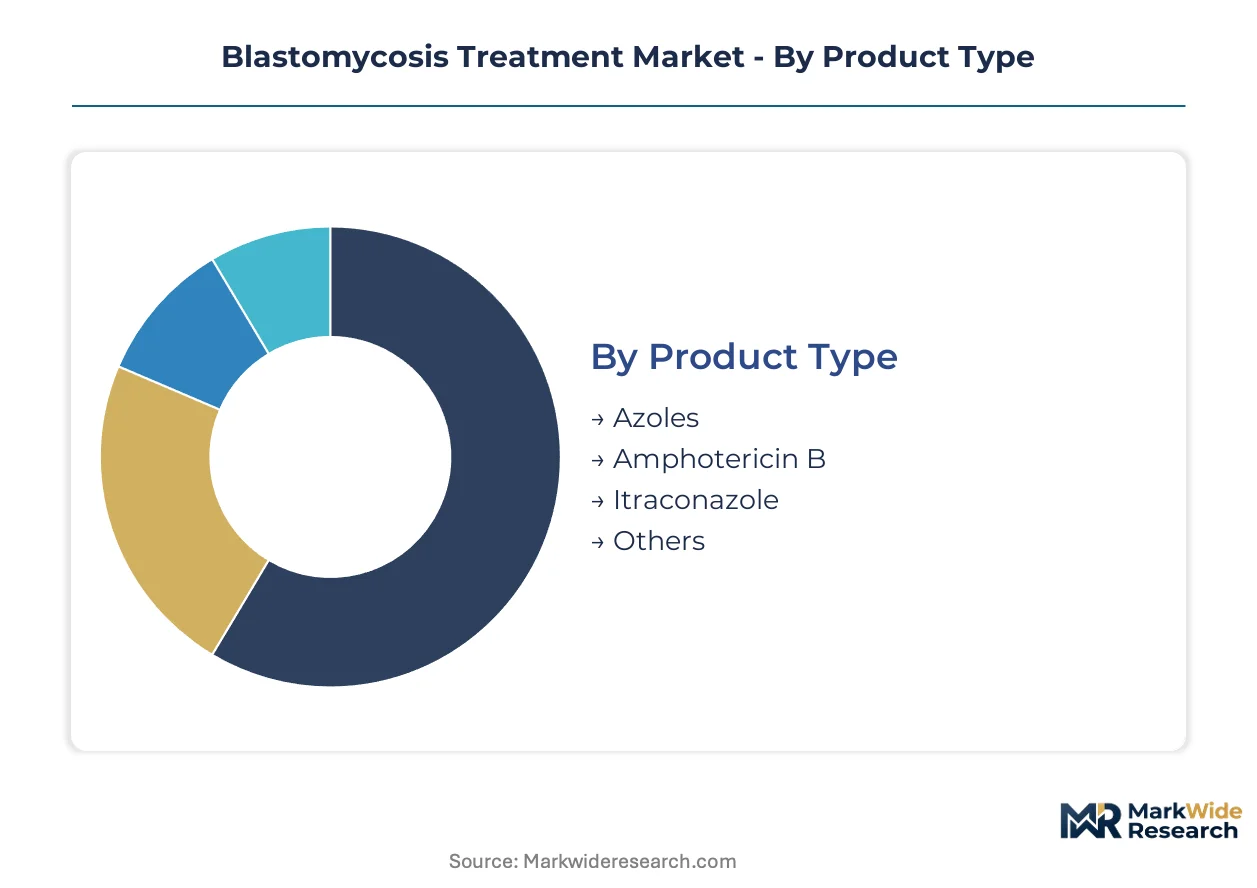
Segmentation in blastomycosis treatment reflects divergent clinical workflows across acute care and ambulatory settings. Procurement patterns differ sharply between hospital formularies prioritizing intravenous induction therapy and outpatient channels managing extended azole consolidation.
Product Type:
Hospital formulary committees weight renal toxicity profiles and acquisition cost in tiered procurement decisions for systemic antifungal therapy.
- Azoles:Oral triazole antifungals including voriconazole and posaconazole provide extended consolidation therapy with favorable safety margins for outpatient adherence. Demand concentrates in transplant centers and oncology clinics across Wisconsin and Minnesota where prolonged maintenance regimens prevent relapse in immunosuppressed patients.
- Amphotericin B:Polyene antifungal administered intravenously delivers fungicidal activity against yeast-phase Blastomyces in severe pulmonary or disseminated presentations. Intensive care units in Ohio River valley hospitals prioritize lipid formulations for renal-sparing induction protocols in patients with baseline kidney dysfunction.
- Itraconazole:First-line oral azole for mild-to-moderate pulmonary blastomycosis and step-down consolidation after amphotericin B response.
- Others:Investigational agents and combination therapies under evaluation for refractory or CNS-penetrant indications.
Volume sits with azoles for maintenance-phase prescriptions; growth tilts toward lipid amphotericin B formulations in high-acuity hospital segments.
Route of Administration:
Patient acuity and gastrointestinal function determine administration pathway selection, with bioavailability constraints driving channel-specific procurement.
- Intravenous:Hospital-administered delivery ensures therapeutic drug levels in critically ill patients with compromised absorption or CNS involvement. Demand concentrates in academic medical centers and transplant units where continuous infusion capability supports extended induction courses.
- Oral:Outpatient-compatible administration enables discharge planning and reduces infusion center burden for stable patients completing consolidation therapy. Retail pharmacy channels in endemic counties capture volume as oral bioavailability supports home-based regimens.
- Topical:Localized delivery for cutaneous blastomycosis lesions as adjunct to systemic therapy.
- Inhalation:Investigational aerosolized formulations targeting pulmonary fungal burden with reduced systemic exposure.
Procurement volume clusters in intravenous channels for inpatient revenue; oral routes are expanding most quickly as stewardship programs push early step-down protocols.
End User:
Care setting determines reimbursement mechanics and formulary control points, with institutional purchasing power concentrating vendor relationships.
- Hospitals:Integrated delivery networks command volume discounts through single-source contracts for lipid amphotericin B and centralized pharmacy oversight. IDN procurement committees in Michigan and Illinois health systems negotiate annual antifungal agreements tied to mortality outcome metrics.
- Clinics:Outpatient infectious disease practices manage stable patients through oral azole prescribing with laboratory monitoring protocols. Community specialty clinics in endemic regions build referral relationships with hospital discharge planners.
- Homecare:Infusion nursing services support prolonged IV therapy for patients failing oral transition.
- Research Labs:Academic medical centers and CROs conduct clinical trials for novel antifungal agents.
Hospital systems capture the largest prescription volume; homecare channels show steepest expansion as payers favor outpatient cost structures.
Application:
Disease severity and anatomic involvement drive therapeutic intensity, with mortality risk stratifying reimbursement authorization requirements.
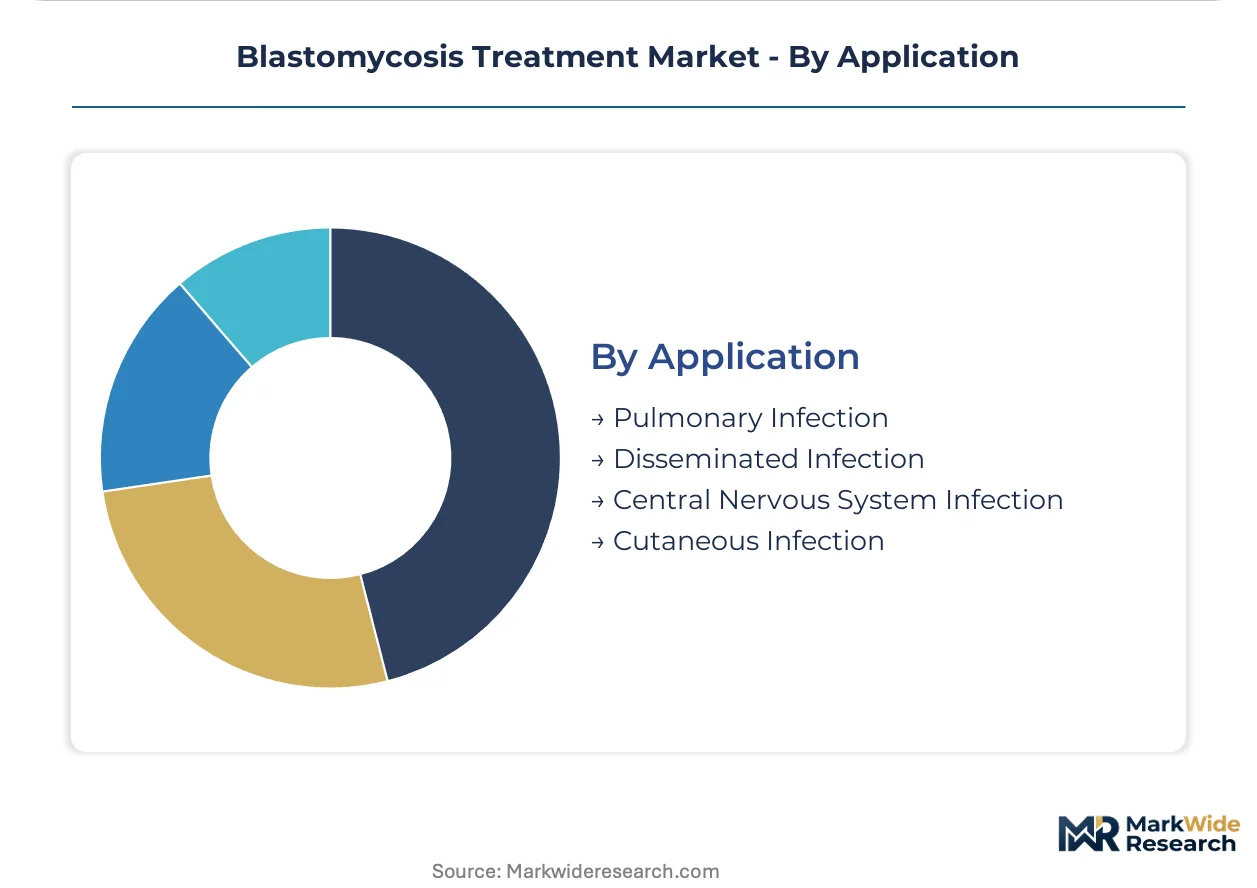
- Disseminated Infection:Multi-organ involvement including bone, skin, and genitourinary sites demands prolonged combination therapy with highest therapeutic urgency. Transplant and oncology services in endemic regions prioritize rapid molecular confirmation to authorize aggressive induction protocols.
- Pulmonary Infection:Isolated lung involvement represents the most common presentation, with diagnostic ambiguity requiring differentiation from malignancy and tuberculosis. Pulmonary services in Wisconsin health systems mandate antigen testing before empiric antifungal initiation.
- Central Nervous System Infection:Meningeal or parenchymal involvement requires agents with blood-brain barrier penetration and extended treatment duration.
- Cutaneous Infection:Skin and soft tissue manifestations often signal disseminated disease requiring systemic rather than local therapy.
Disseminated infection commands the highest per-patient therapeutic investment; pulmonary applications generate the largest case volume for screening and early intervention programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Blastomyces dermatitidis environmental reservoirs concentrate along the Ohio and Mississippi River valleys, anchoring therapeutic demand in the United States while climate-driven range expansion reshapes geographic prescribing patterns across North America.
United States
Wisconsin and Minnesota health systems generate concentrated demand for oral azole maintenance regimens in transplant populations. CDC blastomycosis surveillance requirements drive diagnostic standardization across state health departments. The Ohio River valley hospital networks in Illinois and Michigan negotiate single-source lipid amphotericin B contracts through integrated delivery networks.
Canada
Ontario and Quebec pulmonary services manage sporadic cases imported from endemic US regions or acquired near the Great Lakes. Health Canada reference pricing mechanisms for hospital-administered antifungals pressure manufacturers to demonstrate mortality benefit versus standard azole therapy. Toronto academic medical centers maintain specialized mycology diagnostic capacity for species confirmation.
Germany
Oncology and hematology wards in Berlin and Munich demand head-to-head clinical data for formulary inclusion of novel antifungal agents. EMA orphan drug designation pathways harmonize with FDA incentives for developers targeting systemic mycoses. The German hospital sector applies outcome-based procurement criteria to lipid formulation contracts.
France
Paris infectious disease services coordinate with ANSM on antifungal stewardship protocols for immunocompromised patients. French reference pricing mechanisms for hospital-administered therapies compress per-dose margins for branded formulations. The Île-de-France region concentrates diagnostic expertise for disseminated fungal infections in transplant centers.
United Kingdom
London NHS trusts implement integrated diagnostic-therapeutic protocols mandating antigen confirmation before authorizing induction therapy. NICE technology appraisals evaluate cost-effectiveness of extended-spectrum azoles against standard itraconazole. The UK hospital pharmacy sector consolidates procurement around mortality-outcome metrics for severe fungal infections.
Blastomycosis Treatment Market Competitive Landscape
Portfolio diversification dominates the current landscape as established pharmaceutical manufacturers extend antifungal franchises through lipid formulation expertise and generic azole supply. The vendor base separates into three distinct tiers: large-cap diversified pharmaceuticls with hospital channel dominance, mid-cap specialty infectious disease players, and cost-engineered generic suppliers. Two strategic archetypes anchor competitive positioning: renal-sparing formulation specialists and outpatient oral consolidation protocol enablers. M&A activity and capacity expansion in API manufacturing represent the dominant competitive moves reshaping supply security.
Within the large-cap diversified tier, Pfizer Inc. and Gilead Sciences, Inc. occupy positions anchored by decades of amphotericin B production scale and specialized lipid formulation expertise respectively. Novartis AG sits within the same tier as a Swiss-based pharmaceutical with established hospital formulary relationships. These three entities exemplify the competitive archetype of leveraging manufacturing scale and clinical data portfolios to secure single-source contracts with integrated delivery networks across endemic regions.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences, Inc. |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Scynexis Inc. |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Abbott Laboratories |
| Astellas Pharma Inc. |
| Others |
Pricing and Supply Chain Analysis
Azole API spot pricing indices cascade through contract manufacturing tiers into three-tier pricing structures across premium lipid formulations, standard generic azoles, and economy-grade bulk itraconazole, with hospital procurement committees in endemic US regions arbitrating tier selection through mortality-outcome metrics.
Pricing Analysis
Service bundling separates renal-sparing lipid amphotericin B protocols with embedded clinical pharmacist oversight from unbundled generic azole supply where monitoring costs shift to outpatient providers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA orphan designation status, GMP certification tier, and volume commitment scale. Cost compression in standard azole tiers is intensifying because CMS bundled payment models cap per-episode reimbursement. Community clinics in the Ohio River valley exhibit highest price sensitivity; transplant centers demonstrate lowest sensitivity due to outcome-based contracting.
Supply Chain Analysis
Dual-sourcing mandates from hospital formulary committees in Wisconsin and Illinois now require qualification of at least two API suppliers for critical azole inputs, compressing single-source dependencies. Azole active pharmaceutical ingredient production clusters in India, China, and select Eastern European contract manufacturing sites, drawing from specialized fermentation feedstocks, lipid excipient imports, and cold-chain packaging materials. Single-source vulnerability persists in liposomal formulation technology where patent-protected processes limit supplier diversity. Distribution runs through hospital pharmacy central procurement with regional distribution center consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into azole API fermentation capacity represents the decisive vertical-integration lever as hospital procurement committees prioritize supply security over unit cost in endemic region contracts.
For Market Incumbents: Deepen captive control over liposomal formulation technology through in-house nanocarrier production scale, while locking multi-year azole API offtake agreements with Indian and Chinese contract manufacturers to preempt emerging generic suppliers. The threat of point-of-care molecular diagnostic displacement demands co-development partnerships with PCR platform developers to maintain therapy initiation influence. For New Entrants and Emerging Players: FDA orphan drug streamlined pathways in the United States open a window for novel azole formulations targeting CNS-penetrant indications underserved by current maintenance regimens. White-space concentration sits with outpatient oral consolidation protocols in newly endemic Great Lakes counties where diagnostic infrastructure lags therapeutic demand. Go-to-market execution should anchor on specialty pharmacy channel partnerships with embedded laboratory monitoring services. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap generic azole manufacturers with approved abbreviated new drug applications and established FDA inspection histories in India. Long-term viability hinges on consolidation of fragmented API supply into three to four vertically integrated platforms capable of serving hospital system single-source contracts. The signal to watch is EPA expansion of Blastomyces habitat monitoring into additional state health departments, which would trigger diagnostic infrastructure investment waves and corresponding therapy demand.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pathway | FDA streamlined review accelerates enrollment for severe blastomycosis indications in transplant populations. |
| API Manufacturing Scale-Up | Captive fermentation capacity in India secures supply continuity for hospital formulary single-source contracts. |
| Point-of-Care Diagnostic Partnership | PCR platform integration enables same-day therapy authorization in Wisconsin and Minnesota health systems. |
| Outpatient Oral Consolidation Protocol | Extended-spectrum azole regimens shift revenue capture from infusion centers to retail pharmacy channels. |
| Climate-Driven Geographic Expansion | First-mover diagnostic infrastructure in Great Lakes counties captures emerging endemic case volume. |
Research Methodology
Multi-period observation of hospital antifungal procurement volumes, EPA environmental surveillance expansion, and FDA orphan drug approval timelines anchored the trend analysis, supplemented by interviews with infectious disease clinicians, hospital pharmacy directors, formulary committee chairs, and contract manufacturing executives. Secondary validation drew from FDA Orange Book listings, CMS Medicare Part B reimbursement databases, ClinicalTrials.gov enrollment data, and state health department blastomycosis surveillance reports. Bottom-up patient volume modeling and top-down pharmaceutical expenditure triangulation converged on segment-level estimates.
Input-output matrices mapped azole API production capacity through formulation tiers to end-use hospital and clinic channels across the analysis window. Segmentation dimensions encompassed product type, route of administration, end-user setting, disease severity application, and regional regulatory cluster. CAGRs were derived from log-linear trend fitting to standardized case incidence projections and therapy penetration assumptions. Forecast inputs included climate-driven habitat range expansion models and immunocompromised population growth trajectories.
The model assumes a particular technology adoption path; alternative pathways for liposomal nanocarrier delivery would alter the outlook if renal-sparing protocols displace faster than projected. Deviation in EPA environmental monitoring budget allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Idiopathic Thrombocytopenic Purpura Therapeutics Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Cystic Fibrosis Therapeutics Market
Specialty Medicine
Tinnitus Management Market
Specialty Medicine
Global Axial Spondyloarthritis (Axspa) Market
Specialty Medicine
Advance Renal Cell Carcinoma Therapeutics Market
Specialty Medicine
Global Myopia and Presbyopia Treatment Market
Specialty Medicine
Rosacea Therapeutics Market
Specialty Medicine
North America Gastric Cancer Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Whipple's Disease Market
Specialty Medicine
Sjogrens Syndrome Market
Specialty Medicine
Neurosyphilis Market
Specialty Medicine
Irritable Bowel Syndrome (IBS) Treatment Market