
 Saudi Arabia Telecom Market | 2026-2036
Saudi Arabia Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Telecom Market Outlook
Wholesale fiber backhaul corridors between Riyadh and Jeddah is narrowing as stc anchors long-haul capacity through controlled landing stations and dark fiber leases. Mobily leverages its eastern infrastructure to sustain industrial connectivity contracts around Jubail and Ras Al-Khair. Zain KSA competes on mobile enterprise packages, positioning its 5G slice offerings for logistics and mining operators.
Saudi Arabia telecom encompasses voice, data, and broadband transmission services delivered over 4G, 5G, fiber optic, and satellite infrastructure with latency thresholds below 10 milliseconds for enterprise-grade fiber and throughput rates exceeding 1 Gbps on mid-band 5G deployments. The sector serves residential consumption, business productivity systems, and government digital transformation programs. Data and broadband services dominate value generation as enterprise migration to cloud architectures and IoT backhaul requirements expand. 5G technology represents the fastest-growing infrastructure layer as spectrum auctions and base station densification accelerate. Prepaid and postpaid pricing models segment consumer liquidity profiles, with bundled plans capturing higher lifetime value through fixed-mobile convergence.
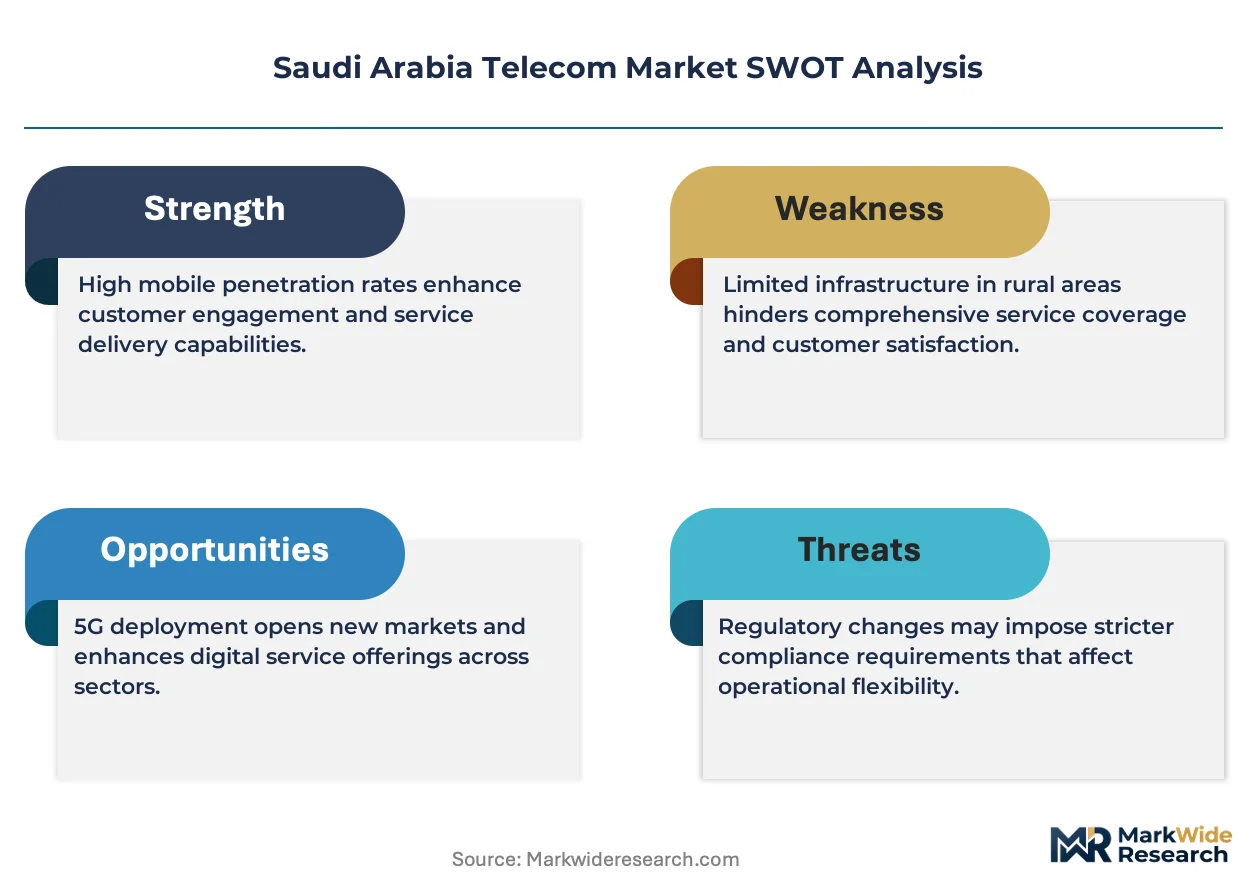
The Communications, Space and Technology Commission governs licensing, spectrum allocation, and interconnection tariffs, while the National Cybersecurity Authority mandates encryption and data sovereignty standards for critical infrastructure operators. These frameworks shape capital deployment timelines and vendor qualification requirements for network equipment procurement. Stakeholders must monitor spectrum refarming decisions and localization rules for cloud data residency as regulatory compliance becomes a competitive differentiator in enterprise contract bidding.
Market Dynamics
Network function virtualization and edge computing architectures are compressing capital deployment cycles while the Communications, Space and Technology Commission accelerates spectrum refarming for 5G-Advanced readiness.
Growth Catalysts
- Enterprise cloud migration:Oil-gas operators and logistics providers in the Eastern Province are procuring dedicated fiber and 5G private networks to support real-time drilling analytics and automated yard management.
- Smart city mandates:NEOM and Red Sea Project infrastructure specifications require sub-10 millisecond latency connectivity, forcing fiber densification and base station upgrades across greenfield developments.
- Data localization requirements:National Cybersecurity Authority data sovereignty rules for critical infrastructure are stimulating domestic data center construction and interconnection demand.
Market Restraints
- Equipment supply concentration:Radio access network hardware dependencies on East Asian component suppliers create lead time volatility and qualification bottlenecks for new base station deployments.
- Fiber trenching costs:Rocky terrain in the central Najd region and rights-of-way negotiations with municipal authorities inflate per-kilometer deployment costs versus coastal plains.
- Skilled technician scarcity:Specialized fiber splicing and 5G antenna calibration expertise concentrates in Riyadh and Jeddah, constraining rollout velocity in secondary cities.
Strategic Opportunities
- Private 5G networks:Mining operators in the Northern Borders and manufacturing complexes in Sudair Industrial City are soliciting dedicated spectrum slices for autonomous haulage and predictive maintenance.
- Edge computing nodes:Content delivery and gaming providers are deploying micro-data centers in Dammam and Khobar to reduce latency for Gulf Cooperation Council traffic.
- Satellite-terrestrial convergence:Low-earth orbit constellation integration offers backhaul redundancy for remote wellheads and desert logistics corridors underserved by fiber.
Industry Challenges
- Legacy copper decommissioning:Operators face stranded asset write-downs and customer migration friction as they accelerate fiber-to-the-home replacement of aging DSL infrastructure.
- Interconnection tariff disputes:Wholesale pricing negotiations between fixed and mobile network operators delay service launches and create margin compression in enterprise segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Telecom Market |
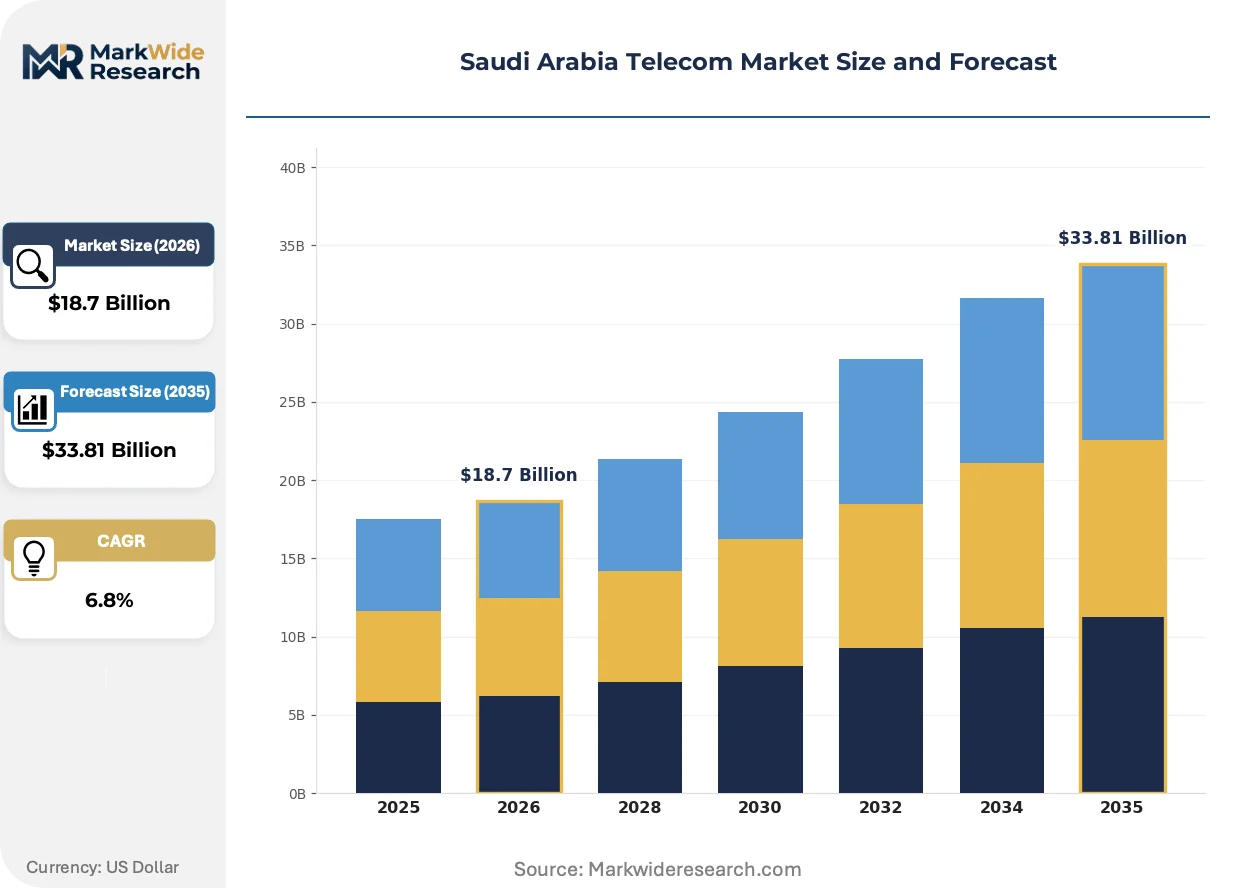
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Data, SMS, Broadband Customer Type: Residential, Business, Government, Wholesale Technology: 4G, 5G, Fiber Optic, Satellite Pricing Model: Prepaid, Postpaid, Bundled Plans, Pay-As-You-Go |
| Companies Covered | Etihad Atheeb Telecommunication Company, Arabian Internet and Communications Services Company, stc (Saudi Telecom Company), Bayanat Al Oula for Network Services, Al Wafa Communication for Internet Services, Mobily (Etihad Etisalat), Integrated Telecom Company, Red Sea International, Zain KSA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Telecom Market Strategic Shifts
Software-defined networking and network function virtualization are rewriting how Saudi operators architect core infrastructure, collapsing hardware dependency and accelerating service velocity.
Open RAN architectures are virtualizing radio access network functions onto commodity servers, enabling stc and Mobily to disaggregate vendor lock-in and trial multi-supplier configurations in Riyadh testbeds. Mobile network operators are adopting these standards to reduce single-source dependency and accelerate feature deployment cycles. This virtualization is compressing equipment procurement timelines from 18-month hardware cycles to quarterly software releases.
The Communications, Space and Technology Commission's mandatory cybersecurity certification for IoT devices and critical infrastructure equipment is reshaping vendor qualification protocols. Equipment suppliers must now demonstrate encryption compliance and supply chain transparency before network deployment authorization. Enterprise buyers in energy and healthcare verticals are prioritizing pre-certified hardware to avoid procurement delays.
Industrial buyers are consolidating connectivity procurement under single-source managed service contracts rather than fragmented carrier relationships. Mining and petrochemical operators in Jubail and Yanbu are bundling fiber, 5G, and satellite failover into multi-year performance-based agreements. This concentration is visible most acutely in the Eastern Province where data center proximity enables service-level guarantee enforcement.
Saudi Arabia Telecom Market Segmentation
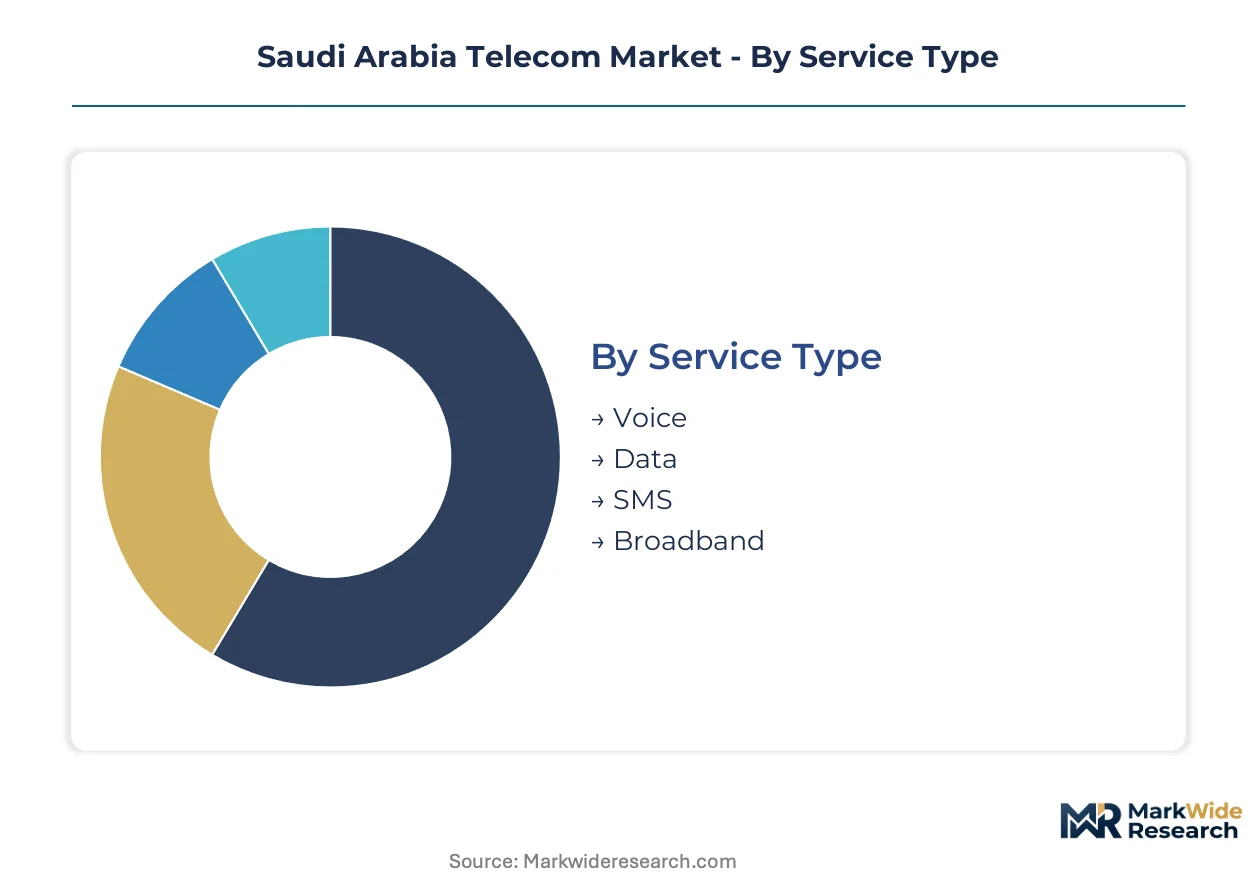
Segmentation in the Saudi Arabia telecom market reveals how service architecture, customer procurement patterns, and infrastructure layers interact to shape revenue concentration. Each dimension exposes distinct margin profiles and capital deployment priorities for operators competing across Riyadh's enterprise corridors and Eastern Province industrial zones.
Service Type:
The use-case spectrum spans legacy voice transmission through high-throughput broadband pipes, with each service tier commanding different infrastructure investments and customer lifetime values.
- Voice:Circuit-switched and VoIP services deliver real-time audio connectivity with compression codecs optimized for sub-150 kbps bandwidth. Demand concentrates among government agencies in Riyadh maintaining secure landline networks for classified communications, constrained by PSTN decommissioning timelines.
- Data:Packet-switched mobile and fixed data services transport enterprise cloud traffic and consumer video streams across 4G and 5G bearers. Oil-gas operators in the Eastern Province are procuring dedicated data pipes for real-time drilling analytics, driving fiber backhaul expansion toward Jubail and Ras Al-Khair.
- SMS:Store-and-forward text messaging services persist as authentication and IoT signaling channels despite OTT displacement of peer-to-peer traffic. Banking and logistics verticals in Jeddah rely on A2P SMS for transaction alerts and delivery notifications.
- Broadband:High-capacity fixed-line internet access delivers 100+ Mbps throughput via GPON and DOCSIS infrastructure to residential and SME premises. Fiber-to-the-home rollouts in Riyadh and Jeddah are displacing aging DSL, though rocky terrain in the Najd region inflates trenching costs.
The dominant share belongs to Data, while Broadband is closing the gap fastest as fiber densification accelerates across greenfield developments.
Customer Type:
Procurement scale and contract duration vary sharply across this dimension, from fragmented residential subscriptions to multi-year government frameworks with embedded service-level guarantees.
- Residential:Individual households consuming voice, video, and internet services through prepaid or postpaid arrangements. Fixed-mobile convergence bundles are capturing higher lifetime value in Riyadh and Jeddah as stc and Mobily compete on household ARPU.
- Business:Corporate entities procuring dedicated connectivity, cloud access, and managed network services. Mining operators in the Northern Borders and manufacturing complexes in Sudair Industrial City are soliciting private 5G networks for autonomous operations.
- Government:Ministries and agencies requiring secure, sovereign infrastructure with data residency compliance. The National Cybersecurity Authority mandates encryption standards that reshape vendor qualification for critical infrastructure contracts.
- Wholesale:Carrier-to-carrier capacity leasing and interconnection services enabling retail operators to extend geographic coverage. Dark fiber leases between Riyadh and Jeddah are narrowing as stc anchors long-haul capacity through controlled landing stations.
Business segment margins outpace residential, though Government contracts deliver the longest revenue visibility through multi-year frameworks.
Technology:
Infrastructure layer selection determines latency thresholds, capital intensity, and competitive differentiation in coverage versus capacity trade-offs.
- 4G:LTE-Advanced macro networks delivering 50-100 Mbps typical speeds through 700 MHz and 1800 MHz spectrum assignments. Rural coverage obligations and voice fallback requirements sustain 4G as the baseline layer despite 5G overlay acceleration.
- 5G:New radio architectures in sub-6 GHz and mmWave bands enabling 1+ Gbps throughput and network slicing for enterprise verticals. NEOM and Red Sea Project specifications mandate sub-10 millisecond latency, forcing base station densification across greenfield developments.
- Fiber Optic:GPON and DWDM terrestrial networks providing wireline backhaul and last-mile access with sub-10 millisecond latency for enterprise grade. Wholesale fiber corridors concentrate between Riyadh and Jeddah, with eastern infrastructure serving Jubail industrial connectivity.
- Satellite:Geostationary and low-earth orbit constellations delivering backhaul redundancy for remote wellheads and desert logistics corridors underserved by terrestrial infrastructure. LEO integration offers failover for mining and oil-gas operations in the Empty Quarter.
5G infrastructure commands the steepest expansion trajectory as spectrum refarming accelerates, while Fiber Optic delivers the most stable margin profile through long-haul and access monetization.
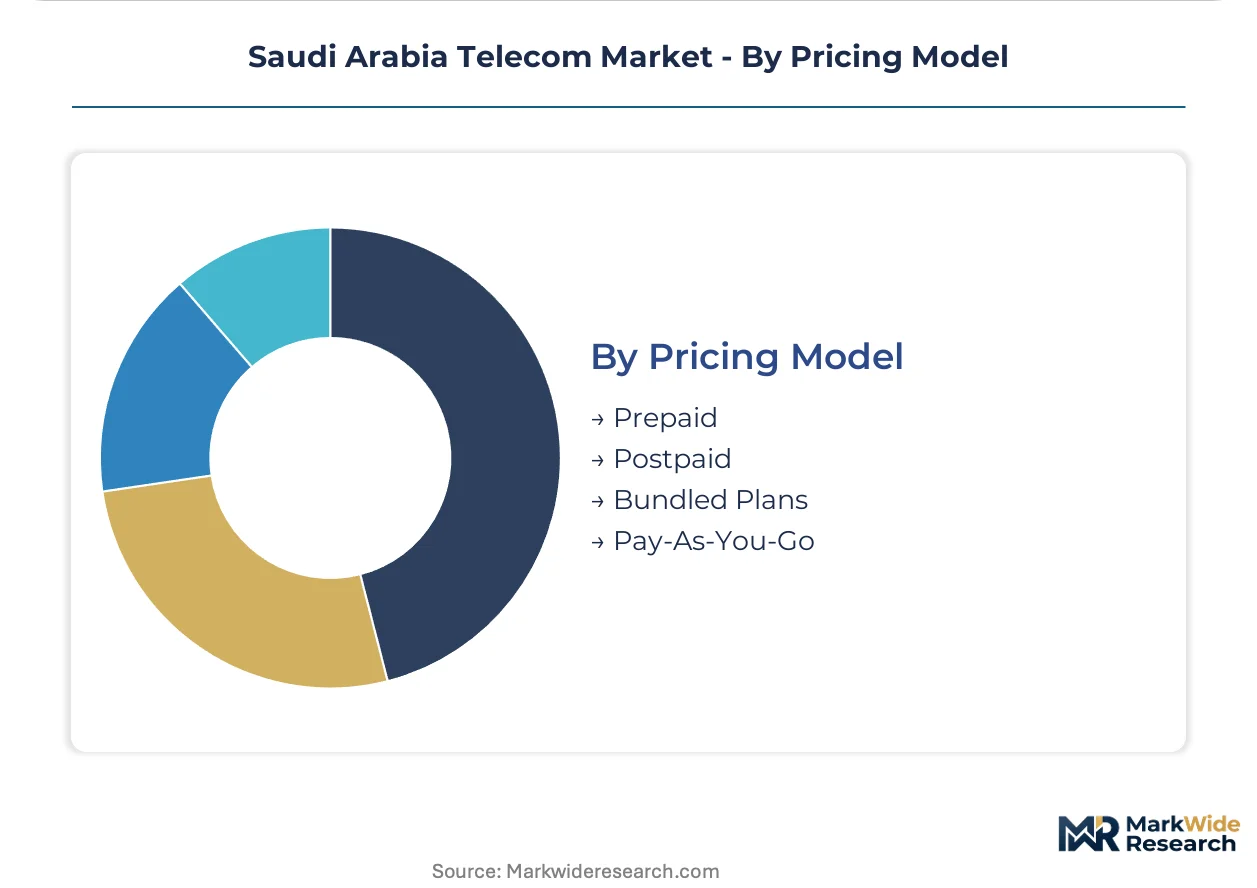
Pricing Model:
Payment structure alignment with customer liquidity profiles and usage predictability shapes churn rates and working capital requirements.
- Prepaid:Advance payment for service credit with no contractual commitment, dominant among price-sensitive residential segments and temporary workers. Lower ARPU is offset by reduced bad debt exposure and simplified credit risk management.
- Postpaid:Monthly billing against usage with contractual minimum terms, capturing higher-value residential and SME customers with predictable consumption patterns. Bundle integration with fixed services reduces churn in competitive Riyadh and Jeddah metros.
- Bundled Plans:Converged offerings combining mobile, fixed broadband, and content subscriptions under single pricing. Fixed-mobile convergence is capturing higher lifetime value through reduced subscriber acquisition costs and stickier household relationships.
- Pay-As-You-Go:Per-use or per-MB metering without recurring fees, serving intermittent users and IoT deployments with sporadic transmission requirements. Logistics and fleet management operators in Dammam and Khobar utilize this model for tracking device connectivity.
Postpaid and Bundled Plans together anchor revenue stability, though Prepaid retains volume dominance in migrant worker demographics and secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Riyadh-Dammam fiber corridor anchors eastern Saudi Arabia's industrial connectivity, while the Jeddah landing stations on the Red Sea route traffic toward Africa and Europe. These terrestrial and submarine assets concentrate procurement decisions and vendor qualification protocols across four distinct economic zones.
Riyadh
Government digital transformation and financial services digitization drive infrastructure procurement in the capital. The National Cybersecurity Authority mandates encryption standards for critical infrastructure contracts, reshaping vendor selection for ministries and agencies. Data center clusters in King Abdullah Financial District attract hyperscale cloud operators seeking low-latency enterprise connectivity.
Eastern Province
Oil-gas digitization projects and petrochemical automation sustain dedicated fiber and 5G private network demand around Jubail and Ras Al-Khair. The Communications, Space and Technology Commission's spectrum allocations enable industrial slicing for real-time drilling analytics. Aramco's digital transformation programs anchor multi-year managed service agreements with guaranteed latency thresholds.
Western Region
Pilgrimage traffic and logistics corridors generate seasonal capacity spikes and year-round mobile data consumption in Jeddah and Makkah. The Saudi Ports Authority's smart port initiatives require redundant backhaul for container tracking and customs automation. Fiber densification lags coastal metros due to terrain challenges and municipal rights-of-way negotiations.
NEOM Northwest
Greenfield city specifications mandate sub-10 millisecond latency connectivity for autonomous mobility and IoT infrastructure from inception. The NEOM Authority's procurement frameworks prioritize software-defined networking and open RAN architectures unconstrained by legacy equipment. Edge computing nodes and micro-data centers deploy alongside residential and industrial zones to localize processing.
Saudi Arabia Telecom Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying radio access hardware and optical transmission equipment. The Saudi market exhibits tiered consolidation with three national mobile operators controlling spectrum assets and a fragmented fixed-broadband layer of regional licensees. Strategic archetypes include state-backed incumbents with infrastructure dominance, mobile challengers competing on enterprise 5G slicing, and wholesale fiber specialists serving industrial zones. Competitive moves center on spectrum acquisition for 5G-Advanced readiness and long-term managed service contracts bundling connectivity with cybersecurity compliance.
Among Riyadh-headquartered operators, stc anchors the incumbent tier with integrated fixed-mobile infrastructure and controlled submarine cable landing stations. Mobily, operating from the Eastern Province base, exemplifies the industrial connectivity specialist leveraging regional fiber density for petrochemical and mining contracts. Zain KSA represents the mobile-first challenger competing on 5G enterprise packages and logistics verticals in Dammam and Jeddah corridors.
| Leading Market Players |
|---|
| Etihad Atheeb Telecommunication Company |
| Arabian Internet and Communications Services Company |
| stc (Saudi Telecom Company) |
| Bayanat Al Oula for Network Services |
| Al Wafa Communication for Internet Services |
| Mobily (Etihad Etisalat) |
| Integrated Telecom Company |
| Red Sea International |
| Zain KSA |
| Others |
Value Chain & Pricing Dynamics
The Dammam-Jubail freight corridor's elevated logistics costs transmit directly into equipment landed pricing and downstream service tier differentiation across the Saudi telecom sector. Supply concentration in East Asian radio access network component manufacturing amplifies these cost dynamics, forcing operators to absorb margin compression or pass through via enterprise contract renegotiation.
Pricing Analysis
Volume-discount tiering structures dominate enterprise connectivity procurement, with oil-gas operators in the Eastern Province capturing steep per-port reductions through multi-year managed service commitments. Price differentiation rests on latency grade certification and fiber route diversity rather than brand premium alone. Pricing pressure stems from wholesale fiber corridor densification between Riyadh and Jeddah as stc anchors controlled capacity. Government agencies exhibit lowest price sensitivity due to cybersecurity mandate compliance costs, while residential prepaid segments in secondary cities resist ARPU elevation.
Supply Chain Analysis
Extended payment terms from Chinese and South Korean radio access network suppliers have become standard, with supply-chain finance facilities bridging 90-120 day procurement cycles for Saudi operators. Geographic supply concentration centers on China for baseband units, South Korea for RF components, and Taiwan for specialized optical chips. Raw material dependencies span gallium nitride semiconductors, high-purity optical fiber, and lithium-ion backup power systems. Single-source vulnerability in 5G massive MIMO antenna arrays creates qualification bottlenecks. Distribution runs through CSTC-certified system integrators serving Riyadh and Dammam enterprise corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi telecom market is navigating a cyclical recovery anchored to the Communications, Space and Technology Commission's 5G-Advanced spectrum refarming timeline. Enterprise cloud migration and smart city infrastructure deployment are restoring capital deployment velocity after a compressed investment cycle.
For Market Incumbents: Harden fiber infrastructure control through accelerated dark fiber lease standardization along the Riyadh-Dammam corridor before wholesale price erosion accelerates. Secure CSTC cybersecurity certification pre-qualification for core network equipment to lock out non-compliant challengers in government segments. Vertical integration into edge computing node construction preserves margin capture as latency requirements tighten.
For New Entrants and Emerging Players: Secondary cities in the Najd region present white-space opportunity where skilled technician scarcity has constrained incumbent rollout velocity. Private 5G network deployments for mining operators in the Northern Borders offer entry with lower spectrum barrier than national mobile licensing. Target satellite-terrestrial convergence for remote wellhead connectivity as a beachhead before fiber extension economics improve.
For Investors and Strategic Acquirers: Regional fiber specialists with eastern province industrial zone density represent the most defensible acquisition archetype given Aramco digital transformation contract visibility. Long-term viability hinges on 5G-Advanced readiness and open RAN architecture adoption rather than legacy vendor lock-in. Watch CSTC spectrum refarming announcements as the inflection signal for infrastructure replacement capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Architecture Adoption | stc and Mobily trial multi-supplier configurations in Riyadh testbeds to collapse vendor lock-in. |
| Private 5G Network Deployment | Mining operators in the Northern Borders procure dedicated spectrum slices for autonomous haulage systems. |
| Edge Computing Node Construction | Content delivery providers deploy micro-data centers in Dammam to reduce GCC traffic latency. |
| Satellite-Terrestrial Convergence | LEO constellation integration offers backhaul redundancy for Empty Quarter wellheads beyond fiber reach. |
| Cybersecurity Certification Pre-Qualification | NCA encryption compliance reshapes vendor selection for critical infrastructure government contracts. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with network planning executives at mobile operators, procurement leads at oil-gas majors, CSTC regulatory affairs officers, and hyperscale cloud infrastructure directors; alongside secondary validation through CSTC spectrum allocation records, NCA cybersecurity directive filings, SEC 20-F submissions by listed operators, and customs data on network equipment imports. Bottom-up service revenue modeling and top-down infrastructure capex triangulation anchored market sizing.
Forecast inputs considered 5G base station densification trajectories, fiber-to-the-home replacement cycles, and enterprise private network adoption curves across the projection horizon. Segmentation dimensions modeled include service type, customer vertical, infrastructure technology layer, and pricing model structure. CAGRs were derived from equipment shipment run-rates and contract value disclosures. Industry-specific inputs encompassed CSTC spectrum auction timelines and Aramco digital transformation program scope.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed infrastructure specialists or sovereign wealth-backed technology platforms would shift outcomes. Macroeconomic oil price volatility, regulatory acceleration of data localization mandates, or breakthroughs in low-earth orbit satellite economics would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
TV White Space Spectrum Market
Telecommunications
Austria ICT Market
Telecommunications
Global Telecom Operations Management Market
Telecommunications
South Africa Telecom Market
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Promotional Sms Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Indonesia B2B Telecom Market
Telecommunications
Managed M2M Services Market
Telecommunications
Dialer Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
Global 4G LTE Market
Telecommunications
IP Telephony Market
Telecommunications
Argentina ICT Market
Telecommunications
Global Dense Wave Digital Multiplexing (DWDM) System Market
Telecommunications
Telecom Radio System Software Market