
 Managed M2M Services Market | 2026-2036
Managed M2M Services Market Size, Share, and Industry Trends Forecast 2026-2036
Managed M2M Services Market Outlook
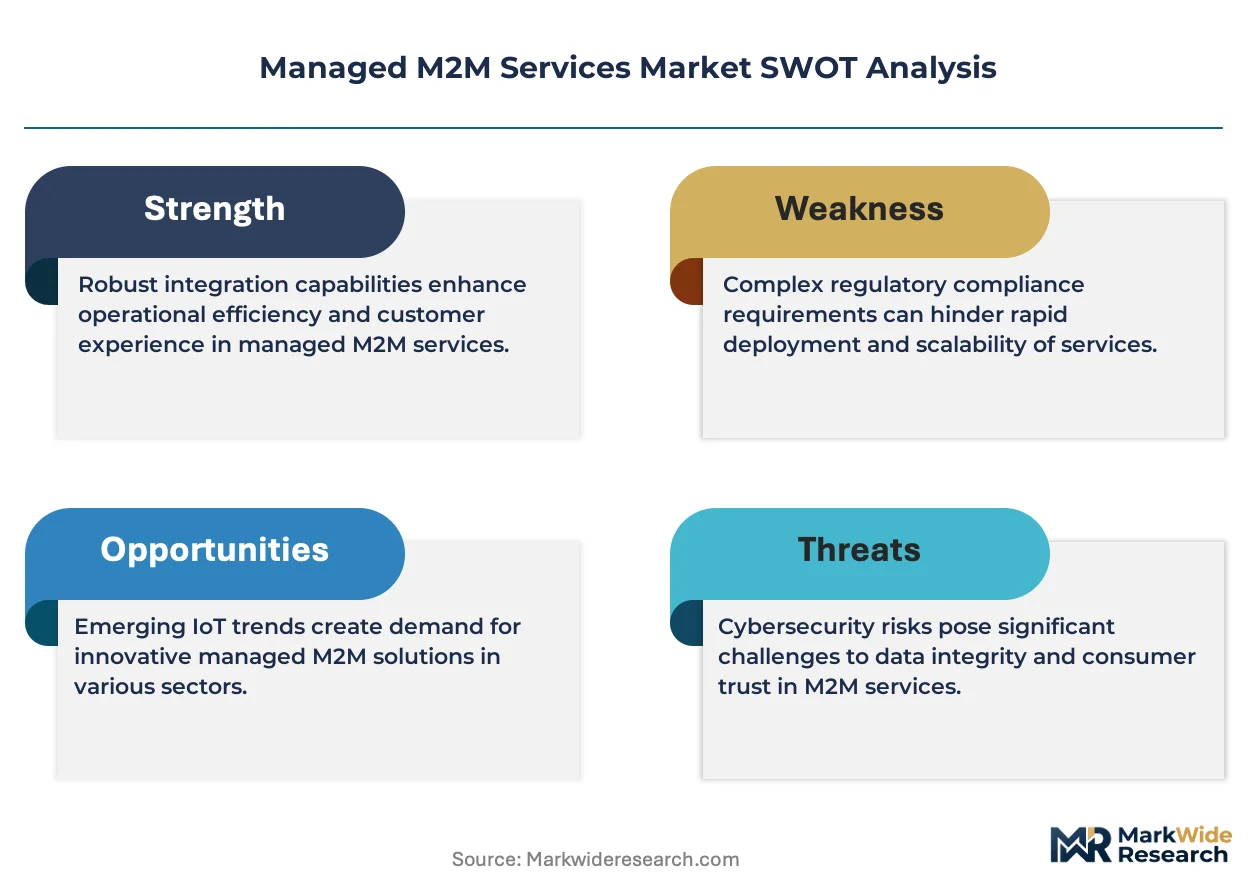
Capital-intensity divergence between network-owning carriers and software-layer specialists is collapsing as cloud-native platforms erode the infrastructure moat of legacy telecom operators. AT&T Inc. leverages its nationwide LTE and 5G spectrum holdings to dominate enterprise fleet telematics contracts. Verizon Communications Inc. sustains premium positioning through private network deployments for manufacturing clients. Cisco Systems Inc. differentiates via edge security orchestration layered over third-party connectivity.
Managed M2M services denote outsourced lifecycle administration of machine-to-machine communications encompassing SIM provisioning, firmware over-the-air updates, usage monitoring, and API-based integration with enterprise ERP systems; these functions typically operate over licensed cellular bands or unlicensed ISM spectrum with latency thresholds under 100 milliseconds for real-time control applications. Network management and security services currently anchor the largest revenue pools as enterprises outsource compliance burden, while data analytics segments exhibit the fastest expansion as predictive maintenance algorithms mature. Public cloud deployment models lead volume uptake among SMEs, though hybrid configurations capture the highest margins from large enterprises with legacy on-premises SCADA investments.
The Federal Communications Commission shapes US market access through spectrum allocation rules for CBRS and licensed cellular IoT, while the EU Cyber Resilience Act and GDPR jointly mandate encryption standards and data residency for cross-border device fleets. China's MIIT enforces GB-standard network access licenses that foreign platform providers must navigate through local partnerships. Stakeholders must weigh regulatory fragmentation against the operational efficiency of unified global connectivity orchestration platforms.
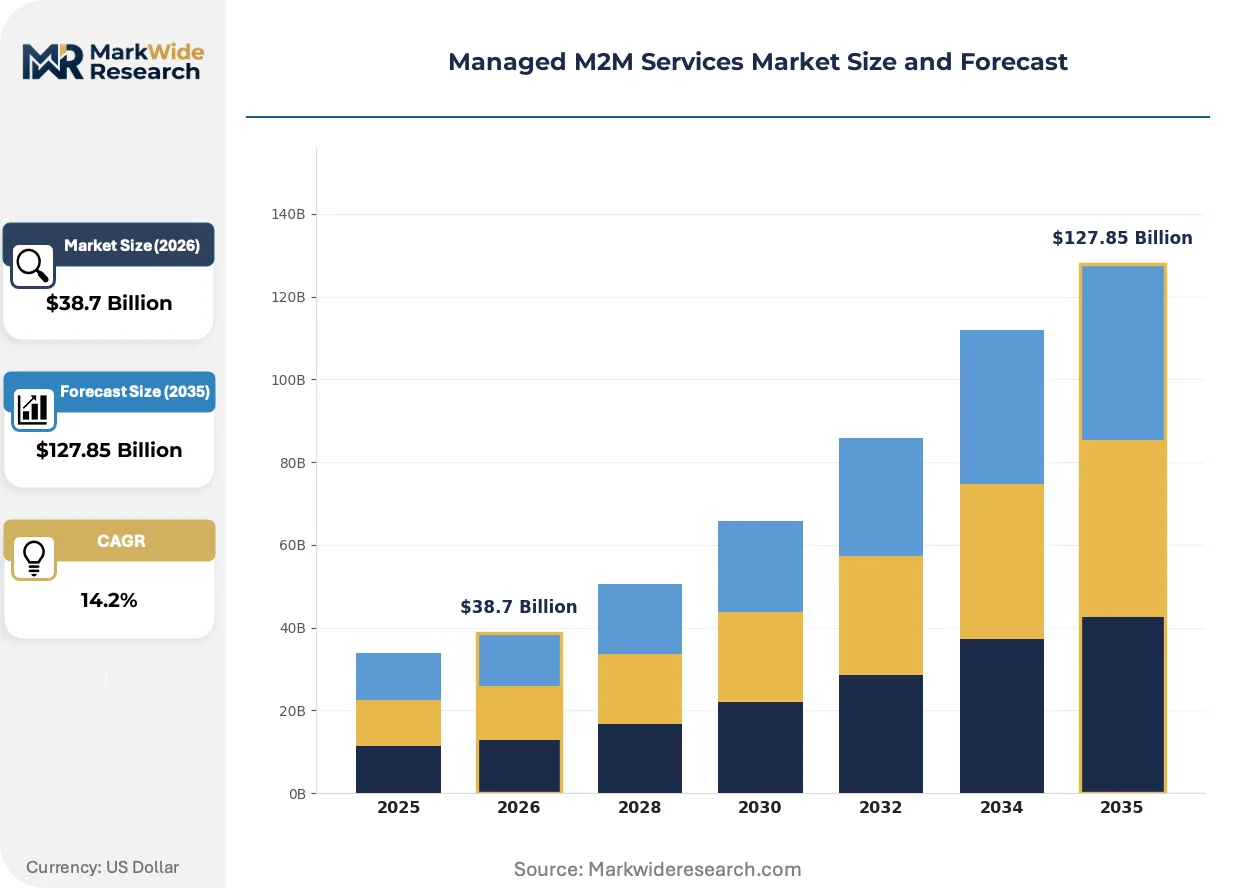
Market Dynamics
Cloud-native orchestration platforms are collapsing the traditional infrastructure moat that once separated network-owning carriers from software-layer specialists, forcing a fundamental repricing of connectivity services across enterprise segments.
Growth Catalysts
- Fleet logistics automation:LTE-M and NB-IoT module cost declines are accelerating deployment among freight operators managing cross-border vehicle fleets. This segment now anchors the fastest-expanding buyer category for managed connectivity contracts.
- EU Cyber Resilience Act:Mandatory security update obligations for connected device ecosystems are pushing manufacturers toward outsourced lifecycle management. Compliance outsourcing now drives enterprise procurement decisions.
- Predictive maintenance algorithms:Maturing machine-learning models for industrial asset monitoring are expanding data analytics segments beyond basic connectivity provisioning. Manufacturing clients now bundle analytics with connectivity subscriptions.
Market Restraints
- Cellular module supply concentration:Production of LTE-M and NB-IoT chipsets remains concentrated among a handful of Asian semiconductor foundries, exposing service providers to input cost volatility and allocation constraints.
- Cross-border data residency requirements:GDPR and China's data localization rules impose conflicting obligations on device fleets operating across jurisdictions, fragmenting platform architectures and inflating compliance overhead.
- Unlicensed spectrum interference:ISM band congestion in dense industrial zones degrades latency performance for real-time control applications, limiting deployment in precision automation settings.
Strategic Opportunities
- Brazilian industrial automation:Managed connectivity penetration in Brazilian manufacturing remains below German and Japanese benchmarks, creating whitespace for platform providers targeting sugar, pulp, and automotive supply chains.
- Edge security orchestration:Convergence of zero-trust architectures with cellular connectivity management is opening premium service tiers for critical infrastructure operators in energy and transportation.
- Hybrid cloud configurations:Large enterprises with legacy SCADA investments are migrating toward margin-rich hybrid deployments that bridge on-premises control systems with cloud-based analytics.
Industry Challenges
- Firmware engineering talent scarcity:Over-the-air update orchestration for heterogeneous device fleets requires specialized embedded systems expertise that remains concentrated among a narrow pool of practitioners.
- API integration complexity:Enterprise ERP system connectivity demands bespoke middleware development, extending deployment timelines and inflating professional services costs for managed M2M implementations.
- Multi-jurisdiction certification timelines:GB-standard licenses in China, FCC equipment authorizations in the US, and CE marking in Europe impose sequential validation requirements that delay global fleet rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Managed M2M Services Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Network Management, Device Monitoring, Data Analytics, Security Services Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Industry Vertical: Healthcare, Transportation, Manufacturing, Agriculture End User: SMEs, Large Enterprises, Government, Developers |
| Companies Covered | AT&T Inc., Verizon Communications Inc., Vodafone Group Plc, Deutsche Telekom AG, Cisco Systems Inc., Huawei Technologies Co. Ltd, Thales Group, Intel Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Managed M2M Services Market Strategic Shifts
Service delivery models are bifurcating between hyperscale cloud orchestration and specialized edge platforms, with buyer preferences hardening around latency performance and data sovereignty rather than connectivity price alone.
AI-driven anomaly detection layered over cellular connectivity streams is displacing scheduled maintenance routines in industrial asset management. Fleet operators and manufacturing clients are adopting predictive algorithms at accelerating velocity. This displacement is compressing traditional break-fix service contracts and rewiring vendor compensation toward uptime-guarantee structures.
The EU Cyber Resilience Act imposes mandatory vulnerability disclosure and patch timelines on all connected products sold in member states. Industrial device manufacturers must now embed lifecycle management capabilities from design phase through end-of-life. German automation suppliers are responding fastest, integrating managed connectivity into hardware offerings as a bundled subscription.
Enterprise procurement of M2M services is consolidating under centralized IT governance rather than distributed operational technology budgets. Manufacturing and logistics buyers are consolidating vendor relationships and demanding API-native platforms that integrate with existing enterprise software stacks. This consolidation is most visible in Japan, where keiretsu-affiliated manufacturers are standardizing on single-provider connectivity architectures.
Managed M2M Services Market Segmentation
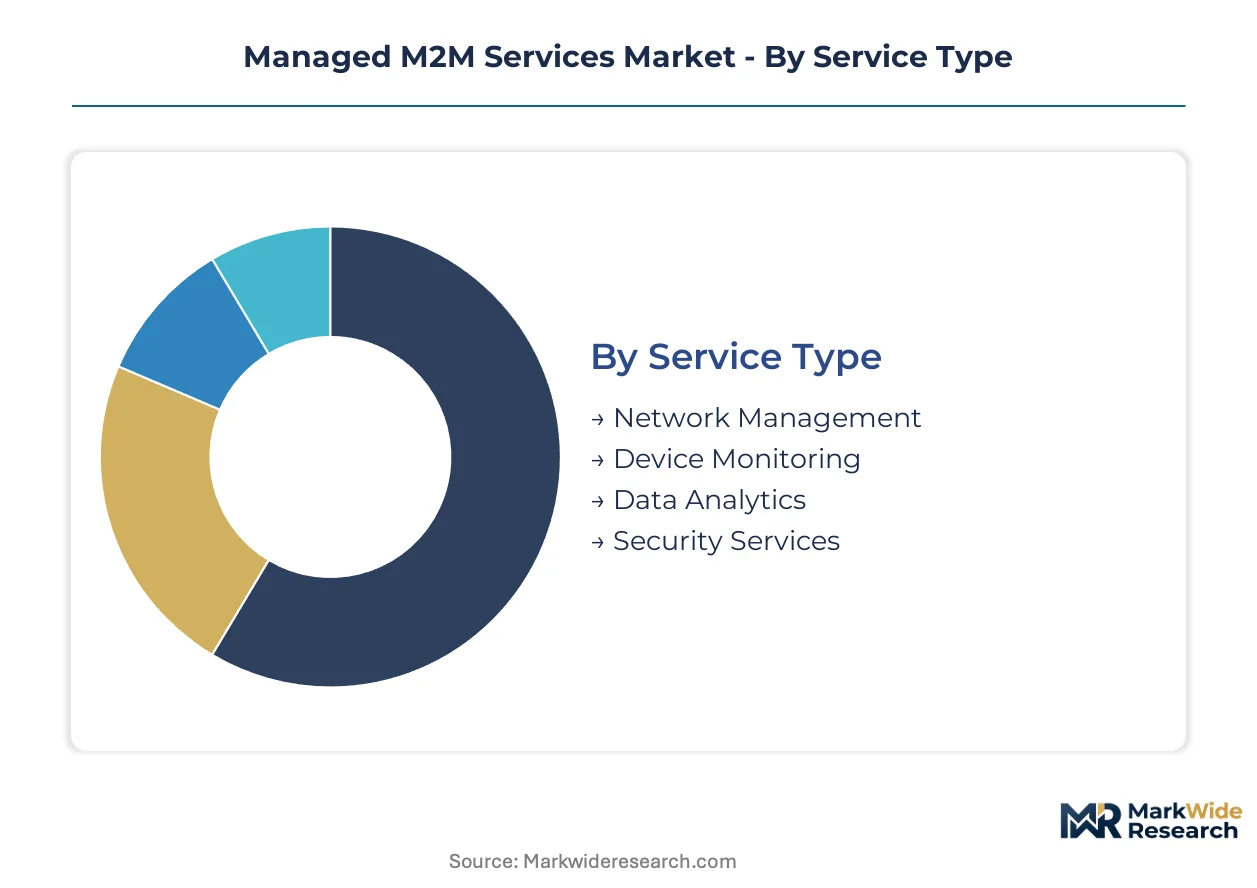
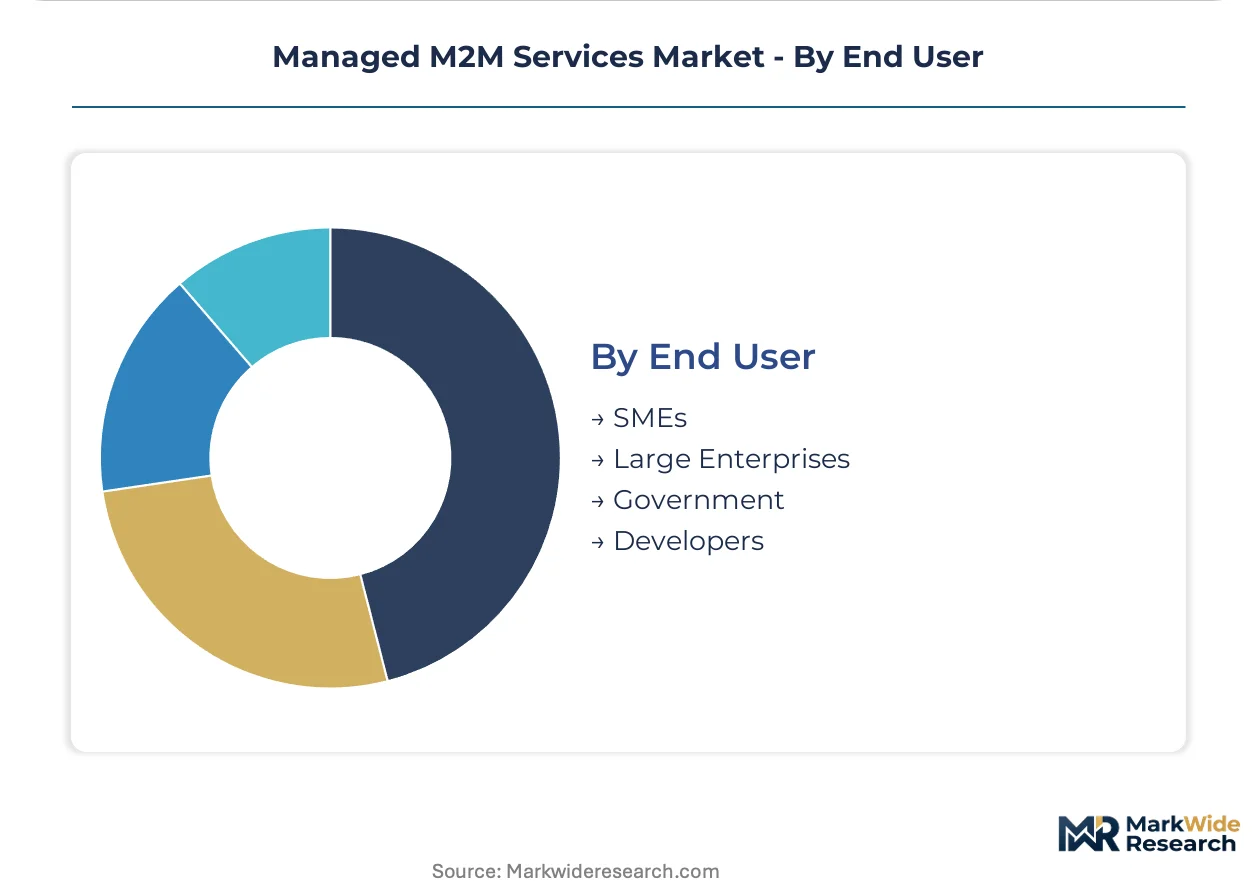
Managed M2M services fragment across four distinct dimensions that determine procurement patterns, margin structures, and vendor specialization. Channel strategy diverges sharply between standardized cloud offerings sold through digital marketplaces and complex hybrid deployments requiring direct enterprise sales engagement.
Service Type:
Channel mix varies by service complexity, with network management flowing through carrier direct sales while security services increasingly route through systems integrators and managed security service providers.
- Network Management:Lifecycle administration of cellular connectivity encompassing SIM provisioning, carrier switching, and usage monitoring across multi-operator environments. Demand concentrates among German automotive suppliers and Japanese keiretsu manufacturers seeking guaranteed latency under 100 milliseconds for production line robotics. Carrier-direct contracts dominate this segment due to spectrum licensing dependencies.
- Security Services:Encryption orchestration, certificate management, and zero-trust edge architectures layered over third-party connectivity. EU Cyber Resilience Act compliance obligations are accelerating procurement among industrial device OEMs selling into European markets. Systems integrators capture margin through bundled implementation services.
- Device Monitoring:Firmware over-the-air distribution, health telemetry aggregation, and remote diagnostics for heterogeneous device fleets.
- Data Analytics:Predictive maintenance algorithms and operational intelligence derived from machine telemetry streams.
By volume, network management leads. By growth pace, security services is climbing the fastest as regulatory mandates compound.
Deployment Model:
Cost tier stratification separates volume-focused public cloud offerings from margin-rich custom architectures serving regulated industries.
- Public Cloud:Multi-tenant SaaS platforms delivering standardized connectivity orchestration with API-native ERP integration. Brazilian sugar processors and Southeast Asian logistics operators drive volume uptake due to minimal capital requirements and rapid deployment timelines.
- Hybrid Cloud:Bridged architectures connecting on-premises SCADA systems with cloud-based analytics layers. German chemical manufacturers and Japanese precision equipment makers anchor demand, accepting premium pricing for data sovereignty guarantees and sub-50 millisecond control loop performance.
- Private Cloud:Dedicated infrastructure deployments for single-tenant isolation in critical infrastructure settings.
- On-Premises:Fully air-gapped installations serving defense, nuclear, and classified government applications with zero external connectivity.
Public cloud captures the widest deployment base. Hybrid configurations command the steepest expansion trajectory among Fortune 500 industrial clients.
Industry Vertical:
Application-specific requirements dictate vendor selection, with transportation prioritizing cross-border roaming capabilities and manufacturing demanding deterministic latency.
- Transportation:Fleet telematics, cold-chain monitoring, and cross-border freight optimization across multi-jurisdictional corridors. US long-haul operators and Brazilian pulp exporters are expanding LTE-M deployments as module costs decline below critical thresholds.
- Manufacturing:Industrial automation, predictive maintenance, and quality control systems requiring real-time machine-to-machine coordination. German automotive plants and Japanese electronics fabs represent the most intensive deployment settings globally.
- Healthcare:Remote patient monitoring, medical device fleet management, and HIPAA-compliant data transmission for connected therapeutics.
- Agriculture:Precision irrigation, livestock tracking, and yield optimization across dispersed rural coverage zones.
Transportation shows the broadest geographic spread. Manufacturing exhibits the densest revenue concentration per enterprise account.
End User:
Customer type determines sales motion complexity, with developers consuming through self-service APIs while government procurement requires extended certification cycles.
- Large Enterprises:Centralized IT governance driving consolidated vendor relationships and multi-year managed service contracts. Japanese keiretsu affiliates and German Mittelstand exporters are standardizing on single-provider architectures to reduce integration overhead.
- SMEs:Digital-native logistics operators and agricultural cooperatives procuring through cloud marketplaces with minimal professional services attachment.
- Government:Critical infrastructure operators in energy and transportation requiring FedRAMP or equivalent security certifications.
- Developers:IoT platform engineers and system integrators building vertical applications atop connectivity infrastructure.
Large enterprises generate the highest contract values. SMEs are expanding most quickly as self-service platforms lower adoption barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing economies generate outsized demand for managed M2M services as cross-border fleet coordination and predictive maintenance become competitive necessities. Import-dependent markets concentrate procurement around compliance-heavy security services. The regulatory patchwork across jurisdictions fragments platform architectures while creating arbitrage opportunities for localized service providers.
Germany
Automotive suppliers and Mittelstand exporters drive dense deployment of industrial automation connectivity. The EU Cyber Resilience Act imposes mandatory security update obligations that push manufacturers toward outsourced lifecycle management. Bavaria's automotive cluster around Munich and Ingolstadt anchors the highest penetration of private network deployments for production line robotics.
United States
Long-haul freight operators and energy infrastructure operators constitute the primary demand base for fleet telematics and critical asset monitoring. The FCC shapes market access through spectrum allocation rules for CBRS and licensed cellular IoT bands. The Gulf Coast petrochemical corridor and Permian Basin energy fields concentrate deployment of edge security orchestration for remote infrastructure.
Japan
Keiretsu-affiliated electronics and precision equipment manufacturers standardize on single-provider connectivity architectures to reduce integration overhead. METI industrial policy encourages predictive maintenance adoption through subsidized IoT platform trials. The Chubu region around Nagoya hosts the densest concentration of hybrid cloud deployments bridging legacy SCADA with cloud analytics.
Brazil
Sugar processors, pulp exporters, and automotive supply chains are expanding LTE-M deployments as module costs fall below critical adoption thresholds. ANVISA and national data protection frameworks impose localization requirements that favor domestic platform partnerships. São Paulo state's industrial belt concentrates managed connectivity penetration in manufacturing settings.
China
Industrial automation and smart manufacturing initiatives drive volume demand for connectivity orchestration platforms. MIIT enforces GB-standard network access licenses that foreign providers must navigate through local joint ventures. The Yangtze River Delta manufacturing cluster around Shanghai exhibits the most intensive deployment of cloud-native M2M platforms.
Managed M2M Services Market Competitive Environment
Concentration sits with network-owning carriers that leverage spectrum licensing advantages to anchor enterprise connectivity contracts. The market structure bifurcates between infrastructure-heavy telecom operators and software-layer specialists competing on orchestration capabilities. Three archetypes dominate: nationwide carriers with licensed spectrum holdings, equipment vendors extending into service layers, and cloud-native platform specialists. Competitive moves center on private network deployment partnerships and edge security capability acquisitions.
Within the carrier archetype, AT&T Inc. and Verizon Communications Inc. occupy positions shaped by nationwide LTE and 5G infrastructure. Cisco Systems Inc. exemplifies the equipment-vendor extension model, layering security orchestration over third-party connectivity. Deutsche Telekom AG represents the European carrier archetype with industrial automation focus. These three anchors illustrate how geographic spectrum control, security software integration, and regional manufacturing specialization create distinct competitive positions.
| Leading Market Players |
|---|
| AT&T Inc. |
| Verizon Communications Inc. |
| Vodafone Group Plc |
| Deutsche Telekom AG |
| Cisco Systems Inc. |
| Huawei Technologies Co. Ltd |
| Thales Group |
| Intel Corporation |
| IBM |
| Others |
Value Chain & Pricing Dynamics
Multi-year managed connectivity contracts lock in both module supply access and price predictability for fleet operators navigating EU Cyber Resilience Act compliance timelines. These agreements bundle SIM provisioning, firmware update orchestration, and API integration into fixed-rate structures that insulate buyers from LTE-M chipset cost volatility.
Pricing Analysis
Industrial OEM buyers anchor subscription-based pricing that stratifies across premium, standard, and economy tiers tied to latency guarantees and security certification levels. German automotive suppliers and Japanese keiretsu manufacturers accept premium positioning for sub-50 millisecond control loops and zero-trust edge architectures. Cost compression in the standard tier intensifies as cloud-native platforms erode carrier infrastructure moats. SME logistics operators in Brazil and Southeast Asia exhibit highest price sensitivity, driving volume procurement through self-service digital marketplaces.
Supply Chain Analysis
Taiwanese and South Korean semiconductor foundries control LTE-M and NB-IoT chipset fabrication, creating single-source vulnerability for module vendors serving European and North American markets. Managed M2M service providers draw from Chinese module assembly capacity, Japanese precision components, and German industrial automation hardware. Tariff exposure on cellular modems fragments platform architectures across jurisdictions. Distribution runs through carrier-direct sales for network management contracts and systems integrator channels for security service bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering expertise for over-the-air update orchestration remains concentrated among a narrow practitioner pool, constraining platform scaling and inflating professional services costs. This capability gap shapes competitive positioning across the managed connectivity value chain.
For Market Incumbents: Shield spectrum-licensing advantages by accelerating private 5G network deployments for manufacturing clients before cloud-native specialists match edge orchestration capabilities. Deepen backward integration into module firmware development to reduce dependency on Asian semiconductor allocation cycles. Prioritize certification investment for EU Cyber Resilience Act compliance tooling. For New Entrants and Emerging Players: API-native ERP integration gaps in the mid-market manufacturing segment offer white-space opportunity where legacy carriers burden clients with bespoke middleware timelines. Brazilian sugar processors and pulp exporters represent the most penetrable geography given sub-scale incumbent presence. Pursue channel partnerships with regional systems integrators already embedded in industrial automation upgrade cycles. For Investors and Strategic Acquirers: Capital is best deployed toward edge security orchestration specialists with zero-trust architectures already validated in energy and transportation critical infrastructure. Long-term viability favors platforms bridging hybrid cloud configurations for Fortune 500 manufacturers with legacy SCADA investments. Monitor FCC CBRS spectrum allocation rulings as inflection signal for private network deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Security Capability Acquisition | Zero-trust architectures layered over cellular connectivity open premium tiers for critical infrastructure operators. |
| Hybrid Cloud Platform Integration | Bridged SCADA-cloud deployments capture highest margins from German chemical and Japanese precision equipment manufacturers. |
| Private 5G Network Deployment | Licensed spectrum deployments for production line robotics lock in multi-year carrier contracts with guaranteed latency. |
| API-Native ERP Partnership | Pre-built middleware connectors with SAP and Oracle reduce deployment timelines for centralized IT governance buyers. |
| Brazilian Industrial Automation Expansion | São Paulo state manufacturing belt offers whitespace below German and Japanese penetration benchmarks. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with managed connectivity platform executives, IoT solution architects, and industrial automation procurement leads at German Mittelstand exporters and Japanese keiretsu affiliates; and secondary validation through FCC spectrum allocation records, EU Cyber Resilience Act implementation guidance, MIIT GB-standard filings, and carrier capex disclosures. Bottom-up triangulation across module shipment estimates and top-down reconciliation against enterprise connectivity contract values anchored market sizing.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning service type complexity, deployment model architecture, industry vertical latency requirements, and end-user governance structure. CAGRs derived from elasticity-adjusted uptake curves for fleet telematics and predictive maintenance algorithm adoption. Forecast inputs incorporated LTE-M module cost decline trajectories and cross-border data residency compliance fragmentation.
Underlying assumptions cover sustained semiconductor foundry allocation stability and regulatory enforcement timelines for EU Cyber Resilience Act patch obligations, with deviation risk concentrated in multi-jurisdiction certification delays and unlicensed spectrum congestion in dense industrial zones. Practitioners should keep alternative scenarios live as CBRS spectrum auction outcomes and Brazil's ANVISA localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Rich Communication Services (RCS) Market
Telecommunications
Voice Communication Control System Market
Telecommunications
North America Underwater Communication Systems Market
Telecommunications
Free Space Optics (FSO) Communication Market
Telecommunications
Machine to Machine (M2M) Services Market
Telecommunications
Austria ICT Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Global 4G LTE Market
Telecommunications
Asia-Pacific IPTV Market
Telecommunications
Indonesia Communication Services Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Global LTE Market
Telecommunications
Luxembourg Telecom Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
5G in Defense Market