
 Saudi Arabia Digital Transformation Market | 2026-2036
Saudi Arabia Digital Transformation Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Digital Transformation Market Insights
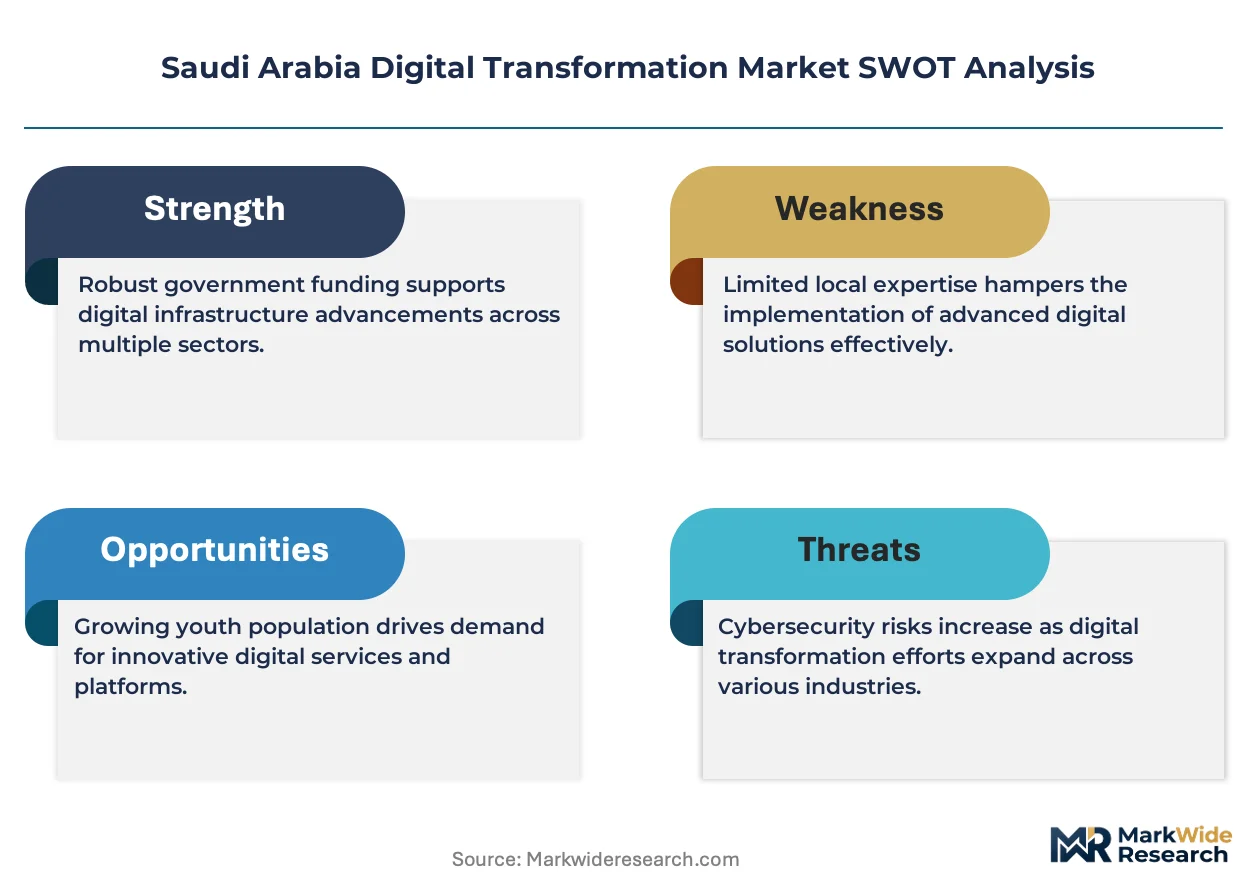
ISO 27001 certification cycles is unwinding the competitive field, forcing smaller systems integrators into costly compliance overhauls. Saudi Telecom Company anchors the infrastructure layer through its data center footprint across Riyadh, Jeddah, and Dammam. Microsoft leverages its sovereign cloud partnership with the kingdom to control sensitive government workloads. IBM competes on hybrid cloud consulting strength, particularly in financial services modernization.
Saudi Arabia digital transformation encompasses the integration of cloud computing, artificial intelligence, and IoT architectures into legacy enterprise systems to automate workflows, enhance data-driven decision-making, and deliver citizen-centric services. The technical stack typically involves API-first middleware, containerized microservices, and zero-trust security frameworks operating at sub-50 millisecond latency thresholds for real-time analytics. Cloud services command the largest value pool as government entities migrate from on-premises data centers to hyperscale environments under NTP targets. Artificial Intelligence segments within the technology dimension attract disproportionate R&D allocation, especially for Arabic natural language processing and computer vision applications in healthcare diagnostics. System integration services remain structurally fragmented, with margin compression among mid-tier vendors unable to scale certified engineering benches.
SAMA operational resilience rules and NCA cybersecurity standards create dual compliance burdens that filter out uncertified foreign entrants. SFDA data localization requirements for healthcare records further segment the vendor landscape by mandating in-kingdom server infrastructure. The National Data Management Office classification scheme adds a third regulatory layer governing cross-border data flows. Stakeholders must weigh sovereign cloud commitments against hybrid flexibility as procurement rules tighten around domestic content requirements.
Market Dynamics
The Saudi Arabia digital transformation market is being fundamentally restructured by sovereign cloud mandates under the National Transformation Program, which compel government entities to migrate sensitive workloads to in-kingdom data centers and disqualify non-compliant vendors from public procurement cycles.
Growth Catalysts
- National Transformation Program cloud mandates:Government agencies in Riyadh must migrate 80% of eligible systems to sovereign cloud environments by 2030, creating guaranteed demand for certified infrastructure providers.
- Edge computing in Jeddah's smart port cluster:Real-time cargo tracking and automated customs clearance require sub-50 millisecond latency, driving concentrated procurement of distributed compute nodes.
- SFDA data localization requirements:Healthcare providers must store patient records on domestic servers, segmenting the vendor landscape toward local infrastructure operators.
Market Restraints
- ISO 27001 certification cost barriers:Smaller systems integrators face six-figure compliance investments that compress margins and force market exit.
- NCA cybersecurity standard complexity:Dual compliance burdens with SAMA operational resilience rules create documentation overhead that filters out uncertified foreign entrants.
- Specialized talent scarcity:Arabic NLP engineering and zero-trust architecture skills command premium wages that inflate project delivery costs.
Strategic Opportunities
- Eastern Province industrial IoT penetration:Petrochemical facilities in Jubail Industrial City remain underdigitized, offering first-mover advantage for predictive maintenance platforms.
- SAMA open banking API frameworks:Regulatory mandates for financial data interoperability create white space for middleware specialists.
- Convergence of computer vision and edge AI:Healthcare diagnostics in Riyadh's hospital networks require real-time radiology analysis, merging two technology stacks into unified procurement decisions.
Industry Challenges
- Legacy ERP integration complexity:Government ministries operate decades-old Oracle and SAP instances that resist containerized microservices migration without custom API development.
- NCA certification timeline compression:Security clearance cycles for foreign engineers extend project kickoffs by four to six months, straining client relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Digital Transformation Market |
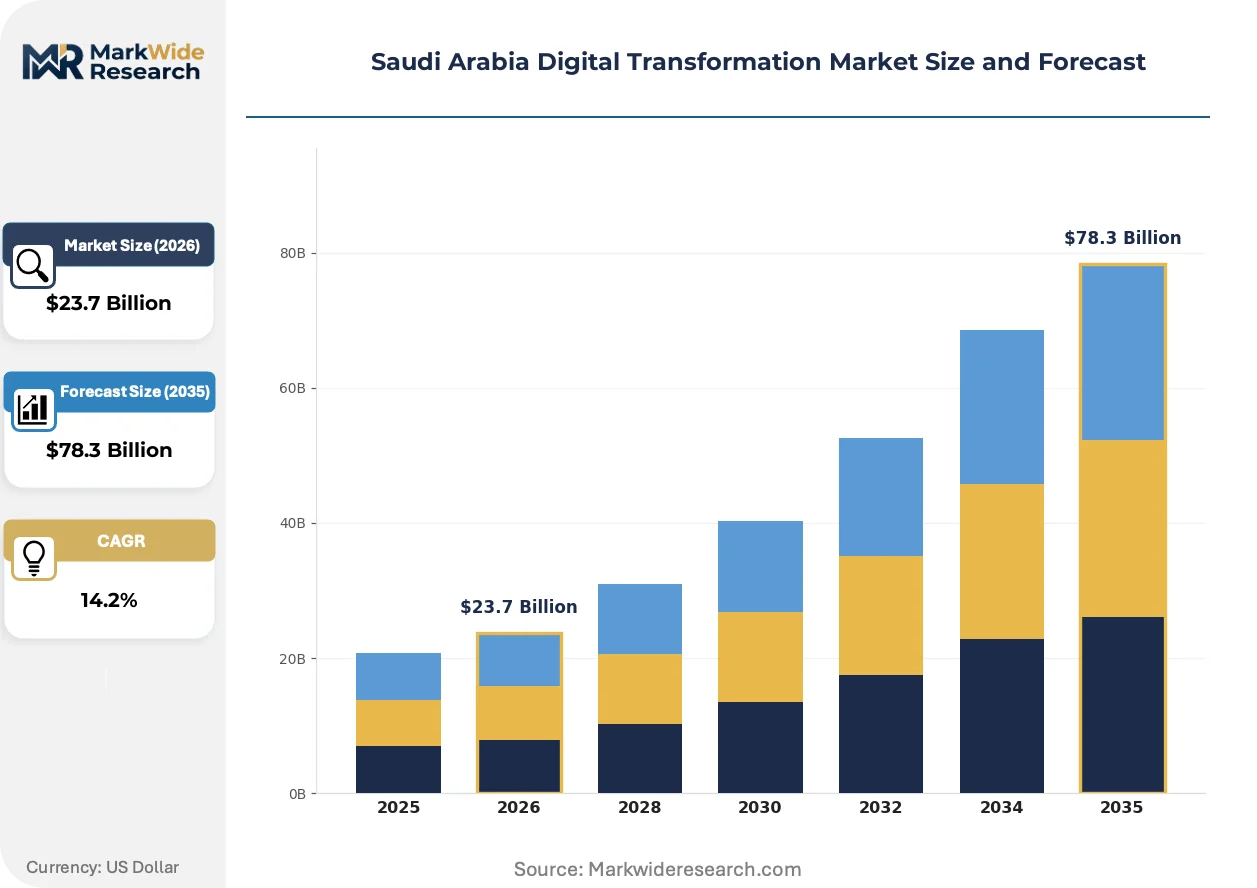
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, System Integration, Cloud Services, IT Infrastructure Technology: Artificial Intelligence, Big Data, IoT, Blockchain End User: Healthcare, Education, Retail, Government Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Managed Services |
| Companies Covered | Saudi Telecom Company (STC), Solutions by stc, Saudi Business Machines, Arabic Computer Systems, Microsoft, IBM, Oracle, SAP, Accenture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Digital Transformation Market Trends and Innovations
Sovereign cloud architectures are actively fragmenting competitive positioning in the kingdom, as hyperscale providers restructure offerings around domestic data residency requirements and local partners gain structural advantage in public sector bidding.
Containerized microservices is bifurcating the integration services market. Financial institutions in Riyadh are adopting Kubernetes-orchestrated workloads at accelerated pace. This technology shift is compressing margins for traditional monolithic system integrators while elevating DevOps-certified specialists.
SAMA cybersecurity standards and NCA operational resilience rules are tightening vendor qualification thresholds. Banks must demonstrate real-time threat detection capabilities and automated incident response protocols. The commercial banking segment is responding by consolidating supplier relationships around dual-certified domestic partners.
Public sector procurement is consolidating around outcome-based engagement models. Government entities are replacing time-and-materials contracts with fixed-outcome agreements tied to citizen service delivery metrics. This pattern is most visible in Riyadh's smart city initiatives, where payment terms link directly to measurable workflow automation gains.
Saudi Arabia Digital Transformation Market Segmentation
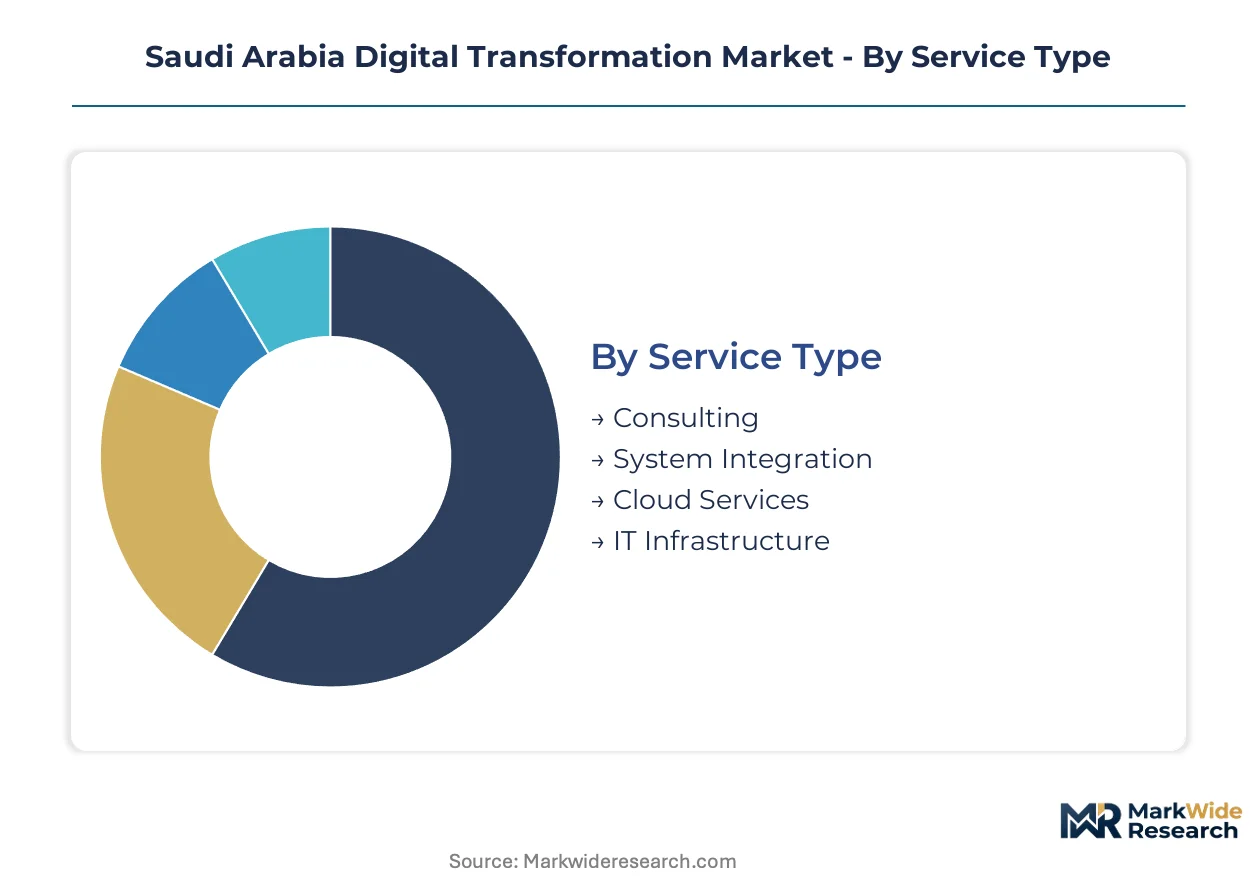
Segmentation in the Saudi Arabia digital transformation market reveals how procurement channels bifurcate between government-mandated sovereign cloud pathways and enterprise-driven hybrid adoption. Understanding these divides exposes where vendor qualification requirements concentrate and which technology stacks attract disproportionate investment under National Transformation Program targets.
Service Type:
Channel flow splits sharply: government contracts route through certified system integrators, while private enterprises increasingly self-procure cloud services direct from hyperscale providers.
- Consulting:Strategic advisory engagements dominate early-phase digital roadmapping for ministries and state-owned enterprises. Riyadh-based government entities drive demand for compliance-heavy transformation planning under NTP mandates.
- System Integration:Legacy ERP consolidation and API middleware development constitute the technical core. SFDA and SAMA certification requirements filter vendor participation toward dual-certified domestic partners with NCA security clearance.
- Cloud Services:Sovereign cloud migrations absorb the largest procurement volume as agencies shift from on-premises infrastructure.
- IT Infrastructure:Edge compute nodes and data center builds concentrate in Jeddah's smart port cluster and Eastern Province industrial zones.
By volume, Cloud Services leads. By growth pace, System Integration is ahead.
Technology:
Cost tiers separate commodity analytics from premium AI workloads, with Arabic NLP capabilities commanding significant pricing premiums.
- Artificial Intelligence:Computer vision for healthcare diagnostics and Arabic natural language processing attract concentrated R&D allocation. Riyadh hospital networks require real-time radiology analysis at sub-50 millisecond latency.
- Big Data:Predictive analytics platforms process petrochemical sensor streams and citizen service delivery metrics. Jubail Industrial City facilities generate unmonitored operational data ripe for first-mover platform deployment.
- IoT:Industrial sensor networks and smart city device management scale across municipal infrastructure.
- Blockchain:Supply chain traceability and financial settlement applications remain nascent but SAMA-supervised.
Artificial Intelligence captures the steepest expansion trajectory as sovereign data residency enables sensitive model training on domestic patient and citizen records.
End User:
Application maturity varies dramatically: government entities operate under forced migration timelines while healthcare and retail follow voluntary adoption curves.
- Healthcare:SFDA data localization mandates require domestic server infrastructure for patient records. Diagnostic imaging AI and electronic health record modernization absorb the bulk of provider technology budgets.
- Government:National Transformation Program targets compel 80% cloud migration of eligible systems. Procurement consolidates around outcome-based contracts tied to measurable workflow automation gains.
- Education:University digital campuses and vocational training platforms expand under Vision 2030 human capital objectives.
- Retail:E-commerce logistics and customer analytics drive private-sector cloud adoption outside sovereign mandates.
Healthcare providers face the tightest regulatory constraints. Government entities offer the largest contract scale.
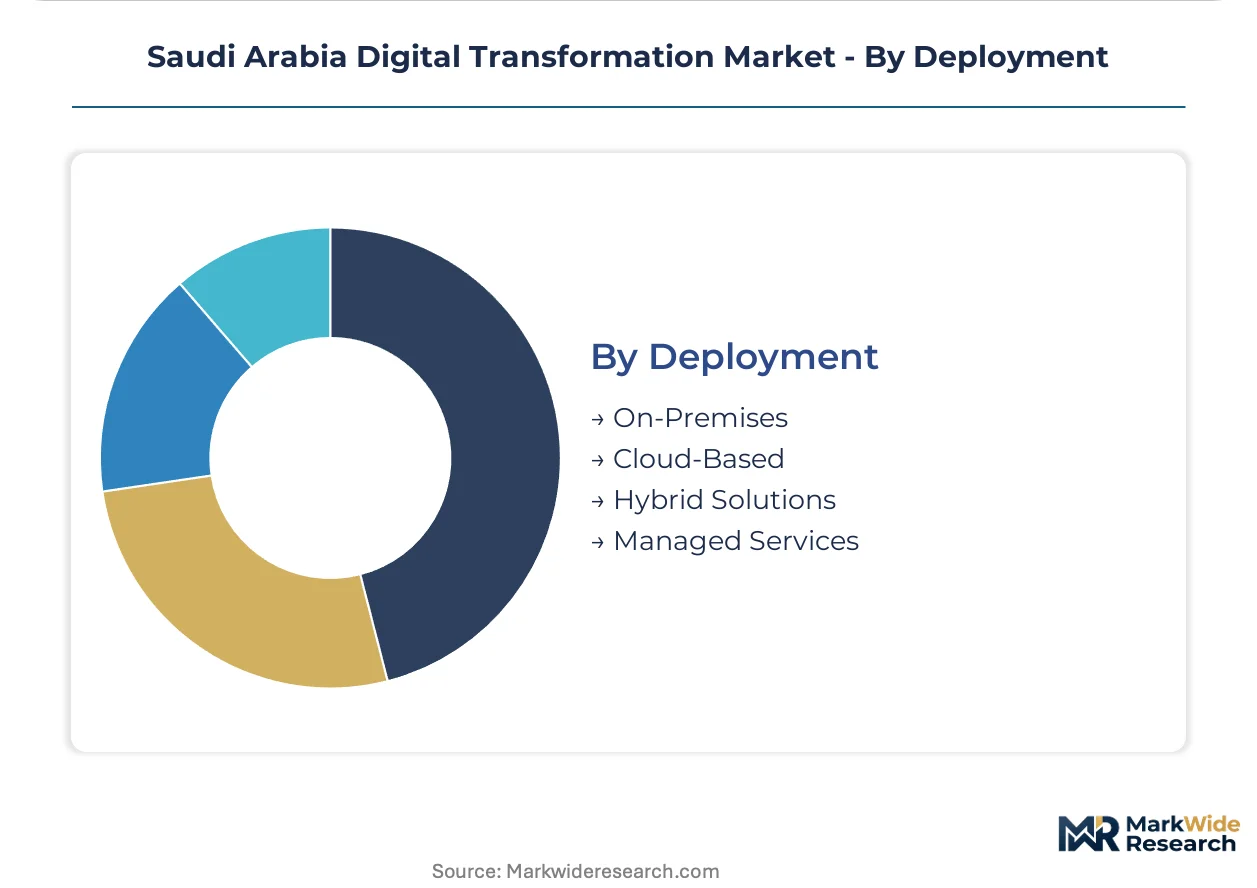
Deployment:
Customer type determines architecture choice: ministries default to managed sovereign clouds, while petrochemical firms favor hybrid flexibility.
- Cloud-Based:Hyperscale environments with domestic data residency dominate public sector procurement. Microsoft and Amazon Web Services compete through local partner structures to meet NCA cybersecurity standards.
- Hybrid Solutions:Financial institutions in Riyadh maintain sensitive core banking on-premises while bursting analytics workloads to cloud. SAMA operational resilience rules mandate this architectural split.
- On-Premises:Legacy Oracle and SAP instances persist in ministries resistant to full containerization.
- Managed Services:Outsourced security operations and DevOps functions gain traction among mid-tier enterprises lacking certified engineering benches.
Hybrid Solutions deliver the highest project margins. Cloud-Based deployments are climbing fastest as sovereign certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National Transformation Program mandates steer procurement concentration toward Riyadh, Jeddah, and the Eastern Province. Government cloud migration timelines and industrial zone digitization create geographically uneven demand patterns across the kingdom.
Riyadh
Government ministries and state-owned enterprises drive sovereign cloud procurement under NTP targets. SAMA operational resilience rules and NCA cybersecurity standards filter vendor participation toward dual-certified domestic partners. King Abdullah Financial District hosts concentrated financial services modernization projects.
Eastern Province
Petrochemical facilities in Jubail Industrial City generate unmonitored operational data ripe for predictive maintenance platform deployment. SFDA data localization requirements for healthcare records segment vendor selection toward local infrastructure operators. Ras Al-Khair industrial zone attracts edge computing investments for real-time process control.
Jeddah
Smart port cluster operations demand sub-50 millisecond latency for automated customs clearance and real-time cargo tracking. Edge computing nodes concentrate procurement demand for distributed compute infrastructure. King Abdulaziz International Airport logistics corridors anchor IoT sensor network deployments.
Western Region
Religious tourism digitization and municipal smart city initiatives expand cloud service consumption outside sovereign mandates. Makkah and Madinah pilgrimage infrastructure requires real-time crowd analytics and automated service delivery systems. Taif emerging technology zones attract mid-tier systems integrators seeking margin relief from Riyadh certification intensity.
NEOM Northwest
Greenfield city construction enables native cloud-first architecture without legacy ERP integration burdens. Cognitive city platforms integrate computer vision and Arabic NLP from inception rather than retrofit. The Line linear urban development concentrates experimental AI procurement outside standard government procurement cycles.
Saudi Arabia Digital Transformation Market Competitive Landscape
Listed leaders compete with private specialists across certification-heavy infrastructure segments. The vendor base stratifies into three tiers: hyperscale cloud providers with sovereign partnerships, domestic telecom-affiliated integrators with NCA clearance, and mid-tier engineering shops facing margin compression from ISO 27001 compliance costs. Strategic archetypes include certification-anchored incumbents, cloud-native entrants, and legacy ERP maintenance specialists. Competitive moves center on local partnership structures to meet domestic content requirements and outcome-based contract restructuring to align with public sector procurement reform.
Within the domestic infrastructure tier, Saudi Telecom Company and Solutions by stc anchor sovereign cloud delivery through established data center footprints. Microsoft occupies a position as the foreign hyperscale provider with formalized kingdom partnerships for sensitive government workloads. IBM sits within the hybrid consulting archetype, particularly in financial services modernization where SAMA rules mandate architectural flexibility between on-premises core systems and cloud analytics bursting.
| Leading Market Players |
|---|
| Saudi Telecom Company (STC) |
| Solutions by stc |
| Saudi Business Machines |
| Arabic Computer Systems |
| Microsoft |
| IBM |
| Oracle |
| SAP |
| Accenture |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day certification cycles for ISO 27001 and NCA cybersecurity clearance concentrate vendor pricing power among dual-certified domestic partners while compressing margins for mid-tier engineering shops lacking pre-qualified engineering benches.
Pricing Analysis
Certification level creates the primary spread between premium sovereign-cloud providers and commodity integration vendors. Project-based contracting dominates public sector procurement, with outcome-based payment terms replacing time-and-materials structures. Price differentiation hinges on NCA security clearance status and Arabic NLP engineering capability, both commanding significant premiums. Pricing pressure intensifies in system integration as containerized microservices adoption compresses margins for traditional monolithic vendors. Mid-tier domestic integrators exhibit highest price sensitivity due to six-figure compliance investments, while hyperscale cloud providers with sovereign partnerships maintain pricing discipline.
Supply Chain Analysis
United States and Ireland anchor hyperscale cloud infrastructure supply through Microsoft and Amazon Web Services sovereign partnerships with kingdom entities. Taiwan and South Korea feed semiconductor dependencies for edge computing nodes deployed across Jeddah's smart port cluster. Supply chain risk centers on single-source vulnerability for Arabic NLP training data and specialized zero-trust architecture talent. Distribution runs through certified system integrators with NCA clearance for government contracts, while private enterprises increasingly self-procure direct from hyperscale providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hyperscale cloud providers with established sovereign partnerships threaten to displace traditional system integrators as government entities consolidate procurement around outcome-based managed services.
For Market Incumbents: Fortify certification moats by accelerating NCA cybersecurity and ISO 27001 renewal cycles ahead of 2030 cloud migration deadlines. Deepen vertical integration into Arabic NLP model training and edge computing hardware distribution to defend against hyperscale encroachment into high-margin consulting engagements.
For New Entrants and Emerging Players: Lead with DevOps-certified system integration targeting Jubail Industrial City's predictive maintenance white space, where petrochemical facilities remain underdigitized. SAMA open banking API frameworks offer a penetrable entry point for middleware specialists lacking legacy government clearance.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because sovereign cloud mandates and data localization requirements structurally advantage domestic partners with NCA clearance. Target acquisition profiles center on mid-tier integrators possessing certified engineering benches and established SFDA healthcare relationships. The signal to watch is compression in government contract award timelines as outcome-based procurement matures.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Microsoft's kingdom alliance secures sensitive government workload access against non-compliant foreign rivals. |
| Certification Acceleration | Dual NCA and ISO 27001 clearance filters competitive field toward pre-qualified domestic integrators. |
| Edge Computing Deployment | Jeddah smart port cluster demands sub-50 millisecond latency infrastructure from distributed compute specialists. |
| Arabic NLP Development | Healthcare diagnostics and citizen service automation require sovereign data residency for model training. |
| Outcome-Based Contracting | Riyadh government entities link payment terms to measurable workflow automation gains under NTP targets. |
Research Methodology
The analysis maps cloud services, system integration, artificial intelligence, and IoT segments, each validated through primary interviews with government procurement officers, hyperscale cloud platform engineers, NCA-certified system integrators, and SAMA compliance leads. Secondary validation draws from SEC filings of listed technology providers, Saudi Vision 2030 progress disclosures, hyperscaler sovereign cloud partnership announcements, and customs data on edge computing hardware imports. Bottom-up project pipeline aggregation and top-down macroeconomic scaling triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, technology stack, deployment architecture, end-user industry, and regional procurement cluster. CAGRs derive from trend extrapolation of government cloud migration timelines, industrial IoT penetration curves, and regulatory compliance cost trajectories. Forecast inputs incorporate NTP target achievement rates and SFDA data localization enforcement patterns.
Forecasts assume regulatory continuity in SAMA operational resilience rules and NCA cybersecurity standards; material policy shifts would require re-modeling. Specific risks include accelerated hyperscale provider market entry, talent scarcity inflation in zero-trust architecture, and legacy ERP integration complexity exceeding projected timelines. Recalibration cycles align with material shifts in sovereign cloud certification pathways and government procurement reform implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Transformation
Global Digital Workplace Transformation Service Market
Digital Transformation
United States Digital Transformation Market
Digital Transformation
Europe Digital Transformation Market
Digital Transformation
Latin America Digital Transformation Market
Digital Transformation
Poland Digital Transformation Market
Digital Transformation
India Digital Transformation Market
Digital Transformation
Digital Transformation Market
Digital Transformation
Spain Digital Transformation Market
Digital Transformation
Malaysia Digital Transformation Market
Digital Transformation
Israel Digital Transformation Market
Digital Transformation
Mexico Digital Transformation Market
Digital Transformation
Middle East Digital Transformation Market
Digital Transformation
UK Digital Transformation Market
Digital Transformation
Contact Center Transformation Market
Digital Transformation
Digital Transformation Consulting Market
Digital Transformation
Automotive Digital Transformation Market