
 South Africa Telecom Market | 2026-2036
South Africa Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Telecom Market Outlook
South Africa's undersea cable landing capacity is restructuring as new fiber routes reach the Western Cape. MTN South Africa leverages its 5G spectrum position to extend enterprise coverage across Gauteng's mining belt. Vodacom South Africa anchors consumer mobile revenue through its financial services integration. Telkom SA SOC Limited competes in fixed-line infrastructure by controlling the largest copper and fiber access network in secondary cities.
South Africa Telecom encompasses voice, data, and internet services delivered through wireless and wireline infrastructure operating across frequency bands from 700 MHz to 3.5 GHz and fiber optic cables with throughput exceeding 100 Gbps per strand. The sector enables enterprise digitalization, consumer connectivity, and government service delivery across a country spanning 1.2 million square kilometers with uneven population density. Mobile Services dominates revenue generation through prepaid and contract subscriber bases exceeding ninety million connections. 5G technology represents the fastest-expanding segment as operators deploy mid-band spectrum in metropolitan zones. Enterprise end users command premium pricing through dedicated leased lines and managed service contracts.
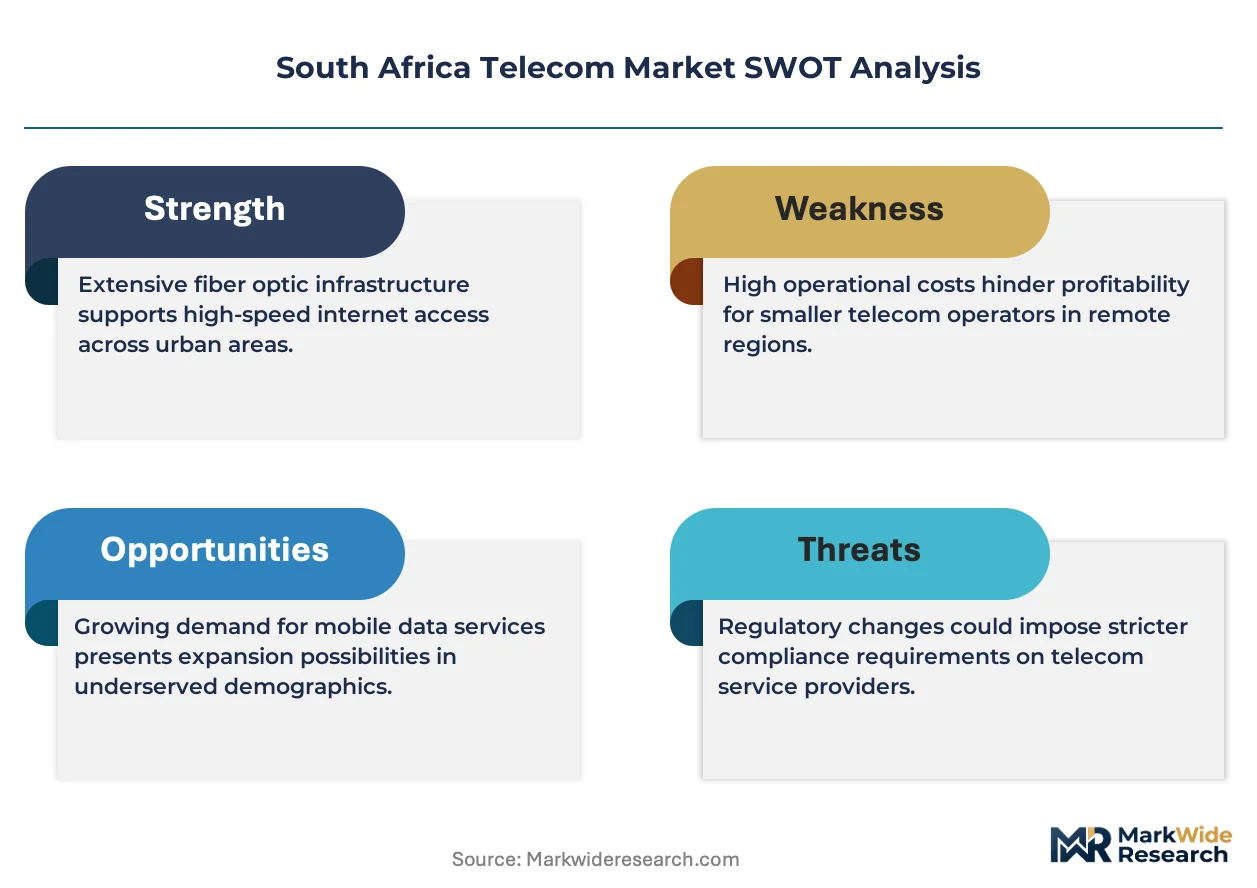
ICASA governs spectrum allocation and licensing under the Electronic Communications Act, while the Competition Commission scrutinizes infrastructure sharing agreements to prevent market concentration. BIS standards apply to equipment certification, ensuring interoperability with international networks. The Department of Communications and Digital Technologies coordinates national broadband policy through SA Connect targets. Stakeholders must monitor spectrum auction timelines and infrastructure partnership rules that determine market entry feasibility for new wholesale operators.
Market Dynamics
ICASA's spectrum licensing reforms are compressing deployment timelines for 5G infrastructure across South Africa's metropolitan corridors, forcing operators to accelerate capital allocation toward mid-band rollout in Gauteng and Western Cape.
Growth Catalysts
- SA Connect broadband targets:Government-mandated connectivity thresholds are pulling fiber deployment into underserviced municipalities, creating anchor tenancy for wholesale network operators.
- Enterprise cloud migration:Financial services firms in Johannesburg's Sandton district are consuming dedicated leased lines at volumes that justify 5G fixed-wireless overlay investments.
- Mid-band spectrum availability:The 3.5 GHz band release is enabling network densification without the propagation limitations of millimeter-wave alternatives.
Market Restraints
- Copper network maintenance burden:Telkom SA SOC Limited's legacy access infrastructure requires sustained operational expenditure that constrains fiber overbuild velocity in secondary cities.
- Equipment import dependency:Base station hardware sourcing concentrates through Asian manufacturing hubs, exposing rollout schedules to shipping lane volatility.
- Right-of-way access friction:Municipal permitting processes for trenching and pole attachment create deployment bottlenecks in dense urban environments.
Strategic Opportunities
- Eastern Cape underpenetration:Port Elizabeth and surrounding manufacturing zones lack fiber competition intensity present in Gauteng, opening greenfield wholesale access plays.
- Smart agriculture connectivity:Precision farming applications in Western Cape wine regions are generating demand for low-latency IoT backhaul that terrestrial wireless can address.
- Open RAN architecture adoption:Disaggregated radio access network standards are converging with operator cost reduction mandates to create vendor diversification pathways.
Industry Challenges
- Radio frequency engineering talent scarcity:Network planning and optimization functions require specialized skills that outpace domestic technical education pipeline output.
- Multi-vendor integration complexity:Operators mixing legacy Ericsson and Nokia cores with emerging Open RAN elements face interoperability testing cycles that delay service launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Telecom Market |
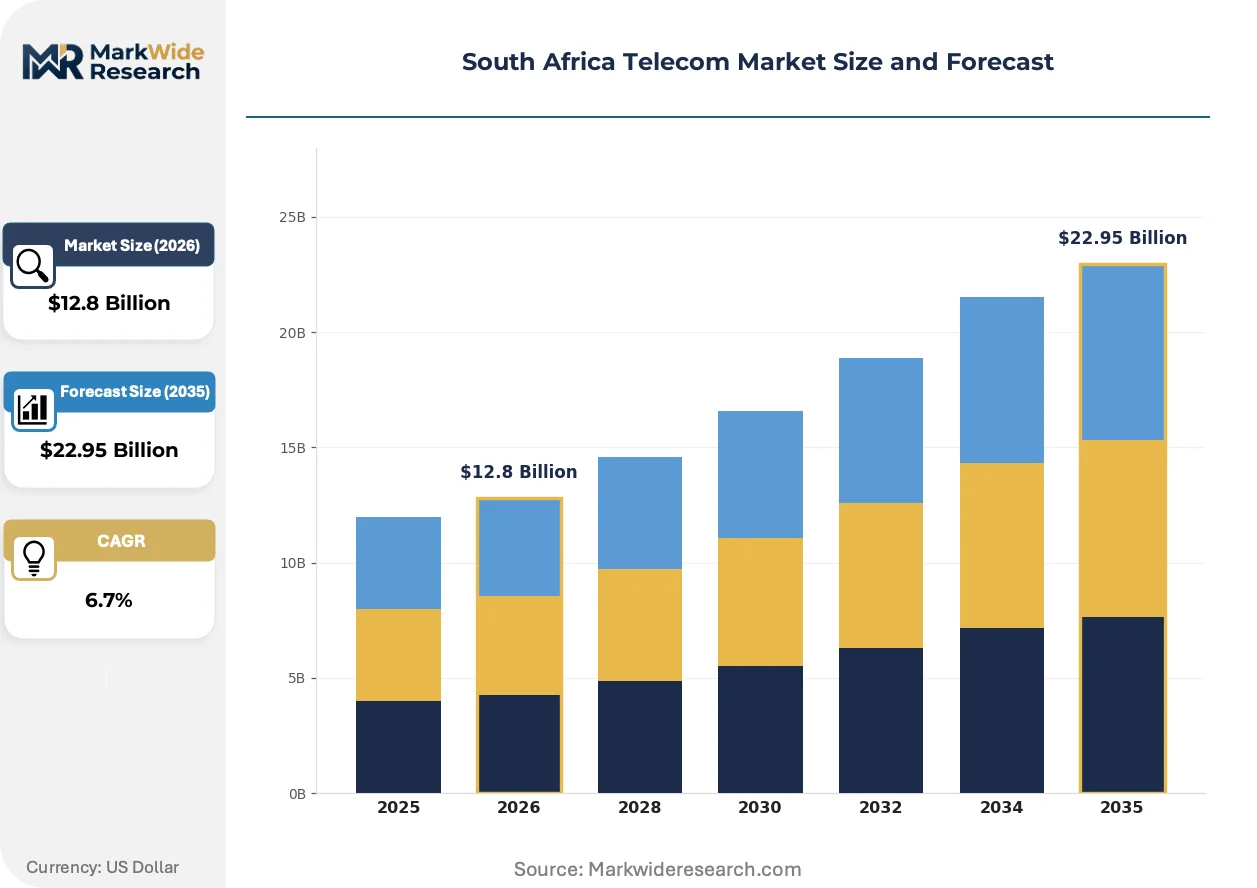
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Services, Fixed-line Services, Broadband, VoIP Technology: 4G LTE, 5G, Fiber Optic, Satellite End User: Residential, Small Business, Enterprises, Government Delivery Model: Retail, Direct Sales, Online, Wholesale |
| Companies Covered | MTN South Africa, Vodacom South Africa, Telkom SA SOC Limited, Cell C Limited, Rain, Liquid Intelligent Technologies, Dark Fibre Africa, Vox Telecommunications, Herotel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Telecom Market Strategic Shifts
Network function virtualization is displacing proprietary hardware dependencies across South African carrier infrastructure, enabling software-defined scaling that matches traffic volatility in enterprise and consumer segments.
Artificial intelligence-driven radio resource management is converging with 5G standalone core deployments to automate beamforming and interference mitigation in dense urban cells. MTN South Africa and Vodacom South Africa are piloting these capabilities in Johannesburg's financial district, compressing manual optimization cycles from weeks to hours. The structural consequence is a shift from coverage-centric to experience-centric network planning, where quality metrics determine capital allocation priority.
ICASA's infrastructure sharing framework under the Electronic Communications Act is mandating co-location and passive infrastructure access that reduces redundant tower builds. This regulatory pressure is forcing competitors into operational separation between active network layers and physical site assets. The wholesale tower segment is consolidating as independent operators acquire stranded real estate from mobile carriers seeking balance sheet relief.
Enterprise procurement of connectivity services is fragmenting from long-term managed contracts toward shorter-term bandwidth-on-demand arrangements. Mining houses in Gauteng's platinum belt are piloting subscription-based private 5G networks that scale with operational tempo rather than fixed capacity commitments. This behavioral shift is most visible in resource extraction verticals where commodity price volatility makes traditional capex-heavy network ownership untenable.
South Africa Telecom Market Segmentation
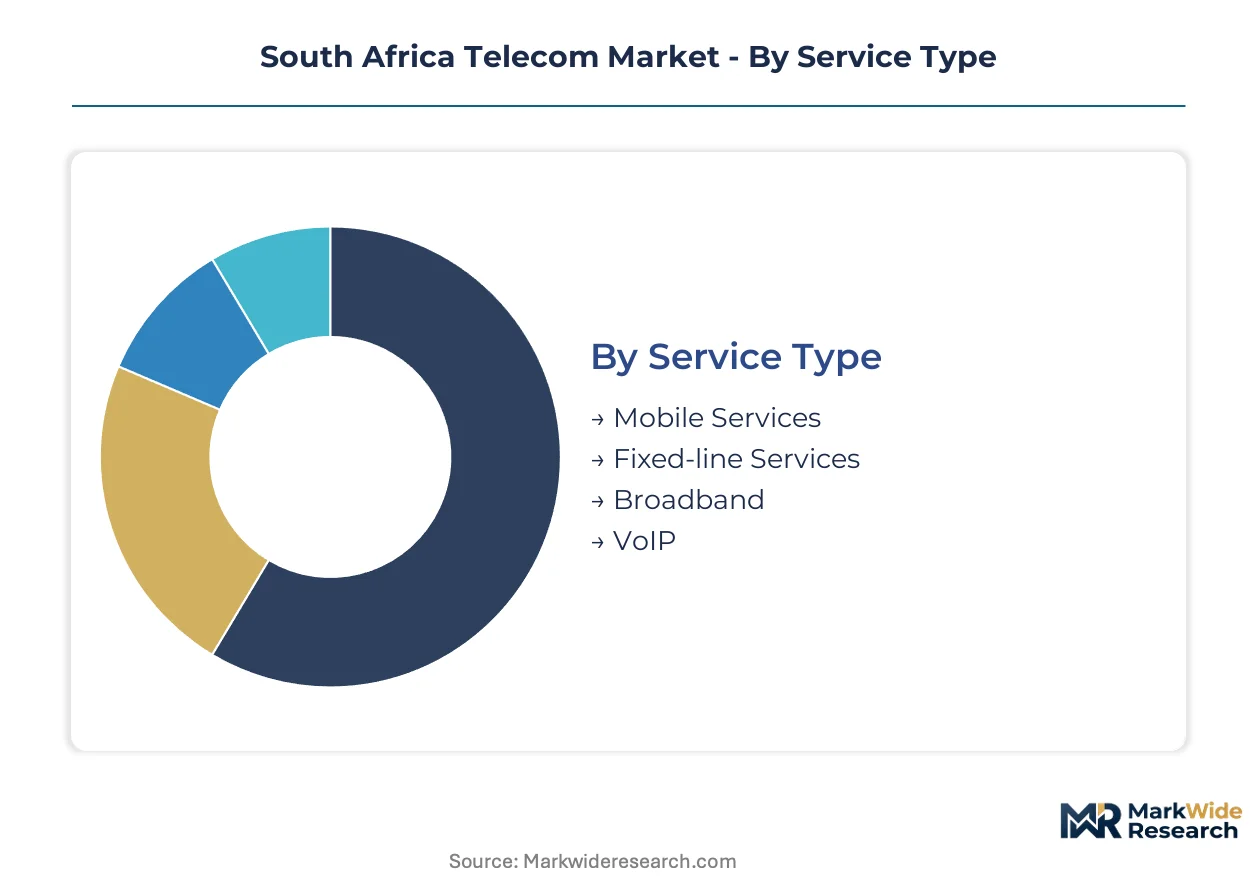
Segmentation in South Africa's telecom sector reveals how ICASA licensing requirements and infrastructure access rules create divergent compliance burdens across service categories. Understanding these divisions clarifies where capital deployment faces regulatory friction versus operational flexibility.
Service Type:
ICASA mandates distinct licensing tiers for each service category, with broadcasting and electronic communications licenses carrying heavier ongoing compliance obligations than data-only permits.
- Mobile Services:Voice and data transmission over cellular networks operating across 700 MHz to 3.5 GHz spectrum bands. Gauteng's mining belt and Western Cape technology corridor generate concentrated demand for enterprise mobile data as fleet management systems require ubiquitous coverage.
- Fixed-line Services:Copper and fiber-based voice connectivity delivered through Telkom SA SOC Limited's legacy infrastructure. Secondary cities in Eastern Cape and Free State remain dependent on this technology where wireless alternatives lack density.
- Broadband:High-speed internet access via DSL, fiber-to-the-home, or fixed-wireless technologies. SA Connect targets are pulling deployment into underserviced municipalities, creating anchor tenancy for wholesale operators.
- VoIP:Voice over Internet Protocol services bypassing traditional circuit-switched networks. Small businesses in Johannesburg's Sandton district are migrating to cloud-hosted PBX systems to reduce line rental costs.
Mobile Services sits at the top of the volume ranking, with Broadband climbing the fastest.
Technology:
Equipment certification through BIS standards and ICASA type approval creates tiered time-to-market constraints, with newer technologies facing longer testing cycles.
- 4G LTE:Fourth-generation cellular technology delivering peak download rates exceeding 100 Mbps. Ubiquitous coverage across South Africa's metropolitan zones supports consumer video streaming and basic enterprise connectivity.
- 5G:Fifth-generation networks leveraging mid-band and millimeter-wave spectrum for ultra-low latency. MTN South Africa and Vodacom South Africa are densifying Johannesburg's financial district with 3.5 GHz deployments to serve high-frequency trading firms.
- Fiber Optic:Glass-core transmission infrastructure with per-strand throughput exceeding 100 Gbps. Western Cape undersea cable landing stations are restructuring backhaul economics for Cape Town's technology corridor.
- Satellite:Geostationary and low-earth-orbit connectivity for remote and rural coverage. Eastern Cape farming communities beyond fiber reach rely on satellite for precision agriculture telemetry.
Fiber Optic commands the highest capital intensity per subscriber, with 5G gaining share fastest in metropolitan deployment schedules.
End User:
Procurement patterns diverge sharply across customer types, with government tenders requiring BEE compliance and enterprises demanding SLA-backed managed services.
- Residential:Individual households consuming prepaid mobile data and fiber-to-the-home subscriptions. Township areas in Gauteng and Western Cape are driving prepaid mobile revenue through data bundle purchases.
- Small Business:Micro-enterprises and SMEs requiring basic connectivity and cloud access. Cape Town's technology startup cluster consumes asymmetric fiber packages with burstable bandwidth.
- Enterprises:Large corporations procuring dedicated leased lines and private networks. Mining houses in Gauteng's platinum belt are piloting subscription-based private 5G networks that scale with operational tempo.
- Government:National and provincial departments sourcing through SA Connect framework agreements. The Department of Communications and Digital Technologies coordinates national broadband policy through mandated connectivity thresholds.
Residential accounts dominate connection volumes, with Enterprises expanding most quickly through private network deployments.
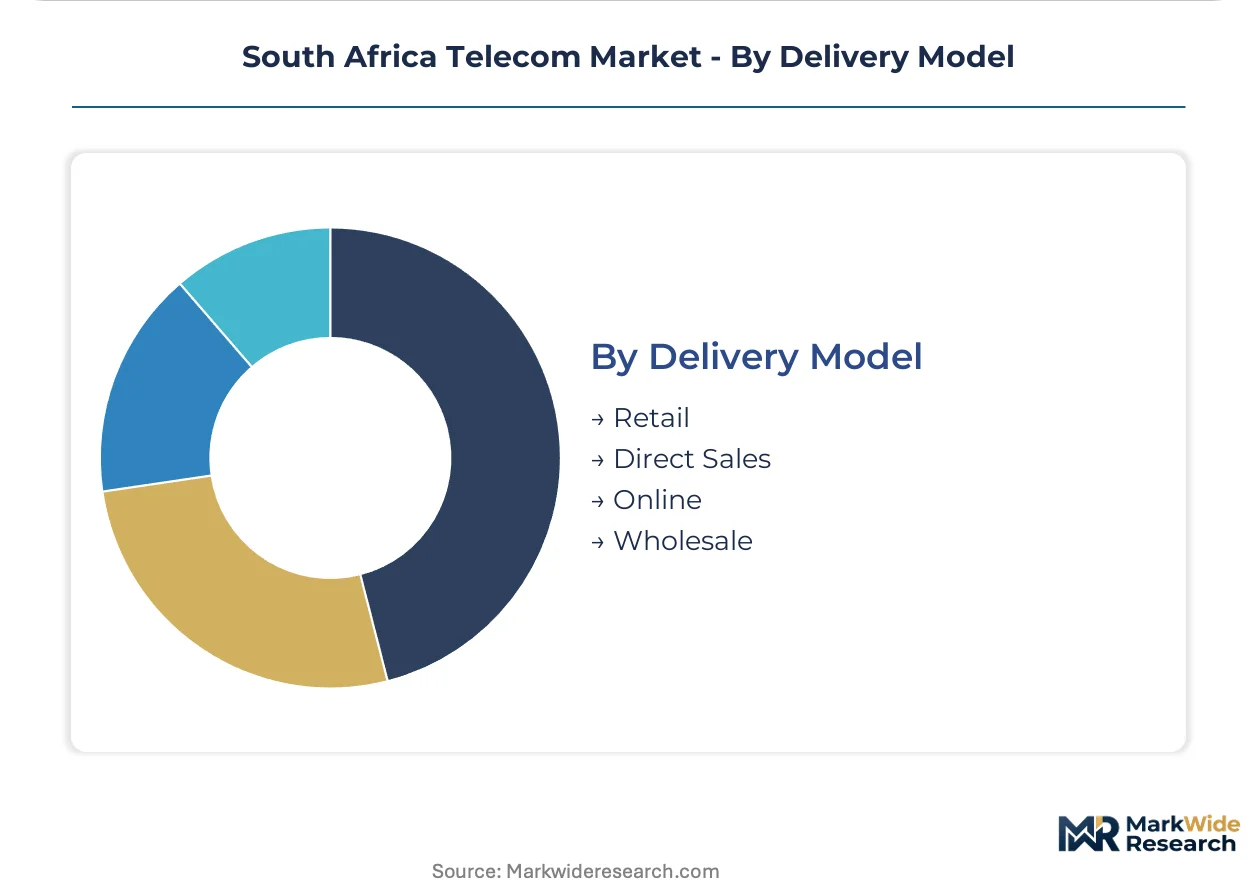
Delivery Model:
Channel economics vary by customer acquisition cost and churn profile, with wholesale arrangements requiring ICASA infrastructure sharing compliance.
- Retail:Branded storefront and call center sales of consumer mobile and broadband packages. Vodacom South Africa anchors consumer revenue through financial services integration at retail touchpoints.
- Direct Sales:Enterprise account teams negotiating customized connectivity contracts. Telkom SA SOC Limited deploys specialized sales engineers for fiber enterprise deals in secondary cities.
- Online:Digital self-service provisioning and account management portals. Younger demographics in Western Cape technology corridor prefer app-based SIM activation and data bundle purchases.
- Wholesale:Bulk capacity resale to virtual network operators and retail service providers. ICASA's infrastructure sharing framework mandates co-location access that reduces redundant tower builds.
Retail maintains the widest geographic footprint, with Wholesale climbing fastest as independent operators acquire stranded real estate from mobile carriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in spectrum licensing and infrastructure access costs is concentrating telecom investment in South Africa's most permissive metropolitan jurisdictions. Operators migrate capital toward provinces where ICASA's Electronic Communications Act enforcement creates faster deployment timelines and lower compliance friction.
Gauteng
Johannesburg's financial district and the platinum mining belt generate concentrated demand for private 5G networks and dedicated leased lines. ICASA's spectrum auction framework prioritizes enterprise-grade mid-band allocations in this province. Sandton's high-frequency trading firms are consuming bandwidth volumes that justify network densification investments.
Western Cape
Cape Town's technology corridor drives fiber-to-the-home and asymmetric broadband uptake among startup clusters and remote-work professionals. The Department of Communications and Digital Technologies coordinates SA Connect anchor tenancy programs for underserviced municipalities in this province. Undersea cable landing stations at Melkbosstrand are restructuring backhaul economics for wholesale operators.
KwaZulu-Natal
Durban's port logistics and manufacturing zones require fleet management connectivity and industrial IoT backhaul. Municipal permitting processes for trenching create deployment bottlenecks that favor fixed-wireless alternatives. The province's tourism corridor along the north coast is pulling prepaid mobile data consumption through seasonal population surges.
Eastern Cape
Port Elizabeth and surrounding automotive manufacturing zones lack fiber competition intensity present in Gauteng. ICASA's infrastructure sharing mandates are opening greenfield wholesale access plays for independent tower operators. Precision farming applications in the Sundays River Valley are generating demand for low-latency IoT connectivity.
South Africa Telecom Market Competitive Environment
Johannesburg-based operators anchor the premium enterprise tier; Cape Town specialists hold positions in fiber infrastructure and wholesale access. The market structure concentrates around three mobile network operators with national spectrum holdings, supplemented by fixed-line incumbents and emerging wholesale challengers. Strategic archetypes include integrated mobile-finance conglomerates, copper-to-fiber transition specialists, and open-access fiber wholesalers. Dominant competitive moves encompass infrastructure sharing agreements under ICASA mandate and spectrum position consolidation through auction participation.
Within the integrated mobile tier, MTN South Africa and Vodacom South Africa exemplify operators leveraging national 5G spectrum positions to extend enterprise coverage. Telkom SA SOC Limited occupies a distinct structural position as the legacy fixed-line incumbent managing copper network obligations while overbuilding fiber in secondary cities.
| Leading Market Players |
|---|
| MTN South Africa |
| Vodacom South Africa |
| Telkom SA SOC Limited |
| Cell C Limited |
| Rain |
| Liquid Intelligent Technologies |
| Dark Fibre Africa |
| Vox Telecommunications |
| Herotel |
| Others |
Value Chain & Pricing Dynamics
Radio frequency engineering talent scarcity in Gauteng's metropolitan corridor widens labor-cost differentials between Johannesburg's premium enterprise tier and Eastern Cape's emerging wholesale markets, compressing pricing-tier spreads as operators compete for the same technical workforce pool.
Pricing Analysis
Distributor margins on base station hardware absorb the volatility from Asian manufacturing hubs, with three-tier pricing structure across premium, standard, and economy levels separating MTN South Africa's enterprise-grade managed services from prepaid mobile bundles in Western Cape townships. Price differentiation hinges on SLA-backed uptime guarantees and ICASA license tier, with enterprise procurement teams in Sandton's financial district showing lowest price sensitivity while small businesses migrating to cloud-hosted PBX systems drive cost compression in VoIP segments.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from MTN South Africa and Vodacom South Africa for 5G base station deployments, while wholesale tower operators acquire stranded real estate through independent distribution networks. Equipment sourcing draws from China, South Korea, and Finland for radio access network components, with fiber optic cable production anchored in domestic plants serving Western Cape undersea cable landing stations. Single-source vulnerability in 3.5 GHz radio unit supply creates deployment bottlenecks when shipping lanes through the Red Sea face disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's telecom market functions as a geographic-arbitrage play where ICASA's infrastructure sharing mandates in Gauteng lower compliance costs versus municipal permitting friction in KwaZulu-Natal, redirecting capital toward provinces with faster deployment timelines.
For Market Incumbents: Deploy spectrum position consolidation as the primary defensive lever against Rain's fixed-wireless encroachment in metropolitan zones. MTN South Africa and Vodacom South Africa should accelerate Open RAN architecture adoption to reduce Ericsson and Nokia core dependency, while Telkom SA SOC Limited must prioritize fiber overbuild velocity in secondary cities to escape copper network maintenance burdens that constrain margin expansion. For New Entrants and Emerging Players: Underserved mining houses in Gauteng's platinum belt present immediate white-space opportunity for subscription-based private 5G networks that scale with operational tempo rather than fixed capacity commitments. Port Elizabeth's automotive manufacturing zones lack fiber competition intensity present in Johannesburg, opening greenfield wholesale access plays for independent tower operators with ICASA co-location compliance capabilities. For Investors and Strategic Acquirers: Valuations sit cheapest among copper-to-fiber transition specialists managing legacy access obligations while overbuilding next-generation infrastructure. Long-term viability in this market rests on spectrum auction participation and infrastructure sharing agreement portfolios, with the signal to watch being ICASA's timeline for mid-band spectrum releases that determine competitive positioning in enterprise mobile data.| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Position Consolidation | ICASA auction participation secures mid-band allocations for 5G densification in Johannesburg's financial district. |
| Open RAN Architecture Adoption | Disaggregated radio standards reduce vendor lock-in with Ericsson and Nokia while cutting core network costs. |
| Wholesale Tower Acquisition | Independent operators buying stranded real estate from MTN South Africa and Vodacom South Africa capture balance sheet relief momentum. |
| Fiber Overbuild Acceleration | Telkom SA SOC Limited's secondary city deployments escape copper maintenance burdens constraining operational expenditure. |
| Private 5G Network Piloting | Mining houses in Gauteng's platinum belt consume scalable connectivity matching commodity price volatility cycles. |
Study Parameters
Bottom-up enterprise connectivity modeling reconciled against top-down spectrum allocation tracking forms the analytical core of this study. Primary interviews with network planning engineers, ICASA regulatory affairs specialists, wholesale tower operators, and enterprise procurement managers at Johannesburg financial services firms combined with secondary validation from ICASA licensing databases, Electronic Communications Act amendments, Competition Commission infrastructure sharing rulings, and operator capex disclosures. Triangulation across these sources ensures segment-level precision without over-reliance on any single data channel.
Historical trendline analysis of mobile subscriber growth, fiber deployment velocity, and spectrum auction participation rates informed the projection framework across the analysis window. Segmentation dimensions modeled include service type, technology generation, end-user archetype, and delivery model, with provincial regulatory environment as an additional South Africa-specific dimension. CAGRs derived from curve-fitting observed deployment trajectories against SA Connect broadband targets and enterprise cloud migration patterns in Western Cape technology corridor.
Underlying measurement precision varies by segment; Mobile Services and Broadband carry tighter precision than emerging VoIP and Satellite categories where subscriber reporting remains fragmented. Forecasts reflect assumptions regarding ICASA spectrum release timelines, municipal right-of-way permitting efficiency, and Asian equipment supply chain stability that could shift materially with regulatory or geopolitical developments. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
5G Radio Access Network Market
Telecommunications
Land Professional Mobile Radio Market
Telecommunications
Software Defined Radio Market
Telecommunications
US Voice-Over LTE (Volte) Market
Telecommunications
Asia Pacific Telecom Expense Management Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Telecom Radio System Software Market
Telecommunications
A2P Messaging Market
Telecommunications
Cellular Modem Market
Telecommunications
A2P SMS Market
Telecommunications
Nigeria Telecom Market
Telecommunications
Global International Calling Apps Market
Telecommunications
GPON Market
Telecommunications
Diameter Signaling Control Market
Telecommunications
Global LTE Market
Telecommunications
Promotional Sms Market