
 Indonesia Communication Services Market | 2026-2036
Indonesia Communication Services Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Communication Services Market Insights
Market Context
Software-defined network features are expanding what Indonesian carriers sell beyond raw bandwidth into programmable connectivity slices. Telkomsel dominates prepaid mobile data distribution across the archipelago's 17,000 islands. XL Axiata differentiates through enterprise-grade fixed broadband in secondary cities. Indosat Ooredoo Hutchison positions its 5G rollout to capture manufacturing and port automation contracts.
Technical Definition and Segment Structure
Indonesia Communication Services encompass the transmission, routing, and value-added processing of voice, data, and video traffic across terrestrial, submarine, and wireless infrastructure operating at frequencies from 700 MHz to 28 GHz with latency requirements varying from sub-10 milliseconds for 5G ultra-reliable low-latency communications to 50-100 milliseconds for standard consumer broadband. Mobile data services and fixed broadband together anchor revenue pools, with fiber optic technology capturing the fastest expansion as the Palapa Ring backbone reaches eastern provinces. Prepaid pricing models still occupy the mass consumer tier, though bundled packages for small businesses are deepening average revenue per user.
Regulatory Framework and Outlook
Kominfo's frequency allocation rules and the Ministry of Communication and Informatics' base transceiver station permitting requirements shape capital deployment timelines and coverage obligations for all operators. BIS-equivalent equipment certification and the government's local content regulations for telecommunications infrastructure constrain vendor selection and raise compliance costs. Stakeholders must monitor how TRAI-style spectrum auction reforms and evolving data localization mandates will alter competitive economics before committing to multi-year infrastructure contracts.
Market Dynamics
Software-defined networking is fragmenting Indonesia's carrier value chain, pushing operators to sell programmable connectivity slices rather than raw bandwidth while Kominfo's spectrum policies accelerate infrastructure commoditization.
Growth Catalysts
- Palapa Ring fiber backbone completion:Eastern provinces gain submarine cable connectivity, enabling cloud service expansion into previously underserved archipelago regions.
- E-commerce logistics digitization:Last-mile delivery networks demand real-time tracking APIs, pulling mobile data consumption into B2B contract structures.
- 5G spectrum allocation framework:Kominfo's 3.5 GHz band assignments unlock industrial automation contracts in Surabaya's manufacturing zones and Tanjung Priok port operations.
Market Restraints
- Base transceiver station permitting delays:Ministry of Communication and Informatics approval timelines stretch 18-24 months, freezing coverage expansion in dense urban corridors.
- Local content procurement mandates:Domestic manufacturing requirements for telecommunications infrastructure constrain vendor selection to approved domestic suppliers, raising equipment costs.
- Submarine cable concentration risk:International bandwidth transits through Singapore landing stations, creating single-point vulnerability for inter-island enterprise connectivity.
Strategic Opportunities
- Papua and Maluku connectivity gaps:Easternmost provinces remain below national broadband penetration averages, offering first-mover advantages for satellite-to-fiber hybrid deployments.
- Smart city mandate convergence:Municipal governments in Bandung, Makassar, and Medan bundle IoT sensor networks with fixed broadband contracts, creating integrated service demand.
- Data localization compliance services:Kominfo's data sovereignty requirements push multinational cloud providers toward in-country edge computing partnerships with licensed carriers.
Industry Challenges
- Legacy copper network stranded assets:Telkom's extensive PSTN infrastructure requires costly decommissioning as fiber substitution accelerates in Java.
- 5G radio frequency engineering talent scarcity:Millimeter-wave propagation modeling and massive MIMO deployment skills concentrate in Jakarta, constraining rollout velocity in secondary cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Communication Services Market |
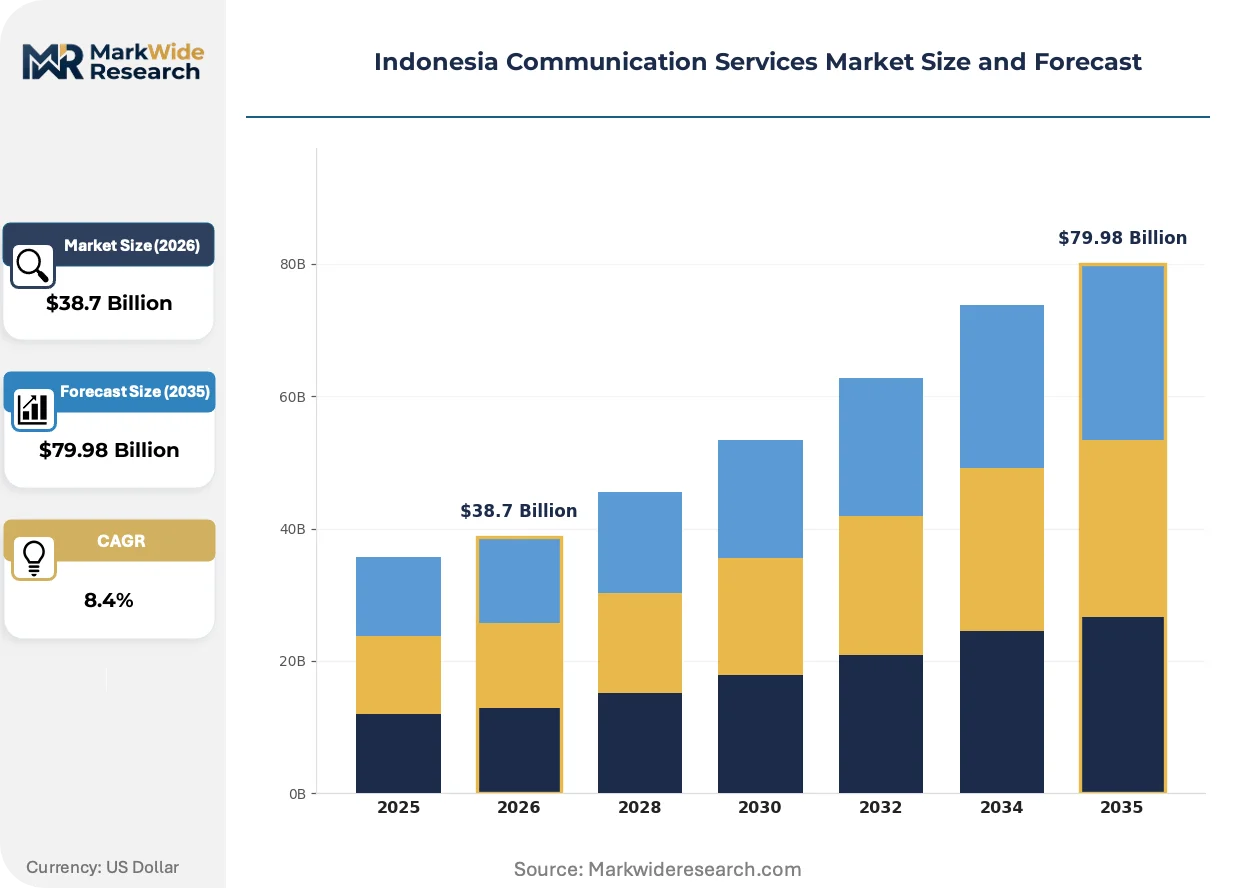
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Voice, SMS, Data Services, Fixed Broadband Technology: 4G LTE, 5G, Fiber Optic, Wi-Fi Customer Type: Residential Users, Small Businesses, Large Enterprises, Government Pricing Model: Prepaid, Postpaid, Bundled Packages, Pay-As-You-Go |
| Companies Covered | PT Smartfren Telecom Tbk, PT Telekomunikasi Indonesia International (Telin), PT Telekomunikasi Selular (Telkomsel), PT Indoritel Makmur Internasional, PT Mora Telematika Indonesia, PT Indosat Tbk (Indosat Ooredoo Hutchison), Telkom Indonesia (Persero) Tbk, Infomedia Nusantara, PT XL Axiata Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Communication Services Market Trends and Innovations
Network function virtualization is collapsing the distinction between hardware-centric and software-defined carrier services, forcing Indonesian operators to rebuild operational models around API-first delivery architectures.
Open RAN architectures are decentralizing Indonesia's base station supply chain, allowing XL Axiata and Indosat Ooredoo Hutchison to mix radio hardware from non-traditional vendors with cloud-native software stacks. Tier-2 cities including Semarang and Palembang see accelerated 5G deployment as procurement flexibility reduces single-vendor lock-in. This fragmentation is compressing infrastructure margins while expanding coverage obligation fulfillment rates.
Kominfo's revised frequency allocation rules tighten electromagnetic compatibility certification for 26 GHz millimeter-wave equipment, extending type-approval timelines by four to six months. Domestic manufacturing quotas for 5G base stations now require 35 percent local value-added content, reshaping vendor consortium structures. Equipment suppliers are responding by licensing Indonesian assembly partnerships rather than direct import models.
Enterprise procurement teams in Greater Jakarta now unbundle connectivity from managed security services, contracting SD-WAN overlays separately from underlying fiber or mobile transport. Systems integrators capture margin that carriers previously held through bundled offerings. This disintermediation is most visible among fintech and e-commerce logistics buyers with in-house network engineering capabilities.
Indonesia Communication Services Market Segmentation
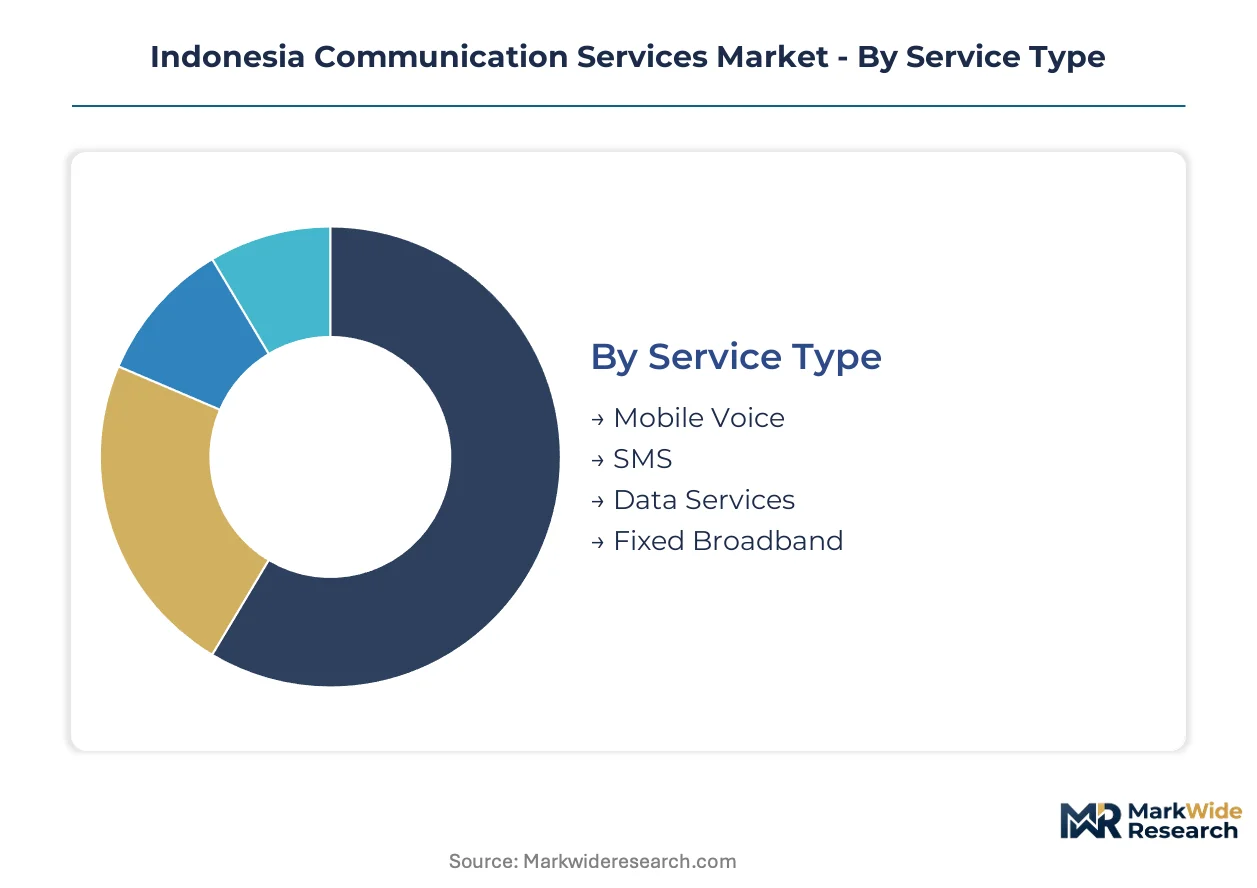
Segmentation in Indonesia's communication services market reveals how regulatory obligations, infrastructure maturity, and customer procurement sophistication create divergent margin structures across service tiers. Each dimension carries distinct certification burdens and capital intensity profiles that shape operator investment priorities.
Service Type:
Kominfo's service-specific licensing requirements impose varying compliance costs across voice, messaging, and data transmission categories, with universal service obligations concentrated in basic telephony segments.
- Mobile Voice:Circuit-switched and VoLTE services remain subject to mandatory quality-of-service benchmarks under Ministry of Communication and Informatics regulations. Demand concentrates in rural archipelago regions where terrestrial infrastructure remains sparse, with prepaid pricing dominating subscriber acquisition in Eastern Java and Sulawesi.
- SMS:Declining person-to-person volumes are offset by A2P messaging growth for banking authentication and e-commerce logistics notifications. Enterprise API integration requirements now exceed consumer traffic in Greater Jakarta's financial services corridor.
- Data Services:Mobile internet consumption drives revenue expansion across Indonesia's 17,000 islands, with video streaming and cloud application traffic shaping capacity planning in fiber-backhauled urban centers.
- Fixed Broadband:FTTH deployments concentrate in Java's enterprise corridors and Surabaya's manufacturing zones, with Palapa Ring fiber backbone extensions enabling expansion into secondary cities.
Data Services sits at the top of the volume ranking, with Fixed Broadband climbing the fastest.
Technology:
Equipment certification timelines and spectrum licensing fees create divergent deployment economics across radio access and wireline infrastructure categories.
- 4G LTE:1800 MHz and 900 MHz deployments cover the mass consumer base across Indonesia's major islands, with network densification requirements intensifying in Jakarta's urban core.
- 5G:3.5 GHz and 26 GHz spectrum assignments unlock ultra-reliable low-latency applications for port automation at Tanjung Priok and manufacturing robotics in Surabaya's industrial zones. Kominfo's 35 percent local content mandate for base station procurement extends rollout timelines.
- Fiber Optic:Palapa Ring backbone completion and metro fiber extensions deliver gigabit symmetrical speeds to enterprise customers in Bandung, Medan, and Makassar.
- Wi-Fi:Offloading infrastructure and public access deployments complement mobile data consumption in retail, hospitality, and transportation hubs across Java and Sumatra.
4G LTE maintains dominant volume position, while 5G gains share fastest among technology categories.
Customer Type:
Contract structures and service level agreements vary sharply between mass-market prepaid users and enterprise procurement teams with dedicated network engineering capabilities.
- Residential Users:Prepaid mobile data and fixed broadband bundles dominate household expenditure patterns, with price sensitivity highest in secondary cities outside Java's economic core.
- Small Businesses:SD-WAN adoption and managed Wi-Fi services concentrate among retail chains and logistics operators in Semarang and Palembang, with bundled security services deepening average revenue per account.
- Large Enterprises:Dedicated fiber leases, private 5G networks, and cloud interconnect services anchor procurement in Jakarta's financial district and Batam's data center corridor. Custom service level agreements mandate redundant submarine cable paths.
- Government:Smart city mandates in Bandung, Makassar, and Medan bundle IoT sensor networks with fixed infrastructure contracts, with local content requirements constraining vendor selection.
Residential Users anchor volume leadership, with Large Enterprises expanding most quickly on a value basis.
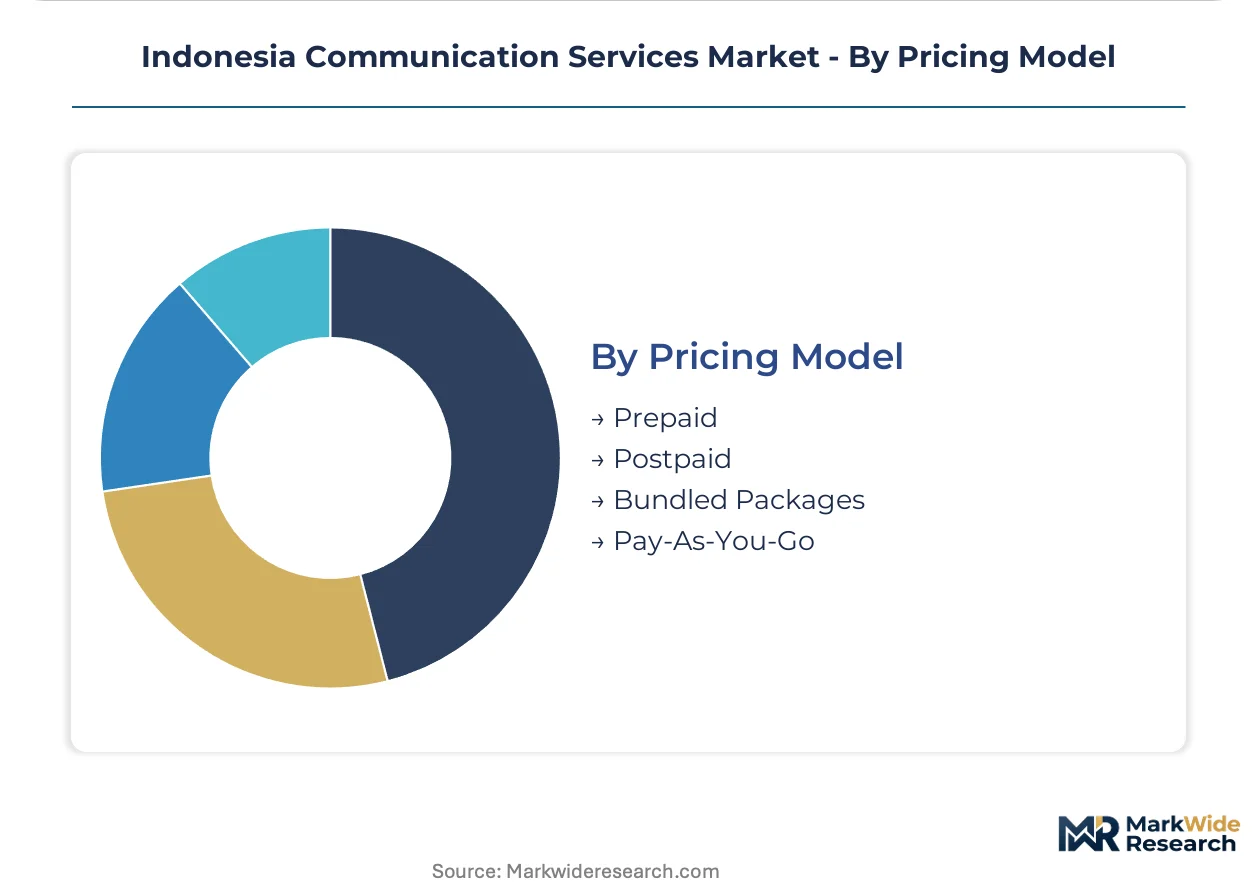
Pricing Model:
Payment structure selection correlates with customer credit infrastructure access and usage predictability requirements across Indonesia's heterogeneous economy.
- Prepaid:Dominant mobile acquisition model across Indonesia's archipelago, with electronic voucher distribution networks extending to remote island communities. Kominfo's mandatory registration requirements ( registrasi kartu prabayar ) impose compliance costs on subscriber onboarding.
- Postpaid:Corporate account structures and premium consumer tiers concentrate in Jakarta and Surabaya, with credit bureau integration enabling subscription financing.
- Bundled Packages:Converged fixed-mobile-service combinations target household and small business segments in fiber-served urban areas, with OTT content partnerships differentiating operator offerings.
- Pay-As-You-Go:Usage-based data and voice pricing persists in machine-to-machine applications and temporary connectivity requirements for events and construction sites.
Prepaid commands the highest transaction volume, with Bundled Packages showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's communication services expansion diverges sharply from Malaysia's infrastructure maturity, with eastern archipelago provinces still awaiting Palapa Ring fiber backbone completion while Java's enterprise corridors already saturate with 5G deployment.
Greater Jakarta
Enterprise procurement for dedicated fiber leases and private 5G networks concentrates in Jakarta's financial district and surrounding industrial zones. Kominfo's base transceiver station permitting requirements create 18-24 month approval timelines that freeze coverage expansion in dense urban corridors. Smart city mandates in satellite municipalities like Tangerang and Bekasi bundle IoT sensor networks with fixed broadband contracts, deepening infrastructure integration.
East Java and Surabaya
Manufacturing robotics and port automation at Tanjung Perak drive demand for ultra-reliable low-latency communications in Surabaya's industrial zones. Kominfo's 3.5 GHz spectrum assignments unlock industrial automation contracts, though 35 percent local content mandates for 5G base station procurement extend rollout timelines. XL Axiata differentiates through enterprise-grade fixed broadband penetration in secondary manufacturing clusters.
West Java and Bandung
Technology startup density and educational institution connectivity requirements shape bandwidth consumption patterns in Bandung's creative economy corridor. Municipal smart city mandates bundle public Wi-Fi infrastructure with fiber backbone extensions, creating integrated service procurement opportunities. Telkomsel's prepaid mobile data distribution networks maintain subscriber acquisition advantages across the province's dispersed population centers.
Papua and Maluku
Easternmost provinces remain below national broadband penetration averages, presenting first-mover advantages for satellite-to-fiber hybrid deployments where Palapa Ring submarine cable landing points reach shore. Kominfo's universal service obligations impose coverage requirements that terrestrial infrastructure economics cannot satisfy without government subsidy support. Telin's international gateway operations position for inter-island enterprise connectivity contracts requiring redundant submarine cable paths.
North Sumatra and Medan
Plantation agriculture digitization and logistics hub development drive B2B mobile data consumption in Medan's industrial zones. Smart city infrastructure procurement in the provincial capital creates bundled IoT and fixed broadband demand from municipal government buyers. Indosat Ooredoo Hutchison positions 5G rollout investments to capture manufacturing and port automation contracts at Belawan port facilities.
Indonesia Communication Services Market Competitive Landscape
Top-tier vendors anchor the integrated carrier tier, while specialized infrastructure providers and international gateway operators occupy distinct competitive positions. Telkom Indonesia and its mobile subsidiary Telkomsel dominate prepaid distribution and fiber backbone ownership across the archipelago's 17,000 islands. Three strategic archetypes define competitive positioning: vertically integrated national carriers with infrastructure ownership, mobile-focused operators leveraging spectrum flexibility, and international gateway specialists facilitating inter-island enterprise connectivity. Dominant competitive moves include fiber backbone expansion through Palapa Ring completion and 5G spectrum acquisition for industrial automation contracts.
Within the integrated carrier tier, Telkom Indonesia and Telkomsel exemplify infrastructure-heavy positioning with fiber backbone dominance and prepaid mobile distribution scale. PT Indosat Tbk (Indosat Ooredoo Hutchison) occupies a distinct competitive position targeting enterprise 5G contracts in manufacturing and port automation verticals. PT XL Axiata Tbk represents the mobile-focused operator archetype, differentiating through enterprise-grade fixed broadband in secondary cities and Open RAN procurement flexibility. PT Smartfren Telecom Tbk anchors the spectrum-specialist position with concentrated holdings in specific frequency bands.
| Leading Market Players |
|---|
| PT Smartfren Telecom Tbk |
| PT Telekomunikasi Indonesia International (Telin) |
| PT Telekomunikasi Selular (Telkomsel) |
| PT Indoritel Makmur Internasional |
| PT Mora Telematika Indonesia |
| PT Indosat Tbk (Indosat Ooredoo Hutchison) |
| Telkom Indonesia (Persero) Tbk |
| Infomedia Nusantara |
| PT XL Axiata Tbk |
| Others |
Pricing and Supply Chain Analysis
E-commerce logistics procurement teams in Greater Jakarta now demand API-integrated mobile data contracts with guaranteed latency SLAs, forcing carriers to restructure legacy prepaid pricing around programmable connectivity slices and compressing margins on raw bandwidth sales.
Pricing Analysis
Capacity additions in fiber-backhauled urban centers are reshaping price floors for fixed broadband as Palapa Ring extensions reach secondary cities. Three-tier pricing structure across premium enterprise leases, standard small-business bundles, and economy residential prepaid dominates contract structures. Cost compression in consumer mobile data is intensifying because Telkomsel and XL Axiata compete for subscriber acquisition in Java's saturated corridors. Small businesses in Surabaya and Bandung show highest price sensitivity due to thin logistics margins, while large enterprises in Jakarta's financial district accept premium pricing for private 5G networks with sub-10 millisecond guarantees.
Supply Chain Analysis
5G base station supply rests on Chinese, South Korean, and Finnish equipment vendors subject to Kominfo's 35 percent local content mandates. Radio access network hardware, fiber optic cable, and power supply systems feed from concentrated Asian manufacturing hubs. Single-source vulnerability concentrates in millimeter-wave antenna arrays where only two qualified suppliers meet Indonesian certification requirements. Distribution runs through Jakarta-based systems integrators who capture margin previously held by carrier direct sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's communication services market offers margin expansion through software-defined network feature monetization and enterprise-grade connectivity tiering, as programmable infrastructure displaces commodity bandwidth sales.
For Market Incumbents: Deepen API-first delivery architectures to defend enterprise relationships against systems integrator disintermediation. Capture margin from SD-WAN overlay services by embedding security and cloud interconnect into fiber lease contracts. Kominfo's evolving data localization mandates create compliance service opportunities that reinforce carrier indispensability. Prioritize Open RAN procurement flexibility to accelerate 5G coverage obligation fulfillment in secondary cities. For New Entrants and Emerging Players: Kominfo's universal service obligations in Papua and Maluku open a window for satellite-to-fiber hybrid deployments where terrestrial economics fail. Target smart city infrastructure procurement in Bandung, Makassar, and Medan where municipal governments bundle IoT sensor networks with fixed broadband contracts. White-space exists in edge computing partnerships for multinational cloud providers seeking data sovereignty compliance. Go-to-market through direct municipal engagement rather than carrier channel partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with infrastructure-light software platforms enabling network function virtualization across multi-vendor hardware estates. Long-term viability centers on carriers who convert fiber backbone ownership into programmable connectivity revenue streams rather than transport commoditization. Acquisition target archetype: regional fixed broadband specialists with Palapa Ring landing point access in underserved eastern provinces. Watch Kominfo's spectrum auction reform timing as inflection indicator for competitive economics reset.| Strategic Initiative | Industry Significance |
|---|---|
| Palapa Ring Fiber Extension | Eastern province connectivity enables cloud service expansion into previously unserved archipelago regions. |
| Open RAN Architecture Deployment | Procurement flexibility accelerates 5G rollout in Semarang and Palembang while reducing vendor lock-in. |
| Private 5G Network Partnership | Surabaya manufacturing zones and Tanjung Priok port operations demand ultra-reliable low-latency communications. |
| API-First Connectivity Platform | Programmable slices capture margin from e-commerce logistics networks requiring real-time tracking integration. |
| Edge Computing Infrastructure Buildout | Kominfo's data sovereignty requirements push multinational cloud providers toward in-country carrier partnerships. |
Research Methodology
Coverage spans Java's enterprise corridors, Sumatra's plantation zones, and the eastern archipelago, with primary inputs from each. Network planning executives at integrated carriers, procurement leads at e-commerce logistics operators, and municipal IT directors in smart city pilot programs provided structured interviews. Secondary validation drew from Kominfo regulatory filings, Palapa Ring infrastructure progress reports, and operator spectrum auction disclosures. Bottom-up subscriber and traffic modeling triangulated against top-down GDP and digital economy indicators.
Granularity-level modeling segmented by service type, technology generation, customer tier, and pricing structure across the projection horizon. Mobile data consumption patterns, fiber penetration rates, and 5G spectrum assignment timelines informed analytical framework construction. CAGRs derived from subscriber growth curves, average revenue per user trajectories, and infrastructure investment cycles. Regional regulatory cluster variations and local content mandate compliance costs shaped geographic differentiation.
Revisions become necessary when Kominfo spectrum policy reforms, submarine cable disruption events, or accelerated Open RAN standardization materially alter deployment economics. Forecasts reflect assumptions about permitting timeline stability and equipment certification continuity. A small set of named triggers warrants ongoing watch: base transceiver station approval acceleration, universal service fund disbursement rates, and millimeter-wave propagation rule changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Canada Hosted PBX Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Global Telecom Order Management Market
Telecommunications
Indonesia Telecom Market
Telecommunications
Thailand Telecom Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Underwater Modems Market
Telecommunications
Cloud Radio Access Network (C-RAN) Market
Telecommunications
5G Equipment Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Global IP Phone Market
Telecommunications
Kenya Telecom Market
Telecommunications
IP Centrex Platforms Market
Telecommunications
Mftpaas Market
Telecommunications
Global Small Cell 5G Network Market