
 Dialer Market | 2026-2036
Dialer Market Size, Share, and Industry Trends Forecast 2026-2036
Dialer Market Analysis
Aftermarket service revenue from dialer maintenance and compliance updates is narrowing toward integrated cloud vendors. Five9 leverages its AI-native platform architecture to capture recurring subscription value. RingCentral sustains broad channel control through unified communications bundling. NICE CXone dominates quality management adjacencies that lock in enterprise renewals.
A dialer is an automated telecommunications system that initiates outbound calls from a pre-loaded contact list, typically operating at call pacing rates of 100 to 300 dials per agent hour depending on algorithm type. Its primary commercial purpose is to maximize agent talk time while minimizing idle intervals and abandoned call rates. Predictive dialer systems lead the product type landscape due to their machine learning-driven pacing engines that optimize connect rates in high-volume telemarketing environments. Cloud-based deployment is expanding fastest as enterprises shed on-premise hardware burdens and adopt SaaS consumption models with elastic seat scaling. The hybrid segment retains relevance in regulated industries requiring local data residency alongside cloud analytics access.
FCC enforcement of STIR/SHAKEN caller ID authentication and TCPA consent requirements shapes product roadmaps for US-facing vendors. GDPR call recording provisions in Europe and India's TRAI telemarketing regulations add compliance layers that filter market access for non-certified platforms. Stakeholders must monitor regulatory divergence between real-time consent frameworks and algorithmic dialing restrictions as jurisdictions tighten consumer protection standards.
Market Dynamics
Cloud-native dialer architectures are collapsing the distinction between predictive algorithms and real-time agent assistance, forcing vendors to reconstitute their platforms around AI-native pacing engines rather than legacy hardware-dependent systems. This structural shift compresses deployment timelines from months to days while elevating compliance automation from optional feature to core infrastructure requirement.
Growth Catalysts
- BPO Sector Expansion in India:TRAI's streamlined telemarketing registration framework accelerates dialer procurement for domestic outsourcing clusters in Bengaluru and Hyderabad.
- STIR/SHAKEN Mandate in the United States:FCC enforcement of caller ID authentication protocols creates replacement demand for non-compliant legacy systems across financial services collections.
- Elastic Cloud Consumption Models:SaaS seat-scaling architectures enable seasonal campaign operators to provision dialer capacity without capital expenditure commitments.
Market Restraints
- TCPA Litigation Exposure:Private right-of-action provisions in US consumer protection law expose dialer operators to statutory damages per non-compliant call.
- Data Residency Requirements:India's data localization mandates fragment cloud infrastructure strategies, requiring hybrid deployments that increase operational complexity.
- Algorithmic Pacing Limitations:Machine learning models trained on North American connect-rate data underperform in emerging markets with divergent telephony infrastructure patterns.
Strategic Opportunities
- GDPR-Compliant Recording Analytics:European call centers seek automated redaction and consent-management modules that transform compliance burden into competitive differentiation.
- Conversational AI Integration:Natural language processing convergence with predictive dialers creates voice-bot handoff capabilities for pre-qualification workflows.
- API-First Distribution Channels:Embedded finance and CRM platforms represent new integration surfaces for dialer functionality as a component rather than standalone purchase.
Industry Challenges
- STIR/SHAKEN Certificate Management:Multi-tenant dialer platforms face operational complexity in maintaining attestation levels across disparate carrier relationships.
- Legacy PBX Integration Friction:Enterprises with sunk investments in on-premise telephony infrastructure encounter API incompatibility when layering cloud dialer overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialer Market |
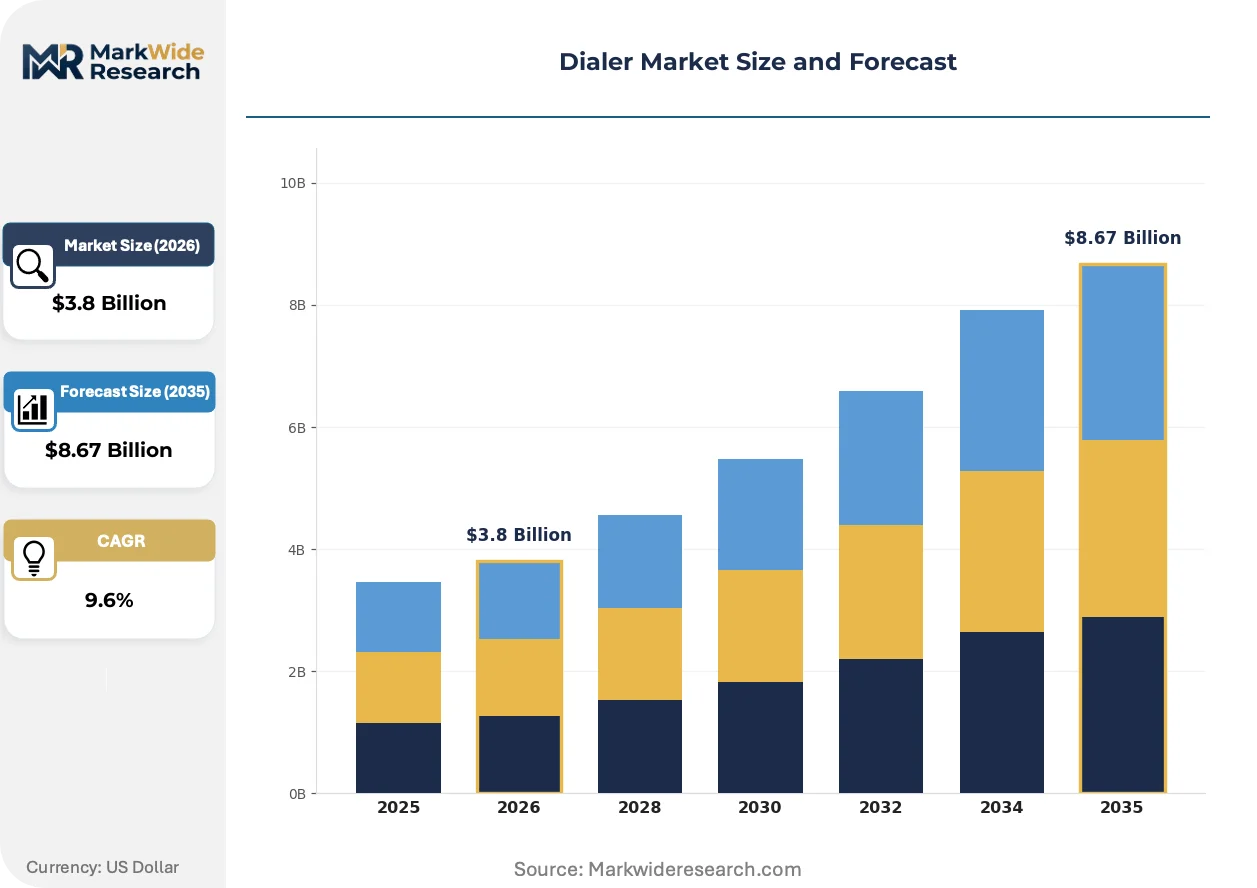
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Predictive Dialer, Preview Dialer, Automatic Dialer, Power Dialer Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Telemarketers, Call Centers, Sales Teams, Customer Support Technology: VoIP, PSTN, Machine Learning, AI |
| Companies Covered | RingCentral, Five9, Talkdesk, NICE CXone, CloudTalk, Dialpad, PhoneBurner, Orum, Nooks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialer Market Emerging Trajectories
Agent-assistance AI is collapsing the traditional separation between dialer logic and conversation intelligence, compressing what were distinct software categories into unified platforms. This convergence redefines vendor competitive boundaries and elevates real-time transcription from ancillary feature to core pacing input.
Neural voice detection is collapsing the accuracy gap between human and automated call classification, enabling predictive engines to distinguish answering machines from live contacts with sub-second latency. Debt collection agencies and political campaign operators deploy these models to maximize talk-time ratios without expanding headcount. The structural consequence is collapsing price premiums for basic predictive functionality as AI-native entrants commoditize core algorithms.
FCC's STIR/SHAKEN framework is mandating cryptographic caller ID attestation across all IP-based voice networks, creating compliance infrastructure as a mandatory cost of market participation. Dialer vendors must integrate with certificate authorities and maintain attestation level documentation for each call path. US-facing telemarketing operations bear the heaviest adaptation burden, with attestation downgrade risks threatening call completion rates.
Enterprise buyers are consolidating vendor relationships around platforms that bundle dialer functionality with quality management and workforce optimization tools. This pattern displaces point-solution procurement in favor of suite contracts with single-vendor accountability. Financial services and healthcare verticals in the United States exhibit the most pronounced concentration, where HIPAA compliance and TCPA risk management favor integrated audit trails over best-of-breed assembly.
Dialer Market Segmentation
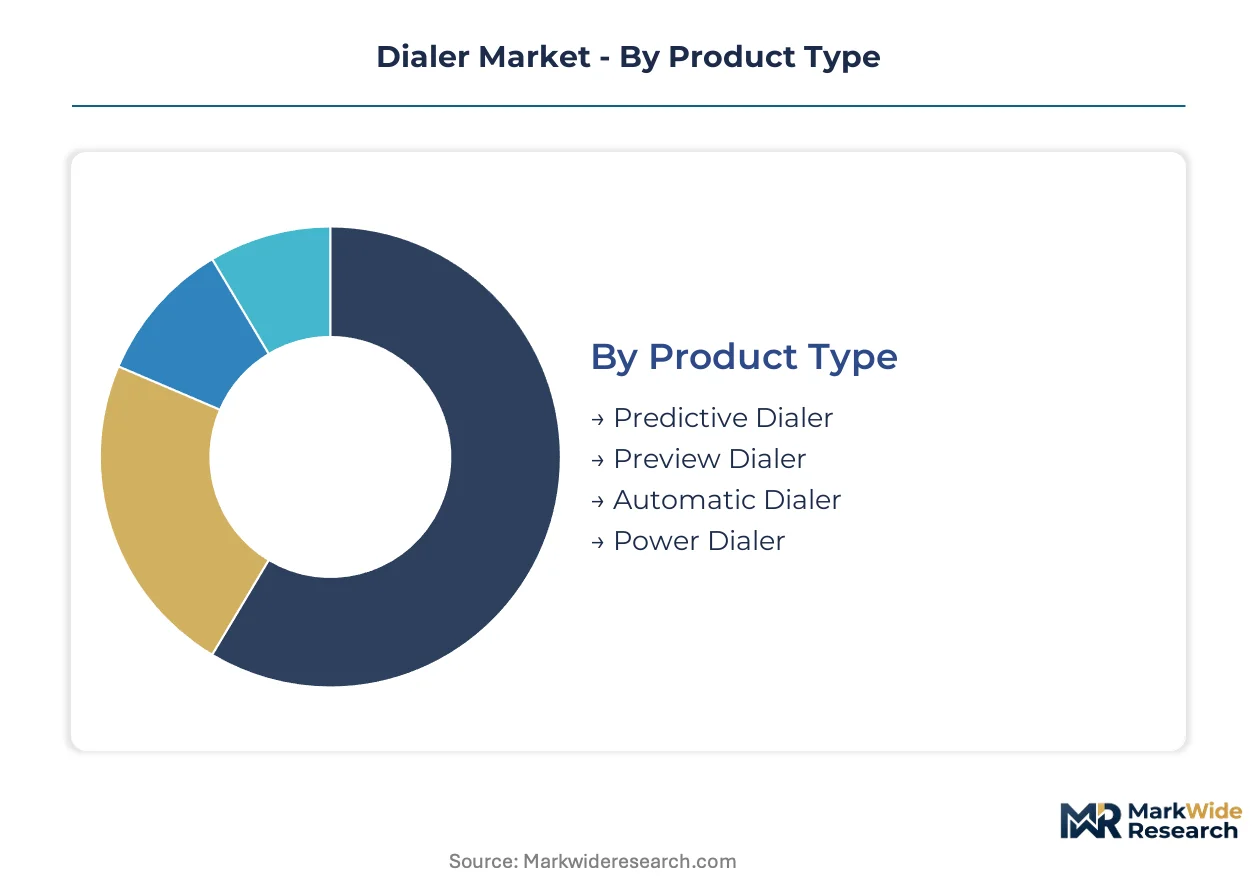
Dialer procurement decisions hinge on compliance architecture and integration complexity rather than base functionality. Vendors structure pricing and service tiers around deployment topology, algorithm sophistication, and vertical risk exposure.
Product Type:
After-sales service intensity varies sharply across dialer categories, with predictive systems demanding continuous algorithm tuning and compliance module updates.
- Predictive Dialer:Machine learning pacing engines optimize connect rates by analyzing historical answer patterns and agent availability in real time. Financial services collections operations in the United States concentrate procurement here, driven by TCPA litigation exposure that demands precise abandonment rate controls. These systems require ongoing model retraining as carrier routing patterns shift.
- Preview Dialer:Agents review contact records before initiating each call, enabling personalized outreach at reduced volume velocity. Healthcare appointment reminder programs and high-value B2B sales teams favor this modality where script customization outweighs throughput metrics. The manual intervention layer reduces compliance automation requirements.
- Automatic Dialer:Systems dial numbers sequentially and connect answered calls to available agents without predictive pacing. Small-scale political campaigns and survey research firms deploy these for simplicity.
- Power Dialer:Maintains a fixed dialing ratio per agent, eliminating idle time without abandonment risk. Inside sales teams at software companies favor this balanced approach.
Predictive dialers hold the largest share; momentum sits with preview dialers as consent-based outreach displaces high-volume telemarketing.
Deployment:
Cost tier stratification separates capital-intensive infrastructure from consumption-based SaaS models.
- Cloud-Based:Elastic seat provisioning enables seasonal campaign operators to scale capacity without hardware procurement. India's BPO clusters in Bengaluru and Hyderabad favor this model to align telephony costs with contract revenue cycles. FCC STIR/SHAKEN compliance emerges as a bundled service rather than custom integration.
- SaaS:Subscription pricing embeds maintenance, security patches, and feature updates into recurring fees. Mid-market sales organizations prioritize this predictability over ownership economics.
- Hybrid:Local data residency satisfies India's TRAI localization mandates while cloud analytics access preserves operational flexibility. Regulated industries requiring call recording custody face elevated integration complexity.
- On-Premise:Sunk infrastructure investments persist among government agencies and legacy financial institutions with stringent audit requirements.
Cloud-based deployment holds the largest share; momentum sits with SaaS as procurement patterns shift from capital to operating expenditure.
End User:
Application-specific workflows dictate feature prioritization and integration depth.
- Call Centers:Omnichannel routing requirements and workforce optimization integration dominate procurement criteria. Quality management adjacencies lock in enterprise renewals through unified audit trails.
- Sales Teams:CRM synchronization and conversation intelligence capture drive purchasing decisions. API-first platforms embedding dialer functionality into Salesforce or HubSpot workflows gain preference over standalone systems.
- Customer Support:Inbound call blending and ticket system integration shape vendor selection. Callback scheduling and queue position notification reduce abandonment rates.
- Telemarketers:TCPA compliance automation and DNC list scrubbing constitute mandatory capabilities. Litigation exposure elevates attestation documentation to core infrastructure.
Call centers hold the largest share; momentum sits with sales teams as revenue operations platforms consolidate communication tooling.
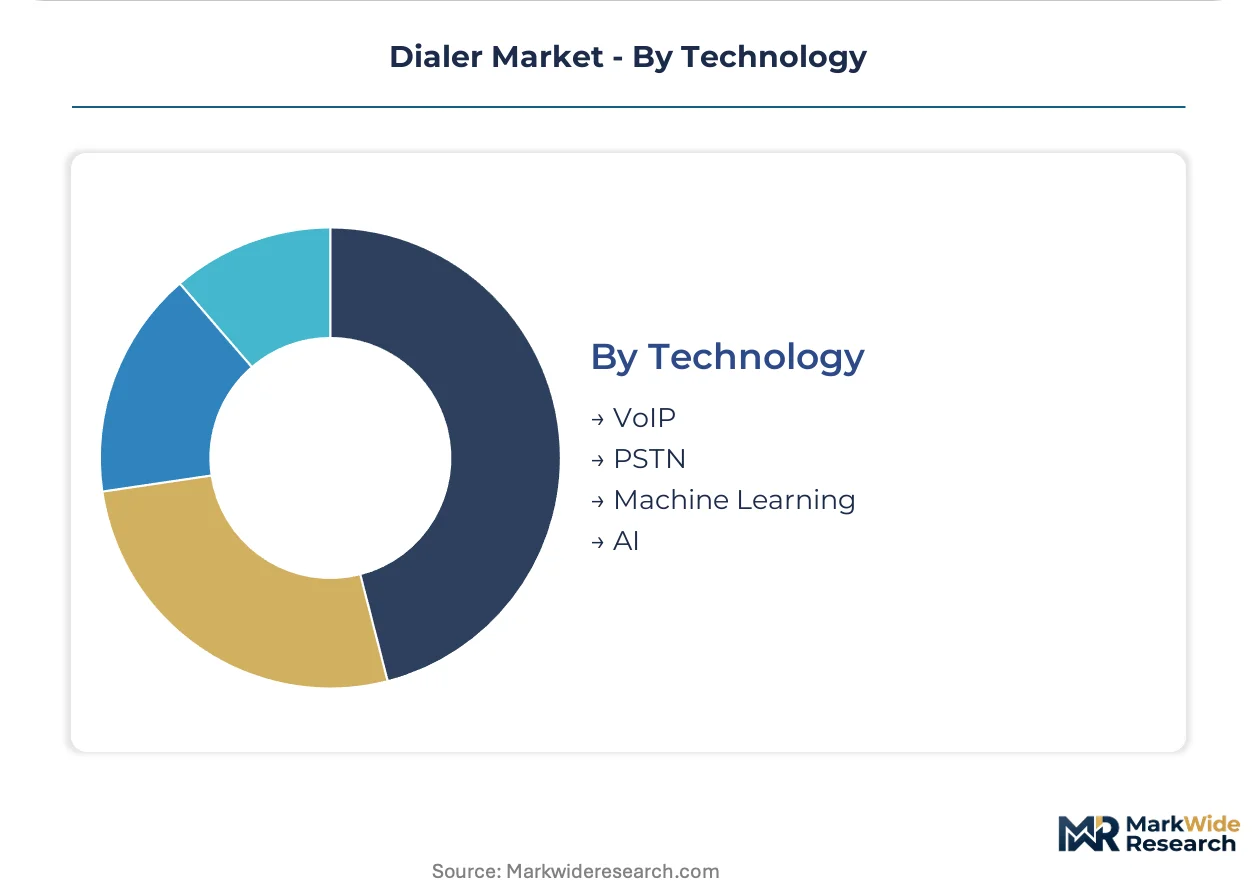
Technology:
Customer maturity separates legacy telephony infrastructure from AI-native architectures.
- Machine Learning:Neural voice detection distinguishes answering machines from live contacts with sub-second latency. Debt collection agencies deploy these models to maximize talk-time ratios without expanding headcount. Model drift requires continuous retraining as carrier signaling patterns evolve.
- AI:Natural language processing convergence creates voice-bot handoff capabilities for pre-qualification workflows. Conversational AI integration transforms dialers from connection engines to full customer interaction platforms.
- VoIP:IP-based voice networks enable STIR/SHAKEN attestation and encrypted transmission. Certificate authority integration becomes mandatory for US-facing operations.
- PSTN:Traditional circuit-switched networks persist in rural coverage gaps and legacy enterprise PBX environments. Interconnection costs and regulatory arbitrage sustain residual demand.
Machine learning holds the largest share; momentum sits with AI as agent-assistance capabilities collapse category boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for dialer systems diverge sharply by geography. US enterprises prioritize TCPA litigation shielding and STIR/SHAKEN attestation. Indian BPO operators optimize for elastic cloud scaling aligned to contract revenue cycles. European buyers emphasize GDPR-compliant recording and consent automation.
United States
Financial services collections operations and political campaign organizations drive procurement volume. FCC enforcement of STIR/SHAKEN caller ID authentication and TCPA private right-of-action provisions shapes vendor selection criteria. Dallas-Fort Worth and Phoenix host dense concentrations of debt collection agencies replacing legacy hardware-dependent systems.
India
Domestic outsourcing clusters in Bengaluru and Hyderabad expand dialer procurement to match BPO contract growth. TRAI's streamlined telemarketing registration framework and data localization mandates accelerate cloud-hybrid deployment decisions. Hyderabad's HITEC City corridor sees rapid platform adoption among voice-process operators serving US and UK clients.
Germany
GDPR call recording provisions and consent-management requirements elevate automated redaction modules to mandatory status. Financial services and healthcare verticals prioritize audit-trail integration. Frankfurt's banking sector concentrates demand for quality management adjacencies that lock in enterprise renewals.
United Kingdom
Conversational AI integration and CRM-embedded dialer functionality gain preference among mid-market sales organizations. FCA conduct rules and GDPR alignment shape compliance roadmaps. London's fintech cluster drives API-first procurement patterns that embed dialer logic into revenue operations platforms.
Brazil
Telemarketing regulatory tightening by ANATEL and consumer protection agencies elevates abandonment rate controls to core infrastructure requirements. São Paulo's domestic call center operators adopt cloud-based elasticity to manage seasonal campaign volatility. Rio de Janeiro's collections sector migrates from automatic to predictive systems for connect-rate optimization.
Dialer Market Vendor Landscape
Capability concentration sits with AI-native platform architects; scale advantage sits with unified communications bundlers. The vendor base stratifies between cloud-native specialists and legacy telephony incumbents retooling around SaaS delivery. Three archetypes dominate: integrated suite providers capturing enterprise renewals through quality management adjacencies; API-first platforms embedding dialer functionality into CRM workflows; and vertical specialists serving litigation-exposed collections operators. Competitive moves center on conversational AI convergence and STIR/SHAKEN compliance automation as mandatory infrastructure.
Within the integrated suite tier, NICE CXone and Five9 exemplify platform consolidation strategies that collapse dialer, quality management, and workforce optimization into unified audit trails. RingCentral anchors the bundling archetype, leveraging unified communications breadth to sustain channel control. These three occupy positions where recurring subscription value depends on compliance automation depth rather than base connection functionality.
| Leading Market Players |
|---|
| RingCentral |
| Five9 |
| Talkdesk |
| NICE CXone |
| CloudTalk |
| Dialpad |
| PhoneBurner |
| Orum |
| Nooks |
| Others |
Supply Flow & Price Mechanics
FCC STIR/SHAKEN certificate management complexity compresses pricing tier spreads between compliant cloud-native platforms and legacy hardware-dependent systems while fragmenting supply chain architectures across certificate authority dependencies and carrier relationship densities. This regulatory chokepoint forces buyers toward bundled compliance-as-a-service models that collapse standalone dialer pricing power into integrated suite premiums.
Pricing Analysis
Long-term subscription contracts dominate dialer procurement, with SaaS seat-scaling agreements locking in predictable recurring revenue against project-based implementations for regulated hybrid deployments. Three-tier pricing structure across premium, standard, and economy levels separates AI-native platforms with real-time transcription from basic predictive engines and entry-level automatic dialers. Cost compression in the economy tier intensifies as machine learning commoditizes core pacing algorithms. Mid-market sales organizations exhibit highest price sensitivity; financial services collections operators prioritize TCPA litigation shielding over unit economics.
Supply Chain Analysis
Upstream telephony infrastructure feeds from cloud hyperscaler concentration in the United States, India, and Germany alongside carrier-grade VoIP gateway manufacturing in Taiwan and South Korea. Neural voice detection chipsets, STIR/SHAKEN certificate authority APIs, and elastic compute provisioning constitute critical input dependencies. Single-source vulnerability around FCC-approved attestation providers threatens platform certification continuity. Distribution runs through direct enterprise sales teams and CRM-embedded API partnerships rather than traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dialer market expansion sits in early-cycle acceleration as AI-native architectures displace legacy hardware systems and compliance automation transforms from optional feature to mandatory infrastructure. Cloud consumption models and conversational AI convergence create durable tailwinds for platform consolidation.
For Market Incumbents: Build compliance-automation moats through STIR/SHAKEN certificate management integration and quality management adjacencies that lock enterprise renewals into unified audit trails. Deepen backward integration into carrier relationship APIs to control attestation-level documentation. Threat substitution from API-first entrants embedding dialer logic into Salesforce and HubSpot workflows demands defensive platform bundling. Certification investment in India's TRAI localization mandates preserves access to Bengaluru-Hyderabad BPO clusters. For New Entrants and Emerging Players: India's domestic outsourcing corridor offers the most penetrable geography as TRAI's streamlined registration framework accelerates procurement cycles for voice-process operators. Target healthcare appointment reminder programs in the United States where preview dialer personalization requirements outstrip incumbent AI-native pacing focus. Conversational AI pre-qualification workflows represent the highest-value white-space application. Go-to-market through embedded finance and revenue operations platforms bypasses standalone procurement gatekeepers. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors integrated suite providers with compliance-automation depth over point-solution vendors. Long-term viability hinges on recurring subscription value capture rather than perpetual license transitions. Acquisition target archetype: AI-native platforms with real-time transcription convergence and established carrier API relationships. Signal to watch: FCC enforcement intensity on TCPA private right-of-action provisions as litigation volume inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Conversational AI Integration | Natural language processing convergence transforms dialers from connection engines to full customer interaction platforms. |
| STIR/SHAKEN Compliance Automation | FCC-mandated cryptographic caller ID attestation becomes mandatory cost of market participation for US-facing vendors. |
| API-First Distribution Expansion | Embedded CRM partnerships embed dialer functionality as component rather than standalone purchase decision. |
| Hybrid Cloud Infrastructure Deployment | India's TRAI data localization mandates fragment strategies toward local residency plus cloud analytics access. |
| Quality Management Adjacency Acquisition | Workforce optimization bundling locks enterprise renewals through unified audit trails and HIPAA compliance integration. |
Methodological Framework
Desk research of FCC enforcement filings, TRAI regulatory circulars, and cloud vendor SEC disclosures preceded structured interviews with call center operations directors, BPO procurement leads, carrier interconnection specialists, and compliance automation engineers. Primary fieldwork with dialer platform product managers and enterprise IT procurement officers validated secondary findings on deployment topology shifts. Bottom-up seat-count modeling across Bengaluru, Hyderabad, and Dallas-Fort Worth clusters triangulated against top-down SaaS revenue estimates from unified communications bundlers.
Forecast assumptions held FCC STIR/SHAKEN implementation timelines and India's data localization enforcement intensity within observed regulatory patterns across the analysis window. Segmentation dimensions modeled include deployment topology, algorithm type, end-user vertical, and regional compliance framework cluster. CAGRs derived from elasticity-adjusted seat-scaling curves and replacement-cycle compression in legacy hardware-dependent installed bases. Neural voice detection accuracy trajectories and TCPA litigation volume trends served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive pricing moves by hyperscaler-backed entrants or accelerated FCC enforcement beyond current trajectories would shift outcomes. Cross-checking against carrier-grade VoIP infrastructure deployment disclosures and BPO contract announcement databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
TV White Space Spectrum Market
Telecommunications
Argentina ICT Market
Telecommunications
Tetra Terminals Market
Telecommunications
5G System Integration Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Global 5G Enterprise Market
Telecommunications
Egypt ICT Market
Telecommunications
Middle East and Africa Telecom Expense Management Market
Telecommunications
Video Door Phones Market
Telecommunications
Mobile Voice Market
Telecommunications
Voice Over LTE (Volte) Market
Telecommunications
Mission Critical Communication (MCX) Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
Global Roaming Tariff Market
Telecommunications
Indonesia Telecom Towers Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market