
 Global 4G LTE Market | 2026-2036
Global 4G LTE Market Size, Share, and Industry Trends Forecast 2026-2036
Global 4G LTE Market Foresight
The gap between legacy 4G core architectures and cloud-native 5G implementations is narrowing as operators pursue incremental upgrades rather than full rip-and-replace cycles. Huawei Technologies leverages its integrated radio-access and transport portfolio to sustain deployment momentum across emerging markets. Ericsson anchors European operator trust through its software-defined baseband platforms. Bharti Airtel competes on spectrum efficiency across India's dense urban corridors.
4G LTE denotes a fourth-generation wireless broadband standard operating across paired and unpaired spectrum blocks from 700 MHz to 2.6 GHz, employing OFDMA downlink and SC-FDMA uplink modulation to deliver peak theoretical rates exceeding 300 Mbps in LTE-Advanced configurations. Its primary purpose remains reliable, low-latency mobile connectivity for consumer broadband, enterprise VPN backhaul, and massive machine-type communications. FDD LTE dominates subscriber volumes in markets with paired spectrum allocations, while TDD LTE claims share in unpaired-band economies such as China and India. LTE-M and NB-IoT within the technology segment represent the fastest-expanding slices as utilities and manufacturing plants migrate from 2G telemetry. Deployment models skew heavily toward Non-Standalone architectures that anchor 4G cores for voice fallback even where 5G NR radios overlay.
FCC spectrum-refarming orders in the United States push operators toward efficient LTE band reallocation, while ETSI and 3GPP standards frameworks govern European equipment interoperability and MNO procurement specifications. India's TRAI mandates on minimum broadband speeds in rural circles shape carrier capex toward LTE tower densification rather than premature 5G standalone builds. China's MIIT spectrum policies enforce domestic equipment certification that filters vendor participation. Stakeholders must monitor regulatory divergence between markets prioritizing 4G lifecycle extension and those accelerating 5G standalone migration, as this split determines equipment refresh cycles and residual value of installed baseband assets.
Market Dynamics
Network operators are extending 4G infrastructure lifecycles through software-defined upgrades rather than full 5G core replacements, compressing capital deployment timelines while preserving existing spectrum assets.
Growth Catalysts
- TRAI rural broadband mandates:India's minimum speed requirements in non-metro circles force tower densification and spectrum refarming, sustaining equipment demand outside urban cores.
- LTE-M telemetry adoption:Logistics fleets and ride-hailing operators deploy machine-type communication modules for real-time vehicle tracking and predictive maintenance.
- Private LTE for factory automation:Southeast Asian manufacturing corridors replace aging Wi-Fi with licensed-spectrum networks to support deterministic latency for robotic control systems.
Market Restraints
- Input cost volatility:Gallium nitride power amplifiers and advanced substrate materials face supply concentration from limited foundry capacity in East Asia.
- Regulatory friction:China's MIIT domestic equipment certification requirements filter vendor participation and extend procurement cycles for non-Chinese suppliers.
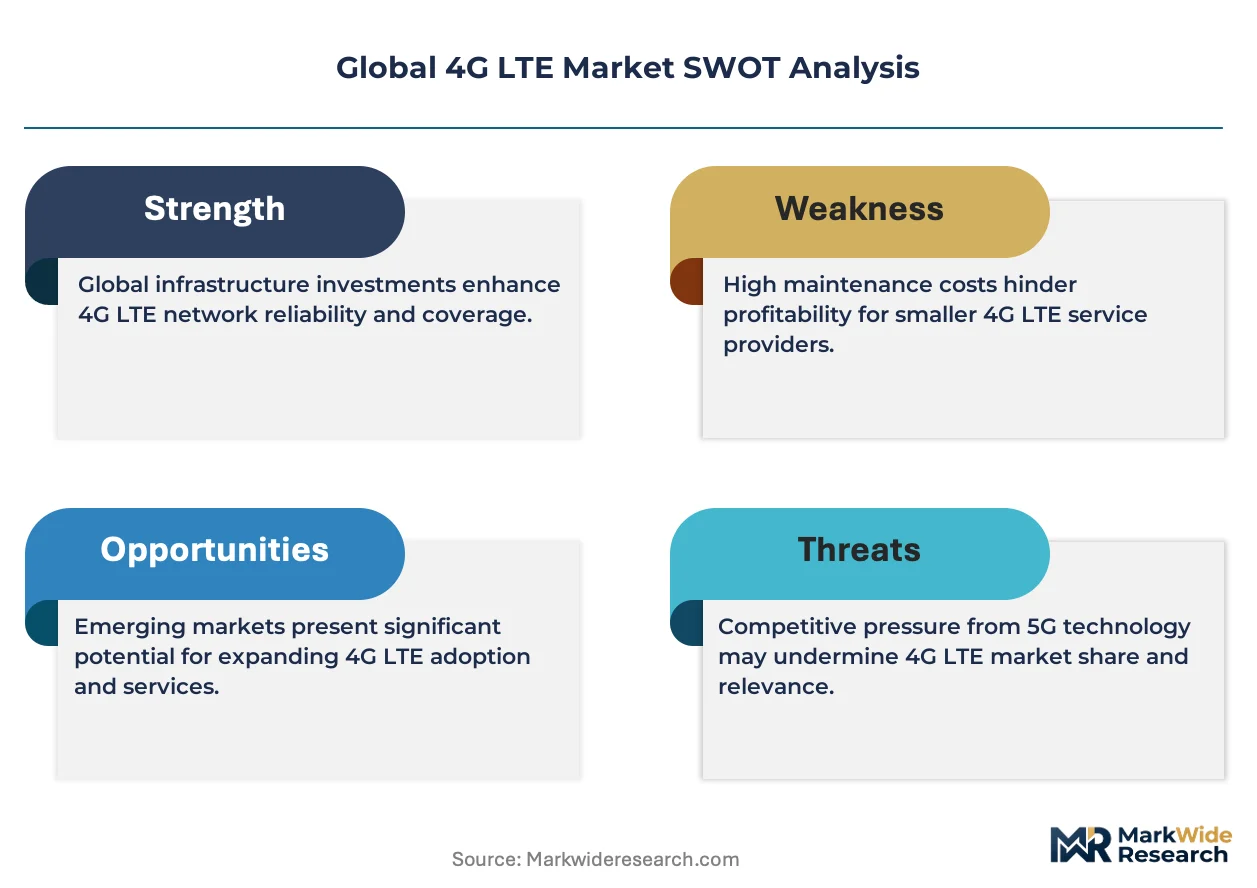
- 5G substitution pressure:Standalone 5G cores in premium urban markets reduce residual value projections for 4G baseband assets and constrain upgrade financing.
Strategic Opportunities
- Underpenetrated African markets:Spectrum auctions in Nigeria and Kenya create greenfield deployment windows before 5G economics mature.
- NB-IoT utility metering:Smart grid infrastructure mandates across Brazil and Mexico drive massive machine-type communication subscription growth.
- Cloud-native core convergence:Containerized 4G packet cores enable operators to bridge toward 5G architectures without forklift upgrades.
Industry Challenges
- Skill scarcity in software-defined radio:Baseband virtualization requires rare expertise combining RF engineering with cloud-native orchestration.
- Legacy circuit-switched voice integration:Maintaining CSFB compatibility during IMS migration consumes engineering resources and delays feature rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 4G LTE Market |
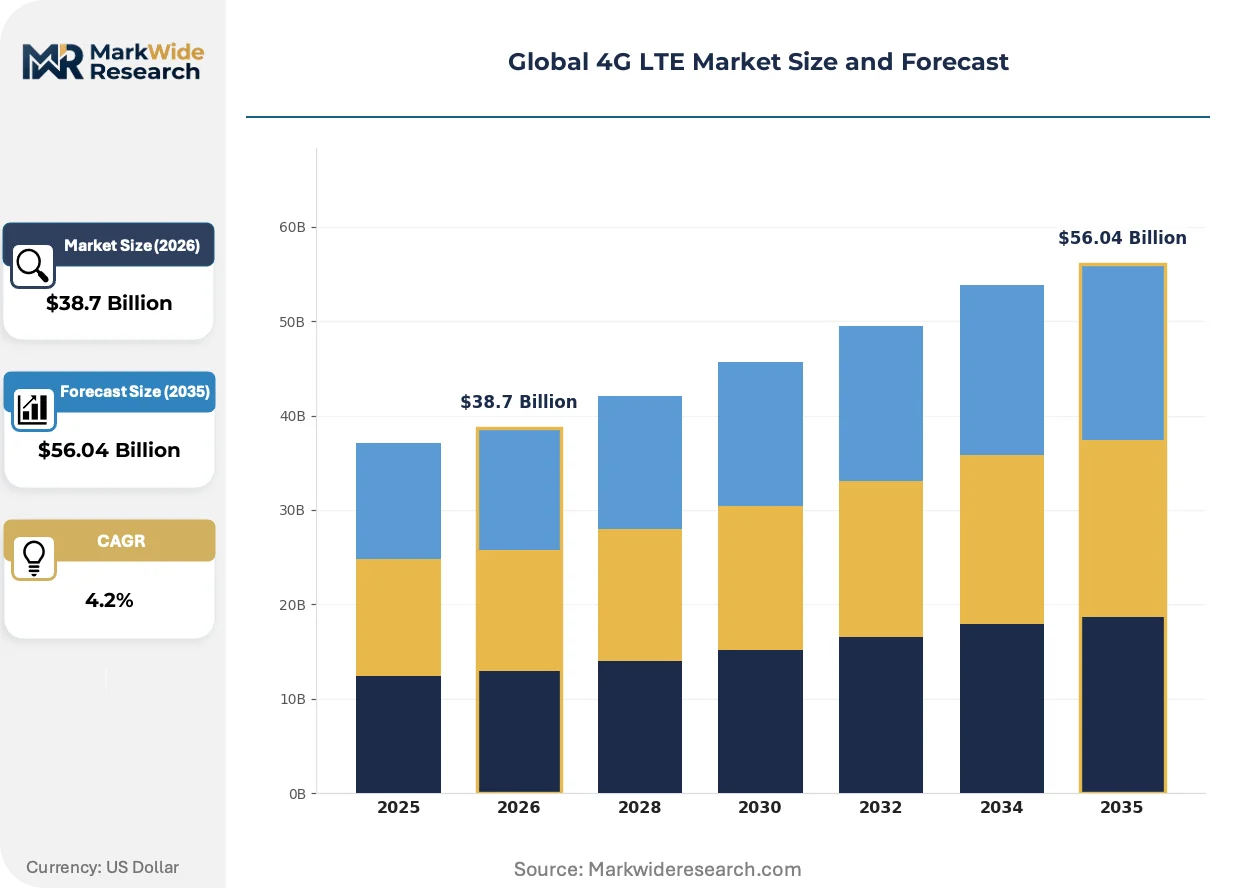
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $56.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: FDD LTE, TDD LTE, LTE Advanced, LTE Advanced Pro, LTE-M, NB-IoT Device Type: Smartphones, Tablets, Routers, Modems, Wearables, Connected Cars Deployment Model: Non-Standalone, Standalone, Hybrid, Virtualized, Cloud-RAN End User Industry: Telecom Operators, Manufacturing Plants, Transportation Services, Public Safety Agencies, Utilities, Media Companies |
| Companies Covered | Verizon Wireless, AT&T, Huawei Technologies, SK Telecom, Vodafone Group, Bharti Airtel, Ericsson, ZTE, T-Mobile US, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 4G LTE Market Shifts & Advancements
Operational technology buyers are redefining connectivity procurement around guaranteed latency tiers rather than peak throughput metrics, reshaping how carriers architect their 4G edge networks.
Dynamic spectrum sharing is migrating from trial deployments to production networks, allowing operators to allocate bandwidth between 4G and 5G users in real-time. Manufacturing plants and port operators in Germany and the Netherlands adopt this capability to preserve existing LTE-M sensor investments while overlaying 5G URLLC for time-critical control loops. The technology is compressing refresh cycles by deferring full 5G standalone builds.
FCC refarming orders in the United States are accelerating 600 MHz and C-band reallocation toward more spectrally efficient LTE configurations. Rural carriers respond by consolidating fragmented holdings into contiguous blocks that support wider channel bandwidths. Equipment vendors must now certify multi-band radios capable of operating across dynamically reassigned frequencies.
Enterprise procurement teams are unbundling connectivity from hardware ownership, favoring network-as-a-service contracts with guaranteed SLA tiers. Brazilian agribusiness operators and Indonesian plantation managers lease managed LTE connectivity rather than building private networks. This shift concentrates buyer power with systems integrators and compresses direct equipment margins for radio vendors.
Global 4G LTE Market Segmentation
4G LTE market segmentation reveals how spectrum allocation, device ecosystems, and deployment architectures diverge across operator strategies. Understanding these splits clarifies where infrastructure investment concentrates versus where legacy systems face displacement pressure.
Technology:
The maturity spectrum spans from legacy FDD/TDD foundations through emerging cellular-IoT variants that extend network lifecycles.
- FDD LTE:Paired-spectrum operation dominates subscriber volumes across markets with symmetric band allocations. Telecom operators in Germany and Brazil rely on FDD configurations for voice fallback and consumer broadband density in urban corridors.
- TDD LTE:Unpaired-spectrum flexibility enables dynamic uplink-downlink ratio adjustment for asymmetric traffic patterns. China's MIIT spectrum policies and India's TRAI unpaired-band allocations concentrate TDD deployment across dense Asian metros where video upload dominates.
- LTE Advanced:Carrier aggregation and enhanced MIMO boost peak rates through licensed spectrum bonding.
- LTE Advanced Pro:Prologues 4G capability through higher-order modulation and small-cell densification.
- LTE-M:Narrowband machine-type communication serves logistics fleet telemetry with extended coverage and power efficiency.
- NB-IoT:Ultra-narrowband specification supports utility smart metering at minimal module cost and decade-long battery life.
FDD LTE handles the majority of throughput; NB-IoT is climbing the fastest on subscription share as utilities accelerate meter replacement cycles.
Device Type:
Volume concentration tilts toward consumer endpoints, while margin expansion tracks specialized industrial and automotive form factors.
- Smartphones:Handset volumes anchor baseband chip demand and carrier ARPU across all licensed bands. Southeast Asian manufacturing corridors and Indian urban districts drive refresh cycles as TRAI mandates push 4G penetration into tier-2 cities.
- Connected Cars:Embedded cellular modules enable real-time navigation, over-the-air updates, and predictive maintenance telemetry. Ride-hailing operators in Mexico City and São Paulo deploy connected car fleets with LTE-M for vehicle tracking and driver safety monitoring.
- Tablets:Enterprise field-service and education segments sustain niche demand for large-screen mobile broadband.
- Routers:Fixed-wireless access devices extend 4G coverage to premises outside fiber footprints.
- Modems:USB and embedded modules serve industrial gateway and point-of-sale applications.
- Wearables:Smartwatch cellular variants rely on LTE-M for standalone connectivity without smartphone pairing.
Smartphones absorb the bulk of unit shipments; connected cars are expanding most quickly as automotive OEMs phase out 3G dependency.
Deployment Model:
Customer type differentiation separates operators preserving legacy core investments from those pursuing cloud-native flexibility.
- Non-Standalone:4G core anchoring with 5G NR radio overlay dominates current capex cycles. European operators and US rural carriers favor this model to defer standalone core expenditure while enabling marketing 5G compatibility.
- Cloud-RAN:Centralized baseband processing with remote radio heads reduces site footprint and enables dynamic capacity allocation. Japanese and South Korean operators deploy Cloud-RAN architectures to support stadium and dense urban capacity surges.
- Standalone:Full 5G core replacement remains limited to premium urban markets with proven 5G device penetration.
- Hybrid:Selective 5G core functions overlay existing 4G infrastructure for transitional architectures.
- Virtualized:Containerized packet cores enable rapid feature deployment without hardware forklift upgrades.
Non-Standalone configurations carry the heaviest deployment share; Cloud-RAN is gaining traction fastest among operators with fiber-rich backhaul.
End User Industry:
Application focus varies from consumer-facing bandwidth arbitrage to deterministic latency requirements in operational technology environments.
- Telecom Operators:Licensed spectrum holders monetize consumer broadband, enterprise VPN, and wholesale capacity. Bharti Airtel and regional MNOs in Nigeria balance urban 5G overlay with rural 4G densification to satisfy universal service obligations.
- Manufacturing Plants:Private LTE networks replace Wi-Fi for robotic control and AGV coordination. German automotive plants and Dutch port operators deploy licensed-spectrum 4G to guarantee sub-20ms latency for time-critical automation loops.
- Transportation Services:Fleet operators leverage LTE-M for real-time tracking, fuel monitoring, and predictive maintenance.
- Public Safety Agencies:Mission-critical push-to-talk and video streaming require hardened network priority mechanisms.
- Utilities:Smart grid infrastructure mandates drive massive NB-IoT subscription growth for distribution automation.
- Media Companies:Broadcast contribution links and live event streaming utilize 4G bonded connectivity for field production.
Telecom operators command the largest revenue share; manufacturing plants are the steepest expansion trajectory as Industry 4.0 budgets hardwire cellular into automation architecture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecom operators and industrial automation buyers concentrate infrastructure procurement across five national markets where spectrum policy, manufacturing density, and logistics digitization intersect.
United States
Rural fixed-wireless access and connected vehicle fleets drive equipment procurement. FCC refarming orders accelerate 600 MHz reallocation toward contiguous LTE blocks. Midwest agricultural operators and Texas oilfield service companies deploy private LTE networks for remote telemetry.
Germany
Automotive OEMs and port operators demand deterministic latency for robotic control systems. ETSI standards frameworks govern equipment interoperability certifications. Hamburg port authorities and Bavarian automotive plants deploy licensed-spectrum 4G to guarantee sub-20ms automation loops.
China
Massive machine-type communication subscriptions scale through utility and manufacturing verticals. MIIT spectrum policies enforce domestic equipment certification requirements. Yangtze River Delta manufacturing clusters replace aging Wi-Fi with TDD-LTE configurations for factory automation.
India
TRAI rural broadband mandates force tower densification outside metro corridors. Minimum speed requirements in non-urban circles sustain equipment demand. Gujarat and Tamil Nadu manufacturing corridors deploy private LTE networks for Industry 4.0 automation.
Brazil
Agribusiness operators lease managed LTE connectivity rather than building private networks. ANVISA regulatory frameworks intersect with national broadband plans. São Paulo logistics operators and Mato Grosso plantation managers expand LTE-M telemetry for fleet tracking.
Global 4G LTE Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Tier-one integrated infrastructure vendors anchor operator trust through radio-access portfolio breadth. Tier-two regional equipment specialists concentrate on spectrum-efficient configurations for emerging markets. Tier-three systems integrators capture enterprise connectivity contracts through network-as-a-service offerings. Competitive moves center on software-defined baseband virtualization and strategic partnerships for cloud-native core convergence.
Among Asian infrastructure specialists, Huawei Technologies and ZTE occupy positions exemplifying integrated radio-access and transport portfolio strategies. European equipment architects Ericsson represents software-defined baseband platform archetypes. Bharti Airtel anchors operator-side competitive positioning through spectrum efficiency optimization. Verizon Wireless, AT&T, and T-Mobile US sit within the tier of channel-controlling service providers leveraging scale procurement power.
| Leading Market Players |
|---|
| Verizon Wireless |
| AT&T |
| Huawei Technologies |
| SK Telecom |
| Vodafone Group |
| Bharti Airtel |
| Ericsson |
| ZTE |
| T-Mobile US |
| Others |
Supply & Pricing Matrix
Shenzhen's concentrated baseband chipset foundry capacity shapes downstream pricing power for LTE equipment vendors serving emerging market operators. Contract structures for radio access units increasingly embed gallium nitride substrate costs with quarterly indexation clauses, transferring input volatility risk from manufacturers to carrier procurement teams.
Pricing Analysis
Cost-plus contracts with gallium nitride and advanced substrate indexation dominate equipment procurement between Asian foundries and European operators. Three-tier pricing structure across premium, standard, and economy levels separates cloud-native baseband configurations from legacy hardware and refurbished rural deployments. Pricing pressure stems from 5G standalone substitution in premium urban corridors, compressing residual value projections for 4G assets. Emerging market operators exhibit highest price sensitivity, while German automotive plants and Dutch port operators accept premium tiers for deterministic latency guarantees.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn, Jabil, and Compal Electronics holding capacity for baseband unit assembly and radio head production. Taiwan, South Korea, and China anchor substrate wafer fabrication and final equipment integration. The supply chain draws from concentrated gallium nitride foundry output, advanced PCB laminates, and precision RF filter components. Single-source vulnerability in East Asian gallium nitride capacity creates exposure to geopolitical disruption. Distribution runs through carrier-direct procurement for tier-one operators and systems integrator channels for private LTE enterprise deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against standalone 5G core migration in premium markets, requiring lifecycle extension strategies that preserve installed base value.
For Market Incumbents: Build software-defined baseband moats through containerized packet core investments that bridge 4G infrastructure toward 5G architectures without forklift upgrades. Prioritize spectrum efficiency optimization for Indian and Southeast Asian operators where TRAI mandates and manufacturing corridor densification sustain equipment demand. Backward integration into gallium nitride substrate sourcing mitigates foundry concentration risk and stabilizes margin structures against input volatility. For New Entrants and Emerging Players: Build out NB-IoT module specialization targeting Brazilian and Mexican utility smart grid mandates where massive machine-type communication subscriptions expand fastest. Underpenetrated African spectrum auctions in Nigeria and Kenya offer greenfield deployment windows before 5G economics mature. Partner with systems integrators offering network-as-a-service contracts to bypass direct carrier procurement barriers and capture enterprise connectivity demand from agribusiness operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors containerized core convergence specialists with proven cloud-native orchestration capabilities. The five-to-ten year viability window hinges on rural infrastructure lifecycles and IoT subscription persistence in utility and logistics verticals. Acquire targets with software-defined radio expertise combining RF engineering with Kubernetes-based orchestration. Watch 5G standalone penetration rates in tier-one cities as the inflection signal for 4G asset residual value compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Convergence | Containerized 4G packet cores enable Bharti Airtel and European operators to bridge toward 5G without forklift upgrades. |
| Dynamic Spectrum Sharing Deployment | German automotive plants and Dutch port operators adopt real-time 4G/5G bandwidth allocation to preserve LTE-M sensor investments. |
| NB-IoT Utility Metering Expansion | Brazilian and Mexican smart grid mandates drive massive machine-type communication subscription growth for distribution automation. |
| Private LTE Manufacturing Networks | Southeast Asian corridors replace aging Wi-Fi with licensed-spectrum 4G to guarantee sub-20ms latency for robotic control systems. |
| Rural Tower Densification Programs | India's TRAI minimum speed requirements in non-metro circles force infrastructure investment outside urban cores. |
Research Methodology
A spread of perspectives from network planning executives at tier-one operators, RF engineering leads at infrastructure vendors, procurement directors at systems integrators, and regulatory affairs specialists at spectrum authorities converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against FCC refarming orders, ETSI equipment certification databases, TRAI rural broadband mandates, and MIIT domestic equipment policies. Bottom-up equipment shipment modeling triangulated against top-down operator capex disclosures across the analysis window.
Demand-supply balance framing anchored the forecast framework across technology segments, deployment architectures, device ecosystems, and end-user industries. The analytical approach modeled FDD versus TDD spectrum configurations, Non-Standalone versus Cloud-RAN deployment models, and consumer versus industrial device form factors throughout the projection horizon. CAGRs derived from equipment replacement cycles, spectrum auction timelines, and IoT subscription trajectories. Forecast inputs incorporated gallium nitride foundry capacity expansion, operator software-defined upgrade roadmaps, and regulatory divergence between 4G lifecycle extension and 5G standalone acceleration markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed Open RAN challengers or state-sponsored equipment vendors would shift outcomes beyond modeled ranges. Regulatory fragmentation between markets prioritizing 4G extension versus 5G migration, supply disruption in East Asian substrate fabrication, and faster-than-expected standalone 5G core adoption in tier-one cities present specific revision risks. Quarterly review of operator RFP pipelines, spectrum auction schedules, and foundry utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
A2P SMS Market
Telecommunications
Egypt Telecom Market
Telecommunications
Japan 5G Small Cell Market
Telecommunications
Private LTE in Mining Industry Market
Telecommunications
Telecom Expense Management Market
Telecommunications
Standalone 5G Network Market
Telecommunications
Smart Feature Phone Market
Telecommunications
Prepaid Communication Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Global Ip Multimedia Subsystem (Ims) Market
Telecommunications
5G Radio Access Network Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Embedded SIM (Esim) Market
Telecommunications
Global Radio Access Network Market
Telecommunications
Telecom API Platform Market
Telecommunications
Australia Mobile Virtual Network Operator (MVNO) Market