
 Oman Telecommunication Market | 2026-2036
Oman Telecommunication Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Telecommunication Market Insights
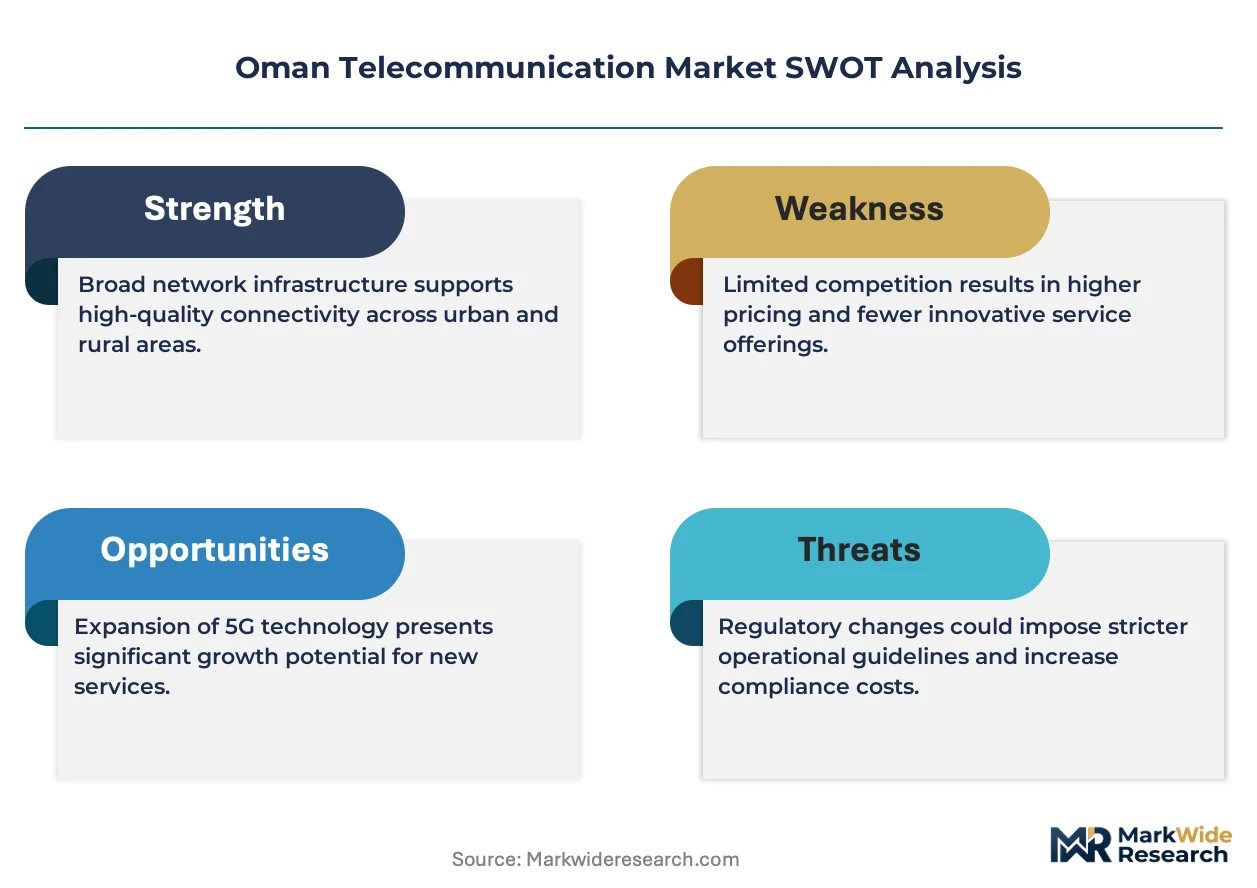
The capital-intensity divergence between fiber infrastructure owners and mobile virtual network operators is unwinding competitive dynamics in Oman's telecom sector. Omantel leverages its nationwide fiber backbone and government contracts to sustain dominance in fixed-line services. Vodafone Oman competes aggressively on 4G LTE pricing to anchor market share among residential subscribers. Ooredoo differentiates through enterprise-grade satellite connectivity for oil and gas clients in remote extraction zones.
Oman telecommunication encompasses the transmission of voice, data, and video across wireless and wireline infrastructure operating at frequencies from 700 MHz to 3.5 GHz and fiber optic wavelengths of 1310-1550 nm, serving as the backbone for national economic digitization and citizen connectivity. Mobile services generate the largest revenue pool as smartphone penetration climbs, while fiber optic deployment represents the fastest-growing technology segment driven by Oman Broadband's national broadband strategy. Enterprise end users command premium pricing due to dedicated leased-line requirements and service-level agreements, whereas residential broadband remains a volume-driven margin-compressed category.
The Telecommunications Regulatory Authority governs spectrum allocation and licensing fees, directly shaping operator capital deployment cycles and network rollout timelines. TRA's infrastructure-sharing mandates and the Ministry of Transport, Communications and Information Technology's digital economy framework compel operators to align investments with national diversification goals beyond hydrocarbons. Stakeholders must monitor how TRA's forthcoming 5G spectrum auction terms alter the competitive balance between established infrastructure owners and newer entrants seeking wireless market position.
Market Dynamics
The Telecommunications Regulatory Authority's spectrum liberalization policies are compressing infrastructure deployment timelines while Oman Broadband's national fiber strategy forces asset-heavy competition among operators serving Muscat's technology corridor and Duqm Special Economic Zone.
Growth Catalysts
- Enterprise Cloud Migration:Omani businesses digitizing operations are demanding dedicated leased-line connectivity with strict service-level agreements, pulling fiber deployment into commercial districts ahead of residential saturation.
- Duqm Special Economic Zone Authority incentives:Tax holidays and streamlined licensing for logistics and manufacturing tenants are creating concentrated demand for redundant connectivity infrastructure in this coastal development corridor.
- 5G mmWave spectrum release:The TRA's allocation of 26 GHz and 28 GHz bands is enabling fixed wireless access deployments that bypass last-mile fiber trenching costs in low-density governorates.
Market Restraints
- Fiber optic cable import dependency:Oman lacks domestic optical fiber manufacturing, exposing operators to freight cost volatility and currency fluctuation risks on submarine cable landing station equipment sourced from East Asian suppliers.
- Mountainous terrain deployment costs:The Al Hajar mountain range running through northern governorates multiplies civil engineering expenses for terrestrial fiber routes compared to flat coastal deployment economics.
- Skilled technician scarcity:Specialized fiber splicing and 5G base station commissioning expertise concentrates in Muscat, forcing operators to transport crews to remote oil field and fishing village installations.
Strategic Opportunities
- Dhofar Governorate underpenetration:Salalah's port expansion and tourism infrastructure investments are outpacing fixed broadband availability, creating first-mover advantage for wireless operators deploying temporary 5G fixed wireless access ahead of fiber.
- Smart city mandate convergence:The Ministry of Transport, Communications and Information Technology's digital economy framework requires municipal IoT integration, opening systems integration contracts that bundle connectivity with sensor deployment.
- Submarine cable landing diversification:New cable systems terminating at Barka and Salalah offer operators neutral access to international bandwidth, reducing reliance on single-point-of-failure architecture at existing Muscat landing stations.
Industry Challenges
- Legacy copper network stranded asset management:Operators must maintain aging DSL infrastructure in rural areas where fiber economics fail while customers churn to wireless alternatives, complicating depreciation schedules and workforce retraining.
- Inter-operator tower sharing negotiations:TRA infrastructure-sharing mandates require commercial agreements on co-location pricing and power backup responsibilities that delay 5G site activation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Telecommunication Market |
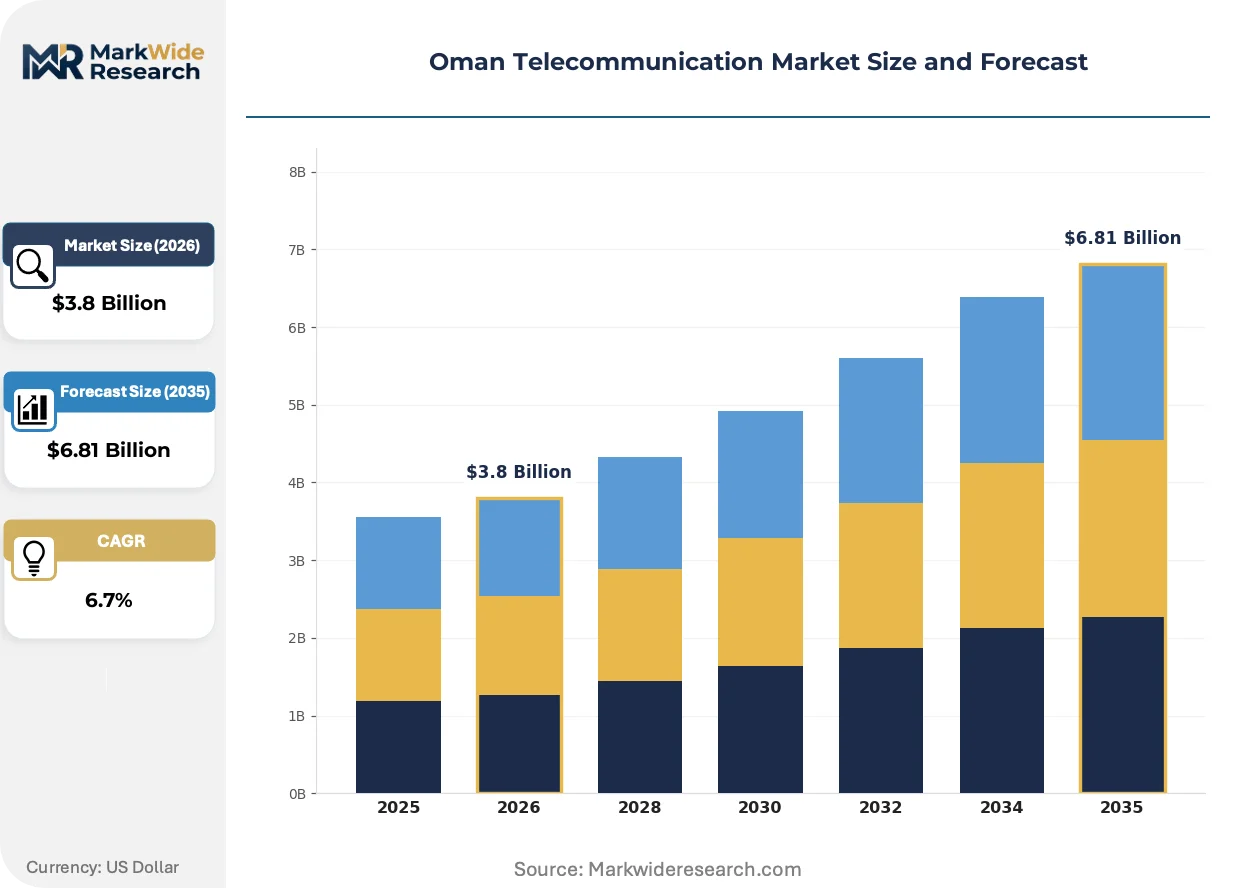
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Broadband, VoIP Technology: 3G, 4G LTE, Fiber Optic, Satellite End User: Residential, Business, Government, Enterprise Product Type: Smartphones, Routers, Modems, Accessories |
| Companies Covered | Oman Telecommunications, Ooredoo, Omani Qatari Telecommunications Company SAOG, Renna Mobile, Vodafone Oman, Oman Broadband, Omantel, Oman Mobile, Awasr, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Telecommunication Market Trends and Innovations
Open RAN architecture is gaining traction among operators seeking vendor diversification, while edge computing integration is reshaping how network intelligence distributes between central data centers and cell tower sites. These shifts are compressing traditional equipment procurement cycles.
Massive MIMO antenna arrays are miniaturizing from 64T64R to 32T32R configurations without sacrificing beamforming precision. Vodafone Oman and Ooredoo are deploying these compact units for urban 5G densification where tower loading limits and visual impact restrictions constrain equipment size. This compression is reducing site acquisition costs and permitting timelines for rooftop installations in Muscat's dense commercial districts.
The Telecommunications Regulatory Authority's infrastructure-sharing framework now mandates active network element sharing for 5G radio access networks in designated coverage zones. This policy is forcing competitors into operational coordination on base station locations and transmission backhaul while preserving service differentiation at the core network layer. Operators in Al Batinah and Ad Dhahirah governorates are most affected, where overlapping buildout plans triggered mandatory arbitration.
Enterprise buyers are unbundling connectivity from managed services, procuring raw bandwidth through wholesale fiber leases while contracting separate systems integrators for SD-WAN overlay deployment. This disintermediation is compressing operator margins on value-added services while expanding addressable market for pure-play network-as-a-service providers. Oil and gas extraction firms in the interior are leading this pattern, driven by cybersecurity compliance requirements that favor specialized vendors over integrated telecom operators.
Oman Telecommunication Market Segmentation
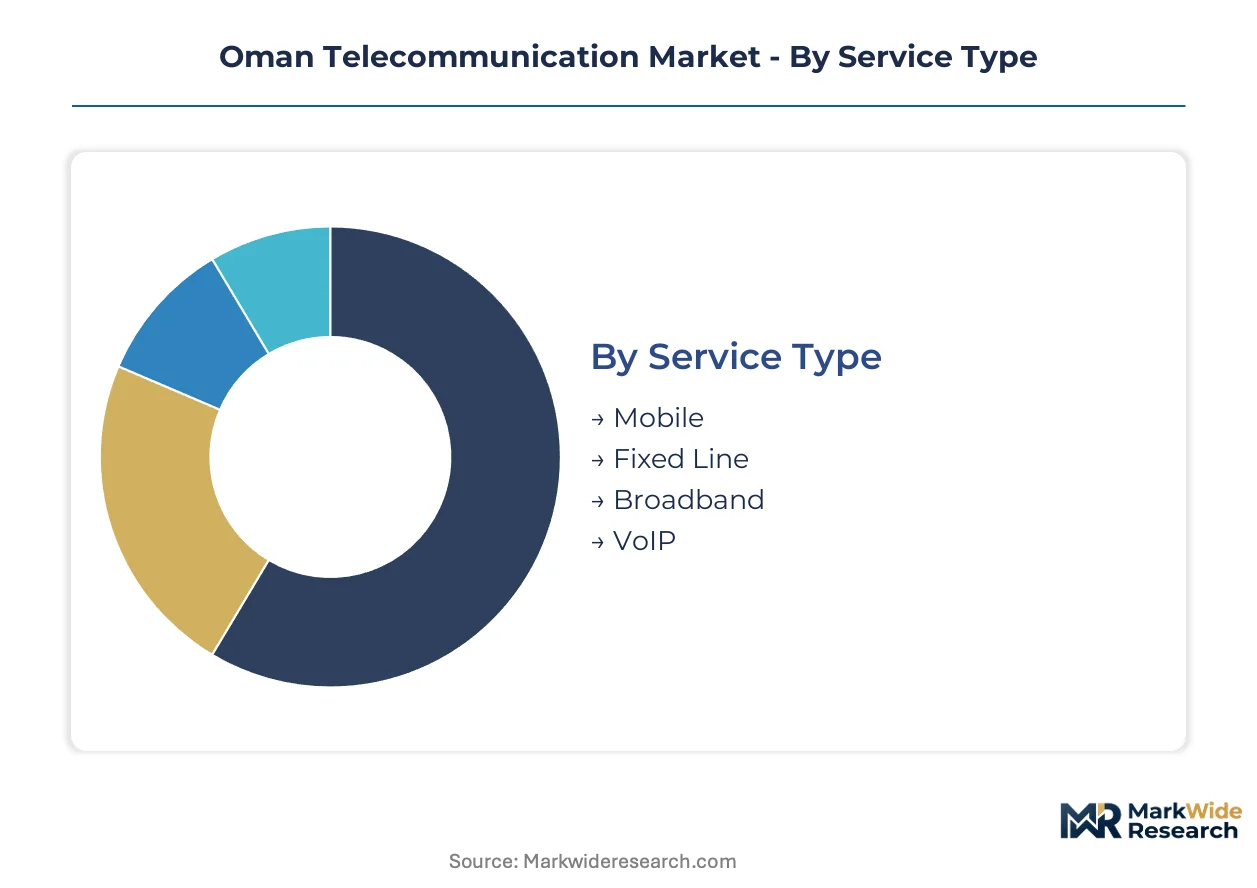
Telecommunication segmentation in Oman reveals how substitution pressures between wireless and wireline technologies reshape operator investment priorities. Service type and technology splits expose where fiber deployment economics clash with fixed wireless access alternatives.
Service Type:
Mobile services face intensifying substitution pressure from over-the-top voice applications, while fixed-line infrastructure competes against 5G fixed wireless access in suburban expansion zones.
- Mobile:Voice and data transmission across cellular networks operating from 700 MHz to 3.5 GHz spectrum bands. Smartphone penetration in Muscat's technology corridor and Duqm Special Economic Zone drives demand for unlimited data plans with strict latency requirements for enterprise mobility.
- Fixed Line:Traditional copper and fiber-based voice connectivity delivered through physical premises connections. Government administrative buildings and banking headquarters in central business districts sustain demand for guaranteed service-level agreements despite wireless substitution.
- Broadband:High-speed internet access through DSL, fiber-to-the-home, and cable infrastructure. Residential compounds in Al Batinah coastal governorates concentrate subscriber growth where Oman Broadband's national strategy prioritizes fiber trenching.
- VoIP:Voice over Internet Protocol services transmitting calls through packet-switched data networks. Small and medium enterprises in Salalah's port expansion zone adopt cloud-based unified communications to bypass traditional international calling tariffs.
Mobile retains volume leadership; Broadband holds the steepest expansion curve.
Technology:
Cost tier differentiation separates capital-intensive fiber deployment from spectrum-dependent wireless alternatives, with satellite bridging coverage gaps where terrestrial economics fail.
- 3G:Third-generation cellular technology providing basic mobile internet through UMTS/HSPA standards. Remote fishing villages in Al Wusta Governorate and legacy industrial telemetry systems sustain residual 3G dependency where 4G buildout remains uneconomical.
- 4G LTE:Fourth-generation Long Term Evolution delivering peak download speeds exceeding 100 Mbps through OFDMA modulation. Vodafone Oman and Ooredoo compete aggressively on 4G pricing to anchor residential market share in densely populated urban corridors.
- Fiber Optic:Glass-core transmission infrastructure operating at 1310-1550 nm wavelengths with virtually unlimited bandwidth scalability. Omantel leverages its nationwide fiber backbone to dominate enterprise leased-line contracts in oil and gas extraction zones.
- Satellite:Geostationary and low-earth orbit connectivity bypassing terrestrial infrastructure requirements. Offshore drilling platforms and remote desert exploration camps rely on satellite backhaul where fiber deployment costs multiply across mountainous Al Hajar terrain.
Fiber Optic commands premium pricing tiers; Satellite maintains irreplaceable niche positioning.
End User:
Application-driven segmentation separates consumption patterns between bandwidth-intensive enterprise operations and price-sensitive residential households.
- Residential:Individual households and family units consuming streaming video, social media, and remote work connectivity. Apartment complexes in Muscat's technology corridor generate concentrated demand for symmetrical fiber speeds supporting multiple simultaneous 4K video streams.
- Business:Small and medium enterprises requiring reliable internet for cloud software, payment processing, and customer communication. Retail chains and hospitality operators in Duqm Special Economic Zone demand redundant connectivity during port logistics peak seasons.
- Government:Public sector institutions including ministries, municipal authorities, and security services with classified data requirements. The Ministry of Transport, Communications and Information Technology's digital economy framework mandates secure dedicated networks for citizen service portals.
- Enterprise:Large corporations with customized wide-area networking, dedicated leased lines, and stringent uptime guarantees. Petroleum Development Oman and international oilfield service contractors require satellite-fiber hybrid architectures for remote extraction site coordination.
Residential generates subscriber volume; Enterprise extracts highest revenue per connection.
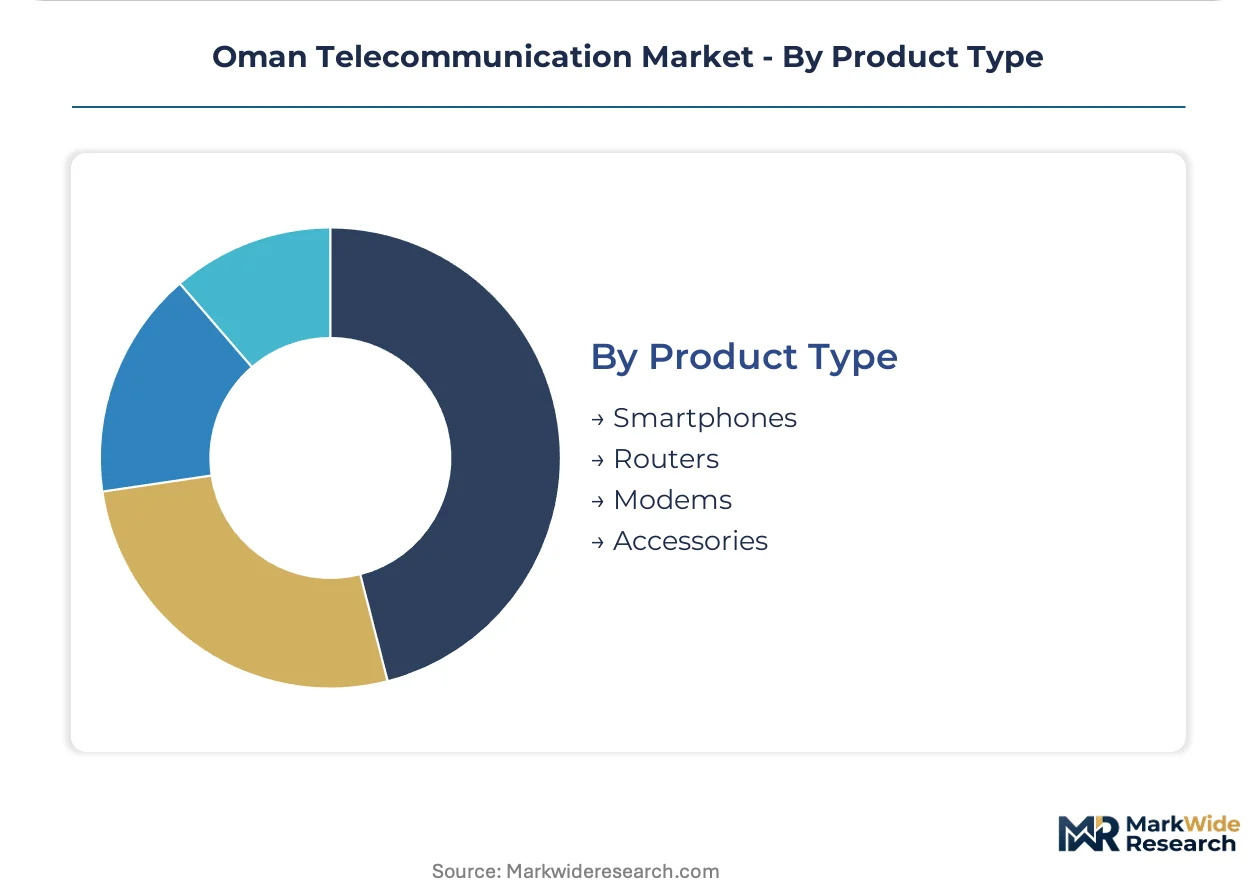
Product Type:
Customer type segmentation distinguishes between device-led purchasing decisions and infrastructure procurement cycles.
- Smartphones:Handheld cellular devices integrating computing, photography, and wireless connectivity functions. 5G-capable flagship models concentrate sales in Muscat's premium retail corridors as subscribers prepare for TRA's forthcoming mmWave spectrum release.
- Routers:Network equipment distributing internet connectivity across multiple local devices through Wi-Fi standards. Enterprise-grade SD-WAN routers see procurement acceleration as oil and gas firms unbundle connectivity from managed service contracts.
- Modems:Customer premise equipment converting incoming signals to usable ethernet or Wi-Fi output. Fiber optic termination units accompany Oman Broadband's residential deployment campaigns in Al Batinah and Ad Dhahirah governorates.
- Accessories:Peripheral equipment including signal boosters, protective cases, charging infrastructure, and audio devices. 5G fixed wireless access customer premises equipment gains traction in Dhofar Governorate where fiber availability lags tourism infrastructure investments.
Smartphones dominate unit shipments; Routers exhibit strongest enterprise procurement momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing-power asymmetry separates Muscat's technology corridor from Dhofar Governorate, where fiber deployment lags tourism infrastructure investments by several years and wireless operators capture temporary premiums.
Muscat Governorate
Enterprise cloud migration and smart city mandates concentrate demand in Muscat's technology corridor. The Telecommunications Regulatory Authority's infrastructure-sharing framework compels active network element coordination among operators in designated coverage zones. Petroleum Development Oman headquarters and international oilfield service contractors anchor enterprise-grade connectivity procurement in the central business district.
Al Batinah Governorate
Residential compounds along the coastal strip generate concentrated fiber-to-the-home demand under Oman Broadband's national strategy. TRA spectrum liberalization policies compress 5G deployment timelines in overlapping buildout zones. Sohar Port's logistics expansion and downstream industrial zones create redundant connectivity requirements for shipping and manufacturing tenants.
Dhofar Governorate
Salalah's port expansion and tourism infrastructure investments outpace fixed broadband availability. The Ministry of Transport, Communications and Information Technology's digital economy framework mandates municipal IoT integration in emerging commercial districts. 5G fixed wireless access deployments capture first-mover advantage before fiber economics justify trenching costs.
Duqm Special Economic Zone
Tax holidays and streamlined licensing for logistics and manufacturing tenants create concentrated demand for redundant connectivity infrastructure. Duqm Special Economic Zone Authority incentives accelerate tenant recruitment ahead of terrestrial fiber completion. Remote extraction camps and offshore drilling platforms in the adjacent interior rely on satellite-fiber hybrid architectures.
Ad Dhahirah Governorate
Mountainous terrain across the Al Hajar range multiplies civil engineering expenses for terrestrial fiber routes compared to flat coastal deployment economics. TRA infrastructure-sharing mandates triggered mandatory arbitration where overlapping buildout plans converged. Ibri's agricultural processing facilities and border trade corridors sustain demand for reliable commercial connectivity despite challenging topography.
Oman Telecommunication Market Competitive Landscape
Concentration sits with infrastructure owners possessing nationwide fiber backbones and government contract relationships. The competitive structure tiers between asset-heavy integrated operators and spectrum-dependent challengers. Two strategic archetypes dominate: fiber backbone owners leveraging fixed-line dominance and mobile-first competitors anchoring share through aggressive 4G LTE pricing. Dominant competitive moves include infrastructure-sharing negotiations under TRA mandate and enterprise service unbundling to capture systems integration contracts.
Within the infrastructure-owner tier, Omantel and Oman Broadband exemplify divergent capital deployment strategies. Vodafone Oman and Ooredoo occupy positions as mobile-first challengers competing on wireless pricing and enterprise satellite connectivity respectively. Awasr represents the specialized fiber retail alternative, while Renna Mobile anchors the mobile virtual network operator segment.
| Leading Market Players |
|---|
| Oman Telecommunications |
| Ooredoo |
| Omani Qatari Telecommunications Company SAOG |
| Renna Mobile |
| Vodafone Oman |
| Oman Broadband |
| Omantel |
| Oman Mobile |
| Awasr |
| Others |
Pricing and Supply Chain Analysis
Scale economies at submarine cable landing stations anchor pricing power for international bandwidth while compressing margins for terrestrial last-mile operators. Oman Broadband's fiber trenching campaigns in Al Batinah and Ad Dhahirah governorates create volume-based price floors that mobile virtual network operators struggle to match without infrastructure ownership.
Pricing Analysis
The customization-premium spread separates enterprise-grade dedicated leased lines from residential fiber-to-the-home subscriptions. Three-tier pricing structure across premium, standard, and economy levels tracks service-level agreement stringency and uptime guarantees. Cost compression in residential broadband intensifies because Vodafone Oman and Ooredoo compete aggressively on 4G LTE pricing to anchor market share. Enterprise buyers exhibit least price sensitivity due to cybersecurity compliance requirements and redundant connectivity mandates for oil and gas extraction zones.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability constraints on Asia-Middle East trade lanes elevate inbound logistics costs for optical fiber cable and 5G base station equipment. Supply concentrates in China, South Korea, and Japan for optical fiber manufacturing, radio frequency components, and network processor chipsets. Raw material dependencies span high-purity silica for fiber cores, rare earth elements for amplifier doping, and advanced printed circuit boards for baseband units. Single-source vulnerability sits with submarine cable landing station equipment where East Asian suppliers dominate. Distribution runs through operator-direct procurement for core network infrastructure and authorized distributor channels for customer premise equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Omani telecom operators face substitution defense against fixed wireless access technologies that bypass fiber trenching costs in Dhofar Governorate and low-density interior zones. 5G mmWave deployments threaten to disintermediate traditional fixed-line incumbents before fiber economics justify infrastructure investment.
For Market Incumbents: Consolidate fiber backbone ownership through Oman Broadband partnership structures and deepen government contract relationships with Petroleum Development Oman. Defend against fixed wireless access substitution by accelerating fiber-to-the-home deployment in Salalah ahead of tourism infrastructure completion. Prioritize vertical integration into submarine cable consortium memberships to secure international bandwidth cost advantages.
For New Entrants and Emerging Players: Anchor in Dhofar Governorate's temporary connectivity gap where fiber availability lags port expansion timelines. Target 5G fixed wireless access deployment for hospitality and logistics tenants before Omantel fiber economics justify trenching. Pursue systems integration contracts bundling connectivity with municipal IoT sensor deployment under the Ministry of Transport, Communications and Information Technology's smart city mandates.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors infrastructure owners with nationwide fiber backbones and government contract relationships over spectrum-dependent mobile challengers. Long-term viability rests on 5G radio access network sharing agreement economics and enterprise service unbundling trends. Monitor Telecommunications Regulatory Authority arbitration outcomes on active network element sharing as inflection indicator for competitive intensity in Al Batinah and Ad Dhahirah governorates.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G Radio Access Network Sharing Agreement | TRA infrastructure-sharing mandates force operational coordination on base station locations in overlapping coverage zones. |
| Submarine Cable Landing Station Diversification | New cable systems at Barka and Salalah reduce single-point-of-failure reliance on existing Muscat infrastructure. |
| Enterprise Service Unbundling | Oil and gas firms procuring raw bandwidth separately from SD-WAN overlay compress operator margins on value-added services. |
| Fixed Wireless Access Pre-emption | 26 GHz and 28 GHz spectrum deployment captures temporary premium pricing before fiber economics justify trenching costs. |
| Open RAN Architecture Migration | Vendor diversification initiatives reshape equipment procurement cycles and compress traditional supplier relationships. |
Research Methodology
Operator-level perspectives from network engineering directors, enterprise sales leads, regulatory affairs managers, and infrastructure procurement officers anchored the qualitative base. Primary interviews combined with secondary validation from Telecommunications Regulatory Authority spectrum allocation records, Ministry of Transport, Communications and Information Technology digital economy framework documents, and operator financial disclosures. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from international bandwidth consumption trends and fiber deployment tracking.
Sensitivity analysis tested forecast outputs against varying assumptions for 5G spectrum auction timing, Oman Broadband fiber trenching acceleration, and Duqm Special Economic Zone tenant recruitment rates. Segmentation dimensions modeled include service type, technology generation, end-user category, and geographic governorate cluster. CAGRs derived from historical subscription growth patterns and projected enterprise cloud migration intensity. Industry-specific inputs encompassed TRA infrastructure-sharing arbitration outcomes and submarine cable landing station capacity expansion timelines.
Material uncertainties — regulatory shifts in spectrum pricing, fiber import tariff changes, and fixed wireless access technology cost curves — sit outside the modeled envelope. Forecasts reflect documented assumptions about TRA policy continuity and enterprise digitization commitment levels. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Nigeria Satellite Communications Market
Telecommunications
South Africa Telecom Tower Market
Telecommunications
France Telecom Market
Telecommunications
Argentina ICT Market
Telecommunications
Mobile Satellite Services (MSS) Market
Telecommunications
Cellular Modem Market
Telecommunications
United Kingdom Telecom Market
Telecommunications
Global Broadband Services Market
Telecommunications
Finland Telecom Market
Telecommunications
Global Policy Management in Telecom Market
Telecommunications
Australia Telecom Market
Telecommunications
Indonesia Volte Market
Telecommunications
LTE Advanced Pro Market
Telecommunications
C-RAN Market
Telecommunications
Machine to Machine (M2M) Services Market