
 Indonesia B2B Telecom Market | 2026-2036
Indonesia B2B Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia B2B Telecom Market Insights
Managed network service revenue is fragmenting across standalone connectivity and value-added platform bundles. PT Telekomunikasi Indonesia (Persero) Tbk leverages its nationwide fiber backbone to dominate wholesale infrastructure access. PT Indosat Ooredoo Hutchison Tbk competes through aggressive SD-WAN packaging for mid-market enterprises. Biznet Networks anchors premium data center interconnect demand in Greater Jakarta's financial district.
Indonesia B2B telecom encompasses dedicated voice, data, and managed infrastructure services sold to organizational rather than consumer buyers, typically governed by service level agreements specifying latency thresholds below 50 milliseconds and uptime guarantees exceeding 99.9%. These services enable operational continuity for banking systems, supply chain platforms, and government digital services across the archipelago. Voice Services retains the largest revenue base among service type categories, though Cloud Solutions generates the fastest expansion as Indonesian enterprises migrate workloads from on-premises servers. Fiber Optic technology leads capital deployment, while SD-WAN adoption accelerates among multi-branch retailers seeking centralized policy management across dispersed locations.
Kominfo's broadband acceleration mandate and BSI licensing requirements for network infrastructure operators shape competitive entry and service quality benchmarks across Indonesian territories. The country's national cyber and crypto agency, BSSN, imposes data sovereignty and encryption standards that elevate compliance costs for foreign-hosted cloud offerings. Stakeholders must weigh the trade-off between capital-intensive fiber builds and partnership-dependent cloud resale models as enterprise buyers demand unified connectivity-to-application stacks.
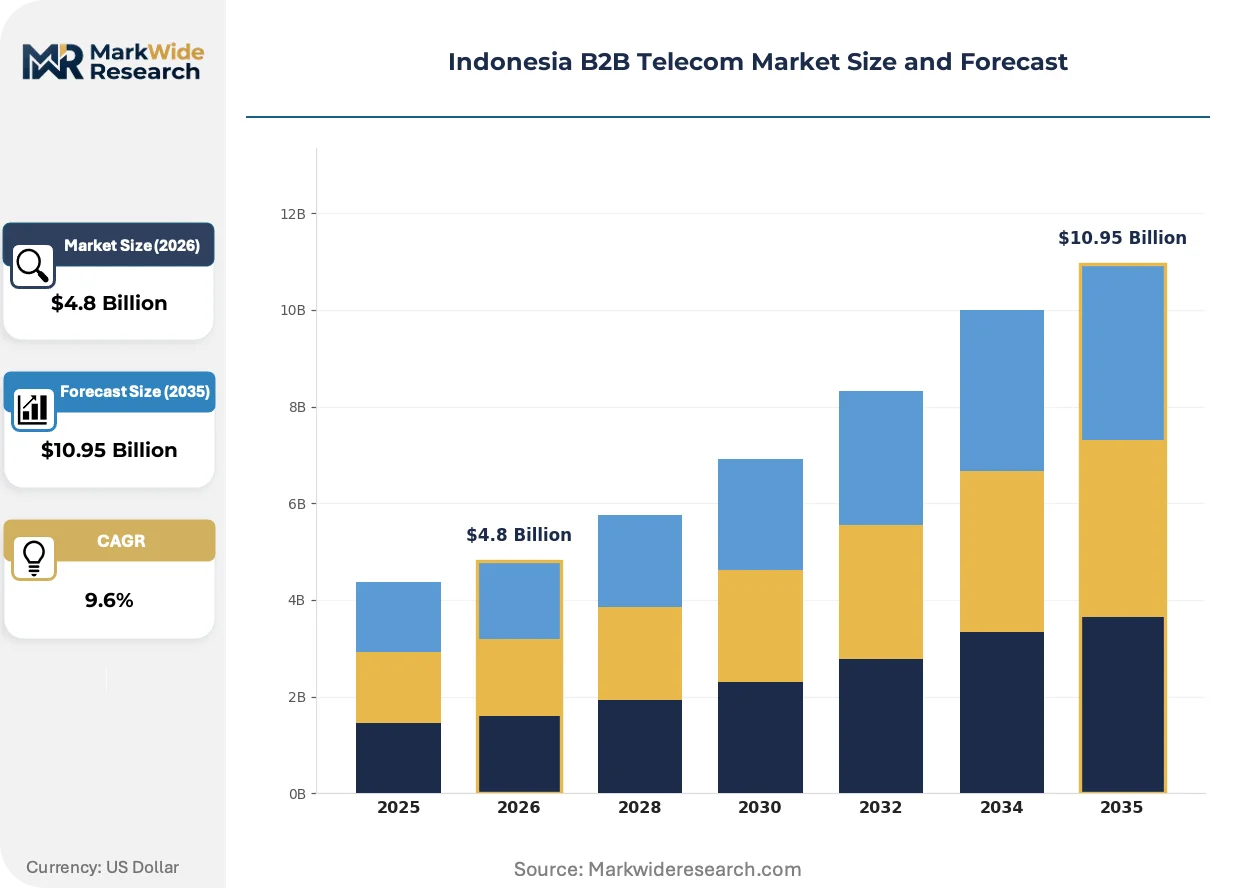
Market Dynamics
Enterprise cloud migration is collapsing traditional voice-centric revenue pools as Indonesian financial institutions demand unified connectivity-to-application stacks. Kominfo's broadband acceleration mandate and BSSN data sovereignty requirements are forcing infrastructure operators to choose between capital-intensive fiber builds and partnership-dependent resale models.
Growth Catalysts
- Palapa Ring Backbone Expansion:The government's fiber optic infrastructure program is extending high-capacity connectivity to secondary cities and outer islands, enabling enterprise-grade services beyond Jakarta and Surabaya.
- Financial Services Cloud Migration:Indonesian banks and insurance providers are accelerating workload shifts from on-premises servers to hybrid cloud environments, driving demand for low-latency dedicated connectivity.
- SD-WAN Technology Maturation:Software-defined wide area networking is enabling multi-branch retailers to centralize policy management across dispersed archipelago locations without proprietary hardware lock-in.
Market Restraints
- Submarine Cable Concentration Risk:International bandwidth relies on limited transpacific and intra-Asian cable systems landing in Java, creating single-point-of-failure exposure for enterprise connectivity.
- BSSN Compliance Cost Burden:Indonesia's national cyber agency imposes data localization and encryption standards that elevate operational expenses for foreign-hosted cloud service delivery.
- Last-Mile Fiber Deployment Economics:The archipelago geography drives per-kilometer construction costs to levels that strain returns outside dense urban corridors.
Strategic Opportunities
- Eastern Indonesia Penetration:Makassar, Manado, and Papua present underdeveloped enterprise connectivity markets where Palapa Ring termination points create first-mover infrastructure advantages.
- Edge Computing Convergence:The intersection of 5G network slicing and distributed cloud architecture enables ultra-low latency applications for manufacturing and logistics automation.
- BSI Licensing Framework:Indonesia's standardization body certification requirements for network infrastructure operators create compliance-based differentiation for certified domestic providers.
Industry Challenges
- IPv4 Address Exhaustion:Indonesian enterprises face migration complexity and dual-stack operational overhead as regional IPv4 pools deplete and IPv6 transition timelines compress.
- Legacy TDM System Integration:Banking and government buyers maintain substantial circuit-switched voice infrastructure, forcing hybrid network architectures that complicate SD-WAN deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia B2B Telecom Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.95 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice Services, Data Connectivity, Managed Services, Cloud Solutions Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Government Technology: Mobile Broadband, Fiber Optic, VoIP, SD-WAN Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Hosting |
| Companies Covered | PT Telekomunikasi Indonesia (Persero) Tbk, PT Telekomunikasi Selular (Telkomsel), PT Indosat Ooredoo Hutchison Tbk, PT XL Axiata Tbk, PT Smartfren Telecom Tbk, Biznet Networks, PT Mora Telematika Indonesia Tbk (Moratelindo), PT Lintasarta Jasatama, PT Cyberindo Aditama (CBN), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia B2B Telecom Market Trends and Innovations
Network function virtualization is collapsing hardware-defined boundaries between connectivity layers, enabling Indonesian operators to deliver software-configurable enterprise services. Three technology and demand shifts are restructuring competitive positioning.
SD-WAN is collapsing the distinction between MPLS and broadband internet as primary enterprise transport. Indonesian multi-branch retailers are adopting hybrid connectivity within eighteen-month procurement cycles. This compression is enabling mid-market buyers to access carrier-grade reliability without premium dedicated circuit pricing.
Kominfo's broadband acceleration mandate is requiring universal service obligation contributions from licensed operators. The policy is redirecting capital toward outer island fiber extension rather than Jakarta-centric capacity expansion. Eastern Indonesia enterprise segments are responding with accelerated digital service adoption as latency thresholds fall below 50 milliseconds.
Enterprise buyers are consolidating vendor relationships from multi-supplier connectivity and cloud arrangements toward single-stack platform contracts. System integrators and direct carrier sales teams are displacing traditional telecom brokers in Surabaya and Bandung procurement processes. Financial services institutions in Greater Jakarta are leading this consolidation, demanding unified SLA accountability across infrastructure and application layers.
Indonesia B2B Telecom Market Segmentation
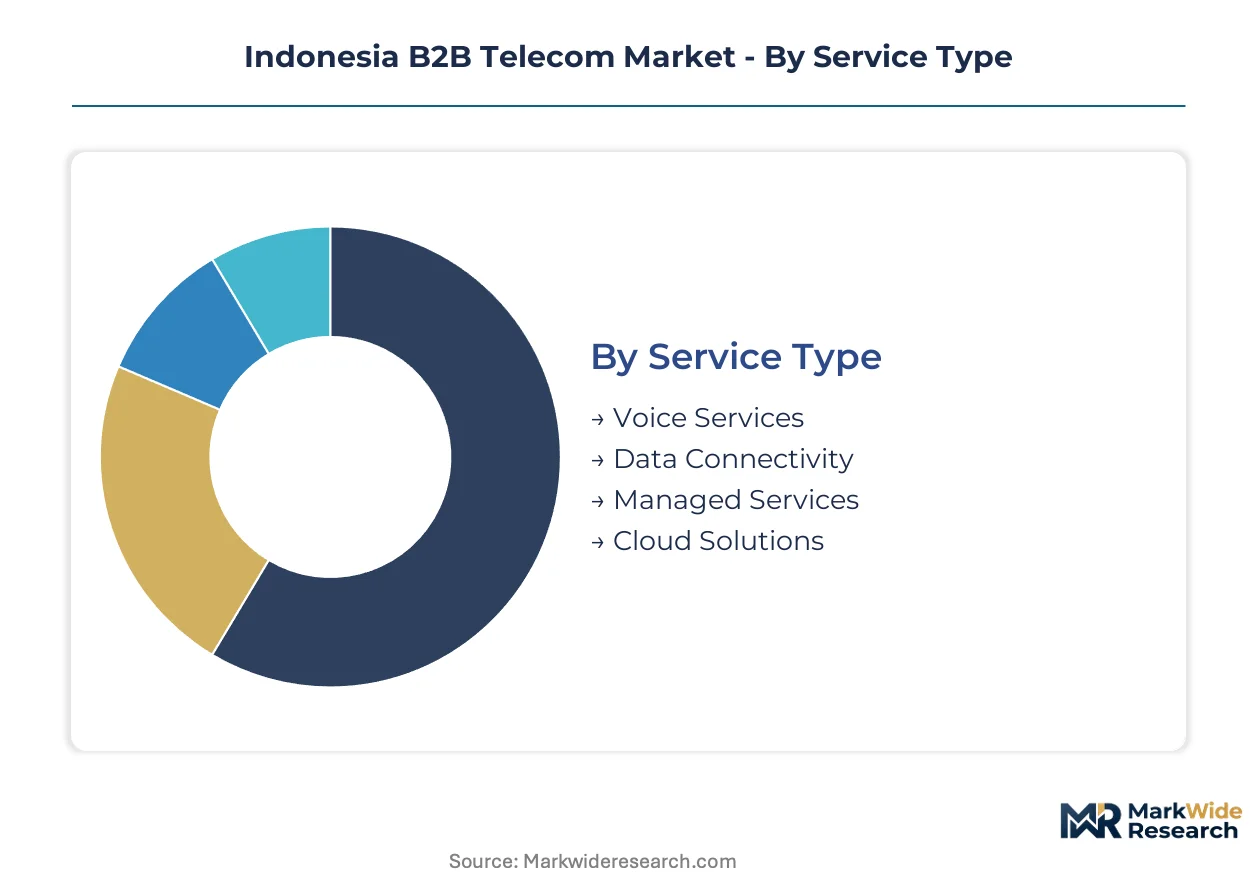
Indonesia's archipelago geography and regulatory fragmentation create distinct service requirements across enterprise tiers. Segmentation reveals how Palapa Ring infrastructure extension and BSSN compliance mandates reshape procurement patterns among organizational buyers.
Service Type:
Mature revenue pools coexist with emerging technology bundles as enterprise buyers consolidate vendor relationships.
- Voice Services:Circuit-switched and VoIP-based dedicated voice circuits retain the largest revenue base across Indonesian banking and government accounts. Legacy TDM infrastructure in Jakarta financial institutions sustains demand despite cloud migration pressures, though procurement teams increasingly bundle voice within unified communication platforms.
- Cloud Solutions:Hybrid and multi-cloud connectivity services generate the steepest expansion curve as financial services institutions migrate core workloads. BSSN data sovereignty requirements and encryption standards elevate compliance costs, driving demand for domestic cloud interconnect and managed security overlays.
- Data Connectivity:Dedicated internet access and private line services form the foundational layer for enterprise WAN architecture.
- Managed Services:Outsourced network operations and security monitoring appeal to mid-market enterprises lacking internal IT capacity.
Voice Services retains volume leadership; Cloud Solutions holds the steepest expansion curve.
Customer Type:
Procurement sophistication varies sharply across the organizational size spectrum, with compliance thresholds acting as market gatekeepers.
- Large Corporations:Multinational and domestic conglomerates demand unified SLA accountability across infrastructure and application layers. These buyers in Greater Jakarta and Surabaya consolidate multi-supplier arrangements toward single-stack platform contracts, driving carrier investment in SD-WAN and edge computing capabilities.
- Government:Central and regional government agencies represent concentrated demand anchored by Kominfo's broadband acceleration mandate and universal service obligations. Palapa Ring termination points in Eastern Indonesia unlock digital service adoption as latency thresholds compress below 50 milliseconds.
- Medium Enterprises:Surabaya and Bandung manufacturing clusters seek cost-optimized connectivity with managed security.
- Small Enterprises:Price-sensitive buyers in secondary cities rely on bundled broadband and basic cloud resale.
Government segments anchor infrastructure investment cycles; Large Corporations command premium pricing through integrated platform procurement.
Technology:
Capital deployment intensity separates fiber-centric infrastructure plays from software-configurable overlay solutions.
- Fiber Optic:Palapa Ring backbone expansion and metro fiber builds absorb the majority of operator capital expenditure. Per-kilometer construction economics strain returns outside dense urban corridors, concentrating high-capacity routes between Jakarta, Surabaya, and emerging Eastern Indonesia termination points.
- SD-WAN:Software-defined architectures enable multi-branch retailers to centralize policy management across dispersed archipelago locations without proprietary hardware lock-in. PT Indosat Ooredoo Hutchison Tbk competes aggressively through packaged SD-WAN offerings targeting mid-market procurement cycles compressed to eighteen months.
- Mobile Broadband:4G and emerging 5G network slicing address temporary connectivity and backup requirements.
- VoIP:Session initiation protocol trunking displaces legacy PSTN connectivity in greenfield deployments.
Fiber Optic dominates capital allocation; SD-WAN gains share fastest through compressed enterprise procurement timelines.
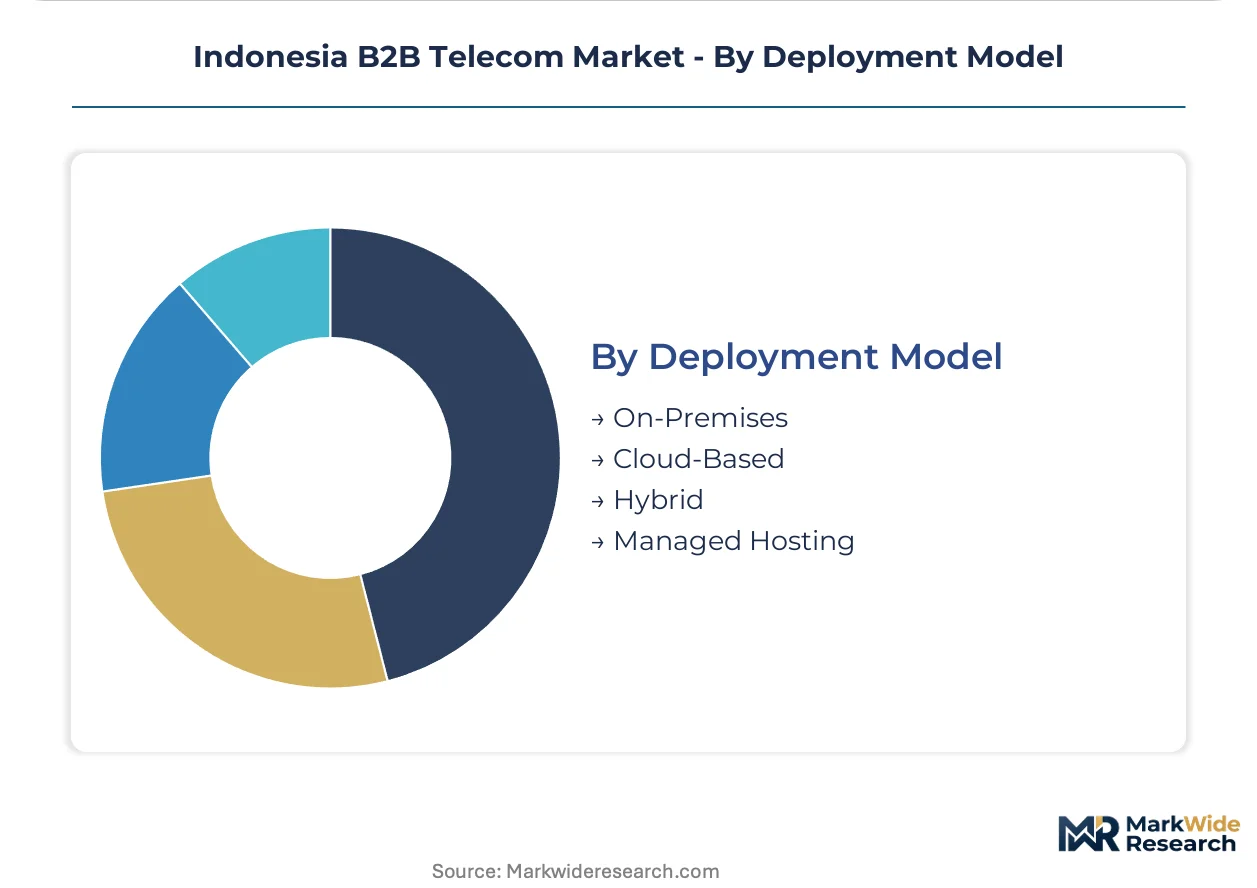
Deployment Model:
Risk tolerance and compliance posture determine organizational preferences for control versus outsourced operations.
- Hybrid:Split workload architectures combining on-premises infrastructure with public cloud resources capture dominant preference among Indonesian financial institutions. BSSN encryption standards and data localization requirements force explicit architectural decisions about sovereignty-critical versus scalable workloads.
- Cloud-Based:Fully outsourced infrastructure appeals to digital-native enterprises and foreign market entrants seeking rapid scaling without capital commitment. Foreign-hosted offerings face margin pressure from domestic compliance costs and competing local cloud partnerships.
- On-Premises:Legacy core banking systems and government classified networks retain captive infrastructure.
- Managed Hosting:Colocation and private cloud instances serve regulated industries requiring physical control with operational outsourcing.
Hybrid deployments concentrate enterprise decision-making; Cloud-Based models face steepest compliance cost headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise connectivity consumption across Indonesian sub-regions diverges sharply: Java-based financial institutions demand unified cloud-to-edge stacks, while Eastern Indonesia buyers prioritize backbone availability over application-layer sophistication.
Greater Jakarta
Financial services institutions anchor premium demand for low-latency dedicated circuits and managed security overlays. Kominfo's broadband acceleration mandate enforces universal service obligations that redirect carrier investment toward national backbone extension. The Sudirman Central Business District concentrates procurement of hybrid cloud interconnect and SD-WAN bundles as banks consolidate multi-supplier arrangements.
East Java and Surabaya
Manufacturing conglomerates and mid-market distributors drive cost-optimized connectivity procurement with compressed eighteen-month technology refresh cycles. BSI licensing requirements for network infrastructure operators shape competitive entry, elevating compliance-based differentiation for certified domestic providers. The Surabaya-Bangil industrial corridor hosts expanding enterprise demand for centralized policy management across dispersed branch locations.
Sulawesi and Makassar
Palapa Ring fiber optic backbone termination points unlock first-mover infrastructure advantages in previously underserved enterprise segments. The national cyber and crypto agency imposes data sovereignty standards that elevate operational expenses for foreign-hosted cloud delivery. Makassar's emerging port and logistics automation clusters generate nascent demand for ultra-low latency edge computing convergence.
Papua and Eastern Archipelago
Per-kilometer fiber construction economics strain returns outside dense urban corridors, constraining carrier capital deployment. Government digital service mandates and classified network requirements sustain captive on-premises infrastructure investment. Jayapura and Sorong procurement teams prioritize backbone availability and submarine cable redundancy over application-layer value-added services.
Sumatra and Medan
Palm oil conglomerates and plantation-based supply chain platforms generate distributed enterprise demand across challenging terrain. Last-mile deployment economics favor wireless backup and mobile broadband network slicing for temporary connectivity requirements. The Medan-Belawan logistics corridor anchors regional data center interconnect demand as latency thresholds compress below fifty milliseconds.
Indonesia B2B Telecom Market Competitive Landscape
Capability concentration sits with state-affiliated infrastructure owners; scale advantage sits with integrated mobile-fiber operators. The vendor base organizes around three strategic archetypes: backbone-dominant incumbents leveraging nationwide fiber assets, agile challengers packaging software-defined overlays for mid-market compression, and specialist data center interconnect providers capturing financial district premium. Dominant competitive moves include Palapa Ring termination point preemption in Eastern Indonesia and partnership-dependent cloud resale model construction to bypass capital-intensive builds.
Within the backbone-dominant tier, PT Telekomunikasi Indonesia (Persero) Tbk and PT Indosat Ooredoo Hutchison Tbk occupy positions reflecting divergent strategic postures. Telkom's state-affiliated structure exemplifies infrastructure control through captive fiber deployment. Indosat Ooredoo Hutchison represents challenger-scale aggression in SD-WAN packaging and compressed procurement cycle capture. Biznet Networks anchors specialist positioning in Greater Jakarta's premium interconnect segment.
| Leading Market Players |
|---|
| PT Telekomunikasi Indonesia (Persero) Tbk |
| PT Telekomunikasi Selular (Telkomsel) |
| PT Indosat Ooredoo Hutchison Tbk |
| PT XL Axiata Tbk |
| PT Smartfren Telecom Tbk |
| Biznet Networks |
| PT Mora Telematika Indonesia Tbk (Moratelindo) |
| PT Lintasarta Jasatama |
| PT Cyberindo Aditama (CBN) |
| Others |
Pricing and Supply Chain Analysis
Greater Jakarta's fiber-dense metro infrastructure concentrates national backbone capacity, granting incumbent operators asymmetric leverage in enterprise contract negotiations. Kominfo's universal service obligations redirect carrier capex toward Eastern Indonesia extension, compressing margins on Java-centric premium interconnect as supply expands.
Pricing Analysis
Long-term offtake contracts dominate enterprise procurement, with three-year SLAs locking dedicated circuit pricing below spot-market broadband rates. Price differentiation rests on latency tier certification and BSSN compliance bundling, where sub-50ms guarantees command substantial premiums over best-effort alternatives. Pricing pressure stems from SD-WAN commoditization as Indosat Ooredoo Hutchison packages software overlays at mid-market price points. Large financial institutions in the Sudirman CBD exhibit lowest price sensitivity, while Surabaya manufacturing clusters drive hardest bargain compression.
Supply Chain Analysis
Submarine cable concentration between Singapore and Java exposes Indonesian B2B connectivity to single-route vulnerability, with transpacific systems landing exclusively in Jakarta and Batam. Equipment sourcing draws from China, South Korea, and Finland for optical transmission gear, while fiber draw and cable manufacturing centers on domestic plants in Tangerang and Surabaya. Tariff exposure on Chinese optical components elevates deployment costs for Palapa Ring extension segments. Distribution runs through carrier-direct enterprise sales teams and certified system integrators, bypassing traditional telecom broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
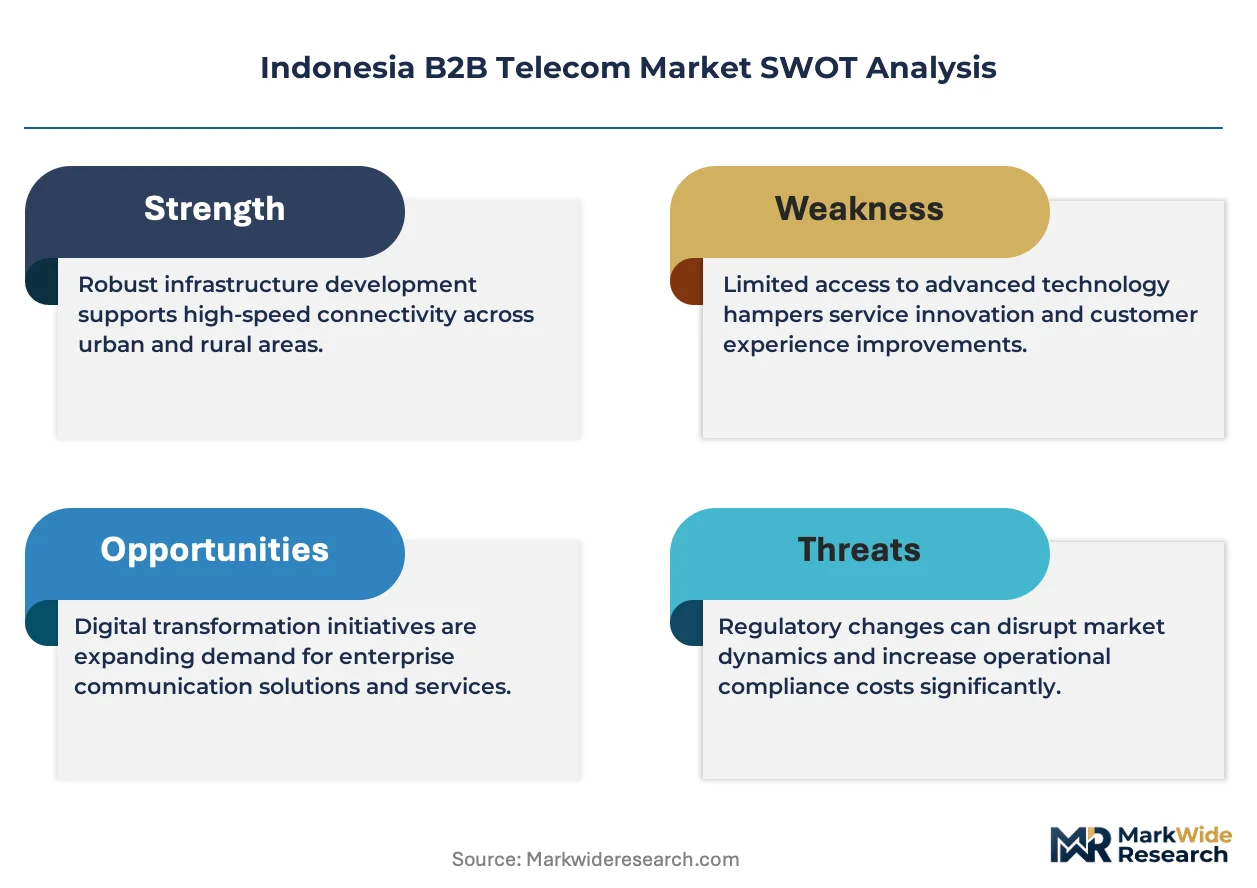
Indonesia B2B telecom constitutes a high-growth disruption as Palapa Ring backbone completion collapses Eastern Indonesia latency thresholds below enterprise-grade thresholds. BSSN data sovereignty mandates and Kominfo broadband acceleration create simultaneous regulatory tailwind and compliance cost inflection.
For Market Incumbents: Insulate core fiber assets through captive Palapa Ring termination point preemption in Makassar and Papua, denying challengers infrastructure leverage. Deepen vertical integration into domestic data center construction to capture cloud interconnect margin pools threatened by hyperscaler partnership models. BSI licensing certification creates defendable moat against unlicensed foreign cloud resale entrants. For New Entrants and Emerging Players: Eastern Indonesia enterprise segments present the most penetrable white-space, where Palapa Ring availability meets nascent digital procurement sophistication. Target Surabaya-Bandung mid-market manufacturing with compressed eighteen-month SD-WAN refresh cycles, displacing legacy MPLS brokers through software-configurable policy management. Go-to-market leverage rests on Kominfo universal service obligation co-investment structures for outer island fiber extension. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate-affiliated captive telecom units lacking standalone BSI certification or Palapa Ring access rights. Long-term viability favors operators with integrated fiber-cloud-edge stacks capable of unified SLA accountability. The signal to watch is BSSN enforcement intensity against foreign-hosted cloud delivery, which would accelerate domestic infrastructure valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Palapa Ring Termination Preemption | First-mover fiber access in Makassar and Jayapura locks Eastern Indonesia enterprise demand before competitors. |
| BSI Licensing Certification Investment | Compliance-based differentiation elevates domestic operators above unlicensed foreign cloud resale competitors. |
| SD-WAN Platform Integration | Software-defined overlays capture mid-market procurement compression away from legacy MPLS broker networks. |
| Domestic Data Center Buildout | Captive cloud interconnect capacity captures margin pools threatened by hyperscaler partnership dependency. |
| Edge Computing Convergence | 5G network slicing and distributed architecture enable ultra-low latency logistics automation in Surabaya corridor. |
Research Methodology
A spread of perspectives from network infrastructure executives, enterprise IT procurement officers, regulatory compliance leads, and system integrator technical architects converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against Kominfo policy circulars, BSSN encryption standards documentation, Palapa Ring project disclosures, and operator SEC filings. Bottom-up service revenue modeling triangulated against top-down national broadband penetration targets.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with enterprise cloud migration velocity and fiber deployment economics as primary demand and supply levers. Segmentation dimensions modeled encompass service type, customer tier, technology deployment, and regional infrastructure maturity. CAGRs derived from weighted scenario analysis of Palapa Ring completion timelines and BSSN enforcement trajectories, with SD-WAN adoption curves and submarine cable redundancy investments as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in rupiah volatility, sovereign debt financing costs, or transpacific cable system reliability would shift the trajectory materially. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Global LTE and 5G Broadcast Market
Telecommunications
Global GPON Technology Market
Telecommunications
Thailand ICT Market
Telecommunications
Peru Telecom Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Egypt Telecom Market
Telecommunications
Switzerland Telecom Market
Telecommunications
Singapore Telecom Market
Telecommunications
Global 5G Base Station Market
Telecommunications
Indonesia ICT Market
Telecommunications
Mobile Virtual Network Operator (MVNO) Market
Telecommunications
Voice Communication Control System Market
Telecommunications
Oman Telecommunication Market
Telecommunications
Dialer Market
Telecommunications
Promotional Sms Market
Telecommunications
Global SS7 Market