
 Saudi Arabia Small Home Appliances Market | 2026-2036
Saudi Arabia Small Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Small Home Appliances Market Analytics
Subscription-based filter replacement programs for coffee makers and air purifiers is recalibrating how manufacturers monetize ongoing customer relationships. LG Electronics leverages its service network to anchor recurring revenue streams across urban Saudi households. Samsung Electronics competes through software-defined appliance features that extend product lifecycles beyond hardware refresh cycles. Haier specializes in localized product configurations that navigate voltage stability and climate conditions specific to the Gulf region.
Small home appliances comprise electrically powered portable devices designed for domestic tasks, typically operating below 2,500 watts with plastic or stainless steel housings, microprocessor-controlled heating elements, and safety interlock mechanisms engineered for countertop or floor placement. These products serve food preparation, beverage brewing, cleaning, and climate comfort functions within residential and hospitality environments. The product type dimension shows coffee makers and blenders capturing disproportionate attention from Saudi consumers upgrading kitchen routines, while the distribution channel structure tilts toward online retail and supermarket chains that control last-mile access across the Kingdom's dispersed population centers. End user segmentation reveals households as the volume base, with hotels and restaurants in Makkah and Medina generating concentrated seasonal demand spikes.
The Saudi Standards, Metrology and Quality Organization (SASO) enforces mandatory energy efficiency labeling and electrical safety certifications that determine market access for imported small appliances. The Saudi Food and Drug Authority (SFDA) regulates food-contact materials and appliance hygiene standards for devices processing consumables. The General Authority for Competition monitors pricing practices and distribution agreements to prevent channel exclusivity that would limit consumer choice. Stakeholders must monitor how SASO's expanding technical regulations on smart home interoperability will reshape product development priorities and supplier qualification requirements.
Market Dynamics
SASO energy efficiency mandates are compressing product development cycles while subscription-based service models are rewriting how manufacturers capture lifetime value from Saudi households.
Growth Catalysts
- Smart home interoperability mandates:SASO expanding technical regulations on connected appliance standards is forcing manufacturers to embed IoT capabilities as baseline features.
- Young urban household formation:Riyadh and Jeddah demographics favor compact, connected kitchen devices that align with smaller living spaces and dual-income routines.
- Hospitality sector clustering:Hotels and restaurants in Makkah and Medina generate concentrated seasonal demand spikes for commercial-grade small appliances.
Market Restraints
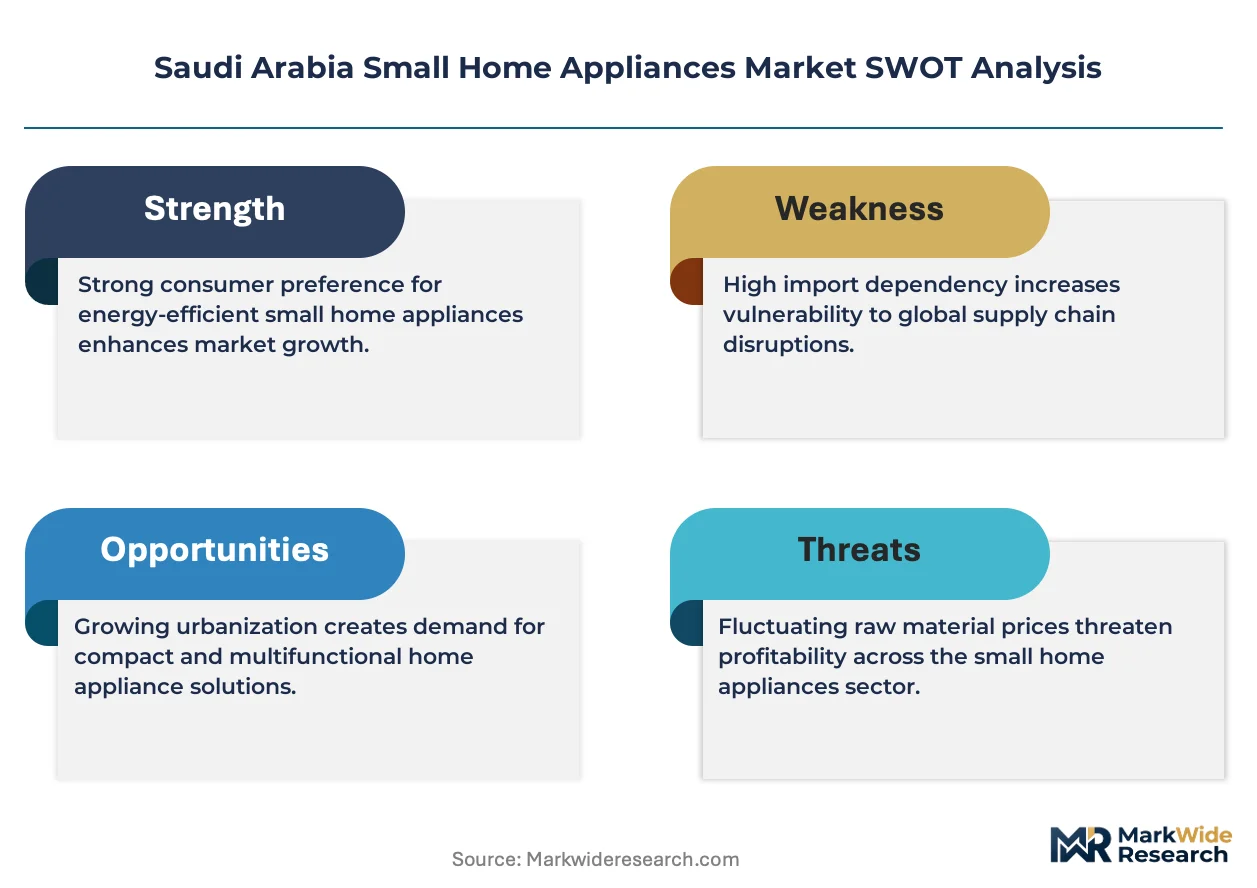
- Copper and semiconductor input volatility:Heating element and control board costs fluctuate with commodity markets, squeezing margin structures on entry-tier products.
- East Asian supply concentration:Component sourcing clusters in specific manufacturing zones create vulnerability to shipping disruptions through Red Sea corridors.
- Voltage stability requirements:Gulf region grid conditions demand hardened power management circuits that add BOM cost versus standard international variants.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar retail infrastructure lags Riyadh and Jeddah, presenting whitespace for distribution network expansion.
- Filter subscription anchoring:Recurring revenue models for coffee maker and air purifier consumables build predictable cash flows beyond hardware sales.
- SASO efficiency labeling differentiation:Premium positioning through top-tier energy ratings commands shelf space and price premiums in supermarket channels.
Industry Challenges
- Embedded software talent scarcity:Connected appliance firmware development requires specialized skill sets in short supply within the Kingdom's labor market.
- SASO certification timeline compression:Expanding technical regulations demand faster retesting cycles that strain product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Small Home Appliances Market |
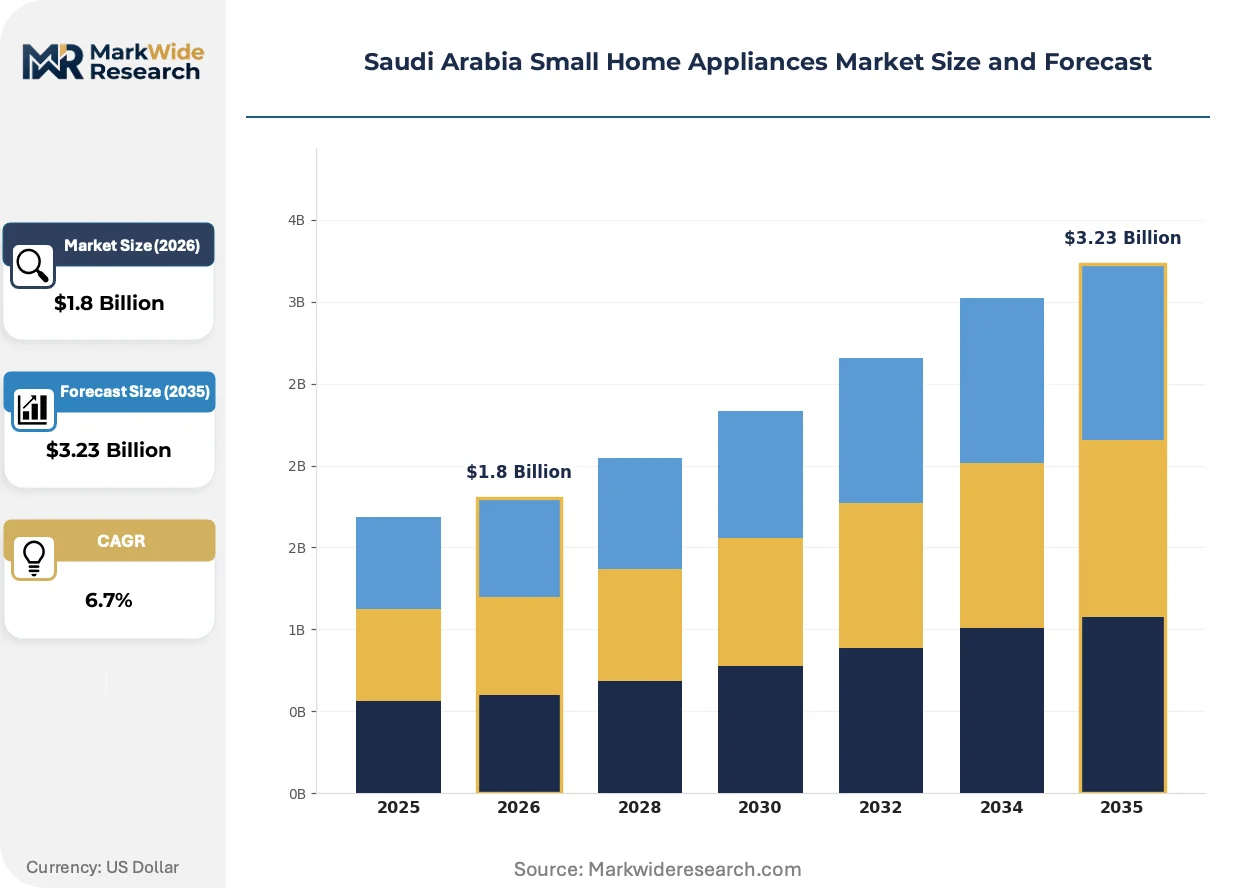
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toasters, Mixers, Blenders, Coffee Makers End User: Households, Hotels, Restaurants, Cafés Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | LG Electronics, Whirlpool, Electrolux Arabia, Toshiba Lifestyle Products, Hisense, Haier, Samsung Electronics, Godrej Group, Panasonic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Small Home Appliances Market Evolving Landscape
Software-defined features and localized hardware configurations are displacing standardized global product portfolios as manufacturers adapt to Saudi-specific operating conditions and consumer expectations.
AI-powered energy optimization in coffee makers and climate devices is rewriting how appliances manage power draw during peak grid hours. Young urban households in Riyadh are adopting these capabilities fastest, treating automated efficiency as a standard expectation rather than premium add-on. This compression of feature differentiation into base product tiers is eroding price premiums for legacy non-connected models.
SASO mandatory energy efficiency labeling requirements are reshaping supplier qualification criteria for market access. Manufacturers must now submit products for standardized testing protocols that measure standby power and active consumption across multiple operating modes. Importers are responding by pre-qualifying factories against SASO technical regulations before production commitments, front-loading compliance costs into sourcing decisions.
After-sales service unbundling is fragmenting traditional warranty bundling as independent repair networks and manufacturer-direct subscription programs compete for maintenance revenue. Supermarket chains controlling last-mile access are experimenting with in-store service desks that handle basic repairs and filter replacements. This channel experimentation is most visible in Jeddah's retail corridors where consumer expectations for immediate resolution run highest.
Saudi Arabia Small Home Appliances Market Segmentation
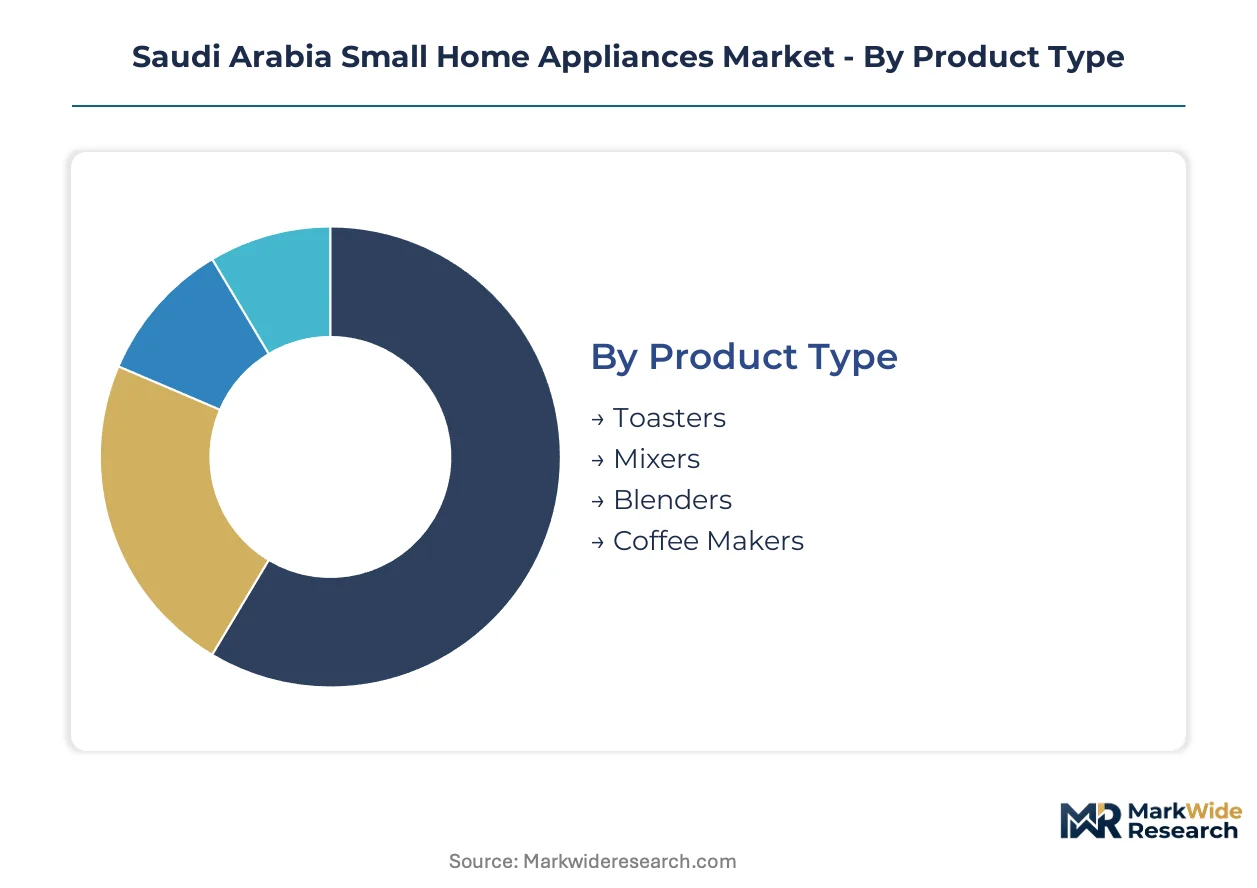
Segmentation in the Saudi Arabia Small Home Appliances Market reveals how capital deployment, regulatory compliance, and channel access create divergent competitive arenas. Manufacturers must calibrate product specifications and pricing architectures to distinct buyer profiles across household, hospitality, and retail segments.
Product Type:
Capital intensity varies sharply across product categories, with coffee makers demanding the highest upfront investment in heating element engineering and IoT integration while toasters require minimal R&D expenditure.
- Coffee Makers:These devices integrate precision temperature control systems, microprocessor-managed brewing cycles, and increasingly SASO-mandated smart home connectivity modules. Riyadh's young urban households drive demand for espresso and capsule systems that align with smaller living spaces and dual-income morning routines.
- Blenders:High-torque motor assemblies and hardened blade alloys distinguish commercial-grade units from residential variants. Hotels and restaurants in Makkah and Medina generate concentrated seasonal demand for industrial-capacity models during pilgrimage periods.
- Mixers:Planetary gear mechanisms and variable speed controllers define performance tiers across stand and hand-held configurations.
- Toasters:Basic resistive heating elements and mechanical timing mechanisms dominate this commoditized category with minimal differentiation headroom.
Most installed capacity flows through coffee makers. Expansion is steepest in blenders.
End User:
Customer procurement patterns separate volume-driven household segments from specification-intensive commercial buyers with distinct service expectations.
- Households:Riyadh and Jeddah's young urban households anchor volume demand for compact, connected kitchen devices. Dual-income routines and smaller residential footprints favor multi-function appliances with automated operation modes.
- Hotels:Properties in Makkah and Medina require commercial-grade durability ratings and rapid service turnaround capabilities to manage seasonal pilgrimage surges.
- Restaurants:Food service operators prioritize NSF-equivalent hygiene certifications and continuous-duty motor ratings for back-of-house reliability.
- Cafés:Specialty beverage operators demand precision temperature stability and brand-aligned aesthetic configurations for front-of-house visibility.
Households absorb the majority of unit shipments. Commercial segments command the steepest price premiums.
Distribution Channel:
Channel economics determine margin capture, with direct-to-consumer platforms offering superior lifetime value visibility compared to wholesale intermediaries.
- Online Retail:E-commerce platforms provide manufacturers with direct access to Riyadh and Jeddah's tech-adopter households while enabling subscription-based filter replacement programs that anchor recurring revenue streams.
- Supermarkets:Chains controlling last-mile access across the Kingdom's dispersed population centers leverage shelf space negotiations to extract promotional concessions.
- Specialty Stores:Focused retailers in Jeddah's commercial corridors serve premium buyers seeking immediate product demonstration and after-sales service integration.
- Wholesale:Bulk procurement channels supply hospitality sector clusters with volume pricing and consolidated logistics for property development projects.
Supermarkets move the highest unit volumes. Online retail is gaining share fastest among urban demographics.
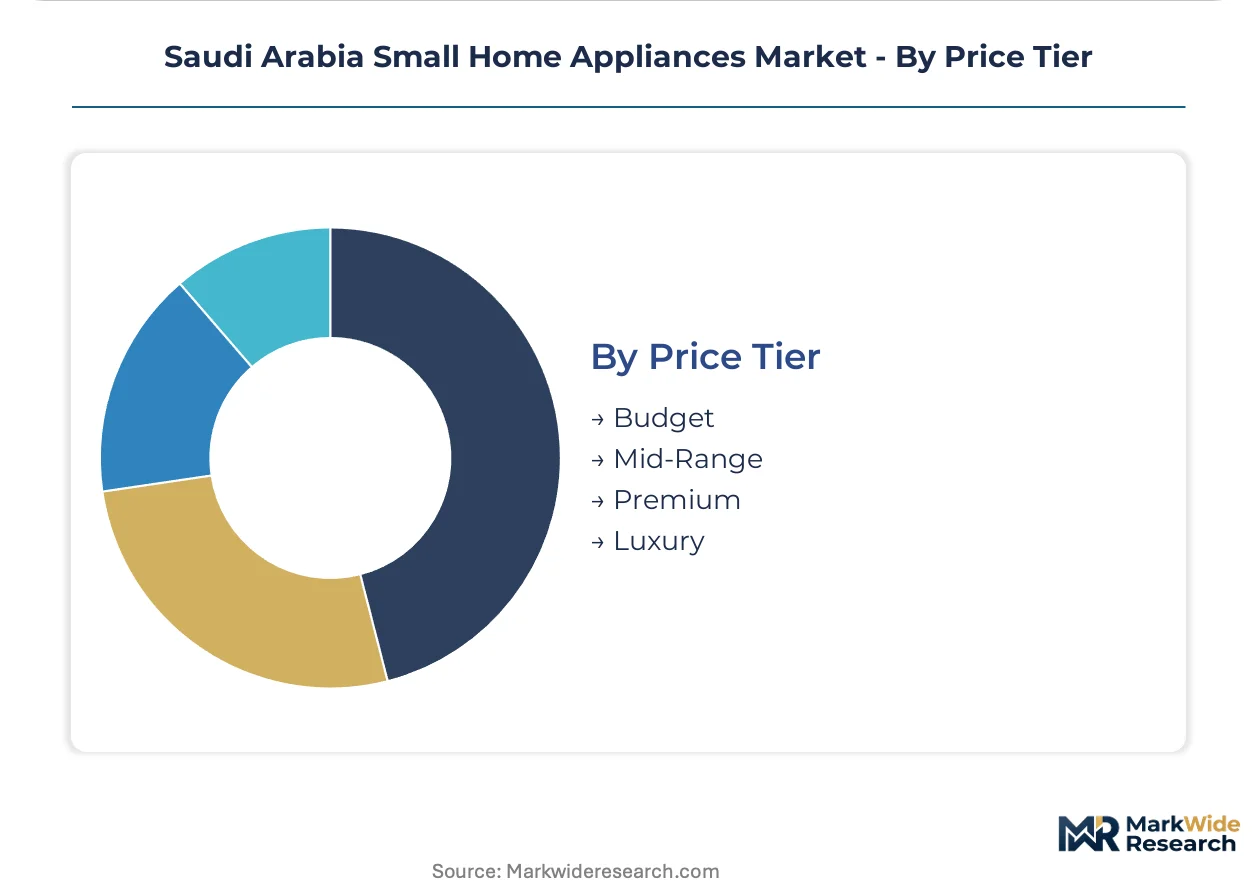
Price Tier:
Margin structures stratify across certification grades and feature bundles, with energy efficiency ratings becoming the primary differentiation mechanism under SASO mandates.
- Premium:Top-tier SASO energy ratings, embedded IoT connectivity, and extended warranty programs define this segment. These products command shelf space priority in supermarket channels and price premiums among Riyadh's affluent households.
- Mid-Range:Balanced feature sets with selective smart capabilities target value-conscious buyers upgrading from basic alternatives.
- Budget:Entry-tier products compete on upfront acquisition cost with minimal energy efficiency optimization and shorter design lifecycles.
- Luxury:Limited-edition finishes, concierge service programs, and bespoke configuration options serve ultra-high-net-worth households in exclusive Jeddah districts.
Premium tiers capture the majority of manufacturer profits. Mid-range products show the steepest volume expansion as SASO efficiency mandates compress entry-tier viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia outpaces Gulf neighbors in smart appliance penetration while the UAE accelerates hospitality-sector procurement. Both markets operate under distinct regulatory frameworks that shape supplier qualification requirements. Divergent urbanization patterns create asymmetric growth corridors across the Arabian Peninsula.
Riyadh
Young urban households anchor demand for compact, connected kitchen devices aligned with dual-income routines. SASO energy efficiency mandates compress product development cycles for manufacturers targeting Central Region distribution networks. Retail infrastructure concentration in Riyadh's commercial corridors enables rapid subscription service deployment for filter replacement programs.
Eastern Province
Dammam and Khobar exhibit retail infrastructure gaps relative to Riyadh and Jeddah, creating whitespace for distribution expansion. The region's industrial base generates demand for commercial-grade small appliances in workforce housing compounds. Grid stability challenges in coastal zones necessitate hardened power management circuits in product specifications.
Western Region
Jeddah's consumer expectations for immediate after-sales resolution drive channel experimentation with in-store service desks. Makkah and Medina hotels generate concentrated seasonal demand spikes for commercial-grade blenders and coffee systems. SFDA hygiene regulations for food-contact materials intensify compliance scrutiny for hospitality-sector suppliers.
NEOM Northwest
The giga-project's smart city infrastructure mandates IoT-native appliance specifications from inception. SASO expanding technical regulations on connected standards align with NEOM's interoperability requirements. Procurement frameworks prioritize vendors with established Saudi service networks over new market entrants.
Saudi Arabia Small Home Appliances Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational electronics conglomerates commanding premium tiers while regional assemblers serve price-sensitive channels. The vendor base concentrates around three strategic archetypes: full-stack appliance conglomerates with integrated software capabilities, regional specialists optimizing for Gulf climate conditions, and volume-oriented OEMs supplying private-label supermarket programs. Competitive dynamics center on M&A activity consolidating service network coverage and strategic partnerships embedding subscription revenue models into hardware sales.
Within the full-stack conglomerate tier, LG Electronics, Samsung Electronics, and Haier represent contrasting geographic origins and strategic postures. LG Electronics exemplifies the service-network-anchored archetype through its recurring revenue focus. Samsung Electronics occupies a position emphasizing software-defined feature extension. Haier sits within the localized-configuration specialist category, with its company name suggesting adaptation to regional operating conditions.
| Leading Market Players |
|---|
| LG Electronics |
| Whirlpool |
| Electrolux Arabia |
| Toshiba Lifestyle Products |
| Hisense |
| Haier |
| Samsung Electronics |
| Godrej Group |
| Panasonic |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap distributors controlling supermarket shelf access in Riyadh and Jeddah anchor both supply allocation decisions and pricing discipline across the Kingdom's dispersed population centers. Their financing structures favor inventory turns over margin capture, compressing price floors for entry-tier appliances while SASO certification costs sustain premiums at the top.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for plastic housings and motor assemblies, transmitting cost compression into budget-tier coffee makers and blenders. Three-tier pricing structure across premium, standard, and economy levels stratifies by SASO energy rating and IoT capability bundling. Pricing pressure stems from copper and semiconductor input volatility squeezing margins on heating elements and control boards. Budget-tier households in the Eastern Province exhibit highest price sensitivity, while NEOM procurement frameworks show least.
Supply Chain Analysis
Workforce availability constraints in Guangdong and Zhejiang provinces are nudging component sourcing toward automated facilities in Thailand and Malaysia. Supply concentrates in China for microprocessors and heating elements, South Korea for display modules, and Taiwan for semiconductor content. Raw material dependencies span copper for conductive elements, ABS plastic for housings, and rare earth magnets for high-torque motors. Single-source vulnerability runs through Red Sea shipping corridors. Distribution runs through Jeddah's port infrastructure for Western Region access and Dammam for Eastern Province penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia functions as a geographic-arbitrage play where SASO certification timelines and service network requirements erect higher barriers than UAE or Kuwait markets, rewarding early compliance investment with sustained pricing power.
For Market Incumbents: Deploy subscription-based filter replacement programs to anchor recurring revenue streams and extend customer lifetime value beyond hardware refresh cycles. LG Electronics and Samsung Electronics should harden power management circuits for Gulf grid conditions while consolidating Eastern Province service coverage before regional specialists establish footholds.
For New Entrants and Emerging Players: Capture whitespace in Dammam and Khobar retail infrastructure where supermarket chains lack dedicated small appliance sections and independent repair networks remain fragmented. Target hospitality procurement clusters in Makkah and Medina with commercial-grade durability ratings and rapid turnaround service commitments as the most penetrable segment.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional assemblers with established SASO pre-qualification and captive distribution into Saudi supermarket channels. Long-term viability across the analysis window hinges on software-defined feature roadmaps and IoT-native architectures aligning with NEOM interoperability mandates. Monitor SASO technical regulation expansion timelines as the signal for compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Filter Subscription Program Launch | LG Electronics anchors recurring revenue streams through automated replenishment tied to coffee maker and air purifier installed bases. |
| Eastern Province Distribution Expansion | Specialist retailers penetrate Dammam and Khobar whitespace before supermarket chains consolidate last-mile control. |
| SASO Pre-Qualification Investment | Manufacturers front-load compliance costs into factory selection decisions, locking out late entrants from supermarket shelf access. |
| Software-Defined Feature Roadmap | Samsung Electronics extends product lifecycles through firmware updates that add IoT capabilities without hardware replacement. |
| NEOM Service Network Partnership | Incumbents with established Saudi repair infrastructure secure preferred vendor status under giga-project procurement frameworks. |
Research Methodology
Coverage spans the Central Region, Western Region, and Eastern Province, with primary inputs from each. The research combines structured interviews with product managers at multinational electronics conglomerates, procurement leads at Saudi supermarket chains, regulatory affairs specialists navigating SASO certification protocols, and hospitality sector facilities managers in Makkah and Medina. Secondary validation draws from SASO technical regulation filings, SFDA food-contact material standards, customs import records for small appliance categories, and NEOM procurement framework disclosures. Bottom-up unit shipment estimates triangulate against top-down market value reconstructions.
Granularity-level modeling extends to product type, end user segment, distribution channel, and price tier dimensions across the projection horizon. The analytical framework derives CAGRs from segment-specific growth drivers including household formation rates in Riyadh, pilgrimage seasonality effects on hospitality demand, and SASO efficiency mandate compliance timelines. Industry-specific forecast inputs incorporate voltage stability requirements for Gulf region grid conditions and smart home interoperability technical regulations.
Underlying measurement precision varies by segment; coffee makers and online retail channels carry tighter precision than toasters and wholesale hospitality procurement. Forecasts reflect documented assumptions regarding SASO regulatory expansion pace and Red Sea shipping corridor stability. Practitioners should monitor SASO smart home technical regulation publication schedules and copper futures volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
India Small Home Appliances Market
Home Appliances
Switzerland Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Range Hood Market
Home Appliances
Undercounter Refrigerators Market
Home Appliances
Mexico Home Appliances Market
Home Appliances
Steam Clothing Care System Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market
Home Appliances
Qatar Home Appliances Market
Home Appliances
Home Appliances Glass Market
Home Appliances
Electrical Appliances Market
Home Appliances
North America Major Home Appliances Market