
 Qatar Home Appliances Market | 2026-2036
Qatar Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Qatar Home Appliances Market Analytics
Multi-source procurement among Qatari retailers is expanding as distributors reduce dependence on single-brand portfolios. Haier Smart Home Co. Ltd. leverages its integrated manufacturing base to offer competitive lead times on refrigeration and laundry systems. Samsung Electronics Co. Ltd. anchors the premium segment through connected appliance ecosystems that integrate with smart home platforms. LG Electronics Inc. differentiates via energy-efficient compressor technologies that align with local utility efficiency programs.
Home appliances encompass electrically powered machines designed for domestic tasks including food preservation, textile cleaning, thermal cooking, and climate control, typically operating on 220-240V at 50Hz with energy efficiency ratings from one to five stars. These products serve residential, commercial, and institutional end-users by automating labor-intensive household operations and maintaining controlled environments in extreme heat conditions. Refrigerators command the largest product type share due to food safety requirements in Qatar's climate, while air conditioners generate the fastest replacement cycles driven by near-continuous cooling demand. The hospitality customer type captures concentrated margin pools as hotel procurement contracts specify extended warranty terms and dedicated service networks.
KAHRAMAA efficiency standards and Qatar General Organization for Standardization (QS) technical regulations govern minimum energy performance and electrical safety compliance for imported appliances. The Ministry of Commerce and Industry enforces conformity assessment procedures that require third-party certification before customs clearance. BSI and SASO-aligned testing protocols further condition market access for brands seeking Gulf Cooperation Council-wide distribution rights. Stakeholders must monitor evolving efficiency tier thresholds and localization incentives that could reshape sourcing strategies and after-sales service obligations.
Market Dynamics
KAHRAMAA efficiency mandates are compressing replacement cycles for cooling and refrigeration equipment while simultaneously elevating minimum performance thresholds for all new installations across residential and commercial sectors.
Growth Catalysts
- Lusail Smart City infrastructure:Master-planned developments specify connected appliance ecosystems, creating embedded demand for IoT-enabled kitchen and climate systems.
- QS energy labeling expansion:Mandatory disclosure of five-star efficiency ratings on retail displays is steering consumer preference toward inverter compressor technologies.
- Hospitality pipeline acceleration:FIFA World Cup legacy hotel conversions and new luxury resort construction sustain commercial-grade procurement volumes for refrigeration and laundry equipment.
Market Restraints
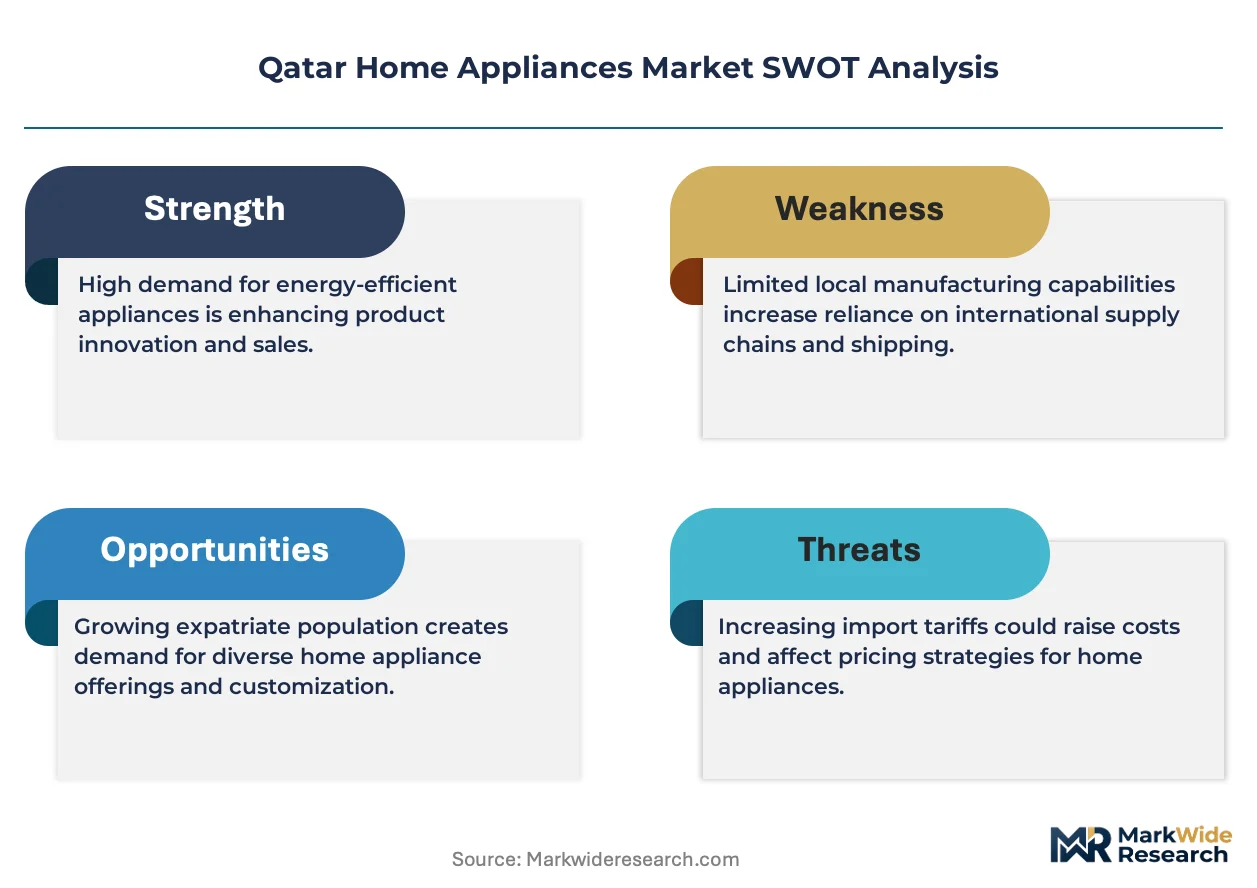
- Import dependency concentration:Over 90% of finished appliances enter through Jebel Ali transshipment, exposing distributors to Red Sea route disruptions and port congestion at Hamad Port.
- Copper and rare earth input volatility:Compressor manufacturing costs fluctuate with global copper futures and neodymium magnet supply constraints from concentrated upstream sources.
- Technical workforce scarcity:Domestic refrigeration technician certification programs produce insufficient graduates to match installation and service demand from villa construction booms.
Strategic Opportunities
- Al Wakrah and Al Khor satellite city penetration:Peripheral municipal zones outside Doha core exhibit lower appliance saturation and rising middle-income household formation.
- Solar-thermal hybrid cooling:Integration of photovoltaic arrays with absorption chillers aligns with KAHRAMAA distributed generation incentives for large villa compounds.
- Direct-to-developer channel expansion:Bypassing traditional retail through bulk supply contracts to master developers reduces margin erosion from distributor markups.
Industry Challenges
- QS conformity assessment bottlenecks:Third-party laboratory testing queues in Dubai and Doha extend pre-import clearance timelines by six to ten weeks.
- Legacy building electrical retrofit complexity:Pre-2010 villa stock requires panel upgrades to support smart appliance loads, slowing connected product penetration in established neighborhoods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Qatar Home Appliances Market |
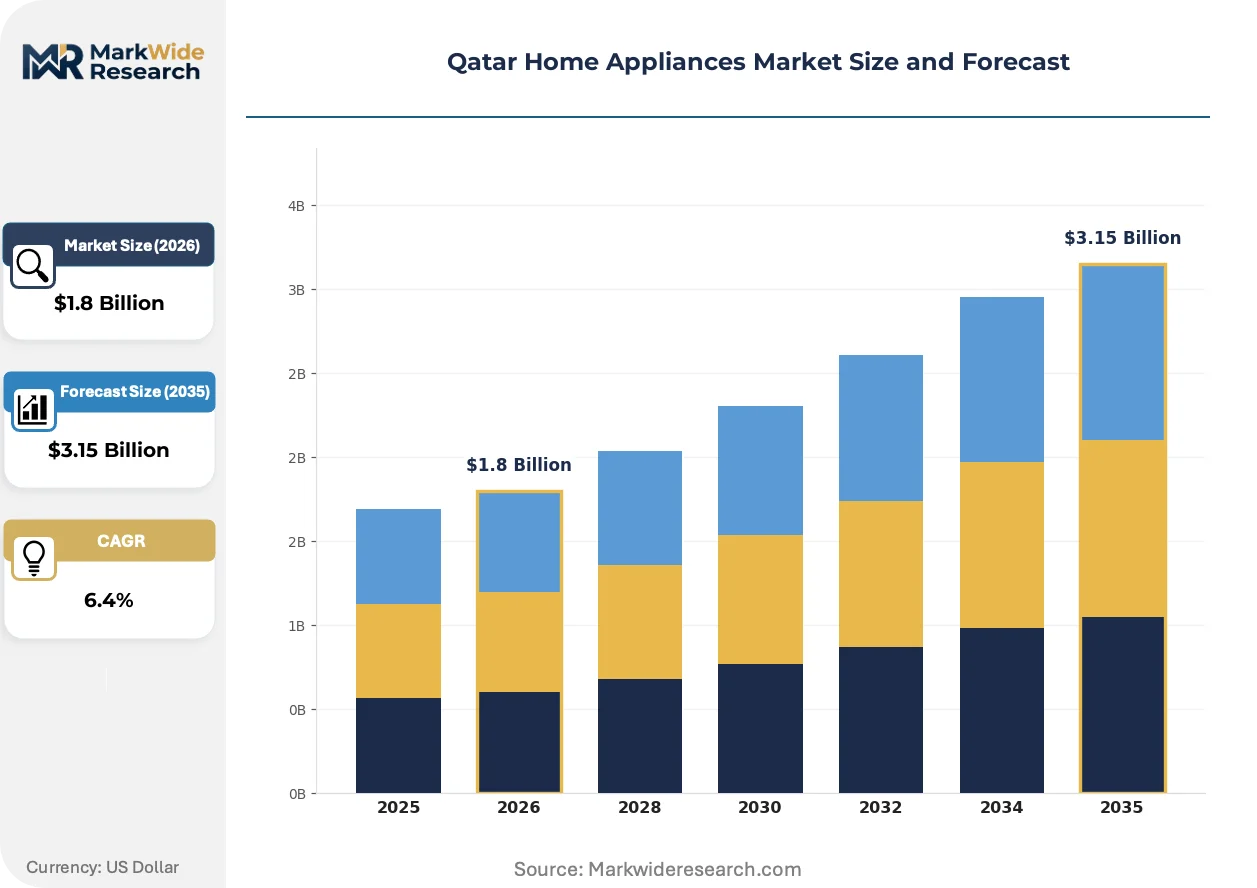
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
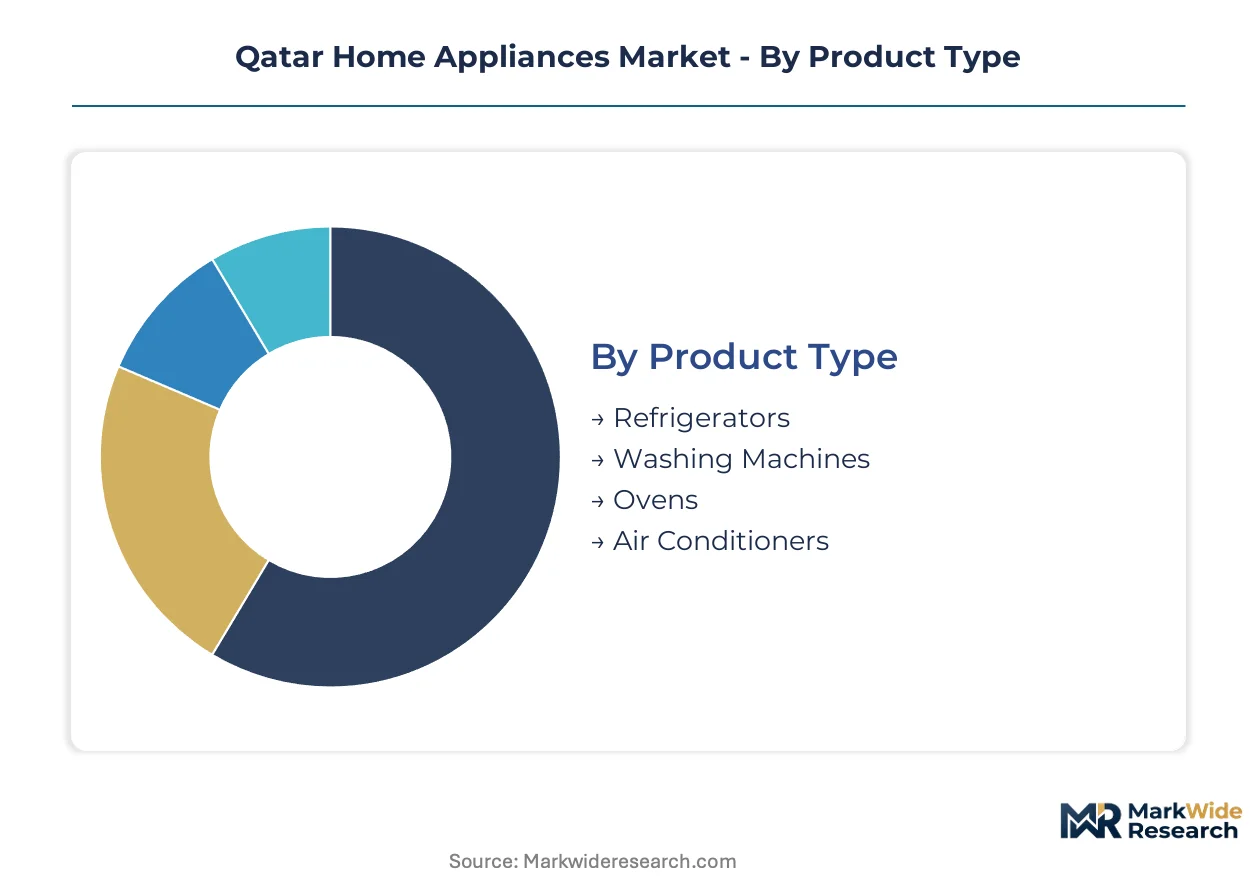
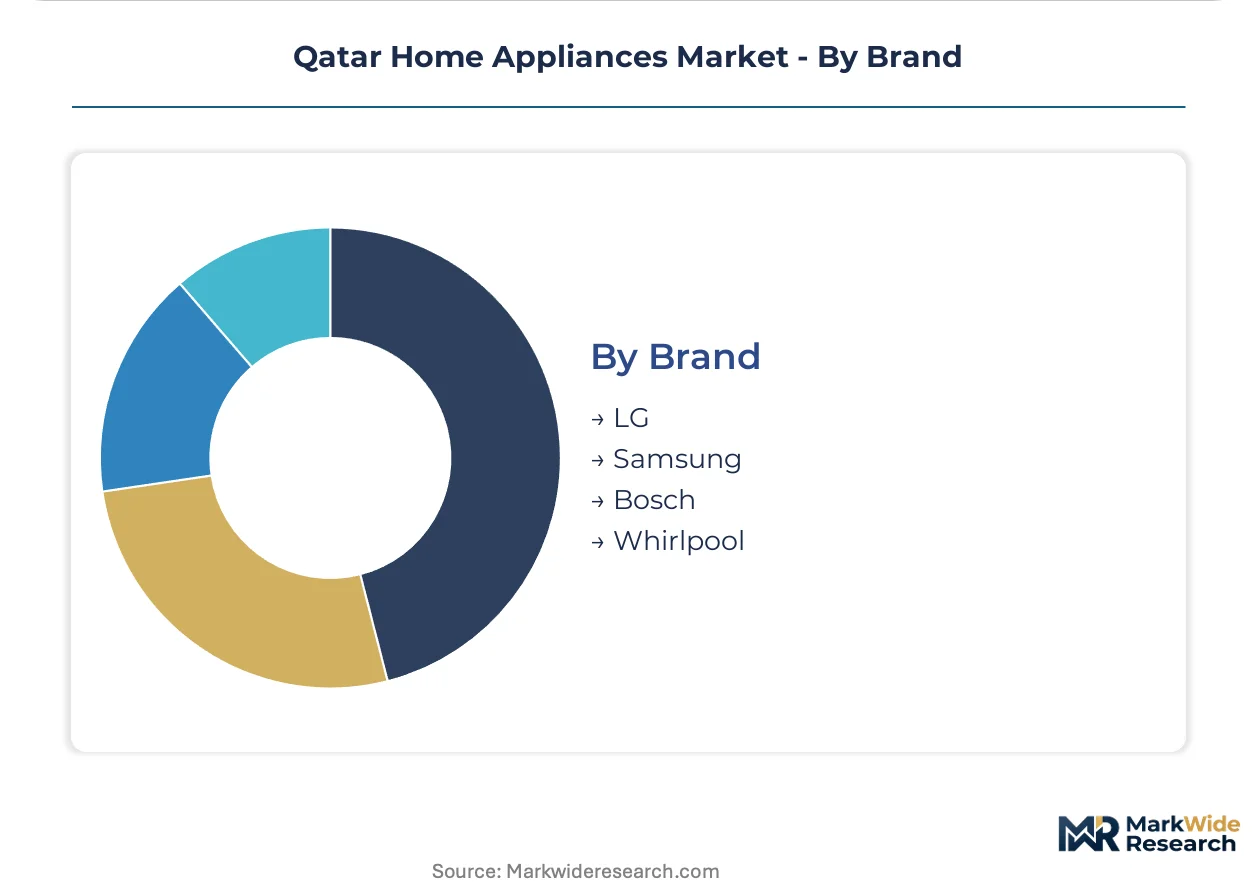
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Air Conditioners Customer Type: Residential, Commercial, Hospitality, Institutions Distribution Channel: Online, Offline, Wholesale, Direct Sales Brand: LG, Samsung, Bosch, Whirlpool |
| Companies Covered | BSH Home Appliances, Haier Smart Home Co. Ltd., Whirlpool Corporation, Kitchen Line, Gettco, LG Electronics Inc., Panasonic Corporation, Gorenje Group, Samsung Electronics Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Qatar Home Appliances Market Evolving Landscape
Digital control architectures and climate-adaptive engineering are redefining product specifications, with efficiency compliance and connected functionality becoming baseline requirements rather than premium differentiators.
Inverter-driven variable-speed compressors are overtaking fixed-speed reciprocating units in residential air conditioning. Five-star hotel engineering departments specify these systems for guest room retrofits to meet corporate sustainability mandates. The technology is overtaking conventional units by enabling partial-load operation during shoulder seasons when full cooling capacity remains unused.
KAHRAMAA Technical Specification No. 015 for air conditioner minimum energy performance is tightening allowable energy consumption ratios for imported cooling equipment. Manufacturers must redesign heat exchanger geometries and expander valve controls to maintain market access. The hospitality sector bears the highest compliance burden as property-wide cooling upgrades trigger full-system replacements rather than component swaps.
Developer-integrated procurement is consolidating appliance specification authority away from end consumers. Master developers for Lusail and Msheireb Downtown Doha now mandate built-in appliance packages as standard fit-outs, compressing retail channel relevance for premium residential segments. This pattern concentrates most intensely in waterfront apartment towers where uniform kitchen specifications preserve architectural coherence.
Qatar Home Appliances Market Segmentation
Qatar's home appliances market segments around regulatory compliance intensity, with KAHRAMAA efficiency mandates and QS certification requirements varying sharply across product categories and end-use applications. Understanding these segmentation boundaries enables stakeholders to align procurement strategies with the country's technical conformity framework.
Product Type:
KAHRAMAA Technical Specification No. 015 governs cooling equipment most stringently, while refrigeration falls under parallel food safety and energy performance standards that demand dual-track certification.
- Refrigerators:Compression-based cooling systems with inverter compressors now dominate specification sheets for five-star hotel kitchens and luxury villa developments. Lusail Smart City master plans embed these units as standard fit-outs, with developer-integrated procurement bypassing traditional retail channels for premium residential segments.
- Air Conditioners:Variable-speed inverter units are displacing fixed-speed reciprocating compressors across both residential retrofits and new commercial installations. Hospitality engineering departments specify these for guest room upgrades to meet corporate sustainability mandates, with near-continuous cooling demand in Qatar's climate driving the fastest replacement cycles of any product category.
- Washing Machines:Front-loading designs with heat pump drying functions align with villa compound utility specifications.
- Ovens:Built-in electric and gas variants integrate with developer-mandated kitchen suites in waterfront apartment towers.
Refrigerators sit at the top of the volume ranking, with air conditioners climbing the fastest.
Customer Type:
Margin concentration and service network requirements diverge sharply across customer types, with hospitality procurement commanding dedicated technical support clauses that residential channels rarely match.
- Hospitality:Five-star hotel chains specify commercial-grade refrigeration and laundry equipment at scale, with procurement contracts mandating extended warranty terms and 24-hour service response protocols. FIFA World Cup legacy conversions and new luxury resort construction sustain concentrated demand volumes for cooling and textile processing systems.
- Residential:Villa construction booms in Al Wakrah and Al Khor satellite cities drive appliance saturation in peripheral municipal zones outside Doha core. Pre-2010 villa stock requires electrical panel upgrades before smart appliance installation, slowing connected product penetration in established neighborhoods.
- Commercial:Retail and office installations prioritize energy efficiency ratings for operating cost control.
- Institutions:Government and healthcare facilities follow public procurement guidelines with standardized specification requirements.
Hospitality captures the steepest margin pools, with residential expanding most quickly in satellite city developments.
Distribution Channel:
Channel selection determines lead time exposure and margin retention, with Jebel Ali transshipment dependency creating vulnerability concentration for traditional wholesale routes.
- Direct Sales:Bulk supply contracts to master developers for Lusail and Msheireb Downtown Doha consolidate specification authority away from end consumers. This channel reduces distributor markup erosion while embedding appliance packages as architectural standard fit-outs.
- Offline:Multi-brand retailers in Doha and Al Rayyan reduce dependence on single-brand portfolios, with showroom energy rating displays steering consumer preference toward inverter technologies under QS labeling mandates.
- Online:E-commerce platforms accelerate specification research but face last-mile service limitations for installation and warranty claims.
- Wholesale:Distributor networks source through Hamad Port transshipment, exposing inventory to Red Sea route disruptions.
Direct sales commands the highest contract values, with offline retaining the broadest SKU coverage.
Brand:
Brand positioning aligns with compressor technology sourcing and connected platform integration, with integrated manufacturing bases offering lead time advantages in a market dependent on import flows.
- LG:Energy-efficient compressor technologies align with KAHRAMAA efficiency programs, with variable-speed systems penetrating both residential and hospitality cooling retrofits.
- Samsung:Connected appliance ecosystems integrate with smart home platforms, anchoring premium segment positioning in Lusail Smart City developments.
- Bosch:Built-in kitchen suites match European specification standards for luxury villa developments.
- Whirlpool:Commercial laundry systems serve hotel chain procurement contracts with extended service network coverage.
LG and Samsung together dominate specification authority in master-planned developments, with Bosch gaining share in premium residential fit-outs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lusail Smart City anchors appliance demand concentration in Qatar, with master-planned developments embedding connected kitchen and climate systems as standard architectural specifications across waterfront residential towers.
Doha Metropolitan Core
Luxury villa developments in West Bay and The Pearl-Qatar accelerate procurement of built-in kitchen suites and inverter-driven cooling systems. KAHRAMAA efficiency mandates compress replacement cycles for pre-2010 residential stock. Five-star hotel chains in the Diplomatic Area sustain commercial-grade refrigeration and laundry equipment contracts with 24-hour service clauses.
Lusail City
Smart city infrastructure specifications mandate IoT-enabled appliance ecosystems across residential, hospitality, and retail components. Developer-integrated procurement consolidates specification authority away from end consumers for waterfront apartment towers. Msheireb Properties and Lusail Real Estate Development Company embed uniform kitchen packages to preserve architectural coherence.
Al Wakrah Satellite Municipality
Rising middle-income household formation drives appliance saturation in peripheral zones outside Doha core. Lower existing penetration rates create first-time buyer concentration for standard-tier refrigeration and laundry equipment. Technical workforce scarcity slows installation capacity despite construction booms.
Al Khor Northern Development Corridor
Industrial zone expansion and worker accommodation construction generate institutional procurement volumes for standardized appliance packages. Public procurement guidelines from the Ministry of Commerce and Industry govern specification requirements for government and healthcare facilities. Port proximity to Ras Laffan reduces transshipment exposure for bulk imports.
Al Rayyan Inland Suburbs
Multi-brand retail showrooms cluster along Doha Expressway corridors, with QS energy labeling displays steering consumer preference toward inverter compressor technologies. Electrical retrofit complexity in established neighborhoods slows smart appliance penetration compared to greenfield developments. Wholesale distributor networks source through Hamad Port, exposing inventory to Red Sea route disruptions.
Qatar Home Appliances Market Competitive Landscape
Global majors compete with regional champions across specification authority in master-planned developments, with brand positioning stratifying around compressor technology sourcing and connected platform integration. Market structure tilts toward consolidated procurement decisions by master developers rather than fragmented retail competition. Three archetypes dominate: integrated manufacturing bases offering lead time advantages, premium ecosystem providers anchoring smart city specifications, and commercial-grade specialists serving hospitality service contracts. Dominant competitive moves include direct-to-developer channel expansion and backward integration into compressor manufacturing.
Within the integrated manufacturing tier, Haier Smart Home Co. Ltd. and Samsung Electronics Co. Ltd. occupy positions shaped by captive production capabilities and connected platform architecture. Haier represents the vertically integrated archetype with manufacturing base advantages in lead time compression. Samsung anchors the premium ecosystem vector through smart home platform integration specified in Lusail developments. LG Electronics Inc. sits within the efficiency-technology archetype, with variable-speed compressor systems penetrating both residential retrofits and hospitality cooling upgrades.
| Leading Market Players |
|---|
| BSH Home Appliances |
| Haier Smart Home Co. Ltd. |
| Whirlpool Corporation |
| Kitchen Line |
| Gettco |
| LG Electronics Inc. |
| Panasonic Corporation |
| Gorenje Group |
| Samsung Electronics Co. Ltd |
| Others |
Value Network & Pricing Analysis
Inverter compressor adoption across Qatar's cooling and refrigeration segments is simultaneously compressing manufacturing cost curves and concentrating procurement leverage among integrated producers with captive component supply. This technology transition rewards manufacturers with backward integration into compressor production while elevating energy efficiency ratings as the primary price segmentation axis.
Pricing Analysis
Copper futures volatility and rare earth magnet supply constraints pass through directly into compressor manufacturing costs, with pricing stratifying across premium, standard, and economy tiers based on energy efficiency certification and after-sales service bundling. KAHRAMAA Technical Specification No. 015 compliance costs are elevating minimum viable price floors for imported cooling equipment. Hospitality procurement contracts show lowest price sensitivity due to mandated 24-hour service response clauses, while residential satellite city buyers in Al Wakrah exhibit highest sensitivity to upfront acquisition costs.
Supply Chain Analysis
Reverse-logistics flows for compressor refurbishment and core returns remain underdeveloped in Qatar, with most end-of-life units diverted to landfill rather than remanufacturing channels. Finished appliance supply concentrates in China, South Korea, and Thailand, with over 90% of units transshipping through Jebel Ali before Hamad Port clearance. Copper coil and neodymium magnet dependencies create single-source vulnerability exposure. Distribution runs through master-developer direct contracts for premium residential segments and multi-brand retail showrooms for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qatar's home appliances market functions as a stable compounder anchored by KAHRAMAA efficiency mandates that perpetually refresh replacement demand across the installed base.
For Market Incumbents: To counter developer-integrated procurement consolidation, secure exclusive supply agreements with Lusail Real Estate Development Company and Msheireb Properties for smart city fit-outs. Deepen backward integration into variable-speed compressor manufacturing to compress lead times against Haier's integrated base. Invest in Doha-based technical certification programs to alleviate workforce scarcity bottlenecks. For New Entrants and Emerging Players: E-commerce platforms with installation partnership networks offer the most penetrable route into price-sensitive residential segments in Al Wakrah and Al Khor satellite municipalities. Target first-time buyer households in peripheral zones with standard-tier refrigeration and laundry bundles. Pursue bulk supply contracts with industrial zone developers in Al Khor for worker accommodation specifications. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with established KAHRAMAA conformity assessment relationships and Hamad Port clearance capabilities. Long-term viability rests on exposure to hospitality procurement cycles and developer-direct channel penetration. Monitor QS energy labeling expansion announcements and Lusail construction permit volumes as inflection indicators for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Developer Channel Expansion | Bypasses distributor markups while embedding appliances as standard Lusail fit-outs. |
| Inverter Compressor Manufacturing Investment | Captures lead time advantages against import-dependent competitors serving KAHRAMAA mandates. |
| Technical Workforce Certification Programs | Alleviates installation capacity constraints from villa construction booms in satellite cities. |
| Solar-Thermal Hybrid Cooling Integration | Aligns with KAHRAMAA distributed generation incentives for large villa compounds. |
| Extended Service Network Coverage | Meets hospitality procurement contract requirements for 24-hour response protocols. |
Research Methodology
Direct dialogue with appliance distributor procurement heads, KAHRAMAA compliance officers, hospitality engineering directors, and master developer specification teams grounded the qualitative foundation. Secondary validation drew from QS technical regulations, KAHRAMAA efficiency standard filings, customs import records through Hamad Port, and hospitality procurement database tracking. Bottom-up demand modeling across product categories triangulated against top-down market sizing from construction permit flows and replacement cycle assumptions.
Bottom-up volume estimates by product type, customer segment, and distribution channel fed into value projections across the analysis window. Segmentation dimensions included cooling equipment efficiency tier, refrigeration capacity class, hospitality versus residential end-use, and direct versus retail channel penetration. CAGRs derived from installed base growth, replacement frequency assumptions, and efficiency mandate-driven upgrade cycles. Forecast inputs incorporated Lusail Smart City build-out schedules and FIFA World Cup legacy hotel conversion pipelines.
The model assumes a particular technology adoption path; alternative pathways for absorption chiller and solar-thermal hybrid cooling would alter the outlook if KAHRAMAA incentive structures shift. Forecasts reflect documented assumptions about satellite city household formation rates and hospitality construction timelines. Practitioners should monitor Red Sea shipping route stability and copper futures volatility for early signals of supply disruption or cost pass-through acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Built-In Hobs Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
India Refrigerator Market
Home Appliances
Australia Washing Machine Market
Home Appliances
UK Household Appliances Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Refrigerator Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Latin America Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
United States Major Home Appliances Market
Home Appliances
Europe Home Appliances Market