
 Desktop Air Purifier Market | 2026-2036
Desktop Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Desktop Air Purifier Market Insights
The split between premium and commodity tiers is realigning around filtration performance claims and connected feature sets rather than price alone. Philips leverages its healthcare heritage to anchor credibility in clinical-grade home units. Coway Co. Ltd. dominates the Asian premium channel through design-forward positioning and subscription filter services. Dyson Ltd. differentiates via integrated sensor ecosystems that extend beyond purification into environmental monitoring.
A desktop air purifier is a compact, electrically powered air treatment device designed for localized deployment on work surfaces, typically employing HEPA media rated at 99.97% efficiency at 0.3 microns, activated carbon layers, or electrostatic precipitation to remove particulates, volatile organic compounds, and biological contaminants from enclosed spaces of 100–400 square feet. Its primary commercial purpose is to deliver point-source air quality improvement in settings where centralized HVAC filtration proves inadequate or unavailable. HEPA-based units continue to command the largest installed base, though smart-enabled systems integrating particulate sensors and app-based control represent the fastest-expanding margin pool. The office end-user segment shows structural resilience as employers retrofit hybrid workspaces, while filterless technologies remain niche due to ozone emission concerns that constrain healthcare adoption.
The EPA establishes indoor air quality benchmarks that shape product certification requirements and consumer trust mechanisms in the United States, while the EU Green Deal and REACH frameworks constrain material choices and energy efficiency thresholds across European markets. Japan's METI enforces stringent electrical appliance standards that filter market access for imported units. Stakeholders must weigh certification investment against the fragmentation of national standards as they allocate manufacturing capacity across regional production footprints.
Market Dynamics
HEPA-to-smart filtration migration is compressing replacement part margins while subscription filter services lock in recurring revenue streams. Manufacturers now compete on sensor integration depth rather than clean air delivery rate alone.
Growth Catalysts
- EPA Indoor Air Quality Benchmarks:Certification requirements under EPA frameworks drive consumer trust mechanisms and retail placement priority for compliant units in the United States.
- Home Office Deployment:Remote workers across Germany and Japan invest in point-source purification where centralized HVAC systems prove inadequate for individual workspaces.
- Activated Carbon Layer Innovation:Enhanced VOC capture capabilities expand addressable use cases beyond particulate removal into chemical contaminant mitigation.
Market Restraints
- Filter Replacement Cost Structure:Proprietary cartridge designs from dominant suppliers create lifetime ownership cost barriers that suppress price-sensitive segment penetration.
- Filterless Technology Limitations:Electrostatic precipitation and ionization methods face ozone emission constraints that block healthcare and childcare facility adoption.
- REACH Material Compliance:EU chemical substance restrictions increase R&D cycle duration and disqualify lower-cost plastic formulations from European market access.
Strategic Opportunities
- Underpenetrated Indian Urban Markets:Metro pollution awareness in Delhi and Mumbai outpaces product availability, creating first-mover advantage for certified entrants.
- EU Green Deal Energy Efficiency Mandates:Stricter standby power thresholds favor brushless motor designs and sensor-driven auto-shutoff capabilities.
- App-Enabled Filter Subscription Channels:Direct-to-consumer replenishment models bypass retail margin capture and generate predictable revenue streams.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Separate METI electrical safety, EPA energy star, and CE marking processes extend product launch windows by 8-14 months.
- Sensor Calibration Skill Gaps:Particulate detection accuracy requires specialized firmware engineering talent concentrated in Japanese and German component suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desktop Air Purifier Market |
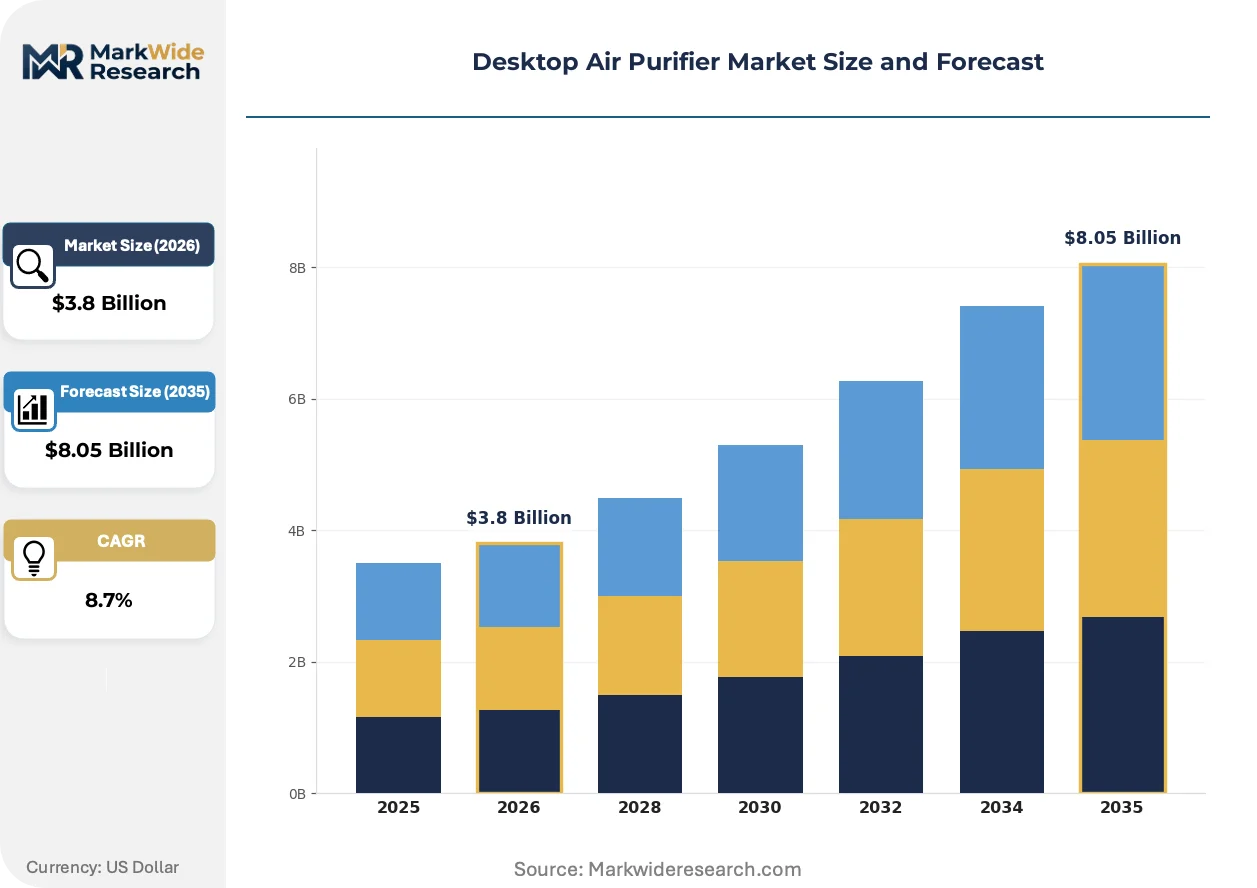
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Ionizer, UV-C Technology: Portable, Smart, Filterless, Hybrid End User: Home, Office, Educational, Healthcare Feature: Noise Reduction, Air Quality Indicator, Remote Control, Energy Efficiency |
| Companies Covered | Honeywell International Inc., Philips, Dyson Ltd., Blueair AB, Sharp Corporation, Coway Co. Ltd., LG Electronics Inc., IQAir AG, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desktop Air Purifier Market Trends and Innovations
Filtration hardware is converging with environmental monitoring platforms, transforming standalone appliances into data-collection nodes. This integration is reshaping competitive differentiation and opening adjacent service revenue streams.
Photocatalytic oxidation technology is absorbing volatile organic compound remediation tasks previously requiring activated carbon saturation. Commercial building operators in Japan are piloting these systems for formaldehyde removal in renovated structures. The shift is compressing filter replacement frequency expectations and forcing carbon-dependent suppliers toward hybrid media development.
REACH framework amendments are constraining halogenated flame retardant usage in plastic housings, compelling redesign cycles for European-bound products. Manufacturers must validate alternative chemistries without sacrificing UL 94 V-0 safety ratings. German testing laboratories report 40% capacity expansion to accommodate verification backlogs from Asian contract manufacturers.
Employer-funded wellness stipends are redirecting procurement authority from facilities management to individual employees in hybrid office arrangements. United States technology firms now subsidize personal air quality devices as taxable benefits rather than capital equipment. This fragmentation is compressing average order values while expanding unit volumes through direct fulfillment channels.
Desktop Air Purifier Market Segmentation
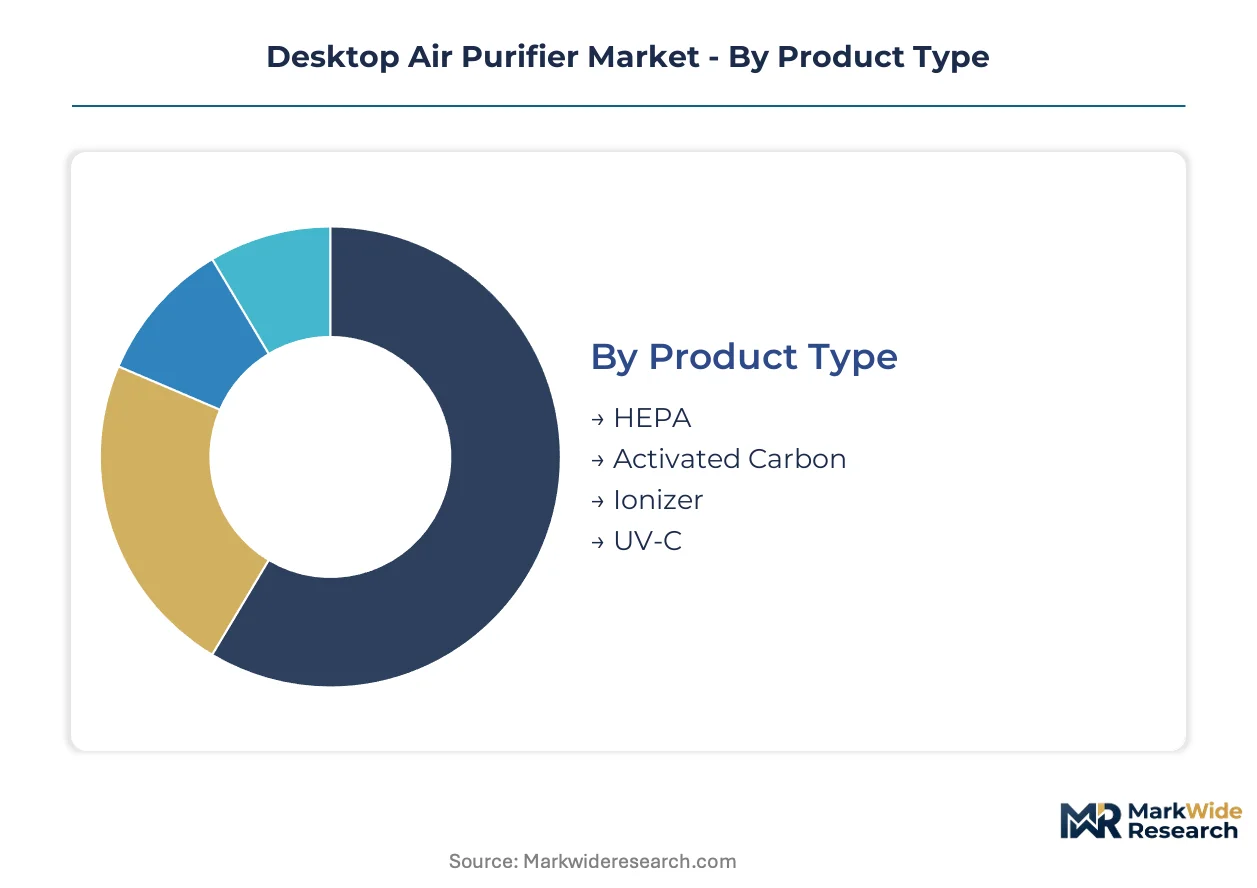
Desktop air purifier segmentation reveals how capital allocation, technical complexity, and regulatory compliance requirements diverge across product architectures. Manufacturers prioritize segments where sensor integration and filtration media investments yield defendable margin positions against commodity competition.
Product Type:
Capital intensity varies sharply across filtration architectures, with multi-stage HEPA systems demanding the highest upfront tooling and certification investment while single-technology units require minimal specialized assembly infrastructure.
- HEPA:Multi-layer mechanical filtration rated at 99.97% efficiency at 0.3 microns dominates installed base in United States home office deployments where EPA certification frameworks anchor consumer trust. Premium units integrate pre-filters and activated carbon stages, extending bill-of-materials complexity and factory calibration requirements.
- Activated Carbon:Porous carbon media optimized for VOC and odor absorption commands specialized sourcing relationships with coconut shell suppliers in Southeast Asia. Demand concentrates in renovated Japanese commercial buildings where formaldehyde remediation drives specification requirements under METI indoor air quality guidelines.
- Ionizer:Electrostatic precipitation generates charged particles without replaceable media, reducing lifetime ownership costs but triggering ozone emission scrutiny that blocks healthcare facility adoption in Germany.
- UV-C:Germicidal ultraviolet irradiation targets biological contaminants through photochemical disruption of pathogen DNA, requiring quartz glass sleeve engineering and safety interlock mechanisms that elevate unit manufacturing costs.
HEPA absorbs the bulk of installed capacity; UV-C is expanding most quickly as healthcare specifications tighten.
Technology:
Supply chain configuration separates app-enabled architectures from basic electromechanical units, with firmware development talent concentrated in Japanese and German component ecosystems creating entry barriers for new entrants.
- Portable:Cordless battery-operated designs prioritize compact form factors and low power draw for travel and temporary deployment scenarios, demanding lithium-ion cell integration and thermal management engineering.
- Smart:Wi-Fi and Bluetooth connectivity enable particulate sensor data streaming, filter life monitoring, and automated speed adjustment based on real-time air quality readings. United States technology sector wellness stipends are redirecting procurement toward these units as taxable employee benefits rather than capital equipment.
- Filterless:Electrostatic precipitation and photocatalytic oxidation eliminate consumable replacement but face ozone emission constraints under EPA and REACH frameworks that suppress healthcare and childcare facility penetration.
- Hybrid:Multi-technology architectures combining HEPA mechanical filtration with UV-C or activated carbon stages command the highest bill-of-materials complexity and firmware integration requirements, justifying premium positioning in German and Japanese markets.
Portable units retain the largest shipment volumes; hybrid systems are climbing the fastest as performance specifications harden.
End User:
Procurement authority fragmentation distinguishes institutional buyers from individual consumers, with employer-funded wellness programs in United States hybrid offices creating direct-to-employee fulfillment channels that bypass traditional facilities management.
- Home:Individual consumers prioritize noise reduction and aesthetic integration with residential interiors, driving demand for brushless motor designs and compact form factors in North American and Western European markets.
- Office:Employer-funded deployment in hybrid workspaces requires enterprise-grade fleet management capabilities and centralized filter subscription logistics, with United States technology firms leading adoption of personal air quality devices as taxable benefits.
- Educational:School district procurement in Japan emphasizes METI electrical safety certification and formaldehyde remediation specifications for renovated structures, creating specialized demand for photocatalytic oxidation hybrids.
- Healthcare:Clinical-grade requirements demand HEPA H13 or higher filtration efficiency with documented particle retention testing, restricting market access to suppliers with healthcare heritage and regulatory dossier capabilities.
Home applications anchor volume; healthcare specifications are gaining share fastest as clinical-grade claims extend into premium residential positioning.
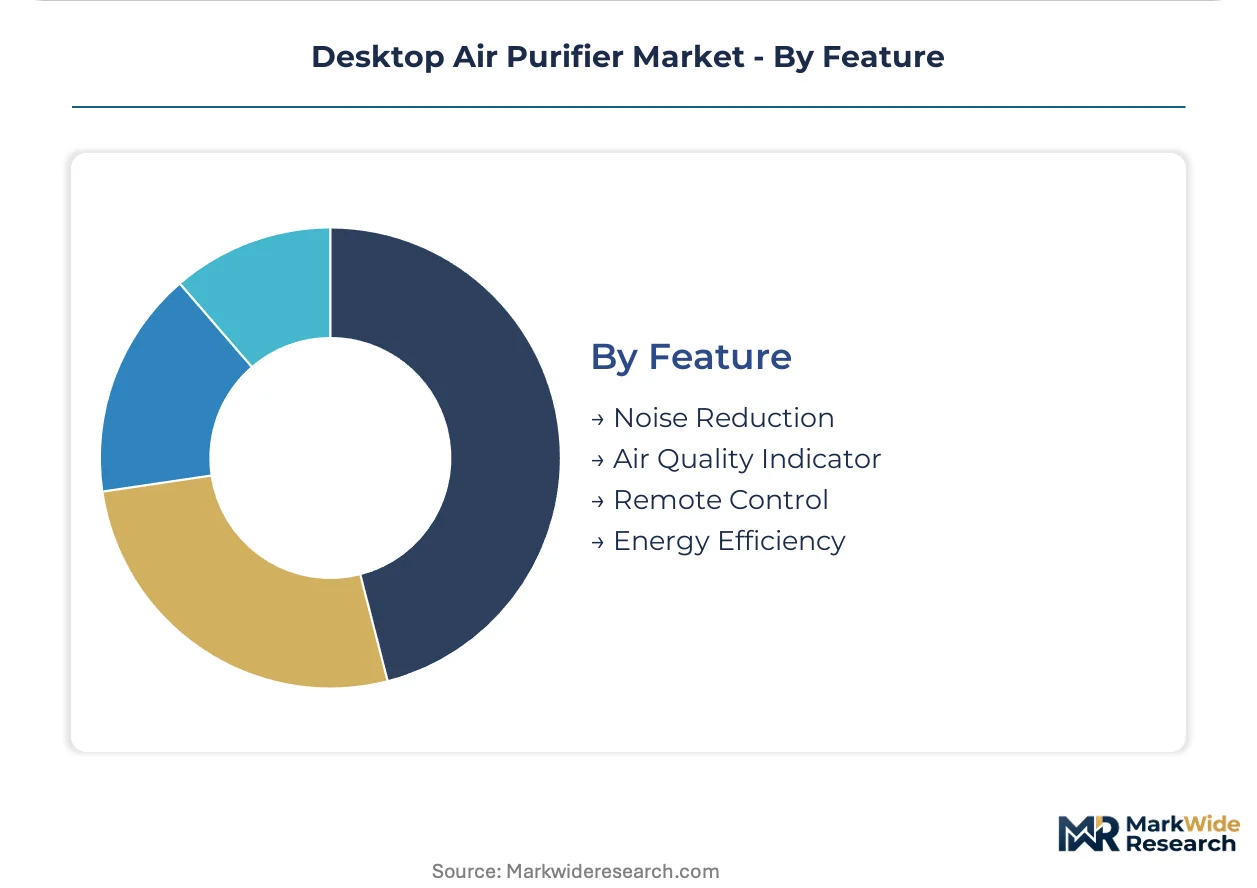
Feature:
Component sourcing depth differentiates feature-rich architectures from basic units, with particulate sensor calibration requiring specialized firmware engineering talent that concentrates among Japanese and German suppliers.
- Noise Reduction:Brushless DC motor designs and aerodynamic fan blade engineering achieve sub-30 decibel operation at sleep speeds, demanding acoustic testing infrastructure and vibration isolation R&D investment.
- Air Quality Indicator:Laser-based particulate sensors measuring PM2.5 and PM10 concentrations in real time transform standalone appliances into environmental data collection nodes, enabling subscription service revenue streams through air quality reporting platforms.
- Remote Control:Smartphone application integration and voice assistant compatibility require ongoing cloud infrastructure investment and cybersecurity compliance that favors established connected home ecosystems.
- Energy Efficiency:Standby power minimization and auto-shutoff capabilities align with EU Green Deal mandates and EPA Energy Star thresholds, driving motor driver IC selection and power management firmware optimization.
Noise reduction dominates specification sheets; air quality indicators are expanding most quickly as environmental monitoring platforms reshape competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors the highest concentration of desktop air purifier deployment density, with metropolitan office workers and residential consumers driving premium-tier adoption amid persistent urban particulate concerns.
United States
Home office adoption among remote workers in Austin and Seattle sustains demand for point-source purification units. EPA Indoor Air Quality Benchmarks and Energy Star certification requirements shape retail placement and consumer trust mechanisms. California's South Coast Air Quality Management District enforces supplementary indoor pollutant guidelines that filter non-compliant imports from Los Angeles and San Francisco distribution channels.
Germany
Employer-funded wellness stipends in Berlin and Munich hybrid offices redirect procurement toward individual employee channels. REACH material compliance and EU Green Deal energy efficiency mandates constrain halogenated flame retardant usage and standby power thresholds. Bavarian testing laboratories report expanded capacity to verify alternative chemistries for European-bound products.
Japan
Renovated commercial structures in Osaka and Nagoya drive specification requirements for formaldehyde remediation capabilities. METI electrical appliance standards and indoor air quality guidelines enforce stringent safety and performance thresholds. Kanto region manufacturers concentrate sensor calibration engineering talent for particulate detection firmware development.
India
Metro pollution awareness in Delhi and Mumbai outpaces certified product availability, creating first-mover positioning for compliant entrants. Central Pollution Control Board ambient air quality notifications heighten consumer consciousness without matching enforcement infrastructure. Maharashtra and Karnataka industrial corridors attract contract manufacturing investment for regional assembly operations.
South Korea
Seoul Capital Area consumers prioritize design-forward units with connected feature sets for residential deployment. MFDS and Korean Agency for Technology and Standards administer electrical safety and electromagnetic compatibility certification processes. Busan-Ulsan manufacturing clusters supply brushless motor components to regional original equipment manufacturers.
Desktop Air Purifier Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated healthcare heritage anchors premium credibility against commodity assemblers. The vendor base stratifies into three archetypes: clinical-grade specialists leveraging regulatory dossiers, design-forward lifestyle brands capturing subscription filter economics, and scale-driven electronics conglomerates optimizing manufacturing throughput. Consolidation pressure concentrates among mid-tier players lacking sensor firmware capabilities or carbon media sourcing relationships. Dominant competitive moves include geographic certification expansion and direct-to-consumer replenishment channel development.
Within the healthcare heritage tier, Philips and IQAir AG exemplify positioning anchored in clinical credibility and documented particle retention testing. Coway Co. Ltd. occupies a distinct archetype through design-forward consumer positioning and recurring revenue infrastructure. Dyson Ltd. represents the integrated sensor ecosystem vector, extending environmental monitoring capabilities beyond core purification functions. Sharp Corporation and Panasonic Corporation sit within diversified electronics conglomerate structures where air treatment serves as a portfolio component rather than sole strategic focus.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Philips |
| Dyson Ltd. |
| Blueair AB |
| Sharp Corporation |
| Coway Co. Ltd. |
| LG Electronics Inc. |
| IQAir AG |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal energy efficiency mandates gate qualified supply for European-bound units while anchoring premium-tier pricing access for compliant manufacturers. REACH material restrictions and standby power thresholds disqualify lower-cost plastic formulations and conventional motor designs, compressing margin pools for non-compliant assemblers and concentrating pricing power among certified incumbents.
Pricing Analysis
Clean air delivery rate anchors value-based pricing tiers across the desktop air purifier market. Three-tier pricing structure across premium, standard, and economy levels separates HEPA H13-certified clinical-grade units from basic mechanical filtration and unbranded commodity alternatives. Price differentiation rests on sensor integration depth and filter subscription bundling rather than hardware alone. Cost compression in the economy tier is intensifying because proprietary cartridge designs from dominant suppliers create lifetime ownership barriers that suppress penetration. Enterprise buyers in United States technology firms show lowest price sensitivity due to wellness stipend structures, while individual consumers in emerging markets remain most constrained by upfront hardware costs.
Supply Chain Analysis
India's phased manufacturing program and domestic content requirements for government procurement are reshaping sourcing footprints for regional assembly operations. Component concentration centers on China for HEPA media and activated carbon, Japan for particulate sensors and brushless motors, and South Korea for lithium-ion cells and power management ICs. Raw material dependencies include coconut shell carbon from Southeast Asia, polypropylene melt-blown fabric for filtration media, and rare-earth magnets for motor assemblies. Single-source vulnerability in laser-based particulate sensor calibration engineering concentrates among Kanto region suppliers. Distribution runs through direct-to-consumer channels for subscription filter services and electronics retail chains for hardware-only transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The desktop air purifier market is becoming a vertical-integration race. Players are pursuing upstream control over sensor firmware capabilities and carbon media sourcing relationships to defend margin positions.
For Market Incumbents: To counter filterless technology erosion in the healthcare segment, lock in proprietary cartridge economics through subscription replenishment platforms and deepen backward integration into activated carbon sourcing from Southeast Asian suppliers. Secure METI electrical safety and EPA Energy Star certifications ahead of multi-jurisdiction launch windows to preempt mid-tier competition. For New Entrants and Emerging Players: Launch via direct-to-consumer app-enabled channels to bypass retail margin capture in underpenetrated Indian metro markets where pollution awareness outpaces certified product availability. Target employer-funded wellness stipend programs in United States hybrid offices as the most penetrable procurement channel, positioning hybrid filtration units with real-time air quality reporting as taxable employee benefits rather than capital equipment. For Investors and Strategic Acquirers: First-mover certification completion in Delhi and Mumbai distribution channels is the leading indicator that regional assembly scale economics are achievable. Long-term viability across the analysis window favors vertically integrated specialists with captive carbon media relationships and firmware engineering talent concentrated in Japanese component ecosystems. Watch for consolidation signals among mid-tier players lacking sensor calibration capabilities or REACH-compliant housing chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Filter Subscription Platform Launch | Direct-to-consumer replenishment bypasses retail margin capture and locks in recurring revenue streams. |
| Photocatalytic Oxidation Integration | Hybrid architectures addressing formaldehyde remediation in Japanese renovated commercial structures expand addressable use cases. |
| METI/EPA/CE Certification Expansion | Multi-jurisdiction compliance reduces launch windows and filters non-compliant competitors from premium channels. |
| Activated Carbon Sourcing Integration | Upstream control over coconut shell supply relationships from Southeast Asia secures VOC capture performance claims. |
| Sensor Firmware Talent Acquisition | Calibration engineering capabilities concentrated in Kanto region suppliers anchor smart-enabled product differentiation. |
Research Methodology
SEC 10-K filings, EPA certification databases, and METI electrical appliance standards formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with product managers at filtration equipment manufacturers, procurement leads at United States technology firms administering wellness stipends, and regulatory affairs specialists navigating REACH amendments were combined with secondary validation. Conversations with carbon media sourcing directors and sensor firmware engineering heads in Japanese component ecosystems informed supply chain concentration analysis. Bottom-up shipment data triangulated against top-down spending patterns from employer-funded benefit programs.
Bottom-up modeling of unit shipments across product type, technology architecture, end-user segment, and feature configuration were reconciled with top-down expenditure flows from hybrid office wellness budgets. Segmentation dimensions included filtration technology, connectivity tier, procurement channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of home office adoption curves and certification requirement phase-ins. Industry-specific forecast inputs incorporated EPA Indoor Air Quality Benchmark enforcement timelines and EU Green Deal standby power threshold implementations across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic oxidation or filterless electrostatic precipitation would alter the outlook if ozone emission constraints ease or healthcare facility specifications shift. Forecasts reflect assumptions regarding certification timeline durations, carbon media supply continuity, and employer wellness stipend persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Window Rain Guards Market
Household Items
Insulated Water Bottles Market
Household Items
Nebulizing Diffuser Market
Household Items
Silicone Soap Mold Market
Household Items
Toilet Hygiene Products Market
Household Items
Titanium Thermos Cup Market
Household Items
Garbage Disposals Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Wax Removal Aids Market
Household Items
Smart Fork Market
Household Items
Brush Cover Market
Household Items
Global Ceramic Tableware Market
Household Items
Flushable Wipes Market
Household Items
Folded Tissues Market
Household Items
Facial Tissue Market
Household Items
Air Freshener Market