
 Global Residential Microwave Oven Market | 2026-2036
Global Residential Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Global Residential Microwave Oven Market Outlook
Buyer fragmentation across rental housing and student accommodations is realigning distribution priorities for appliance manufacturers. Samsung Electronics leverages its semiconductor supply chain to control inverter magnetron costs. Midea Group anchors volume production through captive manufacturing in Guangdong province. Whirlpool Corporation competes on brand equity in North American big-box retail channels.
A residential microwave oven is a countertop or installed electric appliance utilizing magnetron-generated microwave radiation at 2.45 GHz to heat polar molecules in food, with primary commercial purpose of reducing meal preparation time in domestic kitchens. Countertop units dominate unit shipments globally due to zero installation requirements and portability between rental properties. Convection technology commands premium positioning as consumers seek dual-function baking capability without dedicated oven investment. Solo microwaves retain economy-tier dominance in emerging markets where price sensitivity constrains feature adoption.
FCC electromagnetic emission standards in the United States and EU CE marking under the Low Voltage Directive govern product safety and market access for microwave oven manufacturers. China's GB standards and NMPA-equivalent quality certifications create additional compliance layers for brands sourcing from domestic OEMs. India's BIS mandatory certification for electronic appliances adds testing burden but filters substandard imports. Stakeholders must monitor evolving magnetron efficiency thresholds and right-to-repair regulatory momentum that could reshape component sourcing and service network economics.
Market Dynamics
Magnetron supply concentration in East Asian manufacturing clusters is forcing appliance brands to renegotiate component procurement terms and accelerate inverter technology substitution timelines.
Growth Catalysts
- EU Ecodesign regulations:Energy efficiency mandates under the EU framework are accelerating inverter magnetron adoption across European product lines, compressing payback periods for premium-tier upgrades.
- Urban China apartment construction:Space-constrained housing in Shanghai, Shenzhen, and Beijing is concentrating demand for compact countertop units with zero installation footprint.
- Inverter magnetron technology:Variable power control enables precise temperature modulation, expanding use cases from reheating to defrosting and light cooking without dedicated range investment.
Market Restraints
- Neodymium magnet supply volatility:Rare earth price swings from Chinese export quotas directly impact magnetron manufacturing costs and margin stability.
- FCC electromagnetic emission testing:Certification timelines for modified inverter designs extend product launch windows by 8-14 weeks in the United States.
- Air fryer substitution:Countertop convection alternatives are capturing meal-preparation occasions previously served by mid-tier microwave ovens.
Strategic Opportunities
- Metropolitan India:Mumbai, Bangalore, and Delhi NCR present underpenetrated demand for convection-microwave hybrids as first-time appliance buyers seek dual-function value.
- Right-to-repair regulatory momentum:Proposed EU legislation mandating component availability and repair documentation would reshape service network economics for independent technicians.
- Smart home integration:Voice control and app connectivity are converging with microwave functionality, opening premium positioning through ecosystem lock-in with Alexa and Google Home platforms.
Industry Challenges
- Magnetron engineering talent scarcity:Specialized vacuum tube design expertise is concentrating at legacy Japanese and Chinese suppliers, constraining in-house R&D expansion.
- Multi-jurisdiction certification burden:Simultaneous FCC, CE marking, BIS, and GB standard compliance requires dedicated regulatory affairs teams and extended testing cycles.
- Legacy semiconductor fab allocation:Power management IC shortages for inverter control boards are forcing production schedule adjustments and inventory build strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Residential Microwave Oven Market |
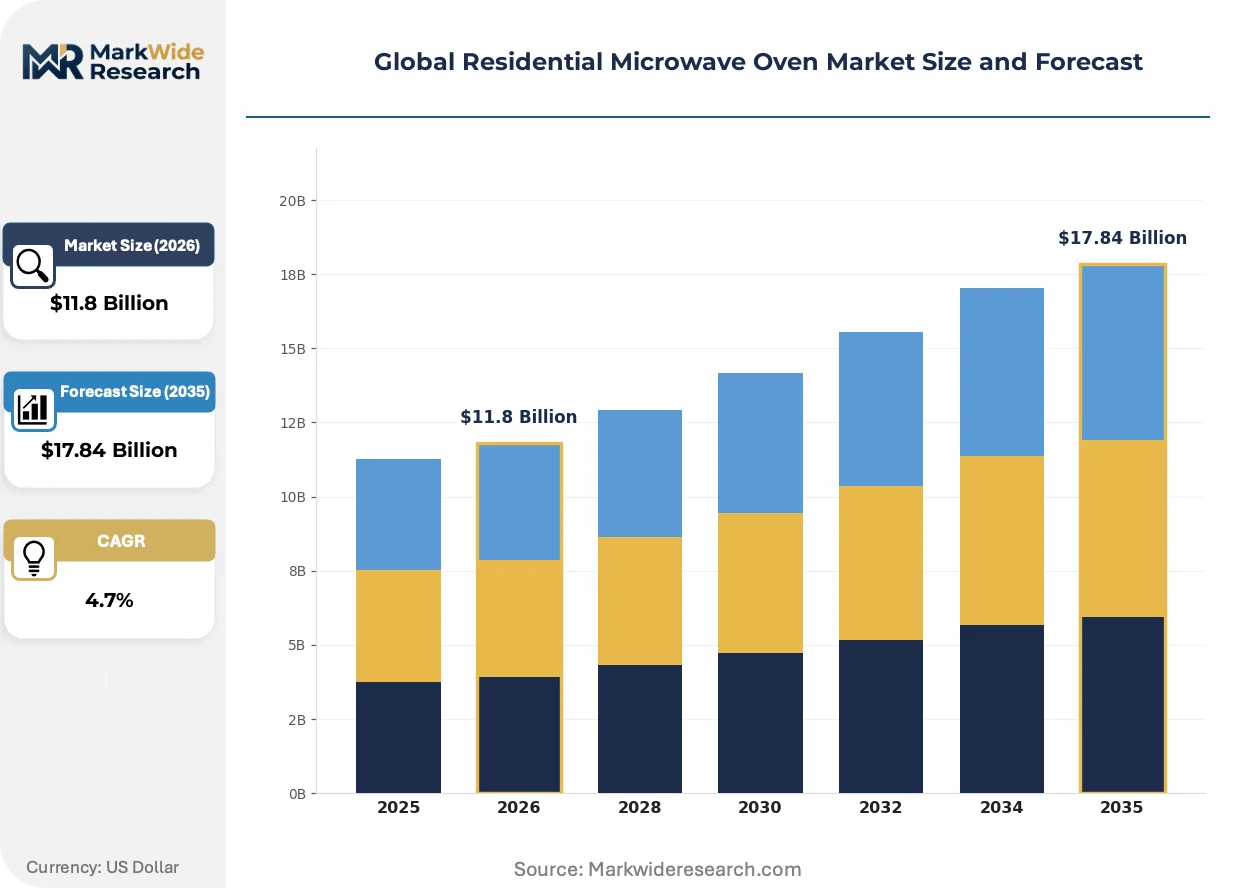
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $17.84 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-Range, Drawer Technology: Convection, Grill, Solo, Combination End User: Households, Apartments, Dormitories, Catering Services Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Panasonic Corporation, Haier Group Corporation, Samsung Electronics, Robert Bosch, Electrolux, LG Electronics, Midea Group, Galanz Enterprise Group, Whirlpool Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Residential Microwave Oven Market Strategic Shifts
Product development priorities are pivoting toward energy-efficient magnetron architectures and connectivity-enabled user interfaces as regulatory pressure and rental housing demographics reshape competitive requirements.
Inverter magnetron technology is converging with precision cooking algorithms to enable temperature-controlled sous-vide and fermentation modes previously unavailable in countertop appliances. Urban apartment dwellers in Seoul, Tokyo, and Singapore are adopting these units at premium price points. The convergence is compressing the addressable market for dedicated single-function cooking devices and expanding microwave replacement cycles.
REACH substance restrictions and RoHS lead-free solder mandates are forcing magnetron manufacturers to reformulate internal component metallurgy and ceramic insulator compositions. Industrial consequence includes extended validation timelines for redesigned vacuum tube assemblies. European OEMs sourcing from Chinese contract manufacturers are absorbing disproportionate compliance costs relative to domestic producers.
Rental housing turnover is fragmenting buyer profiles across student accommodations, short-term lease units, and co-living developments, compressing distribution channel concentration. Traditional big-box retail is losing share to direct-to-consumer platforms and property manager bulk procurement. This behavioral shift is most visible in Germany, the United Kingdom, and the Netherlands where institutional landlord portfolios dominate new residential construction.
Global Residential Microwave Oven Market Segmentation
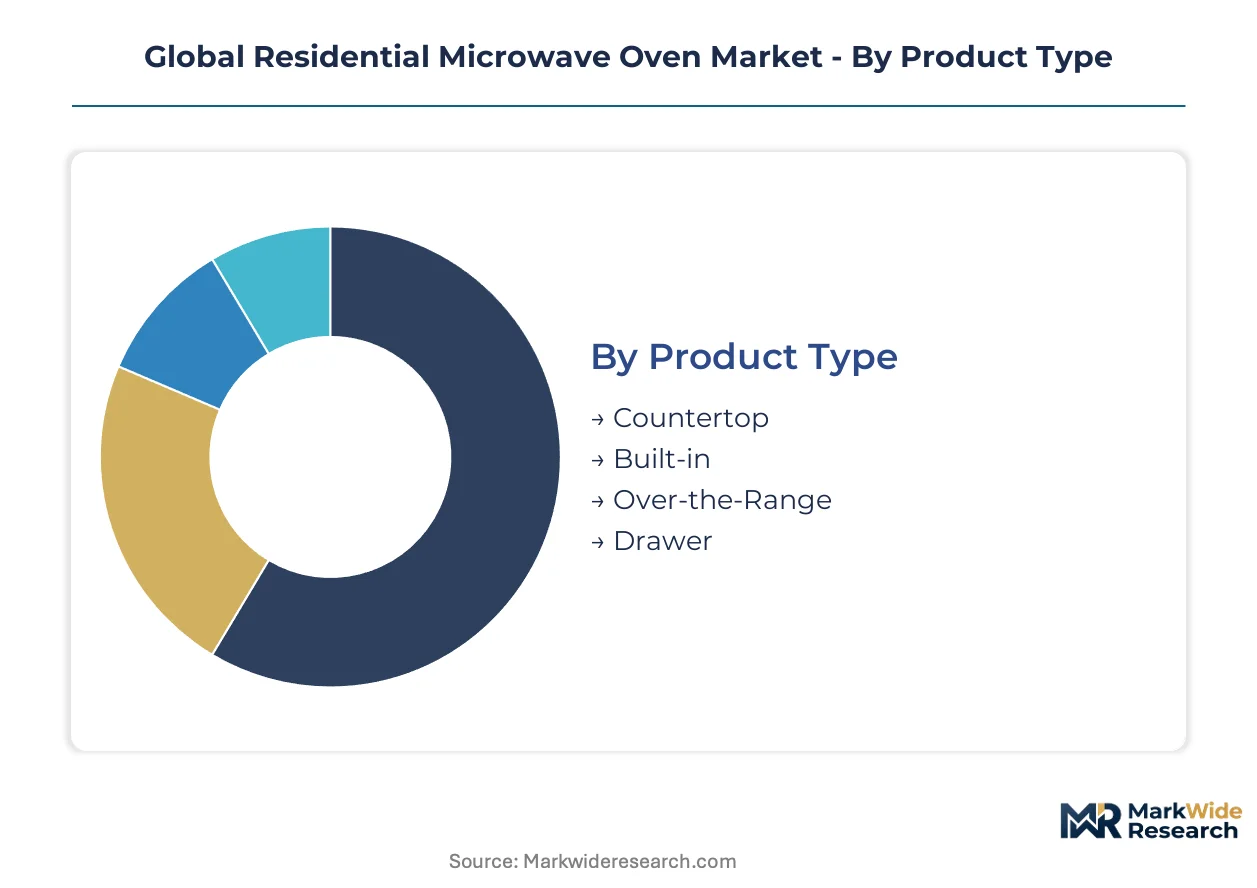
Segmentation in the residential microwave oven market reveals divergent growth vectors across installation constraints, cooking modality preferences, and rental housing demographics. Manufacturers configure product portfolios around these fault lines to capture volume in emerging economies while extracting premium in developed urban markets.
Product Type:
Countertop units dominate unit shipments through zero installation requirements, while built-in and over-the-range formats command margin premiums in renovation-driven replacement cycles.
- Countertop:Portable electric appliances requiring no fixed installation, utilizing standard 120V/230V outlets. Demand concentrates in Shanghai, Mumbai, and Berlin rental markets where tenant turnover favors movable assets over permanent fixtures. FCC electromagnetic emission compliance and EU CE marking under the Low Voltage Directive govern safety certification for these high-volume units.
- Built-in:Cabinet-integrated units designed for custom kitchen installations with standardized cutout dimensions. Demand concentrates in Seoul, Tokyo, and Singapore condominium renovations where space optimization overrides portability concerns. Installation complexity limits distribution to specialized retail channels and contractor networks.
- Over-the-Range:Combined microwave and ventilation units mounted above cooking surfaces, integrating exhaust fan functionality. Popular in North American suburban housing with dedicated range hood infrastructure.
- Drawer:Pull-out compartment design installed below countertop level, enabling ergonomic access without overhead reach. Gaining traction in aging-in-place residential modifications and universal design specifications.
Today's leader: Countertop. Tomorrow's challenger: Built-in.
Technology:
Technology segmentation tracks the migration from basic reheating functionality toward precision cooking capabilities enabled by inverter magnetron architectures.
- Convection:Hybrid systems combining microwave radiation with forced-air heating elements to enable baking and roasting functions. Demand concentrates in metropolitan India—Mumbai, Bangalore, Delhi NCR—where first-time appliance buyers seek dual-function value without dedicated oven investment. EU Ecodesign energy efficiency mandates are accelerating inverter-based convection adoption across European product lines.
- Solo:Microwave-only units utilizing basic magnetron technology for reheating and defrosting. Retains economy-tier dominance in price-sensitive emerging markets where feature adoption faces budget constraints.
- Grill:Microwave units with supplemental quartz or sheath heating elements for surface browning. Popular in Middle Eastern and Mediterranean cooking applications requiring charred texture.
- Combination:Multi-mode systems integrating microwave, convection, and grill functions with programmable sequencing. Voice control and app connectivity are converging with these units to enable ecosystem lock-in with Alexa and Google Home platforms.
Convection systems are climbing the fastest as consumers substitute dedicated appliances with multi-function countertop units.
End User:
End user segmentation reflects housing tenure patterns reshaping distribution channel priorities and product durability requirements.
- Households:Owner-occupied single-family residences with longer replacement cycles and preference for premium features. China's GB standards and NMPA-equivalent quality certifications create compliance layers for brands serving this quality-conscious segment.
- Apartments:Multi-unit rental housing with space constraints and tenant-driven portability needs. Institutional landlord portfolios in Germany, the United Kingdom, and the Netherlands are driving bulk procurement through direct-to-consumer platforms.
- Dormitories:Student housing with high turnover, theft risk, and price sensitivity. Distribution concentrates in seasonal back-to-school retail windows.
- Catering Services:Small commercial foodservice operations utilizing residential-grade equipment for cost containment. India's BIS mandatory certification filters substandard imports serving this price-driven segment.
Apartment dwellers are expanding most quickly as urbanization concentrates populations in space-constrained rental housing.
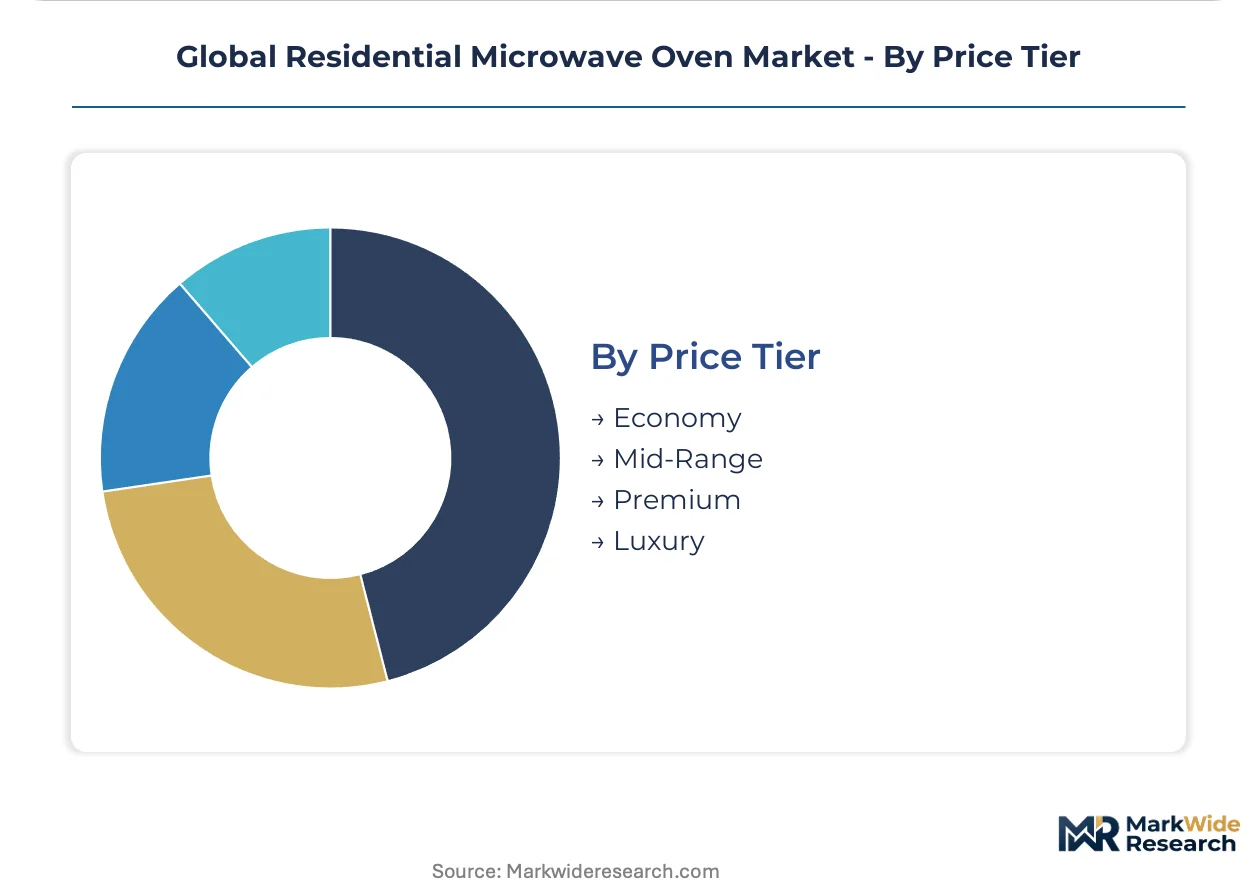
Price Tier:
Price tier segmentation maps feature bundling and material quality to purchasing power distribution across geographies.
- Economy:Basic solo microwave functionality with mechanical controls and reduced magnetron lifespan specifications. Dominates rural China and tier-3 Indian cities where price elasticity constrains feature adoption.
- Mid-Range:Digital controls, preset cooking programs, and improved interior coatings. Represents the volume center in developed market replacement cycles.
- Premium:Inverter magnetron technology, sensor cooking, and stainless steel finishes. REACH substance restrictions and RoHS lead-free solder mandates are forcing reformulation of internal component metallurgy in these higher-specification units.
- Luxury:Designer aesthetics, smart home integration, and professional-grade convection performance. Constrained by air fryer substitution capturing meal-preparation occasions at lower price points.
Premium tier holds margin leadership. Economy tier faces steepest compression from component cost volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's apartment construction dwarfs India's volume, yet India's first-time buyer penetration offers faster percentage expansion for convection-microwave hybrids.
United States
FCC electromagnetic emission testing extends product launch windows by 8-14 weeks for modified inverter designs. Over-the-range formats dominate suburban housing in Texas and Florida where dedicated range hood infrastructure remains standard. Big-box retail channels in the Midwest anchor volume distribution for replacement cycles.
China
GB standards and NMPA-equivalent quality certifications create compliance layers for brands serving owner-occupied households. Space-constrained housing in Shanghai, Shenzhen, and Beijing concentrates demand for compact countertop units with zero installation footprint. Guangdong province anchors captive manufacturing clusters for volume production.
Germany
EU Ecodesign regulations accelerate inverter magnetron adoption across European product lines. Institutional landlord portfolios in Berlin and Munich drive bulk procurement through direct-to-consumer platforms. REACH substance restrictions force reformulation of internal component metallurgy in higher-specification units.
India
BIS mandatory certification for electronic appliances filters substandard imports serving price-driven segments. Mumbai, Bangalore, and Delhi NCR present underpenetrated demand for convection-microwave hybrids. First-time appliance buyers in these metropolitan markets seek dual-function value without dedicated oven investment.
Japan
METI efficiency guidelines and JIS standards govern product safety and market access for domestic manufacturers. Specialized vacuum tube design expertise concentrates at legacy suppliers in Osaka and Nagoya, constraining in-house R&D expansion. Urban apartment dwellers in Tokyo and Yokohama adopt inverter-based precision cooking units at premium price points.
Global Residential Microwave Oven Market Competitive Environment
East Asian producers anchor one tier; North American and European specialists hold brand equity positions in developed market channels. The vendor base organizes around three strategic archetypes: semiconductor-integrated conglomerates controlling upstream magnetron costs, volume-oriented contract manufacturers with captive provincial facilities, and brand-centric incumbents competing on retail channel relationships. Dominant competitive moves include backward integration into magnetron supply and accelerated inverter technology substitution timelines.
Within the semiconductor-integrated tier, Samsung Electronics and Panasonic Corporation exemplify players leveraging component supply chain control to manage inverter magnetron economics. Haier Group Corporation and Midea Group occupy positions among Chinese volume producers with manufacturing concentration in coastal industrial clusters. LG Electronics and Whirlpool Corporation anchor the brand-equity tier, with the former representing Korean conglomerate diversification and the latter exemplifying North American retail channel incumbency.
| Leading Market Players |
|---|
| Panasonic Corporation |
| Haier Group Corporation |
| Samsung Electronics |
| Robert Bosch |
| Electrolux |
| LG Electronics |
| Midea Group |
| Galanz Enterprise Group |
| Whirlpool Corporation |
| Others |
Value Chain & Pricing Dynamics
Neodymium magnet costs from Chinese rare earth processors cascade through magnetron manufacturing into three-tier pricing structure across premium, standard, and economy levels. EU Ecodesign compliance investments compress margins in mid-range tiers while rental housing procurement concentrates volume buying power.
Pricing Analysis
Capacity additions in Guangdong province are reshaping price floors for economy-tier countertop units. Three-tier pricing structure across premium, standard, and economy levels separates inverter-equipped convection models from basic solo units. Price differentiation stems from certification grade (CE marking under Low Voltage Directive vs. basic safety compliance) and volume scale. Pricing pressure stems from air fryer substitution capturing meal-preparation occasions. Economy-tier buyers in rural India and tier-3 Chinese cities exhibit highest price sensitivity; luxury-tier households in Tokyo and Seoul show lowest.
Supply Chain Analysis
Returns and refurbishment flows from European rental housing turnover are creating secondary supply channels for countertop units. Manufacturing concentrates in China, South Korea, and Japan. Magnetron production draws from neodymium magnets, ceramic insulators, and copper windings. Single-source vulnerability concentrates at legacy Japanese vacuum tube designers. Distribution runs through big-box retail in North America and direct-to-consumer platforms in European institutional landlord markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Global residential microwave oven market dynamics reflect late-cycle quality migration as inverter precision cooking displaces basic reheating functionality. Urban apartment construction in Shanghai, Mumbai, and Berlin concentrates demand for premium-tier compact units.
For Market Incumbents: Extend inverter technology substitution timelines to outpace air fryer substitution threats. Consolidate magnetron supply relationships in Guangdong and Osaka industrial clusters. Invest in CE marking and FCC certification infrastructure to compress multi-jurisdiction launch windows. Channel control through property manager bulk procurement platforms defends volume position against direct-to-consumer entrants.
For New Entrants and Emerging Players: Direct-to-consumer platforms unlock underpenetrated metropolitan India demand for convection-microwave hybrids. Target Mumbai, Bangalore, and Delhi NCR first-time appliance buyers seeking dual-function value without dedicated oven investment. Voice control integration with Alexa and Google Home ecosystems provides go-to-market differentiation against established brand equity.
For Investors and Strategic Acquirers: Roll-up economics work for regional service networks because right-to-repair regulatory momentum mandates component availability and repair documentation. Five-to-ten year viability hinges on magnetron engineering talent scarcity concentrating at legacy suppliers. Monitor EU Ecodesign efficiency threshold revisions as inflection indicator for inverter adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Technology Migration | Variable power control enables sous-vide and fermentation modes previously unavailable in countertop appliances. |
| Smart Home Platform Integration | Voice control and app connectivity create ecosystem lock-in with Alexa and Google Home platforms. |
| Direct-to-Consumer Channel Expansion | Property manager bulk procurement in Germany and Netherlands bypasses traditional big-box retail concentration. |
| Right-to-Repair Compliance Investment | EU legislation mandating component availability reshapes service network economics for independent technicians. |
| Magnetron Supply Backward Integration | Captive manufacturing in Guangdong province anchors volume production cost control for Chinese producers. |
Study Parameters
Direct dialogue with appliance manufacturing executives, regulatory affairs specialists at certification bodies, procurement managers at institutional landlords, and aftermarket service technicians grounded qualitative findings. Secondary validation drew from FCC electromagnetic emission filings, EU Ecodesign directive documentation, BIS certification registries, and customs trade data. Bottom-up shipment modeling and top-down market sizing triangulated volume estimates across the analysis window.
Top-down macroeconomic indicators and bottom-up segment-level demand curves converged in the analytical framework. Segmentation dimensions modeled include product type (countertop, built-in, over-the-range, drawer), technology tier (solo, grill, convection, combination), and end-user housing tenure. CAGRs derived from historical trajectory analysis and technology substitution elasticity. Forecast inputs incorporated inverter magnetron cost curves and urban apartment construction permits in Shanghai, Mumbai, and Berlin.
Rare earth export quota volatility, REACH substance restriction amendments, and air fryer penetration acceleration are the dominant revision risks. Forecasts reflect assumptions about magnetron efficiency thresholds and rental housing turnover rates. Practitioners should monitor neodymium price movements, EU right-to-repair legislative progress, and smart home platform partnership announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Italy Home Appliances Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Europe White Goods Market
Home Appliances
Household Induction Cooktops Market
Home Appliances
Sweden Laundry Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
Oman Major Home Appliances Market
Home Appliances
Middle East and Africa Laundry Appliances Market
Home Appliances
Kuwait Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
Major Home Appliances Market
Home Appliances
Residential Washing Machine Market
Home Appliances
UAE Laundry Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market