
 United Kingdom Major Home Appliances Market | 2026-2036
United Kingdom Major Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Major Home Appliances Market Analytics
UK Ecodesign regulations is expanding the minimum efficiency thresholds for refrigerators, washing machines, and dishwashers entering the market. Samsung Electronics leverages its vertical integration in compressor technology to sustain cost advantages across the mid-tier segment. BSH Hausgeräte GmbH anchors its position through specialized engineering in built-in oven systems. Miele & Cie. KG differentiates via extended product lifecycles and premium service infrastructure.
United Kingdom major home appliances encompass electrically powered domestic equipment with rated capacities typically exceeding 50 liters for refrigeration or 5 kg for laundry, manufactured through stamped steel forming, injection-molded polymer assembly, and hermetic sealing of refrigerant loops, serving residential food preservation, textile cleaning, and thermal cooking functions. Refrigerators and washing machines occupy the largest volume positions, though smart appliances command the most attractive margin pools due to embedded IoT modules and subscription-enabled service layers. Energy-efficient technology leads replacement-driven sales as households respond to utility cost pressures and labeling transparency.
The Office for Product Safety and Standards enforces UK-specific Ecodesign and energy labeling rules post-Brexit, while BEIS frameworks shape carbon-reduction timelines for household equipment. These standards force manufacturers to redesign motor systems and insulation packages, raising compliance costs but also clearing lower-efficiency imports from the market. Stakeholders must monitor how the UK's divergence from EU F-Gas Regulation and evolving smart appliance cybersecurity standards will reshape supplier qualification requirements and channel certification obligations.
Market Dynamics
UK Ecodesign mandates from the Office for Product Safety and Standards are compressing replacement cycles by disqualifying lower-efficiency imports, while rental property portfolio upgrades concentrate demand in Greater London and the South East refurbishment corridors.
Growth Catalysts
- BEIS carbon-reduction timelines:Household equipment decarbonization targets accelerate motor system redesigns and insulation package investments, forcing landlords into appliance refresh programs ahead of enforcement dates.
- Smart appliance IoT modules:Embedded connectivity enables subscription-enabled service layers and predictive maintenance revenue streams, attracting premium buyer segments in metropolitan housing stock.
- Greater London housing turnover:Elevated refurbishment activity in premium residential segments sustains above-average replacement rates for built-in refrigeration and laundry systems.
Market Restraints
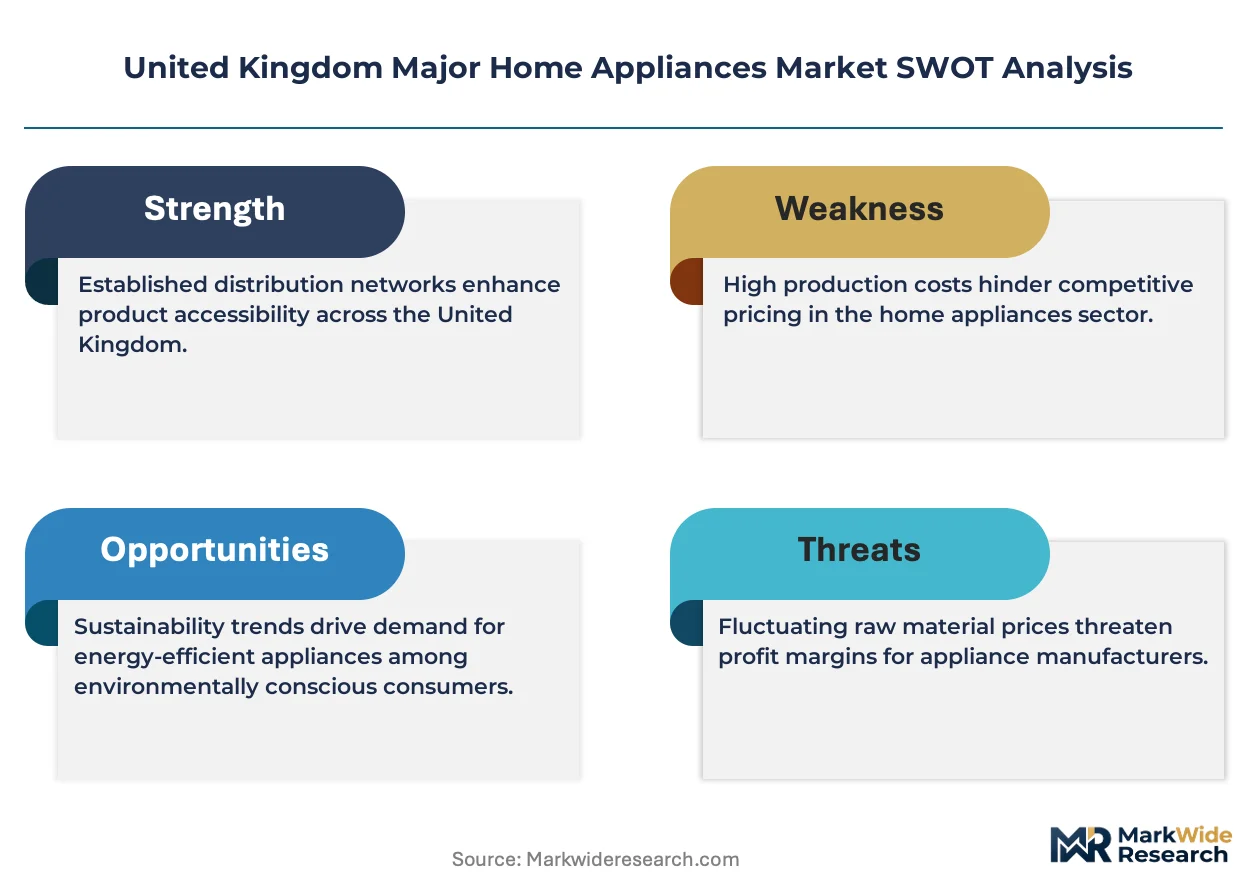
- Copper and steel input volatility:Stamped steel forming and hermetic sealing processes face margin compression from commodity price swings in sheet metal and refrigerant-grade copper tubing.
- Post-Brexit regulatory divergence:UK's departure from EU F-Gas Regulation creates parallel compliance obligations, raising certification costs for cross-channel suppliers and fragmenting inventory pools.
- Extended product lifecycles in premium tiers:Miele and comparable engineered-for-durability positioning slows replacement frequency among high-income owner-occupiers.
Strategic Opportunities
- UK-specific cybersecurity standards for smart appliances:Evolving certification requirements for connected domestic equipment create first-mover advantages for IoT-native manufacturers over retrofitting incumbents.
- Energy labeling transparency mandates:Utility cost pressures and mandatory efficiency disclosure shift buyer preference toward A-rated models, compressing distribution of lower-tier imports.
- South East premium refurbishment clusters:Concentrated housing stock turnover in Surrey, Berkshire, and Buckinghamshire corridors supports dedicated built-in appliance specification channels.
Industry Challenges
- Hermetic sealing technician scarcity:Refrigerant loop certification and compressor replacement skills face pipeline gaps as vocational training programs lag equipment complexity advances.
- Dual compliance inventory management:Warehousing parallel EU and UK-certified product lines strains working capital and obsolescence risk for distribution intermediaries.
- Legacy housing electrical infrastructure:Pre-1990s residential wiring in Northern England and Midlands rental stock limits high-capacity induction cooking and heat-pump dryer penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Major Home Appliances Market |
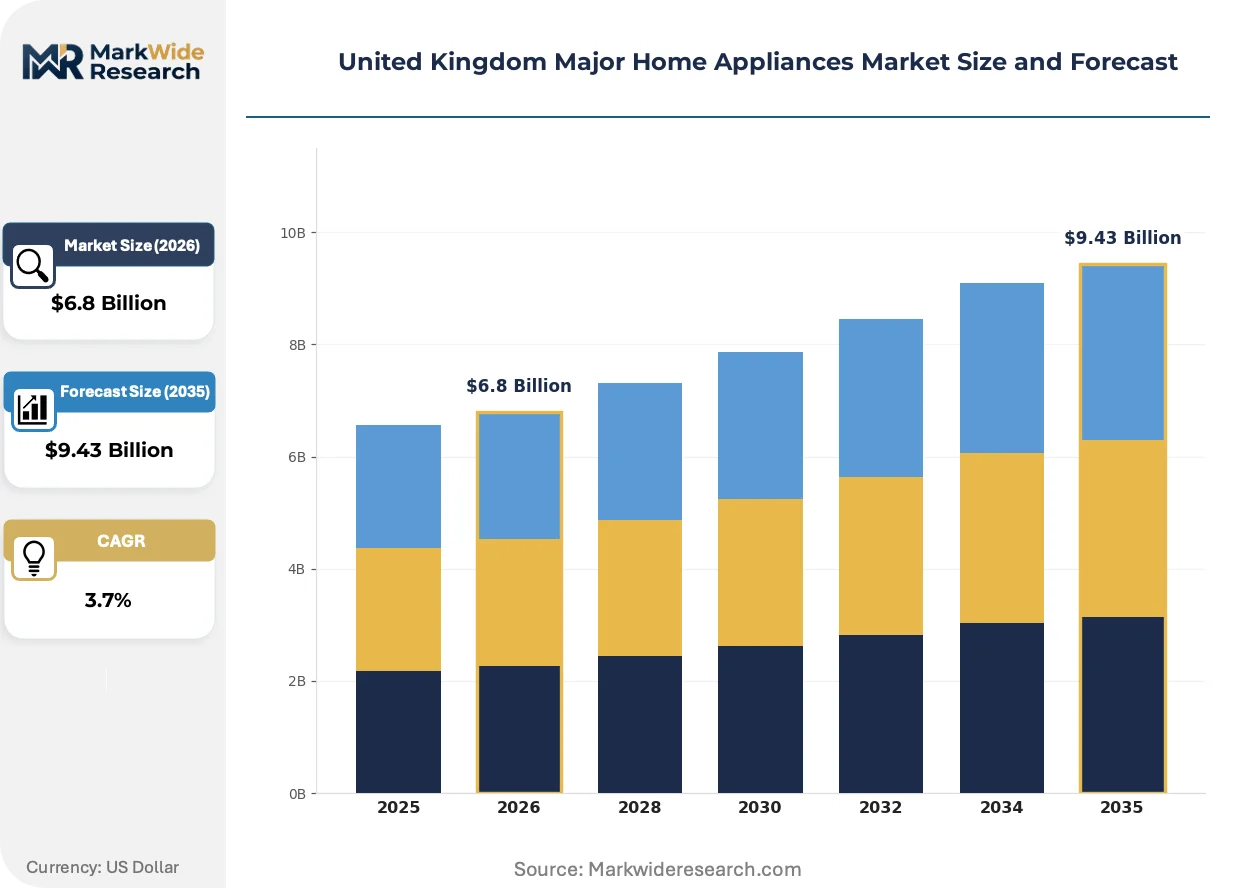
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.43 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Dishwashers Technology: Smart Appliances, Energy-Efficient, Conventional, Hybrid End User: Households, Hospitality, Rental Properties, Institutions Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Samsung Electronics, Miele & Cie. KG, Whirlpool Corporation, Dyson Ltd., LG Electronics, BSH Hausgeräte GmbH, Haier Smart Home, Arcelik AS, Electrolux AB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Major Home Appliances Market Evolving Landscape
Connected appliance ecosystems and predictive service platforms are restructuring how UK households interact with domestic equipment, compressing traditional ownership models toward subscription-enabled maintenance relationships.
Heat-pump dryer technology is consolidating its position in UK laundry segments by extracting moisture through closed-loop refrigerant cycles rather than resistive heating. Buy-to-let landlords in London and the South East are specifying these systems at accelerating rates to meet EPC rating improvements. This consolidation is compressing the addressable market for vented and condenser alternatives while elevating average transaction values.
The Office for Product Safety and Standards is enforcing UKCA marking requirements for Ecodesign compliance, creating a parallel certification track distinct from retained EU law. Manufacturers must submit separate technical documentation and testing protocols, raising fixed compliance costs per SKU. Built-in oven and refrigeration categories face the steepest documentation burdens as thermal performance and energy consumption metrics diverge from continental standards.
Landlords are unbundling appliance procurement from property management contracts, creating direct relationships with manufacturer service networks. This bypasses traditional electrical retail intermediaries in the private rental sector. The shift is most visible in Greater London's institutional build-to-rent developments, where portfolio-scale purchasing agreements prioritize uptime guarantees over upfront capital expenditure minimization.
United Kingdom Major Home Appliances Market Segmentation
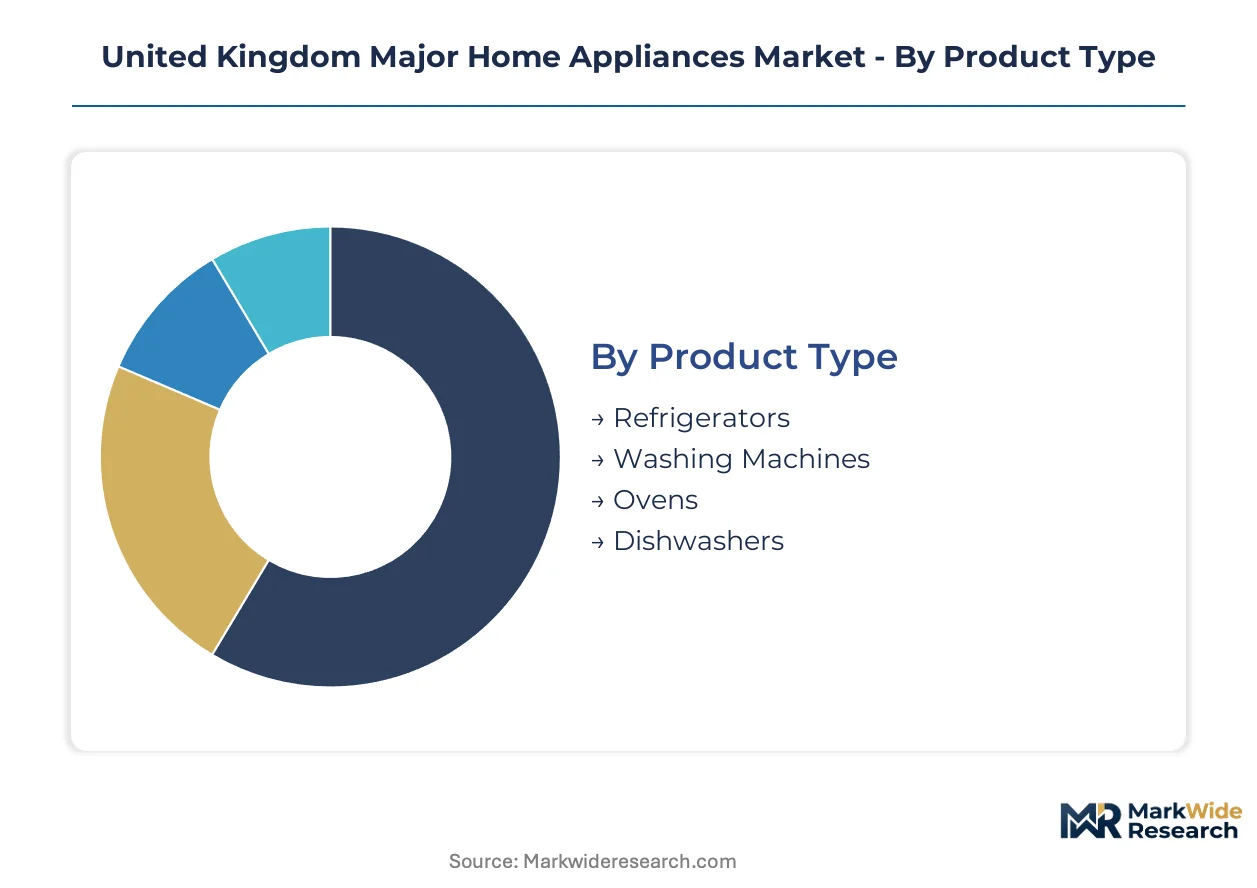
Appliance specification in the United Kingdom diverges sharply across buyer archetypes, with landlords prioritizing compliance-grade efficiency while owner-occupiers weigh connectivity features. Channel selection and technology tier further stratify procurement patterns, concentrating margin pools in distinct supply chain configurations.
Product Type:
Buyer investment intensity varies by replacement frequency and installation complexity, with built-in systems commanding specification cycles that differ materially from freestanding alternatives.
- Refrigerators:Hermetically sealed compressor systems with rated capacities exceeding 50 liters serve residential food preservation across freestanding and integrated configurations. Demand concentrates in Greater London's refurbishment corridors, where EPC rating improvements drive A+++ rated specification ahead of enforcement dates.
- Washing Machines:Drum-based textile cleaning equipment with 5 kg and larger rated loads incorporate motor system redesigns for BEIS compliance. South East premium housing clusters sustain above-average replacement rates as landlords unbundle procurement from property management contracts.
- Ovens:Thermal cooking equipment spans built-in and freestanding formats with divergent thermal performance testing protocols under UKCA marking requirements.
- Dishwashers:Water-based automated cleaning systems face steepest documentation burdens as water consumption metrics diverge from retained EU law.
Volume sits with Refrigerators; growth tilts toward Washing Machines.
Technology:
Embedded capability tiers separate subscription-enabled service relationships from commodity replacement cycles, restructuring margin capture across the value chain.
- Smart Appliances:IoT-native equipment with embedded connectivity modules and predictive maintenance algorithms enable recurring revenue streams through service layer subscriptions. BEIS carbon-reduction timelines accelerate specification in metropolitan housing stock where electrical infrastructure supports high-capacity connectivity.
- Energy-Efficient:Motor system and insulation package investments achieving A-rated labeling transparency under OPSS Ecodesign mandates. Greater London rental property portfolios drive concentrated demand as landlords front-run enforcement dates.
- Conventional:Non-connected equipment with baseline functionality serves price-sensitive segments and legacy housing electrical infrastructure limitations.
- Hybrid:Partial connectivity with manual override systems bridges capability gaps in Northern England and Midlands rental stock.
Volume concentrates in Energy-Efficient tiers; Smart Appliances climb the fastest.
End User:
Procurement centralization and specification authority determine channel access and service relationship structures.
- Households:Owner-occupier buyers with individual decision authority prioritize extended product lifecycles and premium service infrastructure, slowing replacement frequency in high-income segments.
- Hospitality:Commercial-grade durability requirements and uptime guarantees concentrate demand in manufacturer-direct service networks.
- Rental Properties:Institutional build-to-rent developments in Greater London prioritize portfolio-scale purchasing agreements with uptime guarantees over upfront capital expenditure minimization.
- Institutions:Public sector procurement frameworks with extended payment terms and compliance documentation requirements.
Volume concentrates in Households; Rental Properties gain share fastest.
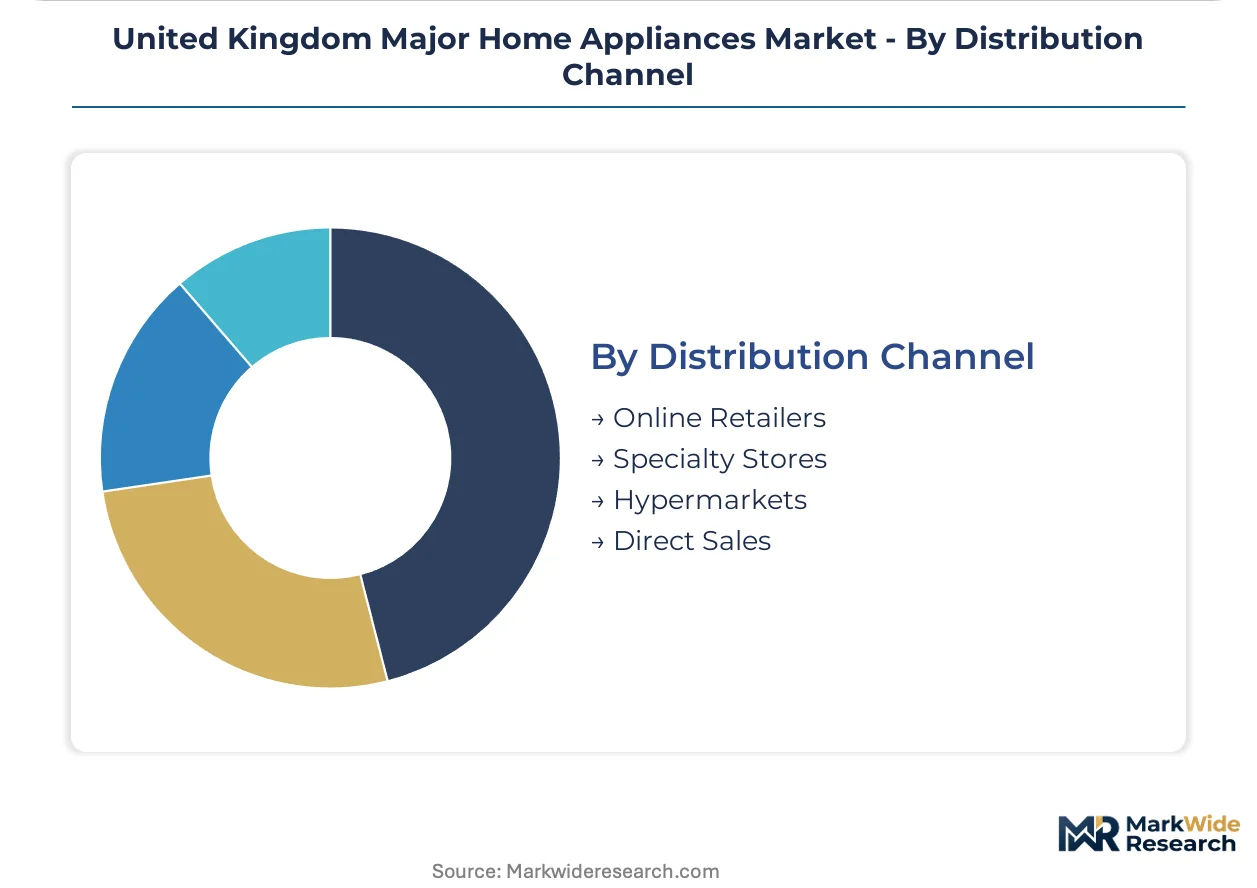
Distribution Channel:
Channel selection determines inventory risk allocation and certification cost recovery mechanisms.
- Online Retailers:Digital-first fulfillment with centralized warehousing faces dual compliance inventory management strain from parallel EU and UK-certified product lines.
- Specialty Stores:Built-in appliance specification channels concentrate in Surrey, Berkshire, and Buckinghamshire corridors with dedicated technical consultation capabilities.
- Hypermarkets:High-volume freestanding equipment distribution with standardized delivery and installation services.
- Direct Sales:Manufacturer-controlled relationships bypass traditional electrical retail intermediaries, most visible in Greater London's institutional landlord segment.
Volume concentrates in Online Retailers; Direct Sales expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise Zones in Greater London and the South East concentrate appliance demand through accelerated housing stock turnover and institutional build-to-rent development pipelines. These designated areas channel investment into premium refurbishment corridors where EPC compliance mandates drive replacement cycles.
Greater London
Institutional landlords in Tower Hamlets and Southwark unbundle appliance procurement from property management contracts, creating direct manufacturer relationships. The Office for Product Safety and Standards enforces UKCA marking for Ecodesign compliance in these corridors. Canary Wharf and Stratford build-to-rent clusters specify smart-enabled laundry and refrigeration systems at portfolio scale.
South East England
Surrey, Berkshire, and Buckinghamshire refurbishment corridors sustain dedicated built-in appliance specification channels. BEIS carbon-reduction timelines accelerate landlord refresh programs ahead of enforcement dates. Guildford and Reading housing turnover concentrates demand for A+++ rated refrigeration and heat-pump dryer systems.
Midlands
Birmingham and Nottingham rental stock faces legacy electrical infrastructure constraints limiting high-capacity induction cooking penetration. The UK's divergence from EU F-Gas Regulation creates parallel compliance obligations for cross-channel suppliers. Leicester manufacturing heritage supports technician training pipelines for hermetic sealing and compressor replacement skills.
North England
Manchester and Leeds private rental sectors exhibit extended product lifecycles as cost-conscious landlords delay appliance refresh cycles. OPSS energy labeling transparency mandates shift remaining demand toward A-rated models. Sheffield and Newcastle housing stock turnover remains below national averages, compressing replacement frequency.
Scotland
Edinburgh and Glasgow tenement housing stock presents installation complexity for built-in appliance retrofit. Scottish Government energy efficiency programs supplement UK-wide Ecodesign mandates with additional landlord grant schemes. Aberdeen's post-energy-transition housing market shows reduced refurbishment velocity compared to central belt cities.
United Kingdom Major Home Appliances Market Competitive Landscape
East Asian producers anchor volume manufacturing tiers; European specialists hold premium engineering positions through extended lifecycle positioning. The vendor structure concentrates around integrated compressor technology and built-in system engineering capabilities. Three archetypes dominate: IoT-native platform builders, durability-focused premium engineers, and scale-driven cost optimizers. Competitive moves center on portfolio diversification into subscription-enabled service layers and captive supply chain control over motor and insulation components.
Among East Asian fabricators, Samsung Electronics and LG Electronics occupy positions emphasizing vertical integration in compressor technology and smart connectivity modules. BSH Hausgeräte GmbH represents the European specialist archetype through its engineering concentration in built-in oven systems and thermal performance optimization. Miele & Cie. KG exemplifies the durability-premium positioning with extended product lifecycle architecture and service infrastructure depth. These three anchors illustrate the geographic split between scale-driven platform economics and engineering-intensive specialization that structures competitive dynamics across replacement cycle segments.
| Leading Market Players |
|---|
| Samsung Electronics |
| Miele & Cie. KG |
| Whirlpool Corporation |
| Dyson Ltd. |
| LG Electronics |
| BSH Hausgeräte GmbH |
| Haier Smart Home |
| Arcelik AS |
| Electrolux AB |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between UKCA-marked and parallel EU inventory pools manifests in dual pricing structures and fragmented warehousing configurations across distribution networks. OPSS Ecodesign mandates compress margins on non-compliant stock while elevating price premiums for certified equipment in Greater London refurbishment corridors.
Pricing Analysis
Short lead-time availability commands premium positioning as landlords front-run BEIS enforcement dates with accelerated procurement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Pricing pressure stems from copper and steel input volatility compressing stamped steel forming margins. Rental property buyers exhibit highest price sensitivity; institutional build-to-rent developments show lowest sensitivity due to portfolio-scale uptime guarantees.
Supply Chain Analysis
Freight cost elevation from post-Brexit customs processing strains cross-channel inventory positioning for distribution intermediaries. Manufacturing concentrates in China, South Korea, and Poland for compressor systems and hermetic sealing components. Supply chains rest on refrigerant-grade copper tubing, injection-molded polymer resins, and IoT connectivity modules. Single-source vulnerability sits with hermetic sealing technician training pipelines lagging equipment complexity advances. Distribution runs through online retailers facing dual compliance inventory management strain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK Ecodesign regulations administered by OPSS construct a cost-of-compliance moat that disadvantages lower-efficiency imports and rewards certified incumbents with cleared market access.
For Market Incumbents: Acquire compressor technology assets to anchor cost positions against commodity input volatility. Consolidate built-in appliance specification channels in Surrey, Berkshire, and Buckinghamshire corridors. Defensive positioning requires investment in UKCA technical documentation capabilities ahead of divergence from retained EU law.
For New Entrants and Emerging Players: Enter via cybersecurity certification for smart appliance ecosystems as UK-specific standards evolve. White-space concentrates in heat-pump dryer segments displacing vented alternatives in London build-to-rent clusters. Direct sales relationships with institutional landlords bypass entrenched electrical retail intermediaries.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to East Asian fabricators seeking European brand equity and distribution infrastructure. Long-term viability favors targets with captive service network density and subscription-enabled maintenance revenue streams. Signal to monitor: divergence velocity between UK and EU F-Gas Regulation creating parallel compliance cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Investment | OPSS Ecodesign mandates clear lower-efficiency imports, rewarding compliant documentation capabilities. |
| Service Network Expansion | Landlord unbundling of procurement from property management contracts elevates uptime guarantee value. |
| Heat-Pump Dryer Portfolio Shift | BEIS carbon-reduction timelines compress addressable market for resistive-heating alternatives. |
| Smart Appliance Cybersecurity Certification | Evolving UK-specific standards create first-mover positioning against retrofitting incumbents. |
| Direct Sales Channel Development | Institutional build-to-rent developments in Tower Hamlets and Southwark prioritize manufacturer relationships. |
Research Methodology
Document review covered OPSS regulatory filings, BEIS policy frameworks, and customs trade data, complemented by interviews with appliance manufacturer product strategy directors, electrical retail category buyers, landlord portfolio managers, hermetic sealing technician training providers, and built-in kitchen specification consultants. Secondary validation drew from SEC filings of listed fabricators, Nielsen retail audit data, and housing stock turnover statistics. Bottom-up SKU-level demand modeling triangulated against top-down macroeconomic consumption projections.
Cross-referencing historical replacement cycle patterns against expert panel input on regulatory enforcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user archetype, and distribution channel. CAGRs derived from installed base depreciation curves and efficiency mandate phase-in schedules. Forecast inputs incorporated EPC rating improvement trajectories and electrical infrastructure upgrade timelines in legacy housing stock.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated OPSS enforcement or prolonged copper price volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Mexico Home Appliances Market
Home Appliances
Electric Fireplace Market
Home Appliances
UAE Small Home Appliances Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Italy Small Home Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
Germany Home Appliances Market
Home Appliances
Refrigerator Market
Home Appliances
Brazil Laundry Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
UAE Major Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Washing Machine Market