
 Undercounter Refrigerators Market | 2026-2036
Undercounter Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Undercounter Refrigerators Market Analytics
A capital-intensity divergence between stainless-steel fabrication capabilities and basic assembly operations is reorganizing competitive tiers in the undercounter refrigeration sector. True Manufacturing Co., Inc. leverages captive metalworking capacity to control lead times on custom commercial units. Liebherr Group anchors its position through precision compressor integration and European distribution density. SMEG S.p.A. differentiates via design-forward residential offerings that command premium positioning in renovation channels.
Undercounter refrigerators are compact refrigeration units engineered for installation beneath standard counter heights, typically operating within temperature ranges of 32°F to 40°F for food preservation and 45°F to 64°F for wine storage applications. These units employ forced-air or static cooling systems with polyurethane insulation cores to maintain thermal stability in constrained commercial and residential spaces. The built-in product category leads volume shipments due to seamless kitchen integration requirements, while outdoor-rated units represent the fastest-growing segment as alfresco dining installations expand. Healthcare facilities and restaurants drive application-level demand, with beverage dispensing configurations capturing concentrated margin pools through specialized dispensing hardware and regulatory compliance features.
The U.S. Department of Energy and the EPA enforce minimum efficiency standards and refrigerant phase-down schedules that compel compressor redesigns and insulation upgrades across the North American supply base. The EU Ecodesign Directive and F-Gas Regulation mandate lower-global-warming-potential refrigerants and standardized energy labeling, reshaping product portfolios for European market access. Stakeholders must monitor refrigerant transition timelines and efficiency threshold escalations to align R&D roadmaps with compliance deadlines that outpace typical product development cycles.
Market Dynamics
Compressor redesign mandates from the U.S. Department of Energy and the EPA's refrigerant phase-down schedules are forcing simultaneous thermal efficiency and insulation upgrades across the North American supply base. These dual compliance pressures are compressing product development timelines while elevating engineering capability requirements.
Growth Catalysts
- Commercial Kitchen Expansion:Foodservice renovation cycles in Germany are accelerating replacement rates for compact refrigeration units in hospitality settings.
- Outdoor-Rated Segment Surge:Alfresco dining installations are expanding demand for weather-resistant undercounter units with specialized sealing and corrosion-resistant materials.
- Healthcare Facility Modernization:Hospitals and clinics are specifying built-in refrigeration for medication storage, driven by Joint Commission temperature monitoring requirements.
Market Restraints
- Stainless Steel Input Volatility:Fluctuations in nickel and chromium prices squeeze fabrication margins for premium-grade cabinet construction.
- Compressor Supply Concentration:European and Asian compressor manufacturers control critical component supply, creating vulnerability for North American assemblers.
- Refrigerant Transition Friction:The EU F-Gas Regulation mandates lower-GWP alternatives that require system redesigns incompatible with existing service infrastructure.
Strategic Opportunities
- India Foodservice Infrastructure:Quick-service restaurant chains are penetrating tier-2 cities where undercounter refrigeration penetration remains minimal.
- IoT-Enabled Predictive Maintenance:Sensor integration and cloud analytics are converging to create subscription-based service revenue streams.
- Residential Wine Storage Premiumization:Design-forward renovation channels in Italy and France command margin premiums for dual-zone temperature control units.
Industry Challenges
- Refrigerant Certification Bottlenecks:EPA Section 608 technician certification requirements slow service network scaling for new low-GWP systems.
- Legacy Control System Integration:BACnet and Modbus protocol compatibility issues complicate smart building deployments in commercial foodservice environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Undercounter Refrigerators Market |
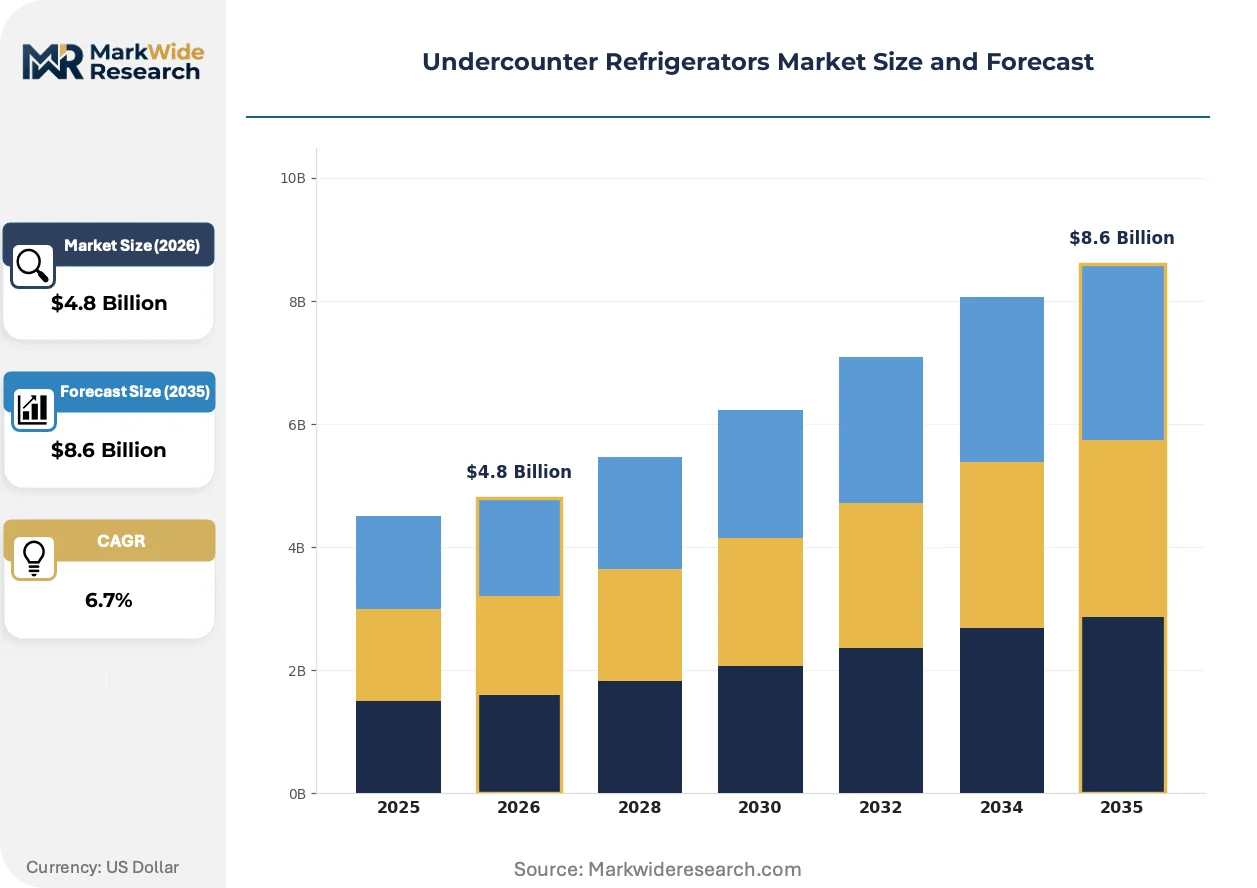
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual Zone, Built-In, Freestanding, Outdoor End User: Restaurants, Offices, Educational Institutions, Healthcare Facilities Application: Food Storage, Beverage Dispensing, Wine Cooling, Display Installation: Countertop, Under Counter, Wall-Mounted, Integrated |
| Companies Covered | True Manufacturing Co., Inc., Sub-Zero, Inc., Liebherr Group, Electrolux AB, Haier Group Corporation, Bosch Home Appliances, Whirlpool Corporation, KitchenAid, SMEG S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Undercounter Refrigerators Market Evolving Landscape
Active thermal management architectures are displacing conventional static cooling approaches across premium product tiers. These shifts are compressing competitive differentiation timelines while elevating software and sensor integration requirements.
Variable-speed compressor technology is displacing fixed-speed units in mid-tier and premium segments. Restaurant chains with 24-hour operations are adopting these systems to reduce energy consumption during low-load periods. This displacement is compressing price premiums for entry-level products while expanding service revenue attachment rates.
The EPA's refrigerant phase-down schedule under the AIM Act is mandating transition to A2L-classified lower-flammability alternatives. Equipment manufacturers must redesign safety systems and ventilation protocols to maintain certification. North American commercial kitchen operators face accelerated capital replacement cycles as service infrastructure for legacy refrigerants contracts.
Specification authority is migrating from general contractors to foodservice design consultants who bundle refrigeration into integrated kitchen systems. These consultants prioritize seamless aesthetic integration and remote monitoring capabilities over standalone unit economics. This shift is most pronounced in German and Austrian commercial renovation markets where design-build contracts dominate procurement.
Undercounter Refrigerators Market Segmentation
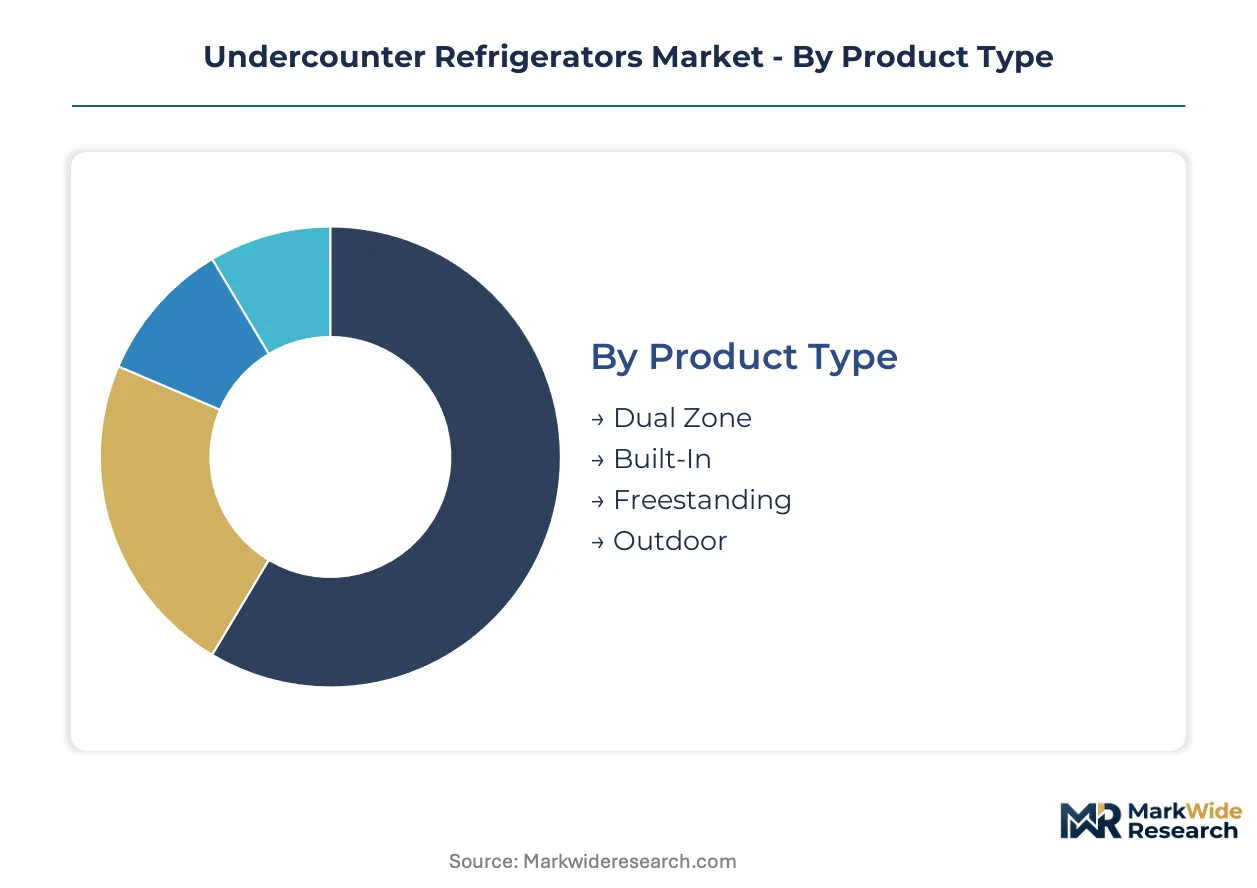
Undercounter refrigerator segmentation reveals divergent engineering requirements across product architectures and use environments. Installation constraints and end-use thermal specifications determine component selection, insulation density, and control system complexity.
Product Type:
Built-in and outdoor-rated units dominate export flows to North American and Middle Eastern markets, while freestanding configurations serve primarily domestic European renovation channels.
- Built-In:Seamless cabinet integration demands front-venting compressor architectures and zero-clearance side panels. German foodservice renovation cycles and premium residential construction in Austria accelerate specification rates for these units.
- Outdoor:Weather-resistant sealing systems and 304-grade stainless exteriors withstand humidity and temperature swings. Alfresco dining installations in Saudi Arabia and UAE hospitality developments drive the steepest demand expansion for this category.
- Dual Zone:Independent temperature compartments serve simultaneous food preservation and wine storage through separate evaporator circuits.
- Freestanding:Castor-mounted mobility and finished side panels suit rental properties and temporary foodservice operations.
Built-in configurations command the established base. The steepest expansion runs through outdoor-rated engineering.
End User:
Healthcare and restaurant procurement concentrates in high-specification tiers, while educational institutions prioritize standard-efficiency units with extended warranty coverage.
- Healthcare Facilities:Joint Commission temperature monitoring mandates and medication storage protocols require calibrated digital controls with alarm integration. US hospital modernization programs and clinic expansion in Texas and Florida concentrate capital deployment.
- Restaurants:24-hour operational cycles and high-door-opening frequency necessitate heavy-duty compressor sizing and rapid recovery insulation. Quick-service chain penetration in India's tier-2 cities creates emerging volume concentration.
- Offices:Break-room configurations emphasize beverage dispensing compatibility and low acoustic signatures.
- Educational Institutions:Cafeteria and laboratory applications balance first-cost constraints against energy certification requirements.
Healthcare procurement commands the established base. The steepest expansion runs through restaurant chain deployment.
Application:
Food storage and beverage dispensing applications diverge in regulatory compliance burden and hardware attachment rates.
- Food Storage:HACCP-aligned temperature logging and NSF-certified interior materials satisfy health department inspection protocols. Commercial kitchen operators in Germany and France specify these units for prep-line accessibility.
- Beverage Dispensing:Integrated tap systems and line cooling hardware capture concentrated margin pools through specialized dispensing equipment. US stadium and arena renovation projects drive specification volume.
- Wine Cooling:Dual-zone temperature control and UV-resistant glass doors serve residential renovation channels in Italy and France.
- Display:LED-illuminated interiors and glass door configurations support retail impulse purchase environments.
Food storage commands the established base. Beverage dispensing climbs the fastest on hardware integration premiums.
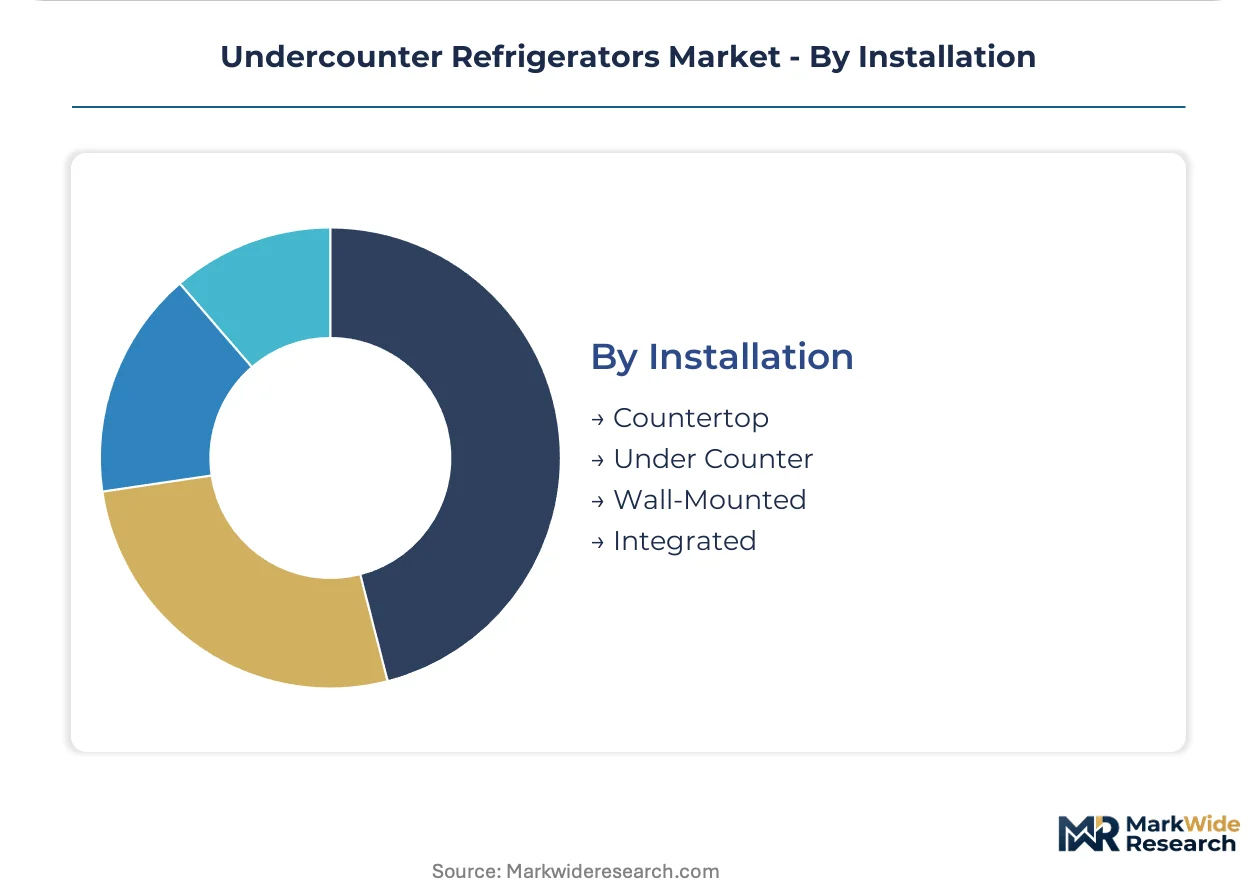
Installation:
Countertop and wall-mounted configurations serve space-constrained urban environments, while integrated installations demand coordinated kitchen system design.
- Under Counter:Standard 34-inch height compliance and toe-kick ventilation define the core product architecture. This configuration anchors volume across all geographic markets.
- Integrated:Panel-ready exteriors and handle-less design merge with custom cabinetry aesthetics. Premium residential construction in Munich and Vienna accelerates specification.
- Countertop:Compact footprints suit studio apartments and mobile foodservice operations with severe space constraints.
- Wall-Mounted:Elevated installation clears floor space for cleaning protocols in healthcare and laboratory settings.
Under counter installations command the established base. Integrated configurations gain share fastest on design-build contract expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in German and Austrian renovation channels, while cost-sensitive procurement dominates Indian quick-service expansion. This asymmetry fragments margin structures across major demand centers.
United States
Stadium renovation cycles and healthcare facility modernization drive specification volume for beverage dispensing and medication storage units. The EPA's refrigerant phase-down schedule under the AIM Act forces accelerated capital replacement timelines. Texas and Florida hospital clusters concentrate procurement for Joint Commission-compliant temperature monitoring systems.
Germany
Foodservice design consultants bundle refrigeration into integrated kitchen systems for commercial renovation projects. The EU F-Gas Regulation mandates lower-GWP refrigerant transitions that compress product development cycles. Munich and Vienna anchor premium residential construction demand for panel-ready integrated installations.
China
Quick-service restaurant chains penetrate tier-2 cities where undercounter refrigeration penetration remains minimal. The country's national appliance efficiency standards tighten compressor performance requirements annually. Yangtze River Delta manufacturing clusters supply forced-air cooling systems for domestic hospitality expansion.
India
Quick-service restaurant infrastructure builds out in tier-2 cities with severe space constraints favoring compact footprints. The Bureau of Indian Standards enforces energy labeling protocols for commercial refrigeration equipment. Maharashtra and Gujarat foodservice hubs accelerate replacement cycles for NSF-certified interior materials.
Saudi Arabia
Alfresco dining installations in hospitality developments drive the steepest demand expansion for outdoor-rated weather-resistant units. The country's national environmental regulator enforces efficiency standards for imported commercial appliances. Riyadh and Jeddah construction clusters specify 304-grade stainless exteriors for humidity-resistant sealing systems.
Undercounter Refrigerators Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the undercounter refrigeration sector. European specialists anchor precision compressor integration and thermal management capabilities, while Asian conglomerates leverage scale economies in basic assembly operations. The market structure organizes around three strategic archetypes: captive metalworking fabricators, precision engineering houses, and diversified appliance conglomerates. M&A activity concentrates on compressor technology acquisitions and regional distribution network consolidation.
Among European precision engineering houses, Liebherr Group and SMEG S.p.A. occupy positions emphasizing thermal system integration and design-forward residential positioning respectively. True Manufacturing Co., Inc. represents the captive metalworking archetype with upstream control over stainless fabrication capacity. These three anchors exemplify how competitive differentiation converges on either supply chain control or specification authority in renovation channels.
| Leading Market Players |
|---|
| True Manufacturing Co., Inc. |
| Sub-Zero, Inc. |
| Liebherr Group |
| Electrolux AB |
| Haier Group Corporation |
| Bosch Home Appliances |
| Whirlpool Corporation |
| KitchenAid |
| SMEG S.p.A. |
| Others |
Value Network & Pricing Analysis
EPA Section 608 technician certification requirements gate both supply qualification for low-GWP refrigerant systems and price differentiation between certified and uncertified service networks. This regulatory threshold simultaneously compresses margins for non-compliant assemblers while enabling premium capture for EPA-authorized distributors.
Pricing Analysis
Configured-to-order pricing for custom commercial units commands spreads of 40-60% above standard SKUs, driven by stainless-steel gauge specifications and compressor sizing. Three-tier pricing structure across premium, standard, and economy levels separates NSF-certified healthcare units from basic foodservice configurations. Cost compression in entry-level segments is intensifying because Asian conglomerates leverage scale economies in forced-air cooling system assembly. Quick-service restaurant chains in India exhibit highest price sensitivity, while German design-build contractors prioritize seamless aesthetic integration over unit economics.
Supply Chain Analysis
Strategic stockpiling of 304-grade stainless steel and polyurethane insulation cores dominates procurement behavior among captive metalworking fabricators, while just-in-time compressor sourcing prevails among basic assemblers. Component supply concentrates in China, Germany, and Japan, with European and Asian compressor manufacturers controlling critical forced-air cooling system production. Raw material dependencies rest on nickel and chromium price volatility, refrigerant transition inventories, and specialized sealing materials. Single-source vulnerability runs through compressor supply concentration. Distribution runs through foodservice design consultants in German renovation channels and direct OEM relationships in North American healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart building protocol convergence is repositioning undercounter refrigeration as an interoperability node within integrated kitchen ecosystems. BACnet and Modbus integration requirements are shifting specification authority toward foodservice design consultants who bundle thermal management into platform-based procurement.
For Market Incumbents: Consolidate captive metalworking capacity to defend margin position against Asian scale competitors. Deepen upstream control over 304-grade stainless fabrication in Yangtze River Delta clusters. Prioritize EPA Section 608 certification investment to capture service revenue attachment as refrigerant transitions accelerate. For New Entrants and Emerging Players: UL certification fast-track for outdoor-rated weather-resistant units unlocks white-space penetration in Saudi Arabian and UAE hospitality developments. Target beverage dispensing configurations in US stadium renovation cycles where hardware integration premiums concentrate. Pursue IoT-enabled predictive maintenance subscriptions as recurring revenue anchor. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision compressor integration tiers as variable-speed technology displaces fixed-speed architectures. Long-term viability favors precision engineering houses with thermal management software capabilities over basic assembly operators. Monitor EPA refrigerant phase-down enforcement intensity as inflection signal for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Compressor Technology Acquisition | Secures variable-speed thermal management capabilities for 24-hour foodservice operations. |
| Regional Distribution Consolidation | Densifies European network coverage to match Liebherr Group's specification authority in renovation channels. |
| IoT Platform Integration | Enables cloud-based predictive maintenance subscriptions for Joint Commission-compliant healthcare deployments. |
| Refrigerant Safety System Redesign | Maintains certification under EPA AIM Act A2L transition mandates for North American market access. |
| Panel-Ready Product Line Extension | Captures premium positioning in Munich and Vienna integrated kitchen construction cycles. |
Research Methodology
Cross-validation between primary interviews with foodservice design consultants and secondary regulatory filings anchors the qualitative findings. Stakeholder engagement spans commercial kitchen operators, healthcare facility engineers, compressor technology specialists, and stainless-steel fabrication plant managers. Secondary sources include EPA appliance efficiency standard dockets, EU F-Gas Regulation implementation reports, and customs trade data for refrigeration equipment flows. Bottom-up unit shipment modeling triangulates against top-down hospitality construction spending estimates.
Sensitivity analysis around refrigerant transition timelines and nickel price volatility bounds the projection range. Segmentation dimensions span product architecture, end-use environment, application type, and installation configuration, with compressor technology tier as an industry-specific overlay. CAGRs derive from fitted growth curves calibrated to renovation cycle frequency and replacement rate assumptions. Forecast inputs incorporate foodservice penetration rates in Indian tier-2 cities and alfresco dining installation growth in Middle Eastern hospitality developments.
Decision-makers should treat outputs as directional under stable regulatory enforcement and commodity price assumptions; material deviation would warrant model refresh. Forecasts reflect embedded assumptions about EPA phase-down adherence and EU Ecodesign Directive stringency. Revision becomes warranted when compressor supply concentration or refrigerant certification bottlenecks cross disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Steam Clothing Care System Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
European Built-In Refrigerator Market
Home Appliances
Israel Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
United States Home Appliances Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Household Refrigerators and Freezers Market
Home Appliances
Qatar Small Home Appliances Market
Home Appliances
South Africa Home Appliances Market
Home Appliances
Canada Laundry Appliances Market
Home Appliances
Europe Home Appliances Market
Home Appliances
Oman Major Home Appliances Market