
 Range Hood Market | 2026-2036
Range Hood Market Size, Share, and Industry Trends Forecast 2026-2036
Range Hood Market Analysis
Skilled HVAC installation labor scarcity across developed economies is redrawing competitive dynamics in the range hood industry. Whirlpool Corporation leverages its captive distribution through builder channels to sustain volume leadership in North American new construction. BSH Hausgeräte GmbH anchors its position through deep backward integration into motor and control systems manufacturing. Faber S.p.A. specializes in premium island and designer configurations that command higher margins in European kitchen renovations.
A range hood is a mechanical ventilation appliance engineered to capture, filter, and exhaust airborne grease, combustion products, smoke, odors, heat, and steam from cooking surfaces, typically achieving capture efficiencies of 70-90% depending on airflow velocity measured in cubic feet per minute and hood overhang geometry relative to the cooktop perimeter. Wall-mounted and under-cabinet configurations dominate residential volume due to standardized cabinet dimensions and retrofit compatibility, while island installations command premium positioning as open-plan kitchen designs proliferate in high-end construction. Exhaust technology leads on raw unit shipments but hybrid systems that switch between ducted and recirculating modes are gaining traction in multifamily and dense urban settings where external ducting faces structural constraints.
The US Department of Energy enforces minimum efficacy standards for kitchen ventilation fans, while the EU Ecodesign Directive and CE marking requirements under the EU Green Deal framework mandate energy consumption limits and noise level thresholds that filter non-compliant imports from Asian manufacturing clusters. The EPA's ENERGY STAR certification in the United States creates a voluntary tier that builders increasingly specify to meet green building code incentives in states like California and New York. Stakeholders must weigh whether to prioritize R&D investment in ultra-quiet blower architectures or to secure installation service partnerships that address the widening technician shortage affecting product pull-through at the point of kitchen remodel decisions.
Market Dynamics
The US Department of Energy's escalating ventilation efficacy mandates are compressing replacement cycles while simultaneously elevating R&D costs for blower motor architectures, forcing manufacturers to choose between premium quiet-performance positioning or volume-focused builder channel partnerships.
Growth Catalysts
- EU Ecodesign Directive:Energy consumption limits and noise thresholds under the EU Green Deal framework are filtering non-compliant imports and accelerating upgrade demand across Western European kitchen renovations.
- Urban middle-class expansion:Households in China and India are upgrading from basic exhaust fans to integrated range hood systems as apartment dwellers prioritize indoor air quality in dense metropolitan construction.
- Residential renovation spending:North American homeowners are redirecting discretionary budgets toward kitchen upgrades, with ventilation appliances capturing priority placement in remodel sequencing decisions.
Market Restraints
- Skilled HVAC labor scarcity:Certified installation technician shortages across developed economies are extending project timelines and depressing point-of-sale conversion rates in kitchen remodel channels.
- Copper and rare-earth motor inputs:Volatility in permanent magnet materials and winding copper is compressing gross margins for mid-tier blower assembly manufacturers without captive supply arrangements.
- Multifamily structural constraints:Dense urban buildings lacking external ducting infrastructure limit exhaust system penetration, forcing reliance on lower-margin recirculating configurations.
Strategic Opportunities
- India tier-2 city penetration:Underpenetrated markets in Pune, Ahmedabad, and Hyderabad present whitespace for ductless hybrid systems as apartment stock modernizes ahead of regulatory mandates.
- Smart home convergence:Integration of range hood controls with IoT kitchen ecosystems and voice-activated home automation platforms is opening premium pricing tiers in new construction specifications.
- California Title 24 incentives:Green building code credits for ENERGY STAR-certified ventilation are driving builder specification shifts in high-compliance states.
Industry Challenges
- Certification timeline compression:Simultaneous EPA ENERGY STAR validation and EU CE marking requirements are extending product launch windows and straining testing laboratory capacity.
- Cross-border motor sourcing:Reconfiguration of permanent magnet supply chains away from concentrated Asian processing is forcing qualification of alternative winding architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Range Hood Market |
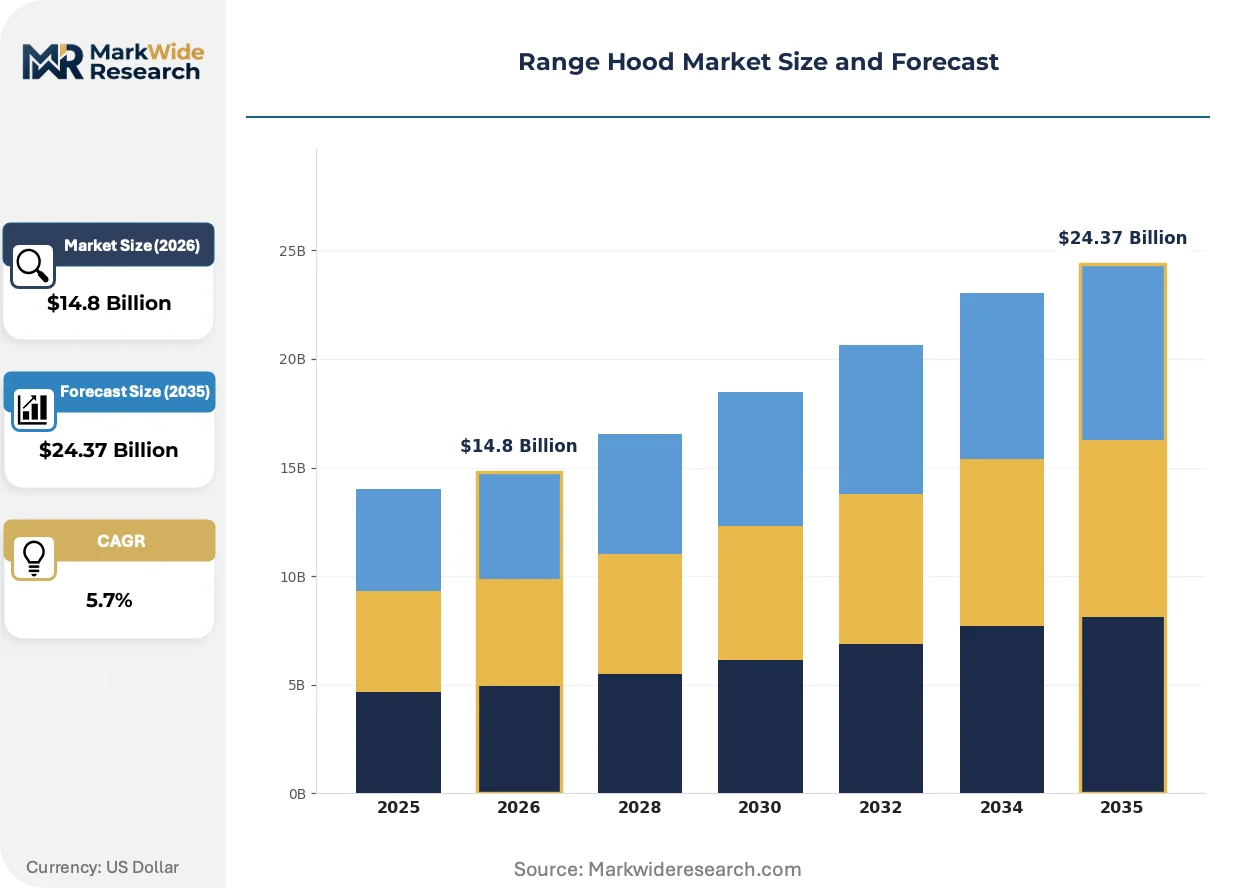
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted, Under-cabinet, Island, Downdraft Technology: Exhaust, Recirculating, Ductless, Hybrid End User: Residential, Commercial, Industrial, Custom Installations Installation Type: Built-in, Portable, Ceiling-mounted, Convertible |
| Companies Covered | Broan-NuTone, LLC, Whirlpool Corporation, BSH Hausgeräte GmbH, Faber S.p.A., KOBE Range Hoods Inc., Vent-A-Hood Company, Zephyr Ventilation, LLC, GE Appliances, a Haier Company, Electrolux AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Range Hood Market Emerging Trajectories
Active noise cancellation blower architectures and perimeter aspiration geometries are redefining performance benchmarks, while regulatory pressure on standby power consumption is accelerating control system semiconductor upgrades.
Perimeter extraction technology that captures effluent through slot geometries along the hood edge rather than central chimney discharge is displacing conventional canopy designs in premium European kitchen renovations. Italian and German appliance manufacturers are specifying these configurations for island installations where aesthetic minimalism commands priority. The shift is compressing market share for traditional deep-canopy suppliers unable to retool stamping operations.
EU F-Gas Regulation phase-down schedules are restricting hydrofluorocarbon refrigerants in heat pump auxiliary systems, indirectly pressuring hybrid range hood manufacturers to validate alternative thermal management approaches. The industrial consequence is elevated qualification costs for recirculating models with integrated heat recovery. Kitchen ventilation OEMs serving multifamily new construction in Germany and France are responding by accelerating partnerships with solid-state cooling technology developers.
Builder procurement consolidation toward turnkey kitchen package specification is disintermediating standalone ventilation distributors in North American new construction channels. National production homebuilders are consolidating appliance purchasing through captive subsidiaries, compressing vendor count and elevating volume commitment thresholds. This pattern is most visible in Texas, Florida, and Arizona metropolitan statistical areas where single-family permit activity concentrates.
Range Hood Market Segmentation
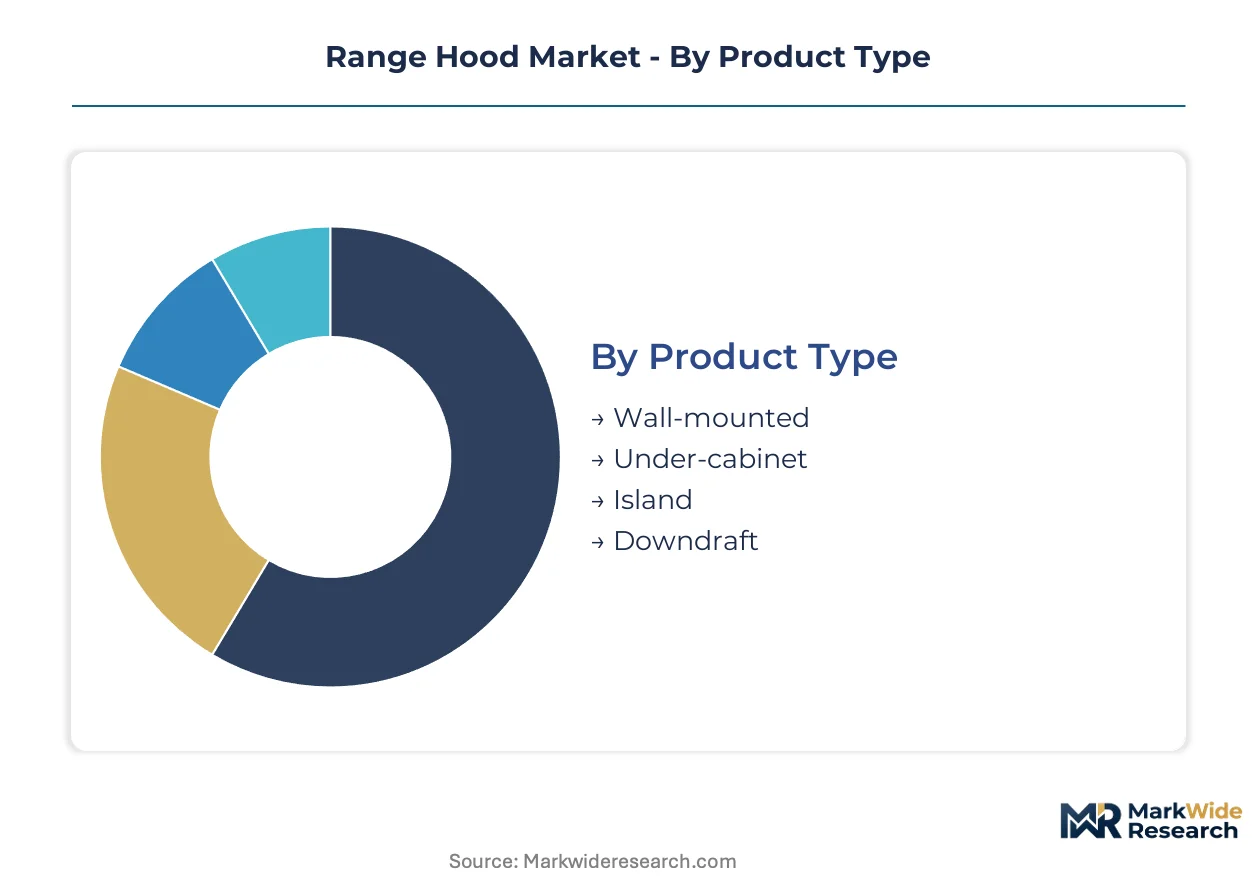
Range hood segmentation reveals divergent margin structures across product architectures and installation constraints. Product type and technology choices determine whether manufacturers capture value through premium positioning or volume scale.
Product Type:
Margin pools concentrate in island configurations where aesthetic differentiation commands pricing power, while wall-mounted units compete on installation efficiency and builder channel relationships.
- Wall-mounted:These hoods attach directly to kitchen walls above cooktops, utilizing standardized ducting runs and cabinet clearances that simplify installation logistics. Demand concentrates in North American single-family renovations where homeowners prioritize retrofit compatibility over design statement. EPA ENERGY STAR certification requirements are elevating blower motor costs and compressing margins for mid-tier suppliers lacking captive motor production.
- Island:Suspended from ceilings above central cooktops in open-plan kitchens, these units require custom ducting and specialized mounting hardware that extends installation timelines. European kitchen renovations in Germany and Italy drive premium demand as perimeter aspiration geometries displace conventional canopy designs. The aesthetic minimalism imperative allows Italian manufacturers to sustain gross margins above commodity tiers.
- Under-cabinet:Compact units integrated beneath overhead cabinetry dominate new construction volume through standardized dimensions.
- Downdraft:Retractable systems that rise from countertops preserve sightlines in contemporary kitchen designs but face airflow performance trade-offs.
The dominant share belongs to wall-mounted configurations, while island installations are closing the gap fastest on value contribution.
Technology:
Technology selection hinges on building infrastructure constraints and regulatory compliance trajectories across residential and commercial applications.
- Exhaust:Ducted systems that vent effluent outdoors achieve superior capture efficiency through direct airflow paths but require structural ducting availability. Demand concentrates in suburban North American construction where external wall access is routine. US Department of Energy ventilation efficacy mandates are forcing motor architecture redesigns that elevate R&D qualification costs.
- Hybrid:Switchable systems alternate between ducted and recirculating modes based on installation constraints or seasonal conditions. Apartment construction in China's tier-2 cities is driving adoption as developers prioritize flexibility over performance optimization. The dual-mode capability commands modest premiums in multifamily specifications where ducting infrastructure is inconsistent.
- Recirculating:Filter-based systems that return treated air indoors serve dense urban buildings lacking external ducting.
- Ductless:Portable configurations with charcoal filtration target rental markets and temporary installations.
Exhaust technology retains volume leadership, though hybrid systems are expanding most quickly in constrained urban construction.
End User:
End-user segmentation separates price-sensitive volume markets from specification-driven premium tiers with divergent procurement patterns.
- Residential:Single-family and multifamily households constitute the volume base, with renovation cycles driving replacement demand. North American homeowners redirecting discretionary budgets toward kitchen upgrades are prioritizing ventilation appliances in remodel sequencing. California Title 24 green building code credits for ENERGY STAR-certified products are shifting builder specifications in high-compliance states.
- Commercial:Restaurants, hotels, and institutional kitchens require heavy-duty extraction capacity with fire suppression integration and grease containment systems. Health department ventilation mandates in the United States and EU member states enforce minimum airflow rates that sustain replacement demand regardless of economic cycles.
- Industrial:Manufacturing and processing facilities with specialized fume extraction needs represent a niche specification market.
- Custom Installations:Bespoke architectural projects demand unique dimensions and finishes with extended lead times.
Residential applications command the dominant revenue share, while commercial end-use is gaining share fastest through regulatory replacement mandates.
Installation Type:
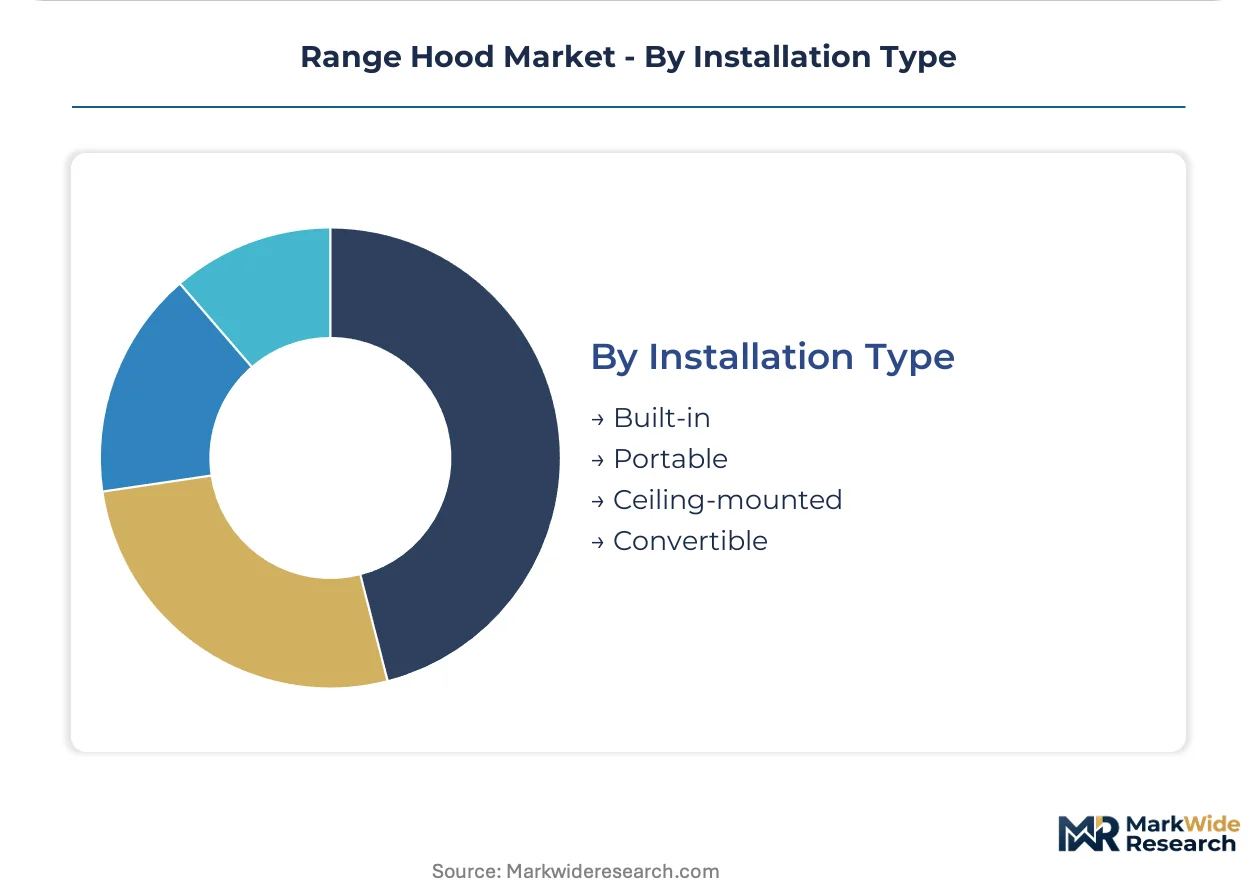
Installation architecture determines service revenue attachment and aftermarket parts potential across the product lifecycle.
- Built-in:Fully integrated hoods concealed within custom cabinetry demand specialized installation labor and finish carpentry coordination. European kitchen renovations favor these configurations where aesthetic continuity overrides cost considerations. Skilled HVAC technician scarcity across Germany and France is extending project timelines and elevating installed costs.
- Convertible:Adaptable mounting systems accommodate multiple installation scenarios with field-configurable ducting orientations. Production homebuilders in Texas and Florida metropolitan areas specify these units to reduce SKU complexity and inventory carrying costs. The flexibility reduces specification risk in volatile permit environments.
- Ceiling-mounted:Suspended units for island and peninsula configurations require structural reinforcement and electrical routing.
- Portable:Temporary or rental-market solutions with minimal installation requirements.
Built-in installations retain margin leadership, while convertible systems are climbing the fastest as builder procurement consolidates toward flexible specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential kitchen renovation patterns diverge sharply between mature markets favoring premium island configurations and emerging economies prioritizing functional exhaust upgrades from basic ventilation.
United States
Single-family kitchen remodels concentrate demand in suburban markets where external ducting access enables high-performance exhaust installations. EPA ENERGY STAR certification requirements under California Title 24 and New York green building codes are shifting builder specifications toward compliant blower architectures. Dallas-Fort Worth and Phoenix metropolitan statistical areas exhibit concentrated permit activity as national production homebuilders consolidate procurement through captive subsidiaries.
Germany
Western European renovation cycles drive premium demand for perimeter aspiration geometries in open-plan kitchen configurations. EU Ecodesign Directive energy consumption limits and noise thresholds filter non-compliant imports while accelerating replacement demand. The Stuttgart and Munich industrial clusters host specialized motor and control system manufacturers supplying backward-integrated appliance OEMs with qualified components.
China
Urban middle-class households in tier-2 cities upgrade from basic exhaust fans to integrated range hood systems as apartment construction modernizes. The country's national standards regulator enforces ventilation efficacy benchmarks that elevate motor architecture requirements for domestic manufacturers. Shanghai and Hangzhou metropolitan areas concentrate demand for hybrid ducted-recirculating systems in dense residential towers lacking external ducting infrastructure.
India
Underpenetrated markets in Pune, Ahmedabad, and Hyderabad present whitespace for ductless hybrid systems as apartment stock modernizes ahead of regulatory mandates. The Bureau of Indian Standards is developing ventilation appliance certification frameworks that will accelerate formal sector adoption. Mumbai and Delhi-NCR industrial corridors host assembly operations serving price-sensitive residential segments with localized product configurations.
Italy
European kitchen renovation demand concentrates in premium island installations where aesthetic minimalism commands pricing power. CE marking requirements under the EU Green Deal framework mandate energy consumption limits that sustain competitive pressure on design-forward manufacturers. The Emilia-Romagna and Lombardy manufacturing clusters specialize in perimeter extraction technologies displacing conventional canopy designs.
Range Hood Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on installation efficiency and regional channel relationships. The upper tier commands premium positioning through captive supply of motor and control architectures, while mid-scale fabricators rely on outsourced component sourcing. Three archetypes dominate: vertically integrated appliance conglomerates, design-specialized premium manufacturers, and volume-focused builder channel suppliers. Competitive dynamics center on strategic partnerships with HVAC installation networks and geographic expansion into underpenetrated tier-2 city markets.
Among North American appliance manufacturers, Whirlpool Corporation and GE Appliances occupy positions exemplifying scale-driven builder channel consolidation. European specialists Faber S.p.A. and BSH Hausgeräte GmbH represent the premium-tier vector where backward integration into motor manufacturing sustains margin structures. Broan-NuTone, LLC anchors the ventilation-focused specialist tier with concentrated exposure to residential retrofit demand.
| Leading Market Players |
|---|
| Broan-NuTone, LLC |
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Faber S.p.A. |
| KOBE Range Hoods Inc. |
| Vent-A-Hood Company |
| Zephyr Ventilation, LLC |
| GE Appliances, a Haier Company |
| Electrolux AB |
| Others |
Supply Flow & Price Mechanics
Permanent magnet motor substitution for conventional copper-wound architectures simultaneously redraws supply geography toward rare-earth processing clusters and compresses pricing power for mid-tier manufacturers lacking captive motor production. This input transition elevates qualification costs while bifurcating margin structures between integrated and outsourced assembly tiers.
Pricing Analysis
Long-term offtake agreements between national production homebuilders and appliance OEMs dominate North American new construction channels, locking in volume commitments that suppress spot-market premiums. Pricing stratifies across ENERGY STAR-certified premium tiers, standard efficiency mid-market configurations, and economy-grade recirculating units sold through retail distributors. Cost compression in the mid-tier is intensifying because copper and rare-earth magnet volatility erodes gross margins for fabricators without backward integration into motor manufacturing. Production homebuilders exhibit the highest price sensitivity due to consolidated procurement power, while European renovation contractors prioritize aesthetic differentiation over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies prevail among European appliance OEMs serving renovation channels, while North American builder-channel suppliers maintain strategic safety stock to accommodate volatile permit environments. Motor and control system manufacturing concentrates in China, Germany, and Italy, with rare-earth magnet processing anchored in Chinese industrial clusters. Supply chain risk centers on tariff exposure for permanent magnet imports subject to trade policy shifts. Distribution runs through captive builder subsidiaries in North American new construction and specialized HVAC distributors in European retrofit markets.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against substitution threats from solid-state cooling technologies and perimeter extraction geometries that displace conventional canopy designs in premium kitchen renovations.
For Market Incumbents: Secure backward integration into blower motor and control system manufacturing to defend margin structures against rare-earth input volatility. Deepen installation service partnerships with certified HVAC technicians to address labor scarcity depressing point-of-sale conversion in kitchen remodel channels.
For New Entrants and Emerging Players: Lead with ductless hybrid system configurations targeting India's tier-2 city apartment construction ahead of Bureau of Indian Standards certification mandates. Establish direct procurement relationships with municipal developers in Pune and Hyderabad to bypass established distributor networks.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated appliance conglomerates with captive motor production and established builder channel relationships. Acquisition targets should demonstrate qualified component supply arrangements and regional regulatory certification portfolios. Watch ENERGY STAR specification tightening and EU Ecodesign Directive enforcement schedules as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive supply of blower architectures insulates margins from rare-earth magnet price volatility affecting outsourced assemblers. |
| Certification Investment for ENERGY STAR and CE Marking | Dual compliance opens specification access to California Title 24 incentive programs and EU Green Deal procurement mandates. |
| Installation Service Network Partnership | HVAC technician scarcity across developed economies elevates pull-through conversion for OEMs with captive installation capacity. |
| Perimeter Extraction Technology Development | Slot-geometry designs displace conventional canopy configurations in premium European island kitchen renovations. |
| Geographic Expansion into India Tier-2 Cities | Underpenetrated markets in Pune and Ahmedabad present whitespace for ductless hybrid systems ahead of BIS regulatory mandates. |
Methodological Framework
Cross-validation between regulatory filing analysis and trade data anchors the qualitative findings across motor and control system supply chains. Primary interviews with HVAC installation contractors, production homebuilder procurement officers, appliance OEM product managers, and kitchen renovation contractors combined with secondary validation from EPA ENERGY STAR certification databases, EU Ecodesign Directive compliance registries, and customs import records. Bottom-up triangulation across product type, technology configuration, and end-use segmentation reconciles with top-down macroeconomic indicators.
Sensitivity analysis around copper and rare-earth magnet price trajectories, permit volatility in North American metropolitan statistical areas, and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, exhaust technology type, installation configuration, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and new construction permit flow projections. Industry-specific forecast inputs incorporate EPA ventilation efficacy mandate implementation schedules and EU F-Gas Regulation phase-down impacts on hybrid system thermal management.
The analysis sits within stated boundaries; outcomes outside sustained residential renovation spending levels or accelerated regulatory enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding motor input cost stabilization and technician labor availability. Revision becomes warranted when rare-earth magnet supply disruptions or trade policy shifts cross thresholds affecting qualified component procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Europe Home Appliances Market
Home Appliances
Israel Home Appliances Market
Home Appliances
India Major Home Appliances Market
Home Appliances
France Home Appliances Market
Home Appliances
Japan Major Home Appliances Market
Home Appliances
India Home Appliances Market
Home Appliances
Europe Personal Care Appliances Market
Home Appliances
United Kingdom Small Home Appliances Market
Home Appliances
Argentina Home Appliances Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
Bahrain Home Appliances Market
Home Appliances
European Built-In Refrigerator Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
United Kingdom Major Home Appliances Market