
 Asia-Pacific Home Appliances Market | 2026-2036
Asia-Pacific Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Home Appliances Market Outlook
Smart appliance connectivity is fragmenting traditional product architectures into modular hardware-software ecosystems. Haier Smart Home leverages its U+ platform to anchor ecosystem control across white-goods categories. Samsung Electronics competes through Bixby-integrated kitchen and laundry portfolios that sustain premium positioning in South Korea and Australia. Midea Group dominates manufacturing scale, operating some of the region's largest compressor and motor facilities to supply its own brands and third-party OEMs.
Asia-Pacific home appliances encompass electromechanical devices designed for domestic tasks, typically operating on 220-240V AC at 50Hz with energy-efficiency ratios measured by regional testing protocols; their primary purpose is to reduce household labor input while managing water, thermal, and electrical consumption. Refrigerators and air conditioners occupy the largest margin pools, though IoT-enabled and smart appliance segments are expanding fastest as connectivity modules drop below cost parity with conventional controls. Washing machines remain the most mature category, with drum-inverter technology now standard across mid-tier and premium offerings.
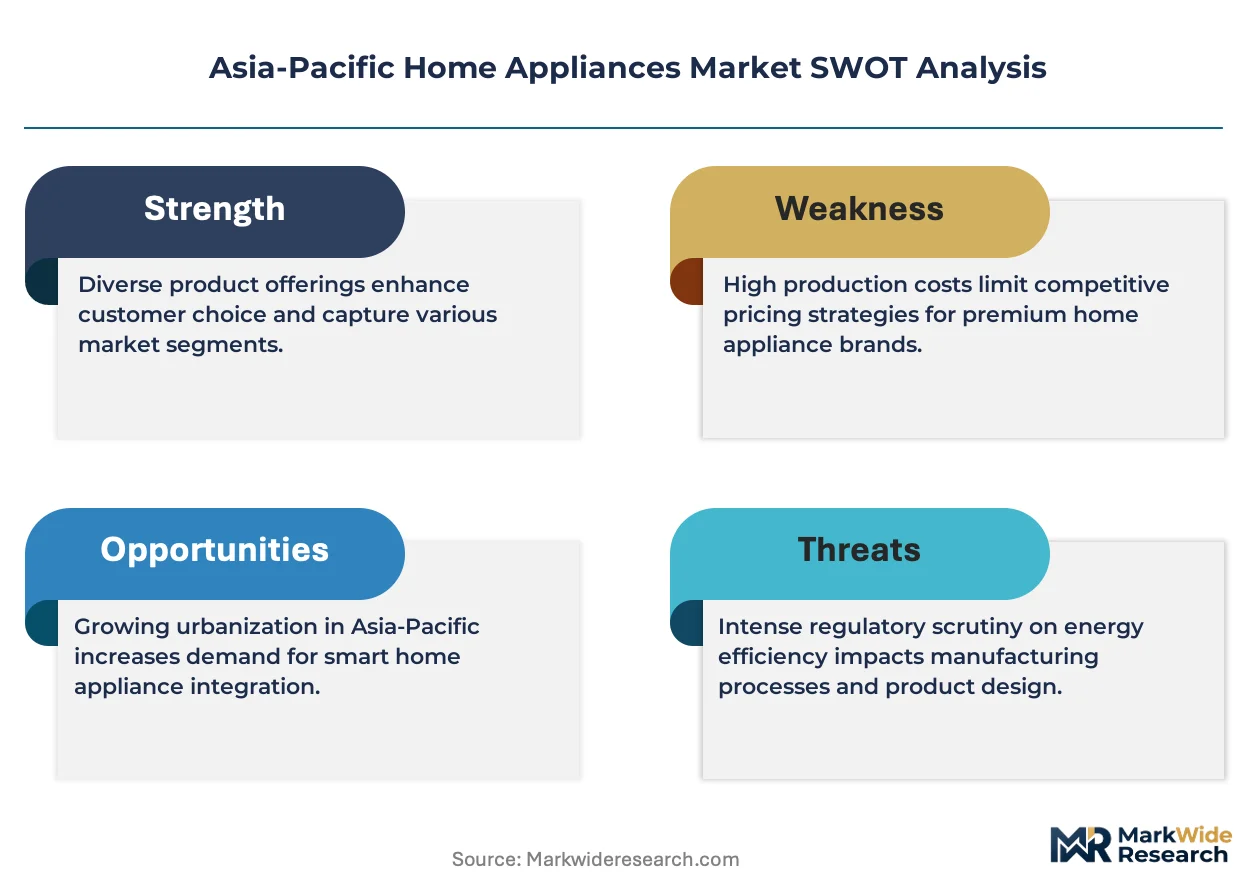
Japan's METI enforces Top Runner standards that continuously ratchet appliance efficiency baselines, while China's GB standards and MIIT circular economy directives mandate recyclability disclosures and restrict refrigerant chemistries. Australia's Equipment Energy Efficiency (E3) program, administered through state-level regulators, imposes mandatory labeling that directly shapes consumer purchase patterns and retailer inventory decisions. Stakeholders must monitor divergence between national efficiency regimes and the pace at which cross-border platform standards for IoT interoperability consolidate across the region.
Market Dynamics
India's Bureau of Indian Standards is ratcheting cooling-appliance efficiency thresholds faster than manufacturer cost curves can absorb, forcing wholesale redesigns of compressor architectures and refrigerant selections across the region's largest volume market.
Growth Catalysts
- Electrification infrastructure:India's Saubhagya scheme and comparable rural electrification programs in Indonesia and Vietnam are converting non-electric households into first-time appliance buyers, particularly for refrigeration and cooling loads.
- MIIT circular economy directives:China's mandates for refrigerant chemistry disclosure and recyclability labeling are accelerating closed-loop manufacturing investments that reduce virgin material intensity.
- Urban household formation:Southeast Asian metropolitan clusters including Jakarta, Manila, and Ho Chi Minh City are generating concentrated demand for connected kitchen ecosystems as condominium stock expands.
Market Restraints
- Copper and rare-earth input volatility:Compressor motor laminations and permanent-magnet materials face price swings that compress already-thin margins on entry-tier products.
- Refrigerant supply concentration:Hydrofluorocarbon blend production clusters in eastern China create single-source vulnerability for cooling-appliance manufacturers across the region.
- Cross-border platform fragmentation:Absence of unified IoT interoperability standards forces redundant hardware module configurations for national-market certification.
Strategic Opportunities
- Vietnam and Philippines penetration gaps:Air conditioner ownership rates in these markets lag regional medians by substantial margins, creating runway for mass-tier product introduction.
- India's western and southern state clusters:Maharashtra, Gujarat, Karnataka, and Tamil Nadu combine residential construction velocity with grid reliability improvements that support premium appliance uptake.
- Energy-efficiency incentive stacking:Australia's E3 program labeling requirements and India's BIS star-rating mandates are creating dual-certificate products that command retail price premiums.
Industry Challenges
- Embedded systems firmware talent:Shortage of engineers capable of integrating connectivity stacks with real-time motor control algorithms delays smart-appliance development cycles.
- Multi-jurisdiction certification sequencing:Divergent test protocols between Japan's METI Top Runner, China's GB standards, and India's BIS regimes extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Home Appliances Market |
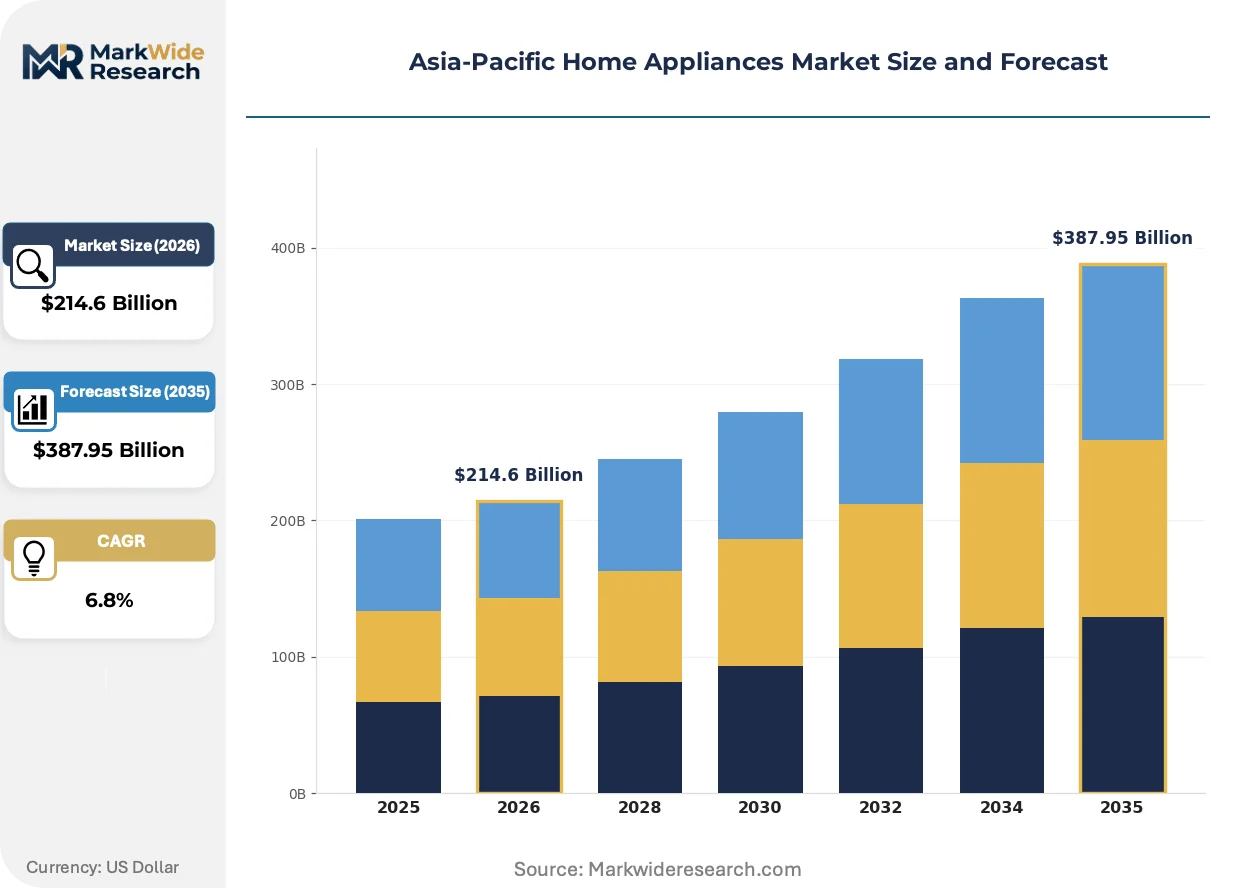
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $387.95 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwave Ovens, Air Conditioners End User: Residential, Commercial, Institutional, Hospitality Technology: Smart Appliances, Energy-Efficient, Conventional, IoT-Enabled Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | LG Electronics, Hisense Home Appliances, Haier Smart Home, BSH Hausgeräte, Whirlpool Corp., Midea Group, Panasonic Corporation, Gree Electric Appliances, Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Home Appliances Market Strategic Shifts
Connected appliance architectures are dissolving the boundary between hardware manufacturing and software service layers, compelling traditional electromechanical producers to build or acquire digital capabilities they previously outsourced.
Inverter-driven variable-speed compressor technology is virtualizing the mechanical on-off cycling that defined twentieth-century refrigeration and air conditioning. Urban households in South Korea and Australia are specifying inverter-native platforms as baseline expectations, not premium upgrades. This compression of the technology adoption curve is virtualizing inventory stratification between tiered product lines.
Japan's METI Top Runner program continuously ratchets efficiency baselines without fixed-phase transitions, forcing manufacturers to maintain permanent redesign cycles rather than episodic compliance updates. The industrial consequence is elevated R&D staffing ratios and compressed product-generation intervals. Air conditioner and refrigerator categories bear the heaviest compliance burden, with manufacturers pre-positioning next-generation heat exchanger geometries two certification cycles ahead.
Appliance-as-a-service contracting is displacing outright purchase in Australian commercial foodservice and Indian institutional laundry verticals. Equipment financiers and facility management integrators are capturing the customer relationship that manufacturers historically owned through dealer networks. This shift concentrates procurement authority in Sydney, Melbourne, Mumbai, and Bangalore-based contract holders with multi-site portfolio scale.
Asia-Pacific Home Appliances Market Segmentation
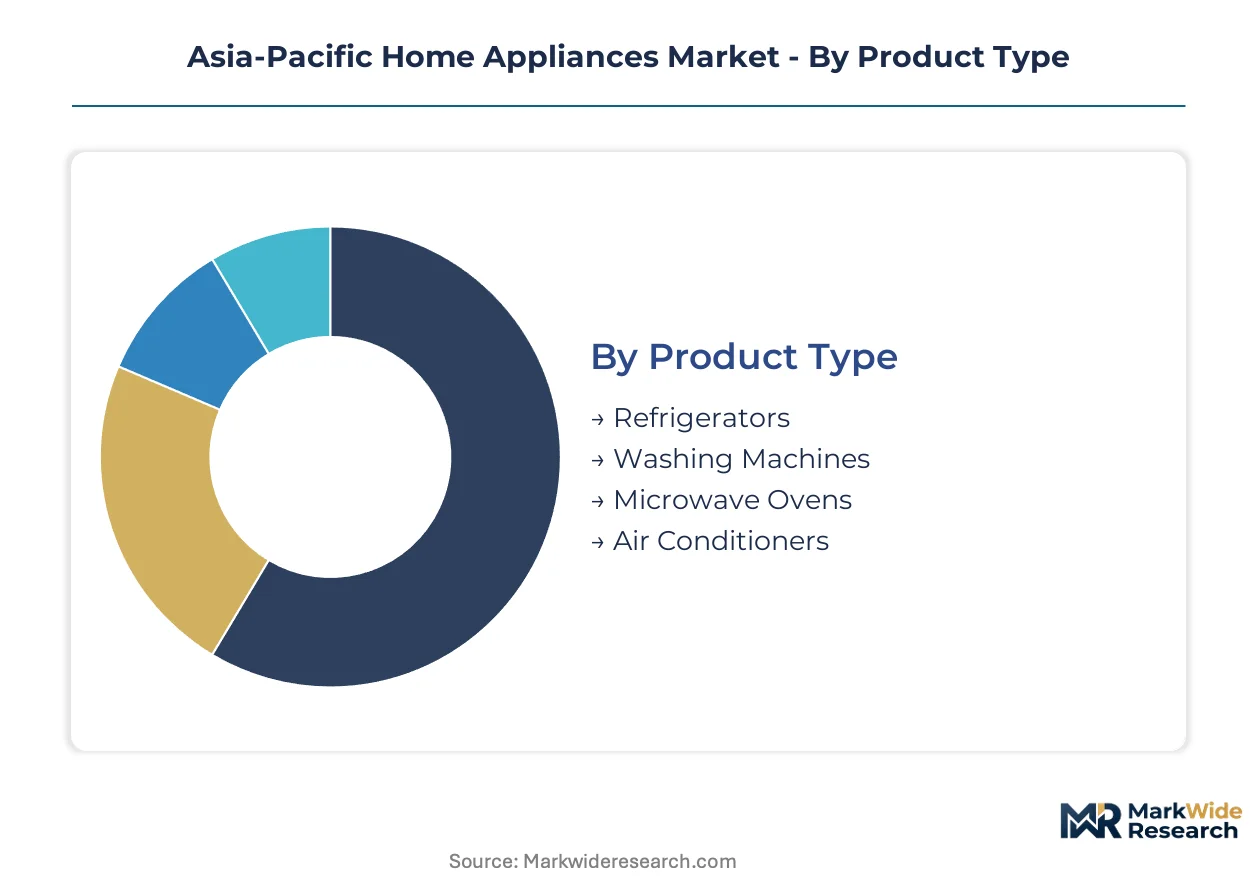
Segmentation in Asia-Pacific home appliances reveals how electrification programs, urban household formation, and regulatory pressure on energy efficiency reshape demand concentration across product categories and customer types. Understanding these divisions exposes where margin pools accumulate and where volume expansion accelerates.
Product Type:
Use cases span thermal management, textile processing, and food preparation with sharply diverging margin structures and replacement cycles.
- Refrigerators:Compressor-inverter architectures with variable-speed drives now dominate mid-tier and premium tiers. Maharashtra and Tamil Nadu state clusters drive replacement demand as BIS star-rating mandates tighten efficiency thresholds and reshape manufacturer compliance costs.
- Air Conditioners:Split-system and window units utilizing hydrofluorocarbon blends face refrigerant supply concentration risks from eastern China production clusters. Vietnam and Philippines penetration gaps create runway for mass-tier product introduction as electrification extends to non-electric households.
- Washing Machines:Drum-inverter technology is standard across mid-tier offerings. Mature replacement cycles concentrate in South Korea and Australia where premium positioning sustains margin.
- Microwave Ovens:Magnetron-based heating platforms serve compact urban kitchens. Southeast Asian metropolitan clusters generate concentrated demand as condominium stock expands.
Established volume favors refrigerators; emerging adoption favors air conditioners.
End User:
Customer archetypes range from individual households to portfolio-scale facility operators with procurement authority concentrated in contract-holding entities.
- Residential:Individual households purchasing through retail channels or online marketplaces. India's western and southern state clusters combine construction velocity with grid reliability improvements that support premium appliance uptake.
- Commercial:Foodservice and retail operators with equipment replacement cycles tied to lease renewals. Appliance-as-a-service contracting displaces outright purchase in Australian commercial foodservice verticals.
- Institutional:Educational and healthcare facilities with centralized procurement. Indian institutional laundry verticals increasingly specify service contracts over capital expenditure.
- Hospitality:Hotel and lodging chains with standardized room configurations. Procurement authority concentrates in Sydney, Melbourne, Mumbai, and Bangalore-based contract holders with multi-site portfolio scale.
Residential commands absolute volume; hospitality offers the steepest expansion trajectory for service-based revenue models.
Technology:
Control architectures differentiate across connectivity integration, motor drive efficiency, and refrigerant chemistry compliance.
- Smart Appliances:Hardware-software ecosystems with modular connectivity modules. Haier Smart Home leverages its U+ platform to anchor ecosystem control across white-goods categories.
- Energy-Efficient:Inverter-native platforms meeting Japan's METI Top Runner standards. Australia's E3 program labeling requirements create dual-certificate products commanding retail price premiums.
- Conventional:Electromechanical controls without connectivity integration. Entry-tier products face copper and rare-earth input volatility compressing already-thin margins.
- IoT-Enabled:Connectivity stacks integrated with real-time motor control algorithms. Shortage of embedded systems firmware talent delays development cycles.
Energy-efficient platforms dominate current certification cycles; smart appliances are gaining share fastest as connectivity module costs drop below conventional control parity.
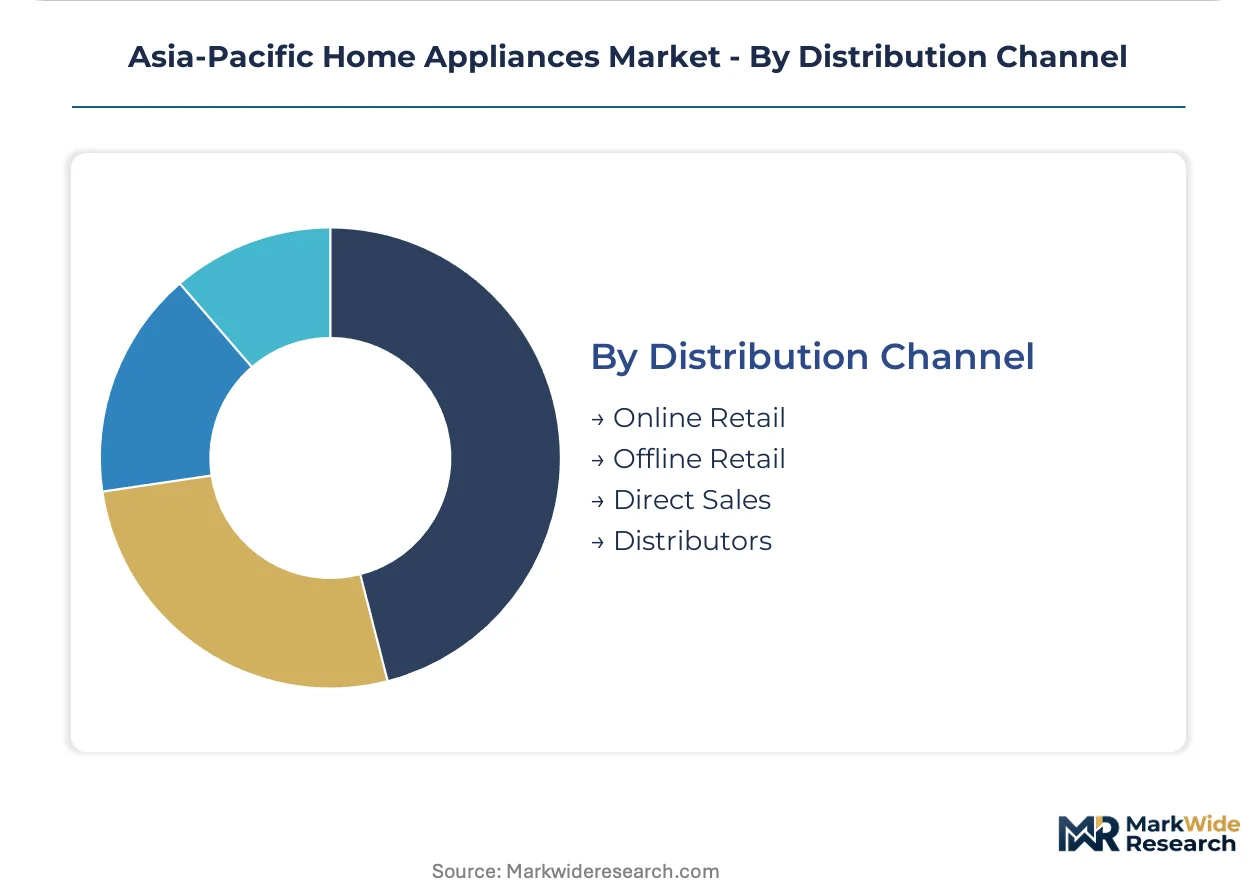
Distribution Channel:
Channel structure reflects inventory stratification between national retail chains, platform aggregators, and direct manufacturer relationships.
- Online Retail:Platform aggregators with logistics networks spanning tier-2 and tier-3 cities. Inventory decisions increasingly shaped by star-rating label visibility.
- Offline Retail:National chains and independent dealers with physical demonstration capacity. Australia's E3 program mandatory labeling directly shapes consumer purchase patterns and retailer inventory decisions.
- Direct Sales:Manufacturer-owned channels targeting premium segments. Samsung Electronics sustains premium positioning in South Korea through Bixby-integrated portfolios sold direct.
- Distributors:Regional wholesalers serving rural electrification conversion. India's Saubhagya scheme converts non-electric households into first-time appliance buyers through distributor networks.
Offline retail maintains margin capture; online retail is expanding most quickly in Indonesia and Vietnam metropolitan clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances across the Asia-Pacific home appliances sector tilt toward manufacturing surplus economies supplying deficit markets. China and South Korea run substantial appliance trade surpluses, while Australia, Vietnam, and the Philippines absorb inbound shipments to cover domestic production shortfalls.
China
Domestic demand for connected kitchen ecosystems and inverter-native cooling platforms sustains factory utilization across Guangdong and Jiangsu manufacturing belts. MIIT circular economy directives mandate refrigerant chemistry disclosure and recyclability labeling, accelerating closed-loop investments. The Yangtze River Delta and Pearl River Delta clusters concentrate compressor and motor production serving both captive brands and third-party OEM contracts.
India
Maharashtra, Gujarat, Karnataka, and Tamil Nadu state clusters combine residential construction velocity with grid reliability improvements that support premium appliance uptake. BIS energy-labeling mandates for cooling appliances are tightening efficiency thresholds faster than manufacturer cost curves can absorb, forcing wholesale redesigns of compressor architectures. Western and southern metropolitan corridors generate concentrated replacement demand as electrification programs convert non-electric households.
Japan
Kanto and Kansai metropolitan areas sustain replacement cycles for inverter-native platforms as baseline consumer expectations. METI Top Runner standards continuously ratchet appliance efficiency baselines without fixed-phase transitions, forcing manufacturers to maintain permanent redesign cycles. Tokyo-Osaka industrial corridors bear the heaviest compliance burden, with manufacturers pre-positioning next-generation heat exchanger geometries two certification cycles ahead.
South Korea
Seoul Capital Area and Busan-Ulsan clusters anchor domestic production of Bixby-integrated kitchen and laundry portfolios sustaining premium positioning. Urban households specify inverter-native platforms as baseline expectations, compressing the technology adoption curve. Samsung Electronics and LG Electronics leverage domestic manufacturing scale to supply regional export markets across Southeast Asia and Australia.
Australia
New South Wales and Victoria concentrate procurement authority for appliance-as-a-service contracting displacing outright purchase in commercial foodservice verticals. Equipment Energy Efficiency (E3) program mandatory labeling directly shapes consumer purchase patterns and retailer inventory decisions. Sydney and Melbourne-based contract holders with multi-site portfolio scale are capturing customer relationships that manufacturers historically owned through dealer networks.
Asia-Pacific Home Appliances Market Competitive Environment
On the supply side, the industry is consolidating around platform ecosystems that dissolve traditional hardware-software boundaries. Tiered competitive structures separate ecosystem architects from component-scale fabricators and regional assemblers. Three archetypes dominate: connectivity-platform owners, manufacturing-scale suppliers, and premium-brand positioners. Competitive moves concentrate on strategic partnerships for IoT interoperability and geographic expansion into underpenetrated Southeast Asian markets.
Among Korean-based electronics conglomerates, LG Electronics and Samsung Electronics exemplify the ecosystem-architect archetype through integrated smart-home platforms. Haier Smart Home occupies a position representing Chinese manufacturers leveraging domestic supply chain density for cost leadership. Midea Group anchors the manufacturing-scale tier, supplying compressor and motor components across white-goods categories. These three companies represent divergent strategic postures within a market fragmenting between premium connectivity and mass-tier efficiency.
| Leading Market Players |
|---|
| LG Electronics |
| Hisense Home Appliances |
| Haier Smart Home |
| BSH Hausgeräte |
| Whirlpool Corp. |
| Midea Group |
| Panasonic Corporation |
| Gree Electric Appliances |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Eastern China's hydrofluorocarbon refrigerant production clusters concentrate supply leverage for cooling-appliance manufacturers, translating upstream chemistry control into downstream margin capture across India's BIS-mandated efficiency tiers and Australia's E3-labeled retail channels.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels, with BIS star-rating certification and inverter-native compressor architectures driving price differentiation. Cost compression in entry-tier products is intensifying because copper and rare-earth permanent-magnet volatility squeezes already-thin margins. Residential households through distributor networks exhibit highest price sensitivity, while hospitality procurement clusters in Sydney and Mumbai demonstrate lowest sensitivity due to service-contract bundling.
Supply Chain Analysis
Copper cathode and rare-earth permanent-magnet feedstock draws from China, Indonesia, and Australia's mining operations, with compressor motor laminations and refrigerant chemistry resting on eastern China production concentration. Single-source vulnerability in hydrofluorocarbon blend supply creates structural risk for cooling-appliance manufacturers. Distribution runs through national retail chains and platform aggregators with tier-2 and tier-3 city logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific home appliances represent a high-growth disruption as inverter-native platforms and BIS efficiency mandates compress technology adoption curves and force permanent product redesign cycles.
For Market Incumbents: Insulate core margin pools by accelerating captive compressor manufacturing in Gujarat and Tamil Nadu state clusters to offset copper and rare-earth input volatility. Pre-position next-generation heat exchanger geometries two certification cycles ahead of Japan's METI Top Runner ratchets. Channel control through direct sales infrastructure sustains premium positioning against platform-aggregator disintermediation. For New Entrants and Emerging Players: Mid-market commercial foodservice in Vietnam and Philippines represents the most penetrable entry point, with air conditioner ownership gaps offering runway for mass-tier product introduction. Appliance-as-a-service contracting in Australian institutional laundry verticals enables customer relationship capture without dealer network investment. Partner with equipment financiers in Sydney and Melbourne to bypass traditional procurement authority structures. For Investors and Strategic Acquirers: Capital is best deployed toward connectivity-platform owners with embedded firmware capabilities and ecosystem control across white-goods categories. Long-term viability hinges on IoT interoperability standard consolidation eliminating redundant hardware module configurations. Monitor cross-border platform fragmentation resolution as inflection indicator for scalable hardware-software ecosystem returns.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Manufacturing | Gujarat and Tamil Nadu captive production mitigates copper and rare-earth price volatility exposure. |
| Smart Home Platform Integration | U+ and Bixby ecosystems anchor customer lock-in across refrigerator, air conditioner, and laundry categories. |
| Appliance-as-a-Service Contracting | Sydney and Melbourne facility managers capture multi-site procurement authority from manufacturer dealer networks. |
| Dual-Certificate Product Development | Combined Australia's E3 and India's BIS star-rating compliance commands retail price premiums in premium channels. |
| Geographic Expansion into Vietnam and Philippines | Air conditioner penetration gaps in electrifying households create volume runway for mass-tier inverter platforms. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted, including appliance manufacturer product managers, BIS certification engineers, retail category buyers, and hospitality procurement directors. Secondary validation drew from BIS star-rating registrations, Australia's E3 program labeling databases, MIIT circular economy disclosures, and METI Top Runner compliance filings. Bottom-up demand modeling and top-down manufacturing capacity assessment were triangulated to anchor volume estimates.
Calibration against historical efficiency-mandate adoption curves and electrification program conversion rates shaped projections across the analysis window. Segmentation dimensions included product type, end-user archetype, technology tier, and distribution channel, with inverter penetration rates and connectivity module cost curves as industry-specific inputs. CAGRs were derived from fitted adoption curves rather than linear extrapolation.
Practitioners should monitor refrigerant chemistry regulatory divergence and IoT interoperability standard consolidation for early signals of forecast revision. Cross-checking against customs trade data for compressor and motor component flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Latin America Laundry Appliances Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
United Kingdom Home Appliances Market
Home Appliances
Saudi Arabia Major Home Appliances Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
Russia Laundry Appliances Market
Home Appliances
US Household Appliances Market
Home Appliances
Europe Portable Washing Machine Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
China Major Home Appliances Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Smart Home Appliances Market
Home Appliances
France Household Appliances Market
Home Appliances
Europe Washing Machine Market