
 Hand-Held Mixer Market | 2026-2036
Hand-Held Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Hand-Held Mixer Market Insights
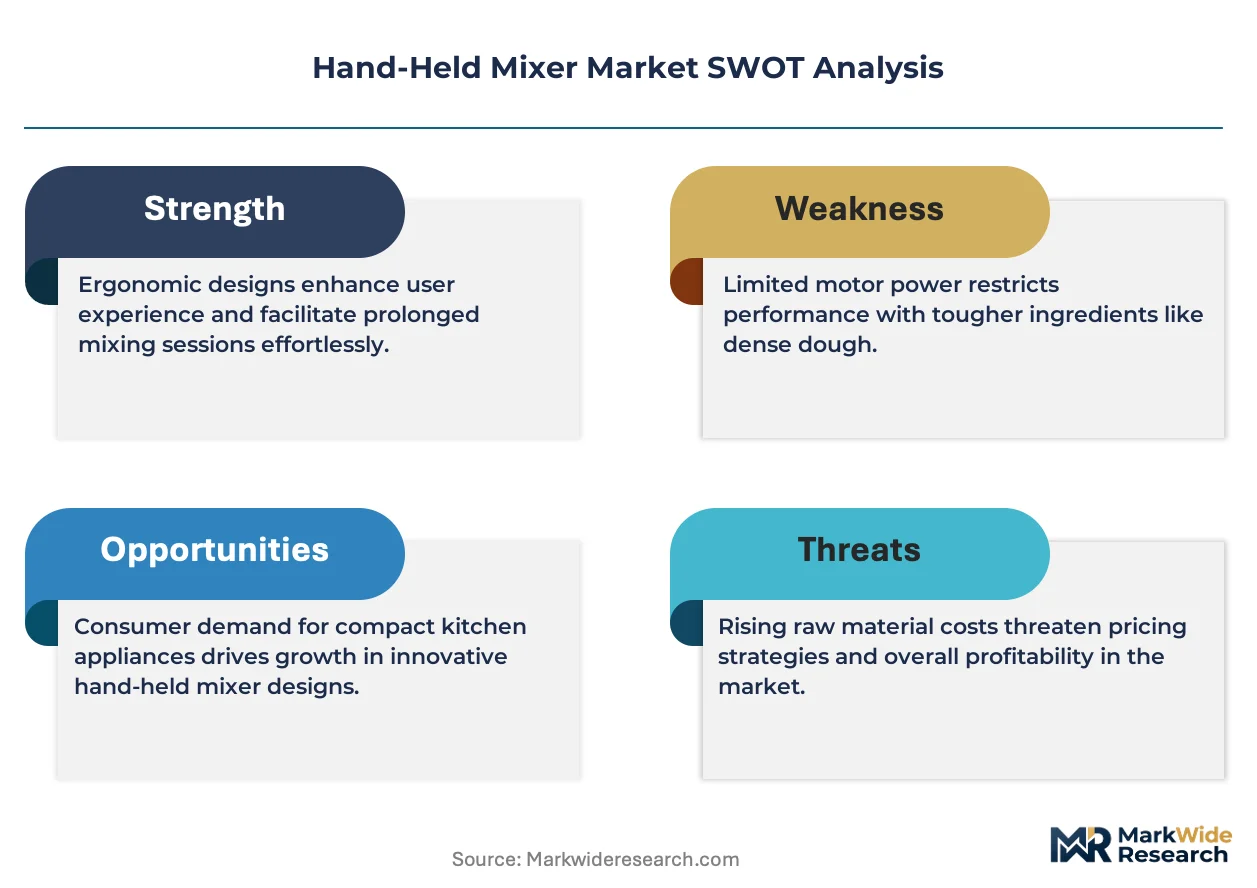
Chinese small-appliance manufacturing is restructuring as domestic producers upgrade from OEM assembly to branded export capacity. KitchenAid leverages vertical integration into die-cast metal housing production to sustain margin control across North American retail channels. Braun anchors European demand through engineering-intensive DC motor platforms that differentiate on torque consistency. Bosch competes with in-house power electronics expertise, extending its industrial motor heritage into consumer kitchen applications.
A hand-held mixer is a portable electric kitchen appliance comprising a motorized drive unit with detachable beaters or whisks, typically operating at 100W to 400W power ratings, designed to blend, whip, or aerate food ingredients in variable-viscosity preparations. The device serves commercial and residential users requiring controlled mechanical agitation without fixed-installation equipment. Hand mixer units occupy the highest volume tier among product types, though immersion blender configurations capture disproportionate margin pools in professional foodservice procurement. Restaurant and bakery end users concentrate demand in 300W to 400W power segments where sustained duty cycles and thermal durability determine replacement cycles and brand loyalty.
The US Consumer Product Safety Commission enforces electrical safety standards that shape corded-product architecture and insulation specifications for kitchen appliances sold through American retail channels. The EU F-Gas Regulation and REACH compliance frameworks constrain refrigerant-adjacent motor cooling technologies and material compositions in European-bound production. China's GB standards and SAMR certification requirements govern electromagnetic compatibility and energy efficiency labeling for domestic sales and export qualification. Stakeholders must monitor diverging efficiency mandates across these jurisdictions to determine where platform standardization yields scale economies versus where regional customization protects market access.
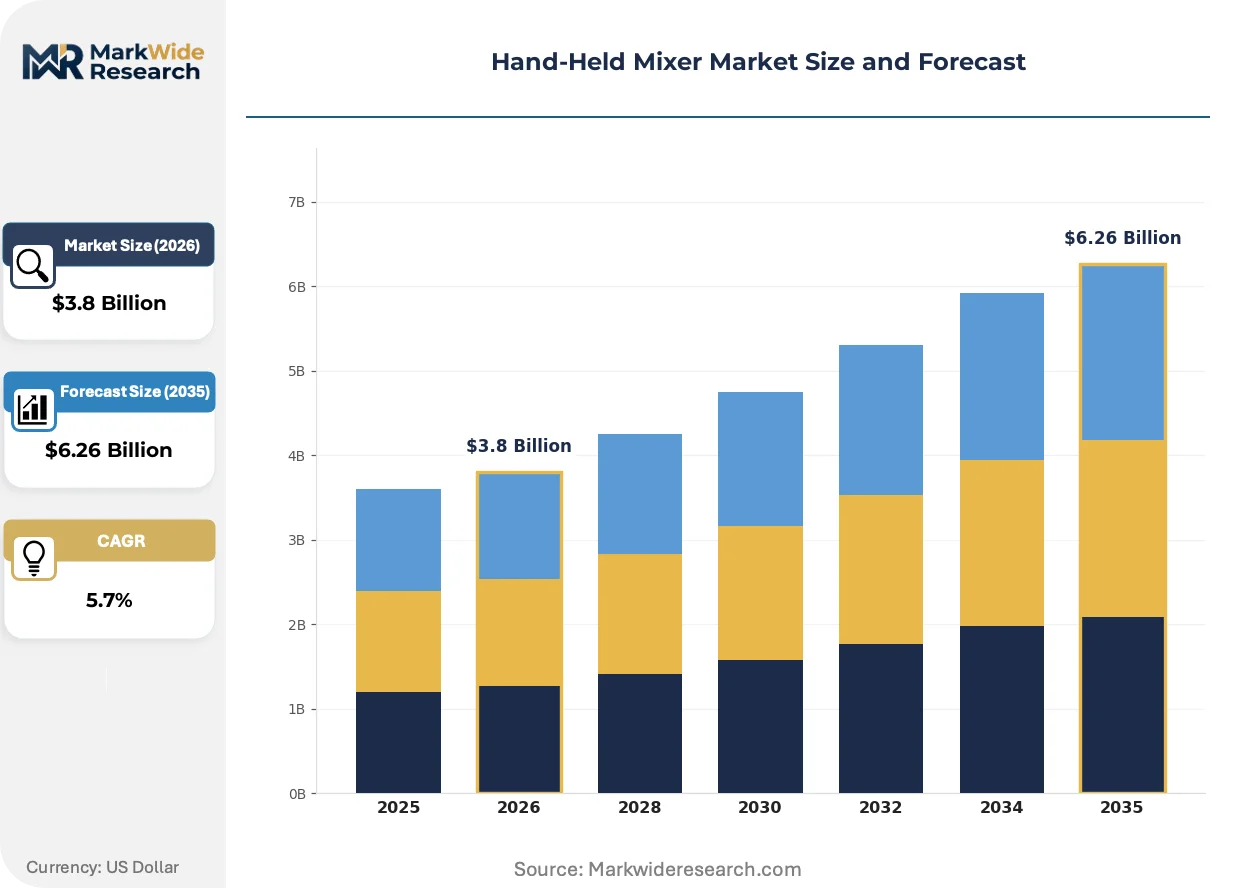
Market Dynamics
The EU Ecodesign Directive is compressing motor efficiency tolerances and forcing platform redesigns across European-bound production lines, while commercial bakeries scale artisan bread programs that demand sustained-duty hardware. This regulatory-demand tension is restructuring supplier R&D allocation and regional manufacturing footprints simultaneously.
Growth Catalysts
- Artisan Bakery Expansion:Commercial bakeries scaling sourdough and laminated dough production require 300W to 400W units with thermal durability, extending replacement cycles and locking in brand loyalty among professional users.
- REACH Compliance Architecture:The EU's material safety framework is accelerating substitution of legacy insulation compounds with bio-based thermoplastics, opening specification windows for engineered polymer suppliers.
- Precision Motor Control:DC brushless architectures with torque feedback circuits are penetrating mid-tier residential segments previously served by universal motors, enabling variable-speed precision for emulsion-sensitive preparations.
Market Restraints
- Copper and Rare Earth Volatility:Neodymium magnet costs and copper winding prices swing with energy transition demand, compressing margin stability for motor manufacturers without captive material hedging.
- Die-Cast Housing Concentration:Zamak alloy housing production clusters in Ningbo and Dongguan, creating single-source vulnerability for brands without backward integration into metal forming.
- Corded Product Substitution:Battery-powered immersion blenders with detachable whisk attachments are capturing countertop space in urban apartments with limited outlet access.
Strategic Opportunities
- India Appliance Electrification:Rural kitchen electrification programs and urban nuclear family formation are creating first-time appliance demand outside traditional wet-grinder preference zones.
- Smart Kitchen Integration:Bluetooth-enabled torque sensors paired with recipe apps are opening premium positioning for connected food preparation ecosystems in North American smart home installations.
- Repairability Mandates:The EU's right-to-repair framework for small appliances is incentivizing modular motor designs with standardized beater couplings and field-replaceable switch assemblies.
Industry Challenges
- Electromagnetic Compatibility Certification:Divergent GB standards for China, FCC Part 15 for the US, and CE EMC for Europe require parallel testing tracks that extend product launch timelines by 4-6 months.
- Thermal Management Expertise Gap:Sustained-duty commercial applications require polymer science and heat-sink engineering capabilities scarce among legacy residential appliance engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand-Held Mixer Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand Mixer, Hand Mixer, Immersion Blender, Mixer Grinder End User: Household, Restaurant, Bakery, Catering Service Power Rating: 100W, 200W, 300W, 400W Functionality: Mixing, Whipping, Kneading, Chopping |
| Companies Covered | KitchenAid, Braun, Cuisinart, Hamilton Beach, Breville, Bosch, Panasonic, BLACK+DECKER, Sunbeam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand-Held Mixer Market Trends and Innovations
Brushless DC motor architectures and integrated power electronics are redrawing competitive boundaries between industrial motor heritage and consumer appliance design. These shifts are compressing the performance gap between residential and commercial-grade equipment.
Sensorless field-oriented control is decentralizing speed regulation from mechanical governors to firmware algorithms. Commercial bakery procurement teams are specifying these platforms for dough consistency across multiple shifts. The technology is decentralizing maintenance schedules and reducing brush replacement downtime in high-utilization environments.
The EU F-Gas Regulation constrains refrigerant-adjacent cooling technologies in motor thermal management systems. Manufacturers are pivoting toward passive heat-sink designs and thermally conductive polymer housings. European-bound production lines are most affected, with German and Italian engineering teams accelerating solid-state thermal interface material qualification.
Foodservice procurement teams are consolidating vendor relationships around equipment suites rather than single-category purchases. Distributor account managers are bundling mixers with immersion blenders and food processors under multi-year service contracts. This pattern is most visible in US regional restaurant chains standardizing back-of-house equipment across 50-plus unit footprints.
Hand-Held Mixer Market Segmentation
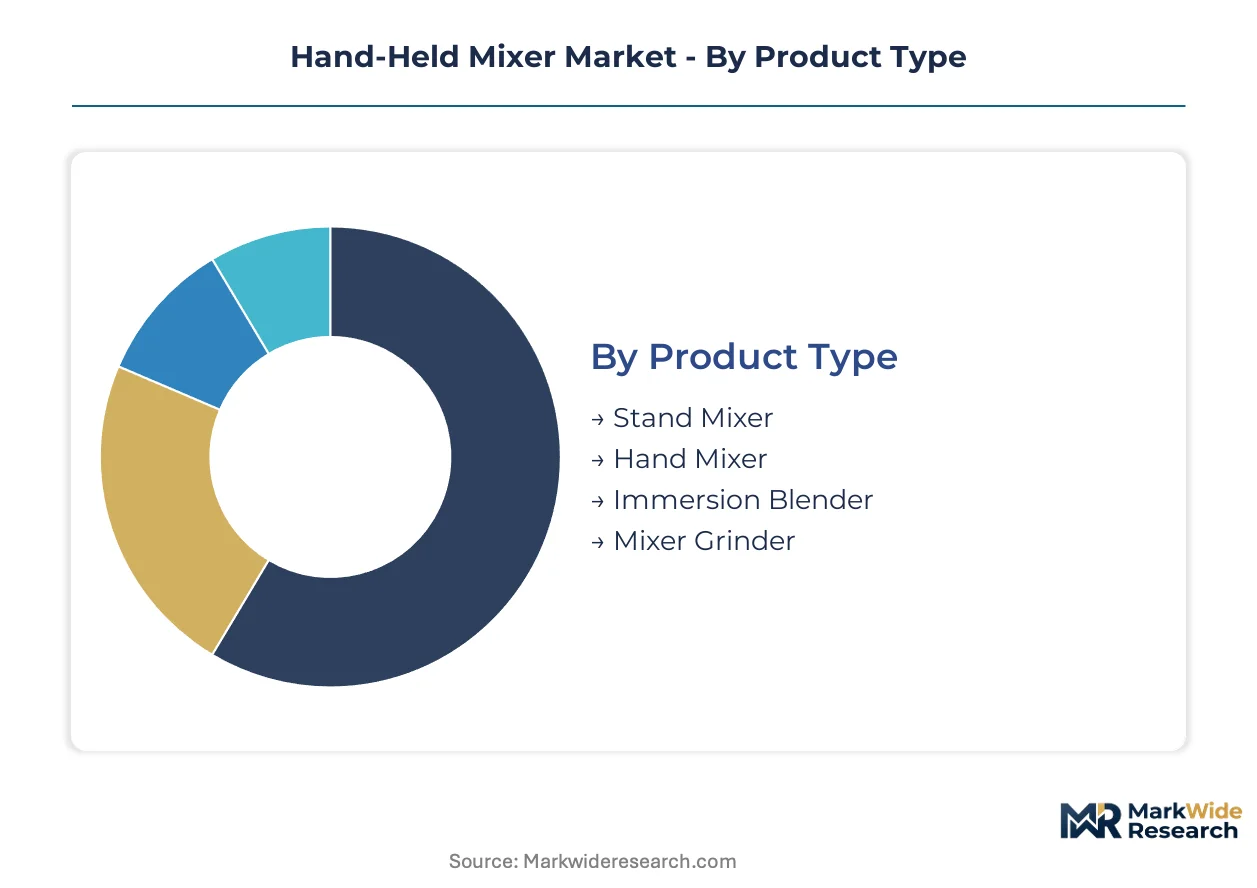
Hand-held mixer segmentation reveals divergent engineering requirements across power classes and duty cycles. Product architecture, thermal management, and motor control specifications vary sharply between intermittent residential use and sustained commercial operation.
Product Type:
Standardization dominates entry-level segments while premium tiers demand bespoke motor platforms and die-cast housing geometries.
- Stand Mixer:Stationary base units with planetary mixing action and bowl-lift mechanisms occupy the highest price tier. Demand concentrates in US suburban households with dedicated kitchen islands and German baking enthusiasts prioritizing dough consistency for artisan bread programs.
- Hand Mixer:Portable motorized drive units with detachable beaters represent the volume anchor across all geographies. Restaurant procurement teams in France and Italy specify 300W to 400W variants with thermal cutout protection for extended whipping operations.
- Immersion Blender:Shaft-style designs with whisk attachments capture professional foodservice margin pools. Catering operations in Spain and commercial kitchens across Japan favor cordless lithium-ion configurations for station flexibility.
- Mixer Grinder:Multi-function units with wet and dry grinding jars dominate Indian household electrification programs. BIS certification requirements and wet-grinder substitution patterns shape regional specification windows.
Most installed capacity flows through Hand Mixer. Expansion is steepest in Immersion Blender.
End User:
Customer archetypes span price-agnostic procurement teams to first-time appliance buyers with divergent replacement cycle expectations.
- Household:Residential users prioritize compact storage footprints and dishwasher-safe attachments over sustained-duty ratings. Urban apartments in South Korea and compact kitchens across the Netherlands drive demand for collapsible-beater designs and retractable cord systems.
- Restaurant:Back-of-house operations require NSF-certified housings and sealed switch assemblies for sanitation compliance. US regional chains and independent bistros in Belgium specify torque feedback circuits for emulsion consistency across shift changes.
- Bakery:Artisan producers scaling sourdough and laminated dough programs demand brushless DC platforms with passive thermal management. German craft bakeries and French boulangerie chains anchor premium positioning for 400W sustained-duty units.
- Catering Service:Mobile foodservice operators prioritize battery-powered portability and rapid-swap battery systems. Event catering hubs in the UK and outdoor hospitality vendors across Australia specify IP-rated enclosures for field durability.
Household segment carries the largest unit base. Bakery applications are climbing the fastest.
Power Rating:
Motor winding specifications and magnet architectures stratify across thermal load tolerances and duty cycle ratings.
- 100W:Universal motor platforms with stamped steel housings serve occasional mixing tasks. Entry-level residential demand in Brazil and Southeast Asian markets concentrates here, with SAMR and INMETRO efficiency labels shaping import qualification.
- 200W:Mid-tier residential segment with improved torque curves for cake batters and whipped creams. Japanese METI energy labeling and Korean KC certification requirements drive platform standardization across East Asian exports.
- 300W:Commercial crossover tier with enhanced heat-sink integration and polymer thermal interfaces. Italian and Spanish restaurant procurement teams specify this threshold as minimum viable for professional kitchen operations.
- 400W:Sustained-duty architectures with sensorless field-oriented control and die-cast Zamak housings. German commercial bakeries and US artisan bread programs lock in brand loyalty through thermal durability specifications and multi-shift reliability.
200W and 300W segments absorb the majority of current production. 400W tier is gaining share fastest among professional end users.
Functionality:
Attachment interchangeability and speed control precision determine specification matching across viscosity ranges and ingredient types.
- Mixing:Standard beater geometry for batters, doughs, and compound ingredients. Residential demand in Canada and Mexico prioritizes splash-guard designs and bowl-scraping attachments for countertop cleanliness.
- Whipping:Wire whisk configurations for aeration and foam stability. French pastry kitchens and Japanese confectionery operations specify planetary motion patterns and variable-speed ramps for meringue consistency.
- Kneading:Dough hook attachments with high-torque low-speed operation. Artisan bread movements across Poland, Austria, and the US Pacific Northwest drive specification for gluten development and fermentation timing.
- Chopping:Mini-processor bowls and blade attachments extending utility into vegetable prep. UK meal-kit subscribers and Australian home cooks favor multi-function platforms that consolidate countertop appliance counts.
Mixing functionality commands the broadest installed base. Kneading specifications are expanding most quickly with artisan bakery scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are migrating assembly capacity toward jurisdictions with narrower efficiency compliance windows, exploiting gaps between EU Ecodesign Directive stringency and emerging market certification timelines to preserve margin on legacy motor platforms.
Germany
Precision-engineered kitchen equipment commands sustained premium positioning among artisan baking enthusiasts and commercial craft producers. The EU Ecodesign Directive pressures domestic manufacturers toward higher-efficiency motor architectures with passive thermal management. Engineering clusters in Stuttgart and Nuremberg accelerate solid-state thermal interface material qualification for 400W sustained-duty units.
United States
Regional restaurant chains standardizing back-of-house equipment across 50-plus unit footprints drive consolidated vendor relationships. The US Consumer Product Safety Commission enforces electrical safety standards shaping corded-product architecture and insulation specifications. Die-cast metal housing production concentrates in Ohio and Pennsylvania manufacturing corridors serving North American retail channels.
China
Domestic producers upgrade from OEM assembly to branded export capacity as rural kitchen electrification programs expand appliance penetration. GB standards and SAMR certification requirements govern electromagnetic compatibility and energy efficiency labeling for domestic sales and export qualification. Ningbo and Dongguan clusters dominate Zamak alloy housing fabrication for global brand supply chains.
India
Urban nuclear family formation and rural electrification programs create first-time appliance demand outside traditional wet-grinder preference zones. BIS certification requirements and wet-grinder substitution patterns shape regional specification windows for multi-function units. Maharashtra and Gujarat manufacturing hubs scale mixer grinder production for domestic distribution and South Asian export markets.
Japan
Confectionery operations and compact kitchen footprints in metropolitan apartments drive demand for collapsible-beater designs and variable-speed precision. METI energy labeling requirements drive platform standardization across East Asian export configurations. Osaka-based engineering teams specialize in torque feedback circuits for emulsion-sensitive preparations in professional pastry kitchens.
Hand-Held Mixer Market Competitive Landscape
German producers anchor the premium engineering tier; Chinese fabricators hold scale-driven supply positions. The vendor base stratifies across three tiers: heritage brands with industrial motor heritage, consumer appliance specialists with retail channel dominance, and emerging Asian manufacturers with captive metal forming capacity. Consolidation pressures favor M&A activity among mid-tier residential specialists and strategic partnerships bundling mixers with broader foodservice equipment suites.
Within the heritage engineering tier, KitchenAid and Braun exemplify divergent approaches to margin preservation. KitchenAid represents North American vertical integration into die-cast housing production, while Braun anchors European demand through engineering-intensive DC motor platforms. Bosch occupies a position bridging industrial motor expertise and consumer kitchen applications, extending power electronics capabilities into residential segments.
| Leading Market Players |
|---|
| KitchenAid |
| Braun |
| Cuisinart |
| Hamilton Beach |
| Breville |
| Bosch |
| Panasonic |
| BLACK+DECKER |
| Sunbeam |
| Others |
Pricing and Supply Chain Analysis
Restaurant procurement teams consolidating back-of-house equipment across multi-unit footprints negotiate volume-based contract structures that compress distributor margins while rewarding direct-OEM relationships. This buyer concentration shifts pricing power toward manufacturers with captive die-cast housing production and certified thermal durability specifications.
Pricing Analysis
Distributor markups on 300W to 400W commercial units run 18-25 points above residential tiers, reflecting NSF certification costs and sealed-switch engineering. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered brushless DC platforms from stamped-steel universal motor imports. Cost compression in entry-level residential tiers is intensifying because Chinese OEMs upgrade to branded export capacity. Price sensitivity peaks among first-time appliance buyers in Indian urban nuclear families, while German artisan bakeries prioritize thermal durability over unit cost.
Supply Chain Analysis
Refurbishment flows for commercial-grade units with failed thermal cutouts concentrate in Ohio and Pennsylvania service depots serving North American restaurant chains. Zamak alloy housing fabrication draws from Ningbo and Dongguan clusters, with copper winding supply anchored in Chinese smelter networks. Single-source vulnerability in die-cast metal forming creates exposure to energy-transition demand swings for copper and neodymium. Distribution runs through foodservice equipment distributors bundling mixers under multi-year service contracts with regional restaurant chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hand-held mixer market compounds steadily as artisan bread production scales across foodservice, creating durable replacement-cycle demand for sustained-duty hardware.
For Market Incumbents: Extend thermal management capabilities into sensorless field-oriented control platforms to defend against brushless DC entrants from industrial motor heritage. Captive die-cast housing production in Ohio and Pennsylvania manufacturing corridors protects margin control as Chinese OEMs upgrade to branded export capacity. Prioritize EU Ecodesign Directive compliance architecture to preempt regulatory displacement in European-bound production lines. For New Entrants and Emerging Players: Rural Indian households outside traditional wet-grinder preference zones present first-time appliance demand with limited incumbent loyalty. Battery-powered immersion blender configurations for UK event catering hubs and Australian outdoor hospitality vendors offer white-space penetration with IP-rated enclosure differentiation. Target foodservice procurement teams through distributor bundling relationships rather than direct retail channel buildout. For Investors and Strategic Acquirers: Foodservice equipment suites consolidating vendor relationships around multi-category back-of-house standardization are the most active acquirer in this space. Mid-tier residential specialists with regional retail channel dominance but lacking thermal management expertise present consolidation targets. Monitor EU right-to-repair mandate implementation timelines as inflection indicator for modular motor design valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Die-Cast Housing | KitchenAid's Ohio manufacturing corridor secures margin control against Ningbo supply volatility. |
| Brushless DC Platform Migration | Braun's Stuttgart engineering cluster differentiates torque consistency for German artisan bakeries. |
| Battery-Powered Configuration Launch | Cordless lithium-ion variants capture UK catering hub demand for station flexibility. |
| EU Repairability Compliance Redesign | Modular motor architectures with standardized couplings align with right-to-repair frameworks. |
| Foodservice Distributor Partnership | Multi-year service contracts with US regional chains lock in replacement cycle visibility. |
Research Methodology
Direct dialogue with foodservice procurement managers, commercial bakery operations directors, appliance brand product planners, and thermal engineering specialists grounded qualitative findings. Secondary validation drew from US Consumer Product Safety Commission enforcement records, EU Ecodesign Directive implementation guidance, SAMR certification databases, and customs trade flows for Zamak alloy and copper winding inputs. Bottom-up unit economics triangulated against top-down category spending estimates.
Top-down macroeconomic anchoring combined with bottom-up segment sizing across power rating tiers, end-user verticals, and functionality attachments. Segmentation dimensions modeled include product architecture, duty cycle classification, regional regulatory cluster, and thermal management technology tier. CAGRs were derived from installed base turnover rates and replacement cycle compression in commercial applications. Forecast inputs incorporated copper and rare earth price volatility bands alongside EU efficiency mandate compliance timelines.
Inputs from regulatory filing databases and foodservice equipment distributor contract disclosures were available through the study window; gaps in real-time commercial bakery capital expenditure tracking introduce uncertainty bands around professional segment penetration assumptions. Practitioners should monitor EU F-Gas Regulation thermal management constraints and artisan bakery scaling announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Cookware Accessories Market
Kitchen Appliances
Japan Kitchen Appliances Market
Kitchen Appliances
Toast Maker Market
Kitchen Appliances
Heavy Duty Mixer Grinder Market
Kitchen Appliances
US Cookware Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Small Kitchen Appliances Market
Kitchen Appliances
US Household Coffee Machine Market
Kitchen Appliances
North America Electric Kettle Market
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Smart Kitchen System Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
France Kitchen Appliances Market
Kitchen Appliances
United States Large Kitchen Appliances Market
Kitchen Appliances
Smart Cooktop Market