
 Mexico Home Appliances Market | 2026-2036
Mexico Home Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Home Appliances Market Foresight
The Mexico home appliances category is restructuring around a widening gap between inverter-driven premium units and basic commodity models without smart connectivity or energy certification. Whirlpool Corporation anchors production scale through its longstanding manufacturing presence in the country. Samsung Electronics differentiates through connected kitchen ecosystems and inverter compressor technology. Mabe sustains dominant share in the domestic refrigerator segment through deep distribution into provincial retail networks.
Home appliances encompass electrically powered machines for domestic tasks, typically operating at 127V/60Hz in Mexico with energy consumption ratings measured under NOM-011-ENER standards for refrigeration equipment and NOM-005-ENER for clothes washers. Refrigerators command the largest product type position due to universal household necessity and replacement cycles driven by energy-efficiency upgrades. The residential end user segment leads volume absorption, while commercial buyers in hospitality and food service generate disproportionate margin contribution through mid-range and premium tiers. Offline retail retains channel dominance in smaller municipalities, though online retail accelerates fastest in metropolitan zones where delivery infrastructure and financing options have matured.
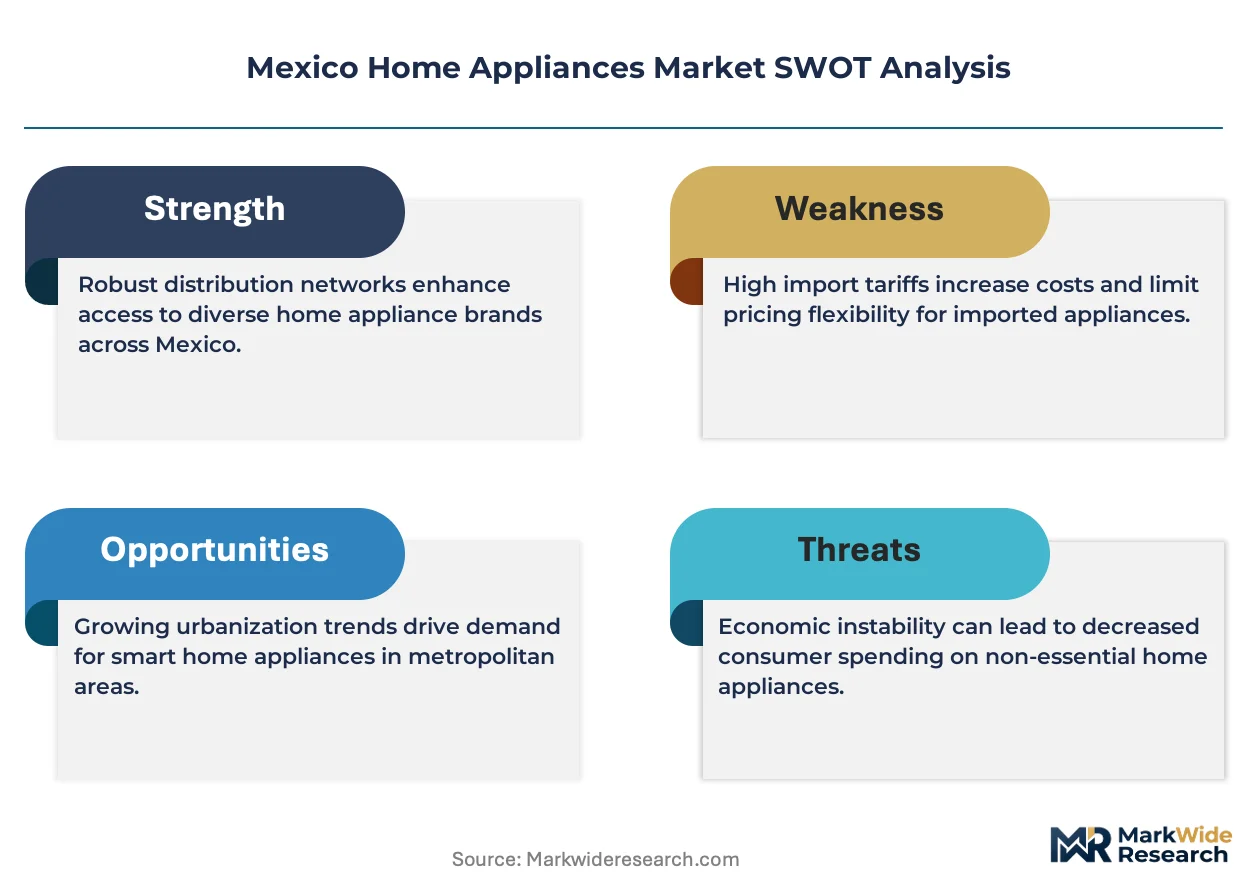
PROFECO consumer protection standards and NOM energy-efficiency mandates from Mexico's national standards body jointly determine product eligibility for domestic sale, with non-compliant imports facing market access barriers. The Secretariat of Economy enforces labeling requirements that shape manufacturer R&D priorities toward inverter motors and low-GWP refrigerants. Stakeholders must monitor how upcoming NOM revisions on standby power and refrigerant transitions will reshape cost structures and competitive positioning in the mid-range tier.
Market Dynamics
NOM energy-efficiency revisions are forcing a bifurcation between certified inverter models and non-compliant inventory across Mexican distribution channels. This regulatory compression is accelerating replacement cycles in urban centers while stranding older stock in peripheral municipalities.
Growth Catalysts
- NOM-011-ENER Refrigeration Standards:Mandatory efficiency labeling drives consumer preference toward inverter compressor refrigerators. Retailers report faster inventory turns for A-rated units versus legacy models.
- Metropolitan Electrification Upgrades:Grid stability improvements in Mexico City and Guadalajara enable higher-wattage appliance adoption without voltage regulator purchases. Residential buyers upgrade to larger-capacity units.
- Embedded Finance Penetration:Point-of-sale credit instruments through OXXO and Elektra networks reduce upfront payment barriers. Provincial consumers access premium tier products previously restricted to cash buyers.
Market Restraints
- Copper and Steel Input Volatility:Compressor manufacturing depends on copper winding and cold-rolled steel pricing indexed to international commodity exchanges. Margin compression hits mid-range tier producers hardest.
- Monterrey Industrial Cluster Concentration:Component stamping and motor assembly concentrate in Nuevo León facilities. Disruption to this corridor propagates nationwide production delays.
- Refrigerant Transition Friction:NOM mandates on low-GWP refrigerants require retooling of compressor sealing technologies. Technical adaptation lags create certification bottlenecks for new product introductions.
Strategic Opportunities
- Querétaro and Bajío Corridor Expansion:Automotive worker settlements generate first-time homebuyer demand. Appliance penetration rates trail Mexico City by substantial margins.
- Smart Grid Convergence:Integration of inverter appliances with time-of-use electricity tariffs creates demand-response revenue streams. Utilities pilot programs in Jalisco validate technical feasibility.
- PROFECO Extended Warranty Mandates:Mandatory defect liability periods shift service revenue from third-party repair shops to manufacturer-captive networks. OEMs capture aftermarket value previously lost to informal technicians.
Industry Challenges
- Inverter Motor Technician Scarcity:Provincial repair networks lack training on variable-frequency drive diagnostics. Service quality gaps damage brand reputation in secondary cities.
- Dual Certification Timeline Compression:Simultaneous NOM energy and PROFECO safety approvals require sequential laboratory testing. Product launch windows compress against seasonal demand peaks.
- Legacy 127V Infrastructure Compatibility:Voltage fluctuation tolerance in rural grids forces engineering compromises on premium feature sets. Urban-optimized designs underperform in target expansion markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Home Appliances Market |
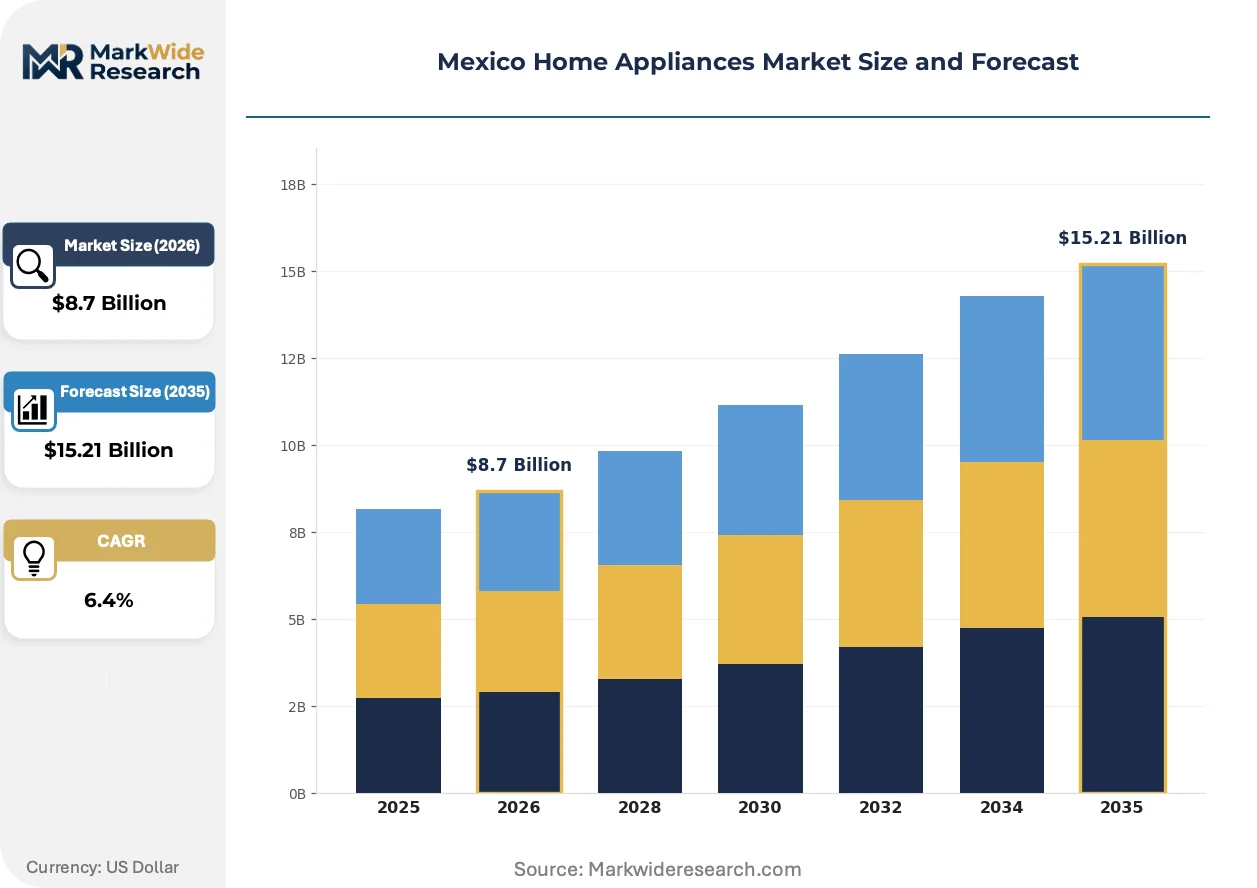
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Ovens, Microwaves End User: Residential, Commercial, Industrial, Institutions Distribution Channel: Online Retail, Offline Retail, Wholesale, Direct Sales Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Samsung Electronics, BSH Hausgeräte, Whirlpool Corporation, Panasonic Corporation, Haier Group, Mabe, Electrolux, Hisense, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Home Appliances Market Shifts & Advancements
Inverter compressor architecture is modularizing product development cycles, enabling rapid tier differentiation without complete platform redesigns. This technical flexibility intersects with regulatory pressure and channel evolution to reshape competitive economics.
Variable-speed compressor technology replaces fixed-speed piston designs across refrigerator and air conditioner categories. Manufacturers deploy modular inverter platforms across three efficiency tiers using identical motor cores with differentiated control algorithms. This architecture is modularizing cost structures, allowing premium feature penetration into mid-range price bands without full supply chain duplication.
NOM standby power regulations under Secretariat of Economy review will mandate sub-1W idle consumption for all new appliance registrations. Manufacturers pre-position zero-standby relay circuits and capacitor-backed memory systems to avoid compliance-driven redesign cycles. The clothes washer segment faces the steepest engineering adaptation due to electronic control panel prevalence.
Buyers in Mexico City and Guadalajara increasingly research NOM efficiency ratings through PROFECO's mobile application before store visits. Offline retailers respond by displaying QR-linked certification databases alongside physical units. This verification behavior concentrates in metropolitan zones where electricity tariffs structure total cost-of-ownership calculations.
Mexico Home Appliances Market Segmentation
Segmentation reveals how NOM efficiency mandates and replacement cycles concentrate demand across distinct buyer profiles and channel configurations. Understanding these divisions exposes where inverter technology penetration runs deepest and where provincial expansion opportunities remain underdeveloped.
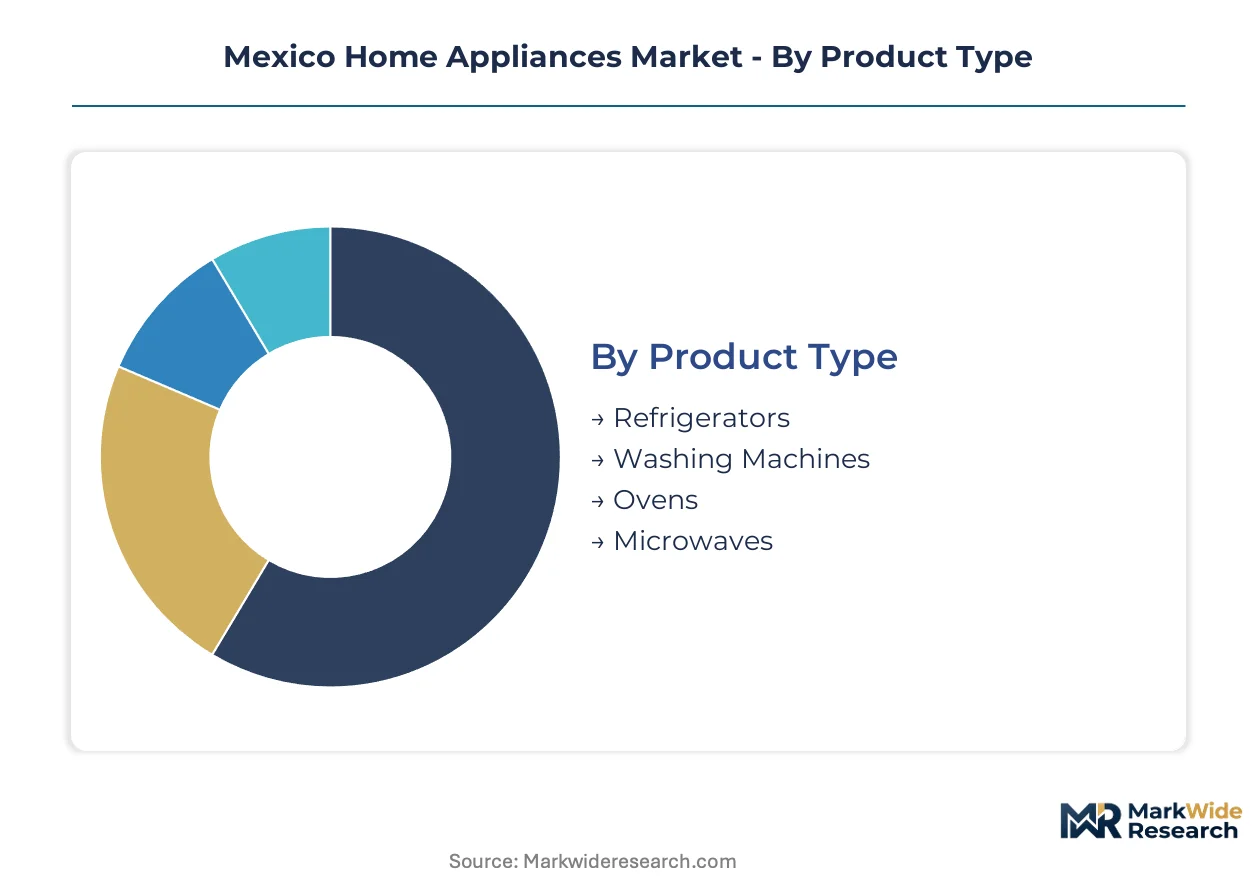
Product Type:
Upgrade trajectories vary sharply by appliance category, with energy-efficiency payback periods and replacement urgency driving divergent purchasing behaviors across Mexican households.
- Refrigerators:Compressor-driven cooling systems operating at 127V/60Hz with NOM-011-ENER efficiency ratings displayed on PROFECO-mandated labels. Demand concentrates in Mexico City and Guadalajara residential corridors where electricity tariff structures make inverter compressor payback periods calculable for middle-income buyers.
- Washing Machines:Horizontal and vertical drum configurations with NOM-005-ENER water and energy consumption standards. Penetration accelerates fastest in Jalisco and Nuevo León first-time homebuyer segments previously dependent on manual laundry or shared facilities.
- Ovens:Built-in and freestanding gas or electric cooking appliances with varying capacity ratings. Commercial hospitality buyers in Monterrey and Puebla drive specification requirements for convection and steam-assisted models.
- Microwaves:Countertop and over-range configurations with inverter power delivery options. Replacement demand dominates in mature urban markets where units approach end-of-design-life.
Refrigerators sit at the top of the volume ranking, with washing machines climbing the fastest.
End User:
Margin structures diverge substantially across buyer categories, with commercial procurement specifications enabling premium tier attachment rates unavailable in residential mass markets.
- Residential:Individual household purchasers operating within cash or embedded-finance constraints. Volume concentrates in central Mexico's urban corridor spanning State of Mexico, Jalisco, and Nuevo León metropolitan zones.
- Commercial:Hospitality and food service operators with equipment reliability requirements and maintenance contract preferences. This segment generates disproportionate margin contribution through mid-range and premium tier absorption.
- Industrial:Large-scale food processing and institutional kitchen facilities with custom equipment specifications. Procurement runs through specialized distributors with project engineering capabilities.
- Institutions:Educational, healthcare, and government facilities with public tender processes and extended warranty requirements. PROFECO defect liability mandates reshape vendor selection criteria.
Residential buyers absorb the highest unit volumes, while commercial procurement delivers the steepest margin expansion trajectory.
Distribution Channel:
Channel selection determines financing availability, installation service quality, and NOM certification verification access for Mexican appliance buyers.
- Online Retail:E-commerce platforms with delivery infrastructure and point-of-sale credit integration. Acceleration concentrates in Mexico City and Guadalajara where logistics networks and digital payment maturity enable remote purchasing.
- Offline Retail:Physical storefronts including national chains and independent provincial dealers. Retains dominance in smaller municipalities where tactile inspection and immediate delivery remain purchase determinants.
- Wholesale:Bulk procurement channels serving property developers and institutional buyers. Volume flows concentrate through Monterrey industrial corridor distributors with project financing relationships.
- Direct Sales:Manufacturer-captive channels for premium and built-in appliance categories. Service integration and extended warranty offerings differentiate this route.
Offline retail maintains volume leadership, with online channels expanding most quickly in metropolitan zones.
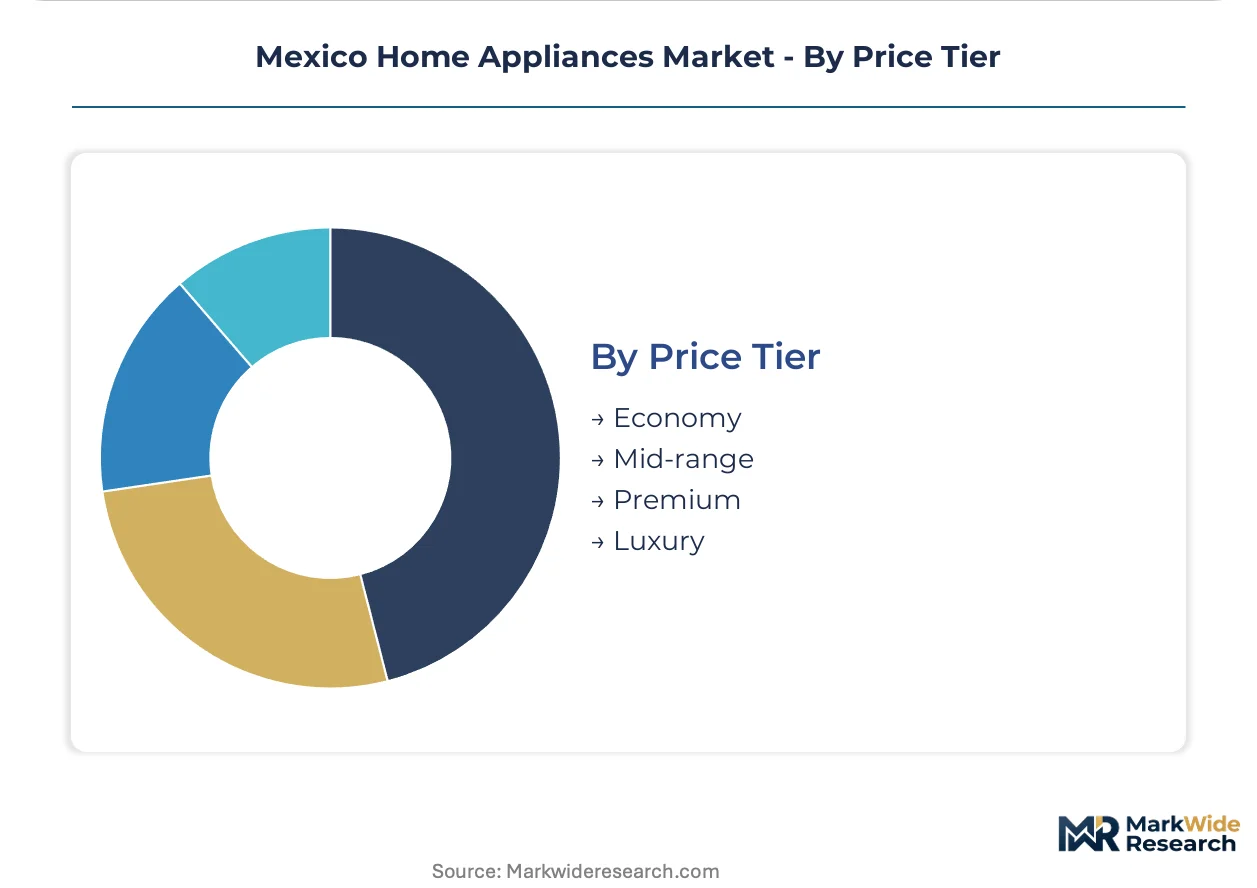
Price Tier:
Price tier selection correlates with NOM certification grade, inverter technology inclusion, and smart connectivity features across Mexican distribution networks.
- Economy:Basic specification models without inverter compressors or energy efficiency certification. Inventory concentrates in peripheral municipalities with price-sensitive demand and limited electricity tariff exposure.
- Mid-range:NOM-certified units with inverter motor technology and standard warranty terms. This tier captures replacement cycle volume in urban centers where efficiency payback calculations influence purchase decisions.
- Premium:Connected appliance ecosystems with variable-speed compressors and extended manufacturer service networks. Demand concentrates in Mexico City and Guadalajara upper-middle-income segments.
- Luxury:Built-in configurations with custom panel integration and concierge service arrangements. Limited distribution through specialized kitchen design studios.
Mid-range products command the highest unit volumes, with premium tier offerings gaining share fastest in connected metropolitan markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing talent pools in Nuevo León and Jalisco anchor Mexico's appliance production capacity, while metropolitan consumer concentrations in Mexico City and Guadalajara drive specification requirements for energy-efficient models.
Mexico City Metro
Upper-middle-income households in Coyoacán and Polanco districts prioritize NOM-011-ENER certified inverter refrigerators with calculable electricity payback periods. PROFECO's mobile verification application shapes pre-purchase research behavior. The Toluca industrial corridor supplies stamped metal components to assembly plants in the State of Mexico.
Nuevo León
First-time homebuyers in Monterrey's suburban expansion zones generate washing machine penetration growth previously constrained by manual laundry practices. The state's grid stability improvements enable higher-wattage appliance adoption without voltage protection purchases. Apodaca and Santa Catarina host compressor motor winding and cold-rolled steel stamping facilities.
Jalisco
Guadalajara's metropolitan zone accelerates online retail channel development through mature delivery infrastructure and point-of-sale credit integration. Residential buyers in Zapopan and Tlajomulco upgrade kitchens with connected appliance ecosystems. The Jalisco Energy Agency pilots time-of-use tariff programs that validate smart grid convergence with inverter appliances.
Bajío Region
Automotive worker settlements in Querétaro and León generate first-time homebuyer demand with appliance penetration rates trailing Mexico City by substantial margins. Embedded finance instruments through provincial retail networks reduce upfront payment barriers for mid-range tier products. The region's electricity tariff exposure remains lower than metropolitan benchmarks.
Northern Border States
Cross-border purchasing patterns in Tijuana and Ciudad Juárez expose consumers to US product specifications and financing models. Voltage compatibility requirements differ from central Mexico's 127V/60Hz standard. Chihuahua's manufacturing maquiladoras concentrate on component subassembly for re-export rather than domestic market supply.
Mexico Home Appliances Market Competitive Landscape
Top-tier vendors anchor the premium connected-appliance tier, while regional specialists and economy-tier assemblers occupy price-sensitive distribution channels. Market structure bifurcates between multinational OEMs with captive manufacturing and domestic distributors sourcing generic platforms. Three archetypes dominate: inverter technology leaders, provincial network deepeners, and modular platform assemblers. Competitive moves concentrate on distribution exclusivity agreements and service network captivity.
Among Korea-based electronics conglomerates, Samsung Electronics and LG Electronics exemplify the connected-ecosystem archetype with inverter compressor integration. Whirlpool Corporation represents the scale-anchored multinational with longstanding manufacturing presence. Mabe occupies a position as the domestic network deepener with provincial retail penetration. These three players illustrate how geographic origin and organizational structure map to distinct competitive vectors in Mexico's regulatory-compressed market.
| Leading Market Players |
|---|
| Samsung Electronics |
| BSH Hausgeräte |
| Whirlpool Corporation |
| Panasonic Corporation |
| Haier Group |
| Mabe |
| Electrolux |
| Hisense |
| LG Electronics |
| Others |
Supply & Pricing Matrix
Commercial hospitality buyers in Monterrey and Puebla anchor premium-tier pricing through specification requirements that bundle installation service and extended warranty coverage. Their procurement contracts favor value-based pricing over transactional spot purchasing, compressing margin flexibility for mid-range assemblers competing on unbundled hardware alone.
Pricing Analysis
Bundled installation and warranty packages dominate premium-tier transactions, while economy-tier sales run through unbundled cash-and-carry channels. Price differentiation rests on NOM-011-ENER certification grade and inverter compressor inclusion, with A-rated units commanding measurable premiums over legacy inventory. Pricing pressure intensifies in mid-range tiers as copper and steel input volatility compresses margins for producers without captive component sourcing. Residential buyers in peripheral municipalities exhibit highest price sensitivity, while commercial hospitality procurement shows lowest elasticity due to reliability requirements and maintenance contract preferences.
Supply Chain Analysis
Direct-to-retail channels handle volume flows to national chains, while specialized distributors serve project-based institutional buyers with captive financing relationships. Manufacturing concentrates in Mexico, China, and South Korea, with compressor motor winding and cold-rolled steel stamping anchored in Nuevo León facilities. Raw material dependencies center on copper windings, cold-rolled steel, and low-GWP refrigerant formulations. Single-source vulnerability runs through the Monterrey industrial corridor, where component stamping and motor assembly disruption propagates nationwide production delays. Distribution runs through layered wholesale networks into provincial retail, with online platforms capturing fastest acceleration in metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-011-ENER efficiency mandates compound replacement demand by stranding non-compliant inventory and accelerating inverter compressor adoption. This regulatory compression creates structural advantage for certified producers while marginalizing legacy assemblers.
For Market Incumbents: Anticipate refrigerant transition bottlenecks by pre-positioning low-GWP compressor sealing technologies before NOM revision deadlines. Defensive consolidation should prioritize captive technician training networks to address inverter motor diagnostic scarcity in provincial repair channels. Vertical integration into stamped metal component production mitigates copper and steel input volatility threatening mid-range tier margins. For New Entrants and Emerging Players: PROFECO extended warranty mandates in Mexico open a window for service-captive market entry through aftermarket network acquisitions previously held by informal technicians. White-space targets concentrate in Querétaro and Bajío Corridor first-time homebuyer segments, where appliance penetration trails Mexico City benchmarks substantially. Go-to-market execution should embed point-of-sale credit instruments through OXXO and Elektra provincial networks to reduce upfront payment barriers. For Investors and Strategic Acquirers: Korean electronics conglomerates are the most active acquirer in this space, seeking connected-appliance platform capabilities and inverter technology assets. Long-term viability favors targets with modular inverter platforms enabling rapid tier differentiation without complete supply chain duplication. Acquisition focus should center on domestic distributors with deep provincial retail penetration and captive service networks. Watch NOM standby power regulation finalization as inflection indicator for zero-standby relay circuit pre-positioning requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Inverter Platform Modularization | Enables rapid tier differentiation across premium, mid-range, and economy positioning without full supply chain duplication. |
| Captive Service Network Expansion | PROFECO extended warranty mandates shift aftermarket revenue from informal technicians to manufacturer-controlled repair channels. |
| Low-GWP Refrigerant Retooling | NOM refrigerant transition requirements demand compressor sealing technology adaptation to avoid certification bottlenecks. |
| Embedded Finance Integration | Point-of-sale credit through OXXO and Elektra networks reduces upfront barriers for provincial mid-range tier penetration. |
| Smart Grid Convergence Piloting | Jalisco Energy Agency time-of-use tariff programs validate demand-response revenue streams from inverter appliance integration. |
Research Methodology
Coverage spans Mexico's central urban corridor, northern border states, and Bajío region, with primary inputs from each. The approach combines structured interviews with appliance manufacturing executives, retail channel managers, and regulatory affairs specialists at Mexico's Secretariat of Economy with secondary validation. Stakeholder inputs were cross-referenced against NOM-011-ENER and NOM-005-ENER certification databases, PROFECO consumer protection filings, and customs trade records. Bottom-up channel volume estimates and top-down macroeconomic triangulation were reconciled to produce consistent market sizing.
Granularity-level modeling disaggregated volume and value across product type, end user segment, distribution channel, and price tier dimensions. The analytical framework projected trajectories across the analysis window using replacement cycle dynamics, regulatory compliance timelines, and electrification upgrade patterns. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated NOM revision schedules, grid infrastructure investment pipelines, and embedded finance penetration curves.
Revisions become necessary when NOM energy-efficiency mandates accelerate beyond current Secretariat of Economy timelines, or when copper and steel commodity volatility exceeds historical bands. Forecasts reflect assumptions about regulatory enforcement consistency, distributor credit availability, and technician training network expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Small Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Asia Pacific Portable Washing Machine Market
Home Appliances
Bahrain Small Home Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Smart Small Home Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Portable Dehumidifier Market
Home Appliances
Sweden Home Appliances Market
Home Appliances
United States Small Home Appliances Market
Home Appliances
North America Major Home Appliances Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
Australia Home Appliances Market