
 Steam Clothing Care System Market | 2026-2036
Steam Clothing Care System Market Size, Share, and Industry Trends Forecast 2026-2036
Steam Clothing Care System Market Analytics
Hotel procurement of commercial garment steamers is expanding faster than traditional home-use channels as hospitality brands prioritize in-room fabric care. Electrolux Professional dominates commercial installations through its dedicated hospitality division. Philips leverages consumer brand strength to sustain premium positioning in European retail. LG competes on smart connectivity integration across its garment steamer lineup.
A steam clothing care system employs pressurized vapor generation, typically through boiler or thermoblock heating elements reaching temperatures between 120°C and 160°C, to relax textile fibers and remove wrinkles without mechanical contact. The primary purpose spans domestic convenience, commercial hospitality service efficiency, and industrial textile finishing quality control. Garment steamers command the fastest expansion trajectory as consumers shift away from traditional ironing boards. Smart technology integration sits at the highest margin tier as connected diagnostics and app-controlled settings justify price premiums. Conventional steam irons retain volume leadership in emerging markets where purchase price sensitivity dominates.
EPA energy-efficiency testing protocols shape minimum performance thresholds for products sold in the United States, while EU Ecodesign regulations and REACH chemical compliance constrain material selection and manufacturing processes for European market access. Japan's METI enforces stringent electrical safety standards that filter out lower-cost competitors. Stakeholders must monitor evolving efficiency mandates and connectivity security requirements as regulatory scope broadens beyond energy into data governance.
Market Dynamics
Commercial hospitality procurement is consolidating demand around in-room garment care as hotel chains standardize guest experience metrics. This institutional buyer concentration is compressing procurement cycles and forcing manufacturers to reconfigure distribution toward direct-contract models with property management groups.
Growth Catalysts
- EPA Energy-Efficiency Testing Protocols:Mandatory minimum performance thresholds for U.S. product entry are accelerating R&D investment in thermoblock heating elements that reduce wattage without sacrificing steam output.
- Hospitality Brand Standardization:Premium hotel chains in Germany and Japan are mandating in-room garment steamers as baseline amenities, creating institutional pull that outpaces residential replacement cycles.
- Smart Connectivity Integration:App-controlled diagnostics and usage tracking are enabling premium pricing tiers that capture margin from connected-home ecosystems.
Market Restraints
- Copper and Aluminum Input Volatility:Heating element manufacturing faces raw material price swings that compress margin predictability for boiler-based system producers.
- EU REACH Chemical Compliance:Material selection constraints on plastics and coatings add certification timeline friction for Asian manufacturers targeting European market access.
- Conventional Steam Iron Substitution:Price-sensitive emerging market consumers continue selecting traditional irons over garment steamers, limiting volume expansion in lower-income demographics.
Strategic Opportunities
- Underpenetrated Indian Household Segment:Rising middle-class appliance ownership in urban centers creates first-mover positioning for compact garment steamer variants adapted to voltage fluctuation conditions.
- EU Ecodesign Regulatory Tailwind:Efficiency mandates are disqualifying legacy high-wattage competitors, opening shelf space for compliant low-energy product lines.
- Direct-to-Property Procurement Channels:Bypassing traditional retail through hospitality supply contracts reduces working capital intensity and locks in multi-year replacement schedules.
Industry Challenges
- Embedded Software Engineering Talent Scarcity:Connected product development requires firmware capabilities that legacy appliance manufacturers must acquire through competitive hiring against consumer electronics firms.
- Multi-Jurisdiction Certification Parallelism:Simultaneous EPA, EU Ecodesign, and Japan METI compliance testing extends product launch timelines and fragments validation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steam Clothing Care System Market |
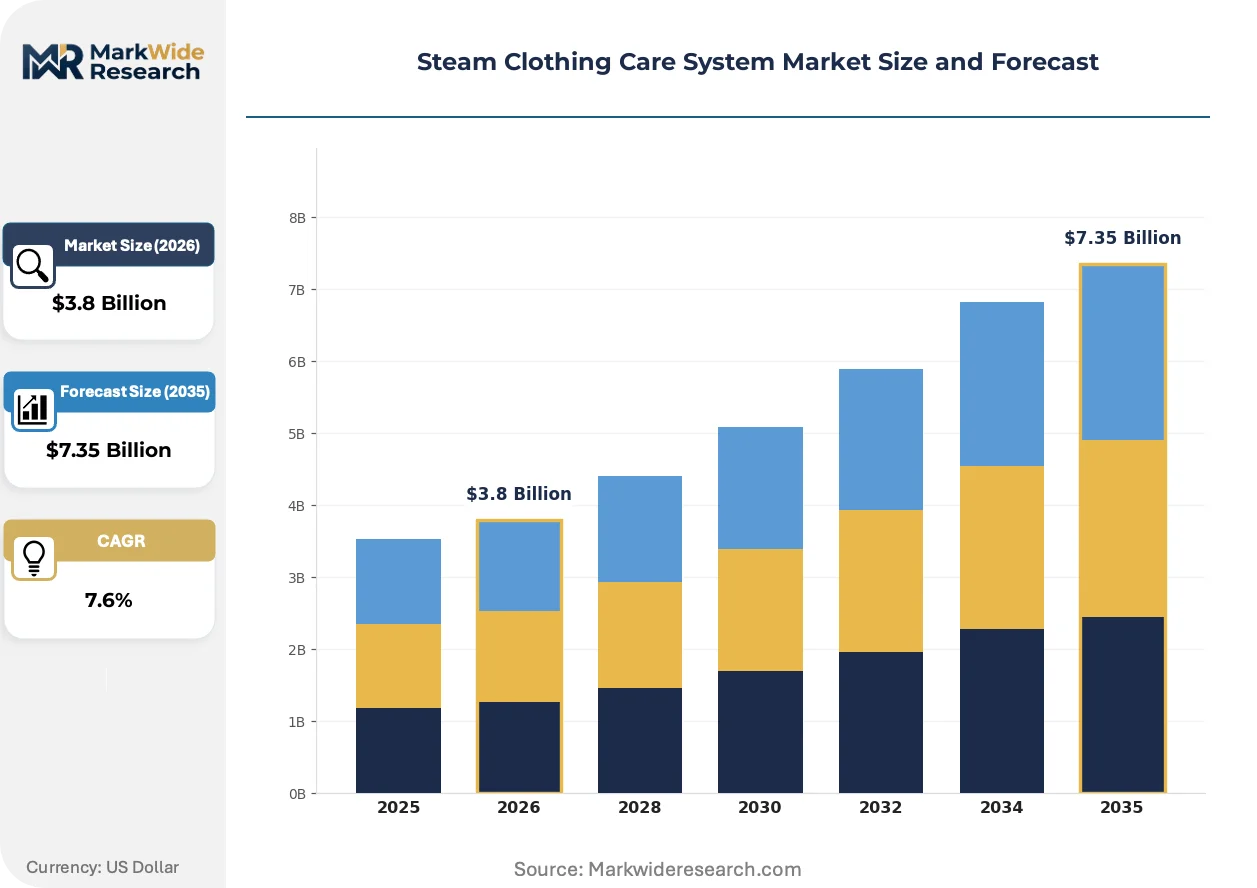
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steam Irons, Garment Steamers, Steam Mops, Fabric Steamers Application: Home Use, Commercial Use, Industrial Use, Retail Technology: Conventional, Digital, Smart Technology, Portable End User: Households, Hotels, Dry Cleaners, Textile Manufacturers |
| Companies Covered | Electrolux Professional, Philips, LG, Haier, Panasonic Corporation, Samsung, Whirlpool, Conair Corporation, Coway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steam Clothing Care System Market Evolving Landscape
Heating element architecture is undergoing fundamental redesign as efficiency mandates intersect with connectivity requirements. Manufacturers are converging on modular platforms that accommodate both regulatory compliance and smart feature integration.
Thermoblock heating systems are consolidating market preference over traditional boiler designs by enabling faster heat-up cycles and reduced energy consumption. Hospitality procurement teams are specifying these systems for new property fit-outs at accelerating rates. The technology is consolidating supplier tiers as smaller boiler-specialist manufacturers lose specification access to institutional buyers.
EU Ecodesign requirements are tightening minimum efficiency thresholds for textile care appliances sold in member states. Manufacturers must now demonstrate reduced standby power consumption and optimized steam generation cycles to maintain market access. Garment steamer product lines targeting European retail face the steepest redesign burden, with several incumbent models requiring heating element replacement to remain compliant.
Commercial buyers are consolidating procurement authority at corporate headquarters rather than property-level discretion. Hotel chains in Germany and the United States are centralizing garment steamer selection into master service agreements that specify brand, model, and replacement cadence. This concentration is compressing vendor diversity and rewarding manufacturers with dedicated hospitality divisions and national service networks.
Steam Clothing Care System Market Segmentation
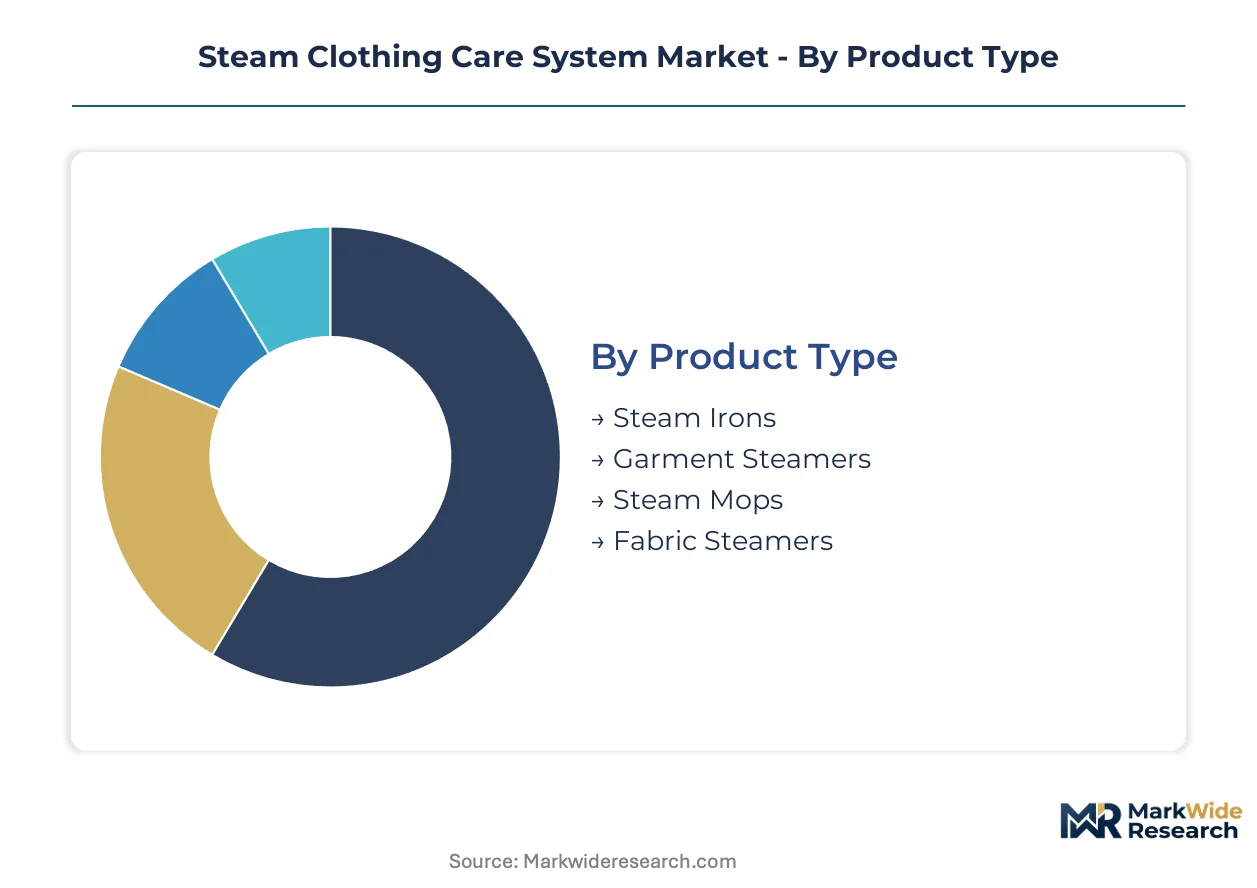
Segmentation in steam clothing care systems reveals how procurement authority, technical specifications, and end-use environments fragment demand. Manufacturers must align heating element architectures and connectivity features to distinct buyer workflows rather than pursuing universal product designs.
Product Type:
Replacement cycles diverge sharply across product formats, with institutional buyers compressing procurement timelines through master service agreements while household users extend ownership durations.
- Garment Steamers:Vertical steaming units deploy pressurized vapor through handheld wands without pressing surfaces. Hospitality procurement in Germany and Japan mandates these as baseline in-room amenities, institutionalizing demand that outpaces residential replacement velocity.
- Steam Irons:Traditional flat-soleplate designs with integrated water reservoirs remain dominant in emerging markets where purchase price thresholds constrain adoption of alternative formats. Volume concentrates in price-sensitive demographics across India and Southeast Asia.
- Steam Mops:Floor-surface cleaning systems adapted for textile-compatible steam output serve hybrid household maintenance workflows.
- Fabric Steamers:Compact portable units target travel and small-space storage constraints in urban apartment segments.
Volume placements concentrate in Steam Irons; the faster expansion belongs to Garment Steamers.
Application:
Cost tier stratification separates capital-intensive commercial installations from discretionary household purchases, with service contract bundling reshaping effective pricing in institutional channels.
- Commercial Use:Hotel chains and hospitality groups specify thermoblock systems through centralized procurement, locking multi-year replacement schedules into property management software. EPA energy-efficiency testing protocols filter supplier eligibility for US market access.
- Home Use:Individual consumers select across premium connected units and basic boiler designs based on countertop space constraints and app ecosystem compatibility preferences.
- Industrial Use:Textile finishing operations deploy high-capacity continuous-feed systems for quality control in garment production workflows.
- Retail:Point-of-sale steaming stations serve fast-fashion inventory presentation requirements in clothing stores.
Margin capture concentrates in Commercial Use; the steepest expansion trajectory runs through Home Use connectivity integration.
Technology:
Maturity gradients separate legacy heating architectures from digitally controlled platforms, with firmware capabilities becoming the binding constraint on product development timelines.
- Smart Technology:App-controlled diagnostics and usage tracking enable premium pricing tiers through connected-home ecosystem integration. EU Ecodesign standby power requirements are disqualifying non-compliant legacy competitors from European shelf space.
- Digital:Microprocessor-regulated thermoblock systems deliver precise temperature control with faster heat-up cycles than analog predecessors.
- Conventional:Boiler-based designs with mechanical thermostats retain cost advantages in price-sensitive market tiers.
- Portable:Battery-compatible compact units sacrifice steam output for mobility in travel and dormitory segments.
Revenue concentration sits with Digital platforms; capability scarcity most constrains Smart Technology development pipelines.
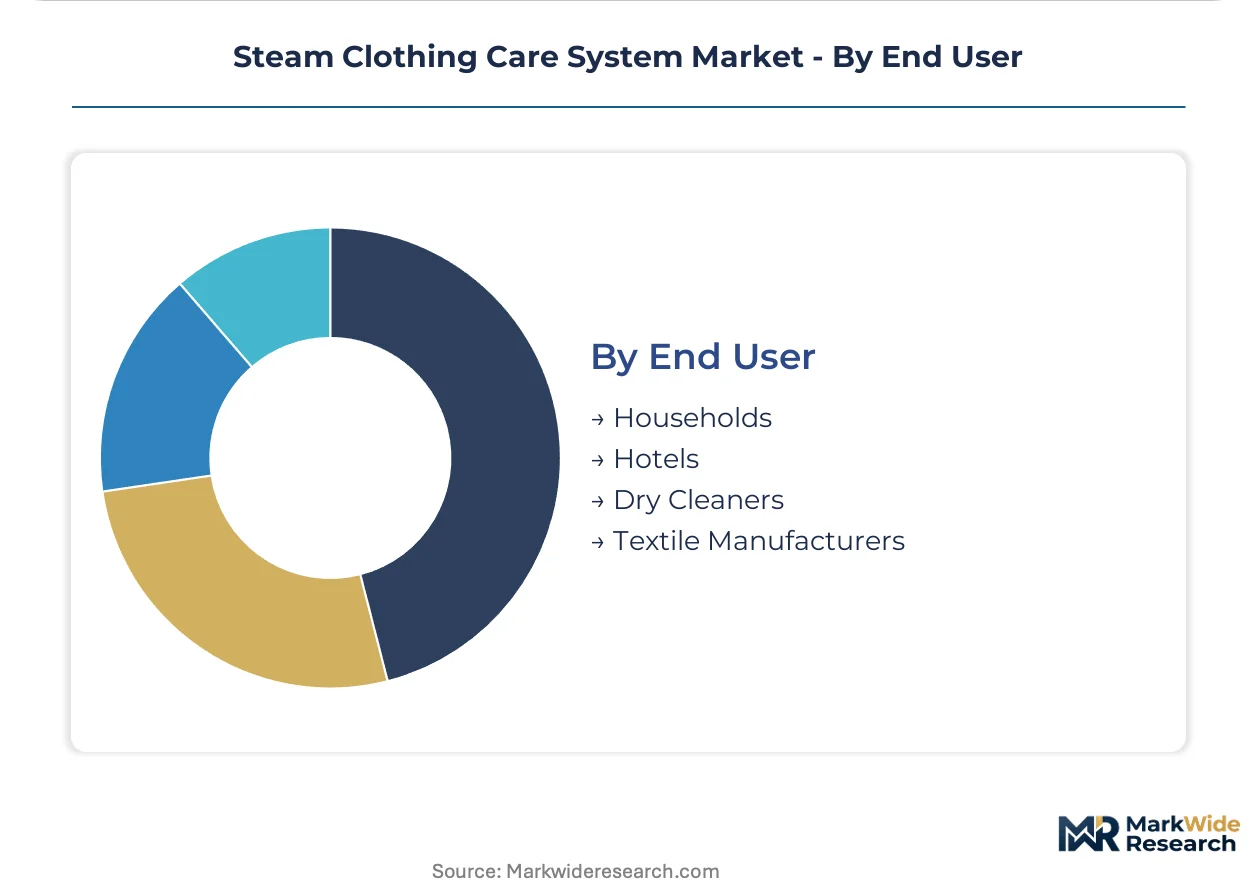
End User:
Customer type fragmentation demands divergent service architectures, with hospitality accounts requiring national maintenance networks that household channels bypass entirely.
- Hotels:Property management groups in North America and Europe centralize garment steamer selection into brand standards that specify model, replacement cadence, and service response times. Electrolux Professional and dedicated hospitality divisions capture this concentrated demand.
- Households:Individual purchasers respond to retail placement and consumer brand recognition, with Philips sustaining premium positioning through European distribution strength.
- Dry Cleaners:Commercial service providers integrate high-capacity units into production workflows with volume-based utilization patterns.
- Textile Manufacturers:Industrial finishing operations deploy continuous-feed systems for quality control in garment production.
Procurement consolidation concentrates in Hotels; Households retain the broadest geographic dispersion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate thermoblock heating element manufacturing, attracting contract manufacturers serving hospitality procurement networks across Asia-Pacific and North America.
United States
Hotel chains in Texas and Florida are accelerating in-room garment steamer deployment as guest satisfaction metrics tighten. EPA energy-efficiency testing protocols filter supplier eligibility for products entering the market. Dallas-Fort Worth hosts distribution centers for commercial hospitality supply contracts serving mid-market hotel brands.
Germany
Premium hospitality groups in Bavaria and Baden-Württemberg mandate thermoblock systems as baseline brand standards. EU Ecodesign requirements constrain standby power consumption and heating element efficiency thresholds. Stuttgart's industrial corridor hosts R&D facilities optimizing thermoblock architectures for European regulatory compliance.
Japan
Discerning household segments in Tokyo and Osaka sustain premium demand for connected garment care systems. METI enforces stringent electrical safety standards that exclude lower-cost competitors from market access. Osaka's appliance manufacturing cluster specializes in compact high-output heating elements for space-constrained urban apartments.
China
Domestic hospitality construction in Shanghai and Guangzhou drives commercial-grade garment steamer procurement for new property fit-outs. GB standards and MIIT regulations govern product safety and energy labeling requirements. Shenzhen's special economic zone concentrates contract manufacturers producing thermoblock components for export to North American and European markets.
India
Rising middle-class appliance ownership in Mumbai and Bangalore creates first-mover positioning for compact garment steamer variants. BIS certification requirements and voltage fluctuation standards constrain product design specifications. Tamil Nadu's manufacturing belt hosts assembly operations adapting heating element designs to local electrical infrastructure conditions.
Steam Clothing Care System Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospitality procurement consolidating around dedicated commercial divisions while household channels fragment across consumer electronics and appliance brands. The vendor base organizes into three tiers: multinational appliance conglomerates with hospitality divisions, consumer electronics firms leveraging smart connectivity integration, and regional contract manufacturers supplying private-label programs. Consolidation pressures are intensifying through direct-to-property procurement contracts and multi-year master service agreements that lock out smaller competitors.
Within the multinational appliance tier, Electrolux Professional, Philips, and LG exemplify divergent strategic positioning. Electrolux Professional anchors the commercial hospitality vector through dedicated institutional service networks. Philips occupies premium retail positioning across European distribution channels. LG represents the connectivity-forward archetype, integrating smart diagnostics into garment care lineups. These three firms collectively illustrate how scale, specialization, and digital capability define competitive separation in procurement channels that increasingly bypass traditional retail.
| Leading Market Players |
|---|
| Electrolux Professional |
| Philips |
| LG |
| Haier |
| Panasonic Corporation |
| Samsung |
| Whirlpool |
| Conair Corporation |
| Coway |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between EPA-compliant thermoblock systems and legacy boiler designs manifests in dual pricing architectures and geographically fragmented supply configurations. Premium hospitality procurement in Germany and Japan commands 40-60% effective price premiums through bundled service contracts, while commodity steam iron channels in India and Southeast Asia compete on landed cost minimization with stripped-down distribution.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with hospitality property management groups paying effective premiums for 4-6 week fulfillment windows versus 12-16 week standard cycles. Three-tier pricing structure across premium, standard, and economy levels separates smart-connected garment steamers with app diagnostics from digital thermoblock units and conventional boiler designs. Pricing pressure stems from copper and aluminum input volatility compressing margin predictability for heating element manufacturers. Household channels in emerging markets exhibit highest price sensitivity, while commercial buyers in North America prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Shenzhen and Dongguan special economic zones concentrating thermoblock heating element manufacturing for export markets. Component sourcing draws from China for thermoblock assemblies, Japan for compact high-output heating elements, and Germany for precision control systems. Raw material dependencies center on copper wire for resistive elements, aluminum for heat exchangers, and engineering plastics for housing components. Tariff exposure on Chinese-manufactured components shipped to US hospitality procurement channels represents the dominant structural risk. Distribution runs through direct-to-property procurement contracts for commercial segments and retail electronics channels for household segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration into heating element manufacturing as copper and aluminum volatility erodes assembler margins. Control over thermoblock production capabilities separates sustainable competitors from margin-compressed assemblers.
For Market Incumbents: Deploy captive thermoblock production capacity to defend margin structure against raw material volatility. Electrolux Professional and Philips should deepen backward integration into Shenzhen manufacturing partnerships or acquire precision heating element specialists. Hospitality procurement consolidation threatens assembler-only business models lacking component control. Certification pre-positioning for EU Ecodesign standby power tightening filters competitor eligibility ahead of regulatory enforcement. For New Entrants and Emerging Players: Direct-to-consumer digital channels offer the most penetrable route for compact garment steamer variants targeting Indian urban middle-class households. First-mover positioning in voltage-fluctuation-adapted designs for Mumbai and Bangalore bypasses established retail distribution gatekeepers. White-space exists in connected-home ecosystem integration for price-disruptive smart garment steamers undercutting LG and Samsung premium positioning. Target hospitality supply contract bidding for mid-market US hotel chains outside Electrolux Professional's installed base dominance. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by multinational appliance conglomerates seeking hospitality division capabilities. Long-term viability favors vertically integrated manufacturers with thermoblock R&D facilities in Stuttgart or Osaka industrial corridors. Acquisition target archetype: mid-cap specialists with EPA-compliant product lines and active hospitality procurement contracts. Watch for EU Ecodesign enforcement acceleration disqualifying legacy high-wattage competitors as inflection indicator for compliant product line valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Thermoblock Heating Element Backward Integration | Captive production of thermoblock components insulates margins from copper and aluminum price swings. |
| Hospitality Master Service Agreement Expansion | Direct-to-property procurement contracts with Marriott or Hilton lock multi-year replacement revenue visibility. |
| Smart Connectivity Platform Development | App-controlled diagnostics integration captures premium pricing tiers in connected-home ecosystems. |
| EU Ecodesign Compliance Pre-Positioning | Standby power optimization ahead of regulatory tightening opens shelf space vacated by non-compliant incumbents. |
| India-Adapted Compact Variant Launch | Voltage-fluctuation-tolerant designs target underpenetrated urban middle-class appliance ownership growth. |
Research Methodology
Trade databases, hospitality procurement registries, and appliance regulatory filings formed the secondary backbone for market sizing and competitive mapping. Primary interviews with hotel procurement directors, heating element manufacturing engineers, appliance retail category managers, and regulatory compliance officers validated demand assumptions and technology transition timelines. Bottom-up unit shipment estimates triangulated against top-down value projections derived from disclosed contract values and retail pricing audits.
Historical trendline analysis of garment steamer adoption rates in hospitality and household channels established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, application, technology tier, and end-user category with regional regulatory cluster overlays. CAGRs were derived from regression analysis of replacement cycle compression, connectivity penetration curves, and efficiency mandate implementation schedules. Forecast inputs incorporated thermoblock versus boiler technology substitution rates and hospitality property construction pipelines.
The model holds under stable copper and aluminum pricing and gradual EU Ecodesign enforcement; deviation in raw material spike events or accelerated regulatory disqualification would shift volume and value trajectories. Forecasts reflect assumptions regarding hospitality brand standardization velocity and smart home ecosystem integration adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
United States Major Home Appliances Market
Home Appliances
Italy Home Appliances Market
Home Appliances
Saudi Arabia Home Appliances Market
Home Appliances
Side-By-Side Smart Refrigerator Market
Home Appliances
India Small Home Appliances Market
Home Appliances
Asia-Pacific Major Home Appliance Market
Home Appliances
Global Electric Motors Household Appliances Market
Home Appliances
Household Refrigerator Market
Home Appliances
Germany Washing Machine Market
Home Appliances
Middle East and Africa Home Appliances Market
Home Appliances
South Korea Small Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
Slovakia Home Appliances Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
High-End French Door Refrigerator Market