
 Europe Washing Machine Market | 2026-2036
Europe Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Washing Machine Market Foresight
EU Ecodesign regulations is recalibrating the cost-of-entry calculus for appliance manufacturers targeting the European market. Electrolux leverages its vertically integrated manufacturing footprint across Poland and Italy to absorb compliance costs without passing full premiums to consumers. Bosch differentiates through precision-engineered motor systems that exceed current efficiency thresholds by substantial margins. Miele sustains its position in the premium tier by controlling captive component supply chains for drum assemblies and electronic control modules.
A washing machine is a motorized domestic appliance engineered to clean textiles through mechanical agitation, centrifugal spin cycles, and programmable water-temperature control typically ranging from 20°C to 90°C. Its primary commercial purpose spans residential garment care, on-premise laundry operations for hospitality properties, and centralized linen-processing facilities. Front-load configurations command the dominant installed base due to superior water efficiency and stackability constraints in European dwellings. Smart washing machines represent the fastest-expanding product category as Wi-Fi-enabled units with automated detergent dosing penetrate urban households. High-efficiency technology anchors margin pools for OEMs because certified models qualify for national rebate schemes in France, Germany, and the Netherlands.
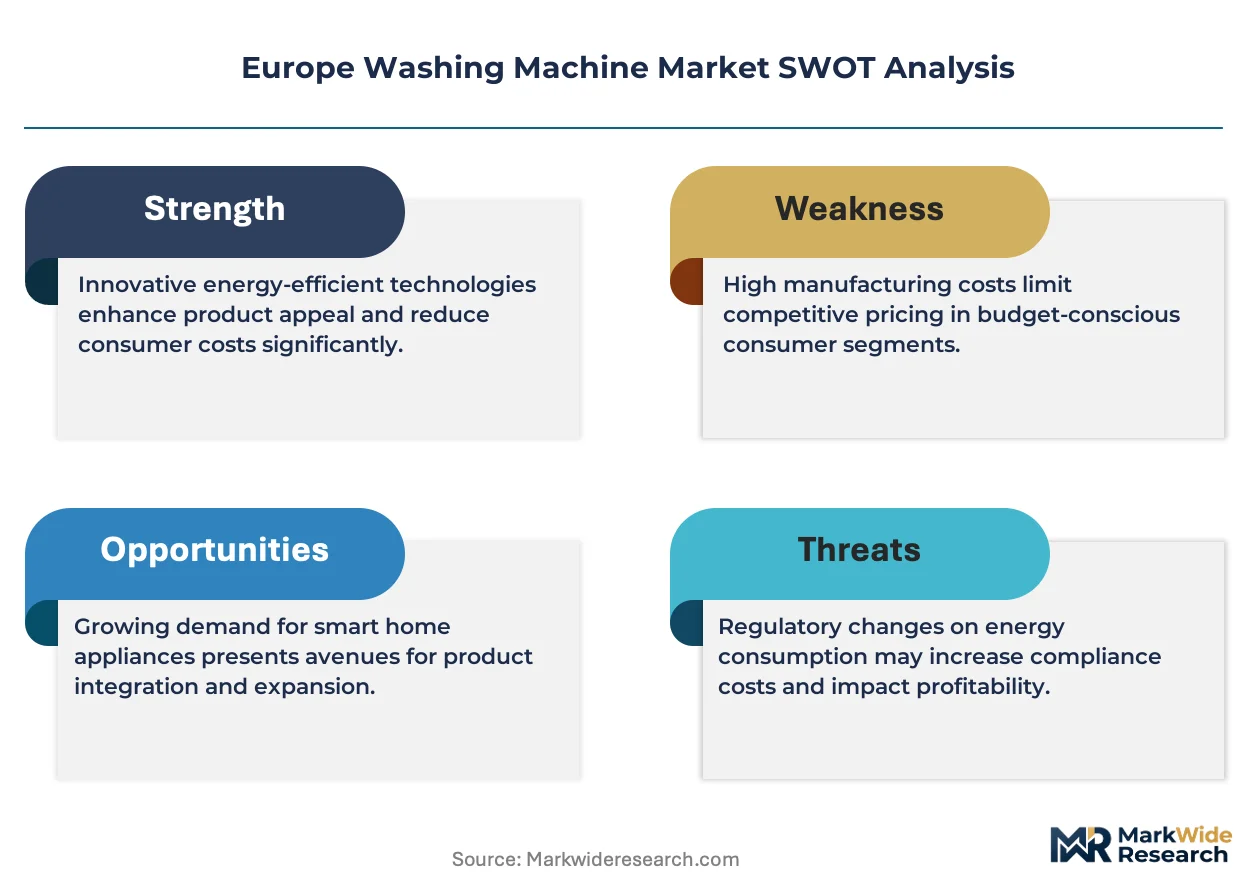
CE marking, EU Ecodesign directives, and national energy-labeling frameworks collectively shape product development timelines and import eligibility for non-European manufacturers. The EU F-Gas Regulation further constrains refrigerant choices in washer-dryer combo units, pushing R&D investment toward heat-pump drying architectures. Stakeholders must monitor pending revisions to the Ecodesign Working Plan that could mandate connected-device interoperability standards before the decade closes.
Market Dynamics
EU Ecodesign mandates are compressing product development cycles and forcing appliance manufacturers to redesign motor architectures and water-heating systems before the next regulatory tranche takes effect.
Growth Catalysts
- EU Green Deal energy-efficiency thresholds:Member states are accelerating replacement cycles for aging machines as rebate schemes in France and Germany favor A-rated appliances over legacy C-class units.
- Commercial laundry fleet modernization:Italian hospitality operators and German hospital linen processors are upgrading to water-recirculating systems to preempt municipal consumption tariffs.
- Heat-pump drying convergence:Washer-dryer combos incorporating heat-pump architectures are displacing vented models as the EU F-Gas Regulation restricts refrigerant options.
Market Restraints
- Steel and copper input volatility:Drum assembly and motor winding costs fluctuate with commodity markets, compressing margin predictability for mid-tier producers.
- Electronic control module supply concentration:Semiconductor fabrication for appliance-grade microcontrollers clusters in East Asian foundries, exposing European OEMs to shipping disruptions.
- Installation footprint rigidity:Front-load machine dimensions are standardized around 60cm width, limiting differentiation and trapping manufacturers in price competition.
Strategic Opportunities
- Polish and Romanian residential penetration:Eastern European markets show lower washing machine ownership per household than Western Europe, creating volume expansion potential for entry-tier suppliers.
- Interoperability mandate preparation:Pending Ecodesign Working Plan revisions may require connected-device standards, rewarding early investments in open API architectures.
- Subscription-based fleet management:Commercial operators in the Netherlands are piloting usage-based leasing models that bundle maintenance and detergent supply.
Industry Challenges
- Embedded software certification timelines:CE marking for Wi-Fi-enabled units requires cybersecurity validation under evolving RED directives, extending time-to-market by quarters.
- Skill scarcity in heat-pump system integration:Technician training for sealed refrigeration circuits lags behind product launch schedules, constraining after-sales service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Washing Machine Market |
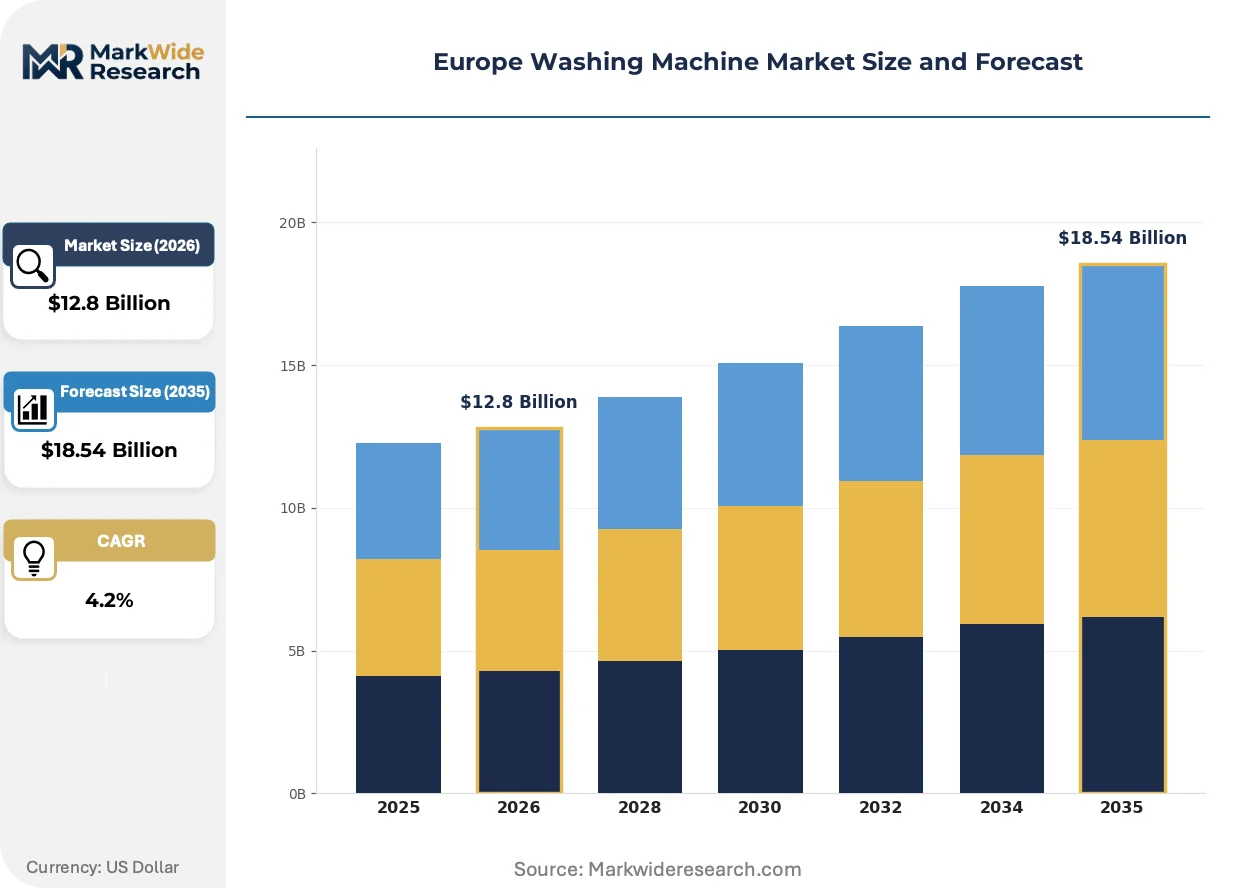
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $18.54 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Load, Front-Load, Washer-Dryer Combo, Smart Washing Machines End User: Households, Commercial Laundries, Retail Stores, Hospitality Technology: Automated, Semi-Automatic, High-Efficiency, Steam Wash Distribution Channel: Online Retailers, Offline Retail Stores, Direct Sales, Third-Party Distributors |
| Companies Covered | Electrolux, Bosch, Whirlpool, Miele, LG Electronics, Samsung Electronics, Haier, Beko, Hitachi, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Washing Machine Market Shifts & Advancements
Connected appliance architectures and circular-economy compliance requirements are redrawing competitive boundaries between hardware specialists and software-platform providers.
Automated detergent dosing systems are integrating optical soil sensors and machine-learning wash-cycle optimization to reduce chemical consumption by calibrated amounts. Urban households in Germany and France are adopting these units fastest, treating water and detergent savings as measurable household budget items. This capability is integrating smart-home ecosystems with utility demand-response programs, compressing the traditional standalone appliance model.
The EU F-Gas Regulation is tightening refrigerant specifications for washer-dryer combinations, forcing R&D investment toward hydrocarbon and CO2 heat-pump alternatives. Manufacturers must redesign sealed systems and retrain field service networks to handle flammable working fluids. Southern European markets with higher combo-unit penetration are experiencing the steepest compliance cost escalation.
Urban households are compressing replacement cycles for washing machines as rental and subscription models displace outright ownership. Dutch and Swedish property management firms now bundle appliances into monthly housing fees, treating durability and remote diagnostics as service-level agreements. This shift is most visible in multi-unit residential construction in Amsterdam and Stockholm, where developers specify connected machines with predictive maintenance APIs.
Europe Washing Machine Market Segmentation
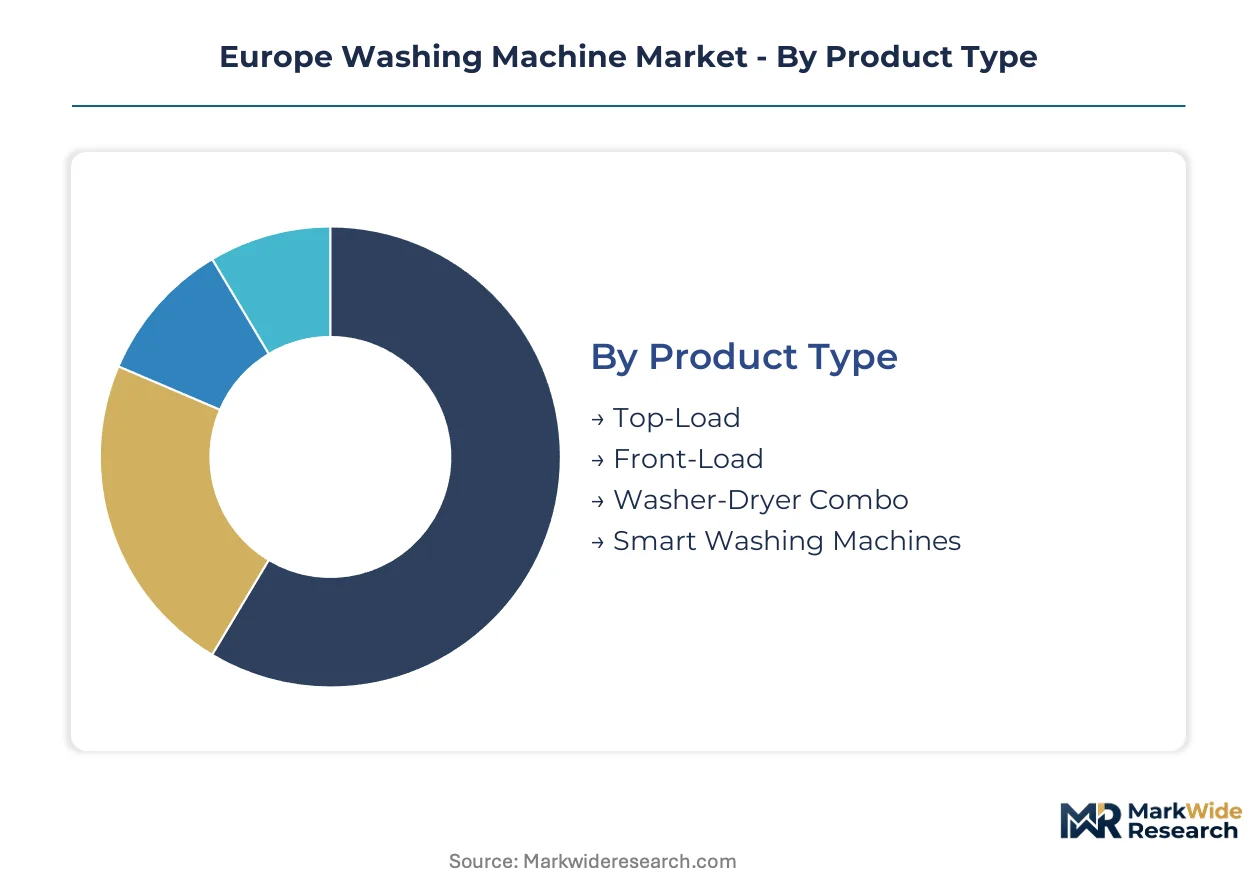
Segmentation in the Europe Washing Machine Market reveals how regulatory thresholds and installation constraints fragment demand across product architectures and customer types. Certification requirements under EU Ecodesign and CE marking create divergent compliance burdens that reshape competitive positioning within each slice.
Product Type:
CE marking and EU Ecodesign directives impose tiered certification burdens: front-load units face stricter water-efficiency thresholds, while washer-dryer combos must satisfy both washing-machine and F-Gas refrigerant regulations.
- Front-Load:Horizontal-axis drum configuration with gravity-fed water circulation and superior centrifugal extraction. German and French urban households dominate demand as stackability solves space constraints in multi-unit dwellings. The segment commands the largest installed base due to mandatory water-consumption limits in municipal building codes.
- Smart Washing Machines:Wi-Fi-enabled units with cloud-connected diagnostics, automated detergent dosing, and utility demand-response integration. Dutch property management firms and Swedish housing cooperatives are adopting these fastest as subscription models replace outright ownership. Cybersecurity validation under RED directives extends certification timelines for these connected architectures.
- Top-Load:Vertical-axis agitation systems with faster cycle times but higher water consumption. Polish and Romanian rural households maintain residual demand where water tariffs remain low and installation footprints are unconstrained.
- Washer-Dryer Combo:Integrated washing and drying in a single chassis using heat-pump or condenser architectures. Southern European markets show higher penetration where space constraints are most severe and separate dryer installation is impractical.
Front-Load sits at the top of the volume ranking, with Smart Washing Machines climbing the fastest.
End User:
Customer type determines procurement scale and service-level expectations, stretching from individual household replacement cycles to fleet-managed commercial operations with predictive maintenance contracts.
- Households:Individual residential purchasers selecting units based on energy-label grades and rebate eligibility. German and French households prioritize A-rated appliances to capture national subsidy schemes, while Eastern European buyers remain price-sensitive toward entry-tier certification levels.
- Commercial Laundries:Centralized linen-processing facilities serving hospitality and healthcare with continuous-duty machines. Italian operators are upgrading to water-recirculating systems to preempt municipal consumption tariffs and comply with regional environmental permits.
- Hospitality:On-premise laundry operations for hotels and resorts with high-throughput requirements. Spanish and Greek island properties favor compact washer-dryer combos where space and ventilation are limited.
- Retail Stores:Demonstration units and customer-facing appliance showrooms requiring reliable performance under intermittent use. Benelux electronics chains specify connected models with remote diagnostics to minimize floor maintenance.
Households generate the dominant revenue pool, though Commercial Laundries are expanding most quickly as fleet modernization accelerates.
Technology:
Automation level and efficiency certification stratify margin structures, with high-efficiency architectures qualifying for premium pricing through national rebate programs.
- High-Efficiency:Optimized motor systems and precision water heating that exceed baseline EU Ecodesign thresholds by substantial margins. French, German, and Dutch rebate schemes restrict eligibility to these certified models, compressing demand for legacy architectures.
- Automated:Fully programmable cycles with sensor-driven load detection and adaptive water levels. Urban households across Northern Europe adopt these units fastest where utility metering creates visible cost savings.
- Semi-Automatic:Manual intervention required for water filling and drainage. Residual demand persists in price-sensitive Eastern European markets and temporary housing installations.
- Steam Wash:High-temperature vapor injection for sanitization and allergen reduction. Healthcare linen processors in Germany and allergy-conscious households in Scandinavia drive niche adoption.
High-Efficiency technology anchors the largest margin pool, while Automated systems are gaining share fastest as sensor costs decline.
Distribution Channel:
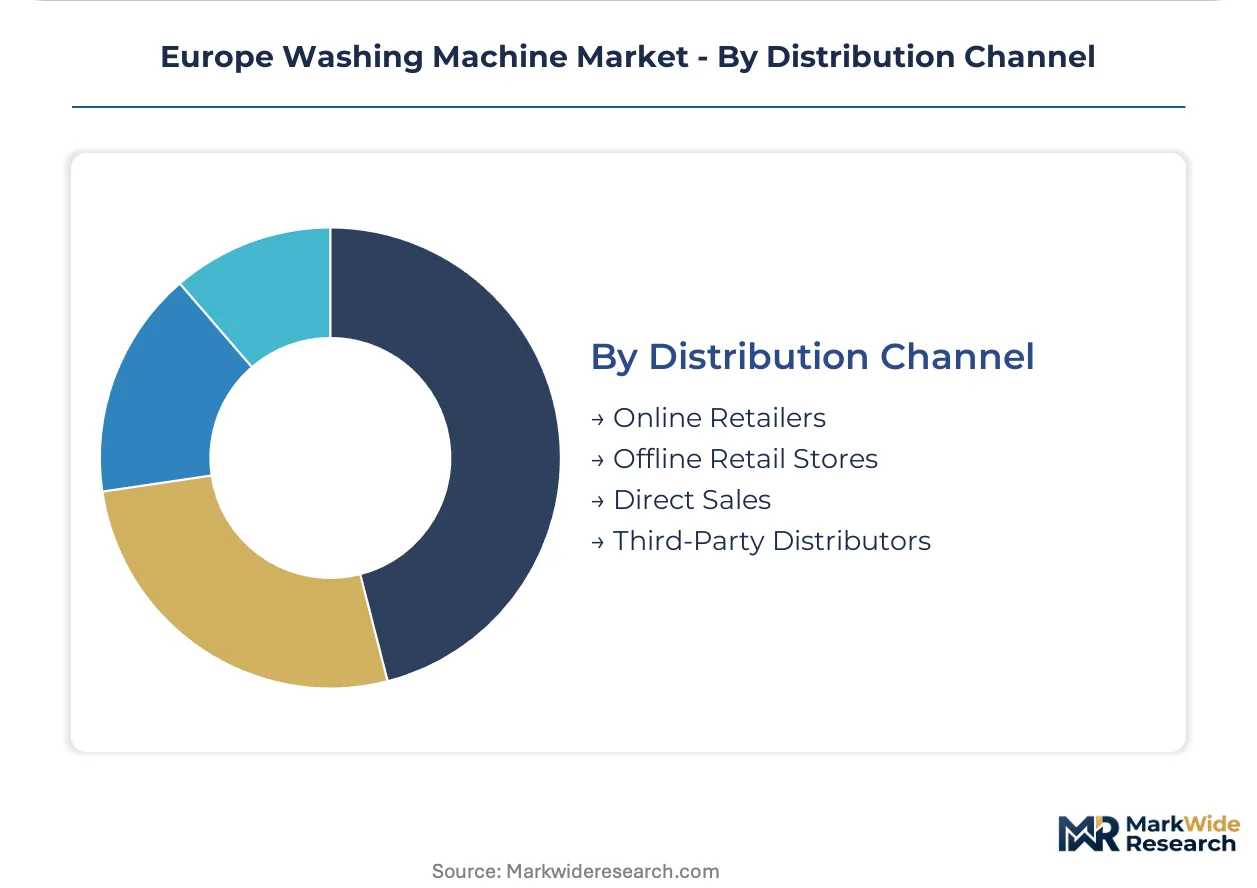
Channel structure reflects customer touchpoint preferences and installation service requirements, with online growth constrained by the need for professional setup and warranty validation.
- Offline Retail Stores:Physical showrooms with tactile product demonstration and bundled installation services. German and Italian kitchen specialists dominate premium transactions where in-person consultation influences selection.
- Online Retailers:E-commerce platforms with comparative energy-label display and home-delivery logistics. Dutch and Swedish consumers show highest online penetration where subscription housing models simplify specification.
- Direct Sales:Manufacturer-controlled channels for commercial fleet contracts and property developer bulk procurement. Electrolux and Bosch deploy dedicated account teams for hospitality and healthcare operators.
- Third-Party Distributors:Independent wholesalers serving rural and secondary markets with inventory buffering. Polish and Romanian coverage depends on these networks where manufacturer direct presence is thin.
Offline Retail Stores retain the highest transaction value, with Online Retailers expanding most quickly among replacement purchases in digitally mature markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European washing machine manufacturing traces its industrial lineage to early 20th-century Germany and Sweden, where precision engineering traditions established the continent's dominance in appliance innovation. These foundational capabilities now concentrate across five national markets, each shaped by distinct regulatory and demand environments.
Germany
Urban households in Berlin, Munich, and Hamburg are accelerating replacement cycles for A-rated appliances under the federal BAFA rebate scheme. The EU Ecodesign directive mandates stricter water-efficiency thresholds that German OEMs must meet by 2027. The industrial corridor between Stuttgart and Nuremberg hosts concentrated R&D facilities for motor architecture and heat-pump system integration.
France
French consumers prioritize connected appliances with automated detergent dosing as utility metering creates visible cost savings in Paris and Lyon metropolitan areas. The national MaPrimeRénov program subsidizes high-efficiency washing machine purchases for energy renovation projects. Manufacturing clusters in the Rhône-Alpes region specialize in electronic control module assembly and precision drum fabrication.
Italy
Commercial laundry operators in Milan and Rome are upgrading fleets to water-recirculating systems ahead of regional environmental permit revisions. The Italian Ministry of Ecological Transition enforces municipal consumption tariffs that penalize legacy equipment. The industrial district around Varese maintains specialized capacity for hospitality-sector compact washer-dryer combos.
Netherlands
Subscription-based appliance models are displacing outright ownership in Amsterdam and Rotterdam multi-unit residential construction. The Dutch Environmental Management Act imposes extended producer responsibility schemes for circular-economy compliance. Eindhoven-region technology firms are piloting predictive maintenance APIs for property management fleet contracts.
Poland
Lower washing machine ownership per household in Warsaw and Kraków creates volume expansion potential for entry-tier suppliers. The Polish Office of Competition and Consumer Protection enforces CE marking validation for imported units. Manufacturing facilities in the Łódź Voivodeship serve as export hubs for Eastern European distribution networks.
Europe Washing Machine Market Competitive Landscape
The competitive structure tilts toward diversified appliance conglomerates with captive component supply chains. Market concentration remains moderate, with five to eight firms commanding significant installed bases across national markets. Two strategic archetypes dominate: vertically integrated European heritage brands controlling drum and motor production, and scale-driven Asian electronics groups leveraging semiconductor and display synergies. Competitive moves center on heat-pump R&D partnerships and compliance-driven portfolio pruning of sub-A-rated models.
Within the heritage-brand tier, Electrolux and Miele exemplify European engineering-focused positioning, while Bosch anchors German precision-manufacturing credibility. These firms occupy positions defined by captive supply chain control and premium-tier pricing power. Asian-scale players including LG Electronics and Samsung Electronics represent electronics-convergence archetypes, situating washing machines within broader smart-home ecosystem strategies.
| Leading Market Players |
|---|
| Electrolux |
| Bosch |
| Whirlpool |
| Miele |
| LG Electronics |
| Samsung Electronics |
| Haier |
| Beko |
| Hitachi |
| Others |
Supply & Pricing Matrix
EU Ecodesign energy-efficiency mandates gate qualified supply and premium-tier pricing access by restricting rebate eligibility to certified A-rated architectures. Manufacturers absorbing compliance costs in motor and heating-system redesigns must recover investment through tiered positioning, while uncertified inventory faces accelerated obsolescence.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by energy-label grade and smart-connectivity bundling. Price differentiation stems from CE marking tier and after-sales service integration, with connected diagnostics commanding sustained premiums. Cost compression in entry-tier units intensifies due to steel and copper volatility, while Eastern European households exhibit highest price sensitivity and Dutch subscription-model buyers show lowest.
Supply Chain Analysis
Container freight rate fluctuations from East Asian foundries to European ports directly input cost variability for electronic control modules. Component fabrication concentrates in China, South Korea, and Taiwan, with drum assemblies and motor windings drawing from Polish and Italian metals processing. Single-source vulnerability in semiconductor-grade microcontrollers creates exposure, while distribution runs through manufacturer-direct commercial fleets and third-party rural wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European washing machines rests on heat-pump technology maturation and subscription-model penetration shifting revenue toward service-based recurrence.
For Market Incumbents: Acquire captive heat-pump system integration capabilities to preempt technician training bottlenecks constraining after-sales capacity. Consolidate position by pruning sub-A-rated portfolios ahead of Ecodesign threshold tightening and deepening backward integration into electronic control module supply to offset East Asian foundry concentration risk. For New Entrants and Emerging Players: EU F-Gas Regulation in Southern Europe opens a window for hydrocarbon heat-pump specialist entry where incumbent retrofit costs are steepest. Target Polish and Romanian residential penetration with entry-tier certified units distributed through third-party wholesale networks, leveraging price sensitivity gaps against established premium positioning. For Investors and Strategic Acquirers: Roll-up economics work for regional commercial laundry fleet operators because municipal water tariffs are tightening replacement cycles into predictable contract revenue. Five-to-ten-year viability favors targets with predictive maintenance API development and hospitality-sector installed base. Watch Ecodesign Working Plan interoperability mandate timing as inflection signal for connected-device platform value.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump R&D Partnership | Accelerates compliant washer-dryer architectures ahead of F-Gas refrigerant restrictions. |
| Subscription Model Launch | Captures Dutch and Swedish property management demand for predictive maintenance APIs. |
| Backward Integration into Motors | Secures margin control against copper winding cost volatility in drum assemblies. |
| CE Marking Fast-Track | Compresses cybersecurity validation timelines for Wi-Fi-enabled RED directive compliance. |
| Eastern European Distribution Expansion | Accesses Polish and Romanian volume potential through third-party wholesale partnerships. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance OEM product managers, commercial laundry fleet operators, and electronics component procurement leads with secondary validation against EU Ecodesign directive filings, CE marking registration databases, and national energy rebate scheme disclosures. Bottom-up unit shipment modeling triangulated against top-down market value reconstruction.
Comparable historical periods anchored the projection horizon to identify replacement cycle acceleration patterns and regulatory compliance cost trajectories. Segmentation dimensions spanned product architecture, end-user type, efficiency certification tier, and distribution channel structure, with CAGRs derived from fitted growth curves incorporating rebate scheme uptake rates and heat-pump technology diffusion parameters.
Revisions become necessary when EU Ecodesign threshold schedules accelerate or East Asian semiconductor supply disruptions materialize beyond modeled contingency bands. Forecasts reflect assumptions on regulatory enforcement consistency and commodity price stabilization. A model refresh is warranted upon material change in F-Gas Regulation implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Argentina Home Appliances Market
Home Appliances
Israel Home Needs Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Egypt Home Appliances Market
Home Appliances
Brazil Home Appliances Market
Home Appliances
Global Residential Microwave Oven Market
Home Appliances
France Household Appliances Market
Home Appliances
Electrical Appliances Market
Home Appliances
Saudi Arabia Small Home Appliances Market
Home Appliances
South Korea Home Appliances Market
Home Appliances
Latin America Washing Machine Market
Home Appliances
GCC Small Home Appliances Market
Home Appliances
North America Home Heating Appliances Market
Home Appliances
UK Household Appliances Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
China Home Appliances Market