
 UK Household Appliances Market | 2026-2036
UK Household Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
UK Household Appliances Market Insights
Aftermarket service revenue is tilting toward connected-device diagnostics and predictive maintenance contracts. Samsung Electronics leverages its SmartThings ecosystem to lock in recurring software-subscription flows alongside hardware sales. Dyson sustains premium positioning through in-house motor technology and direct-to-consumer channel control. BSH Home Appliances Group anchors its UK presence with localized production and retailer-exclusive model lines.
UK household appliances encompass electrically powered machines for domestic food preservation, fabric care, cooking, and cleaning, typically rated between 220-240V at 50Hz for UK grid compatibility and subject to BEIS energy efficiency index thresholds. Refrigerators and washing machines occupy the largest installed base, though margin pools are migrating toward smart appliances where firmware updates and energy optimization algorithms create ongoing revenue attachment. Energy-efficient technology segments face step-change demand from EPC-linked landlord compliance deadlines, while hybrid systems that combine traditional heating with heat-pump elements are gaining specification in new-build developments.
BEIS enforces minimum energy performance standards and rescaling of EU-derived energy labels, while the Environment Agency regulates F-gas phase-down in refrigeration equipment, and the UKCA marking regime governs post-Brexit product conformity assessment. These frameworks compel manufacturers to redesign compressor architectures and refrigerant circuits, raising compliance costs for import-dependent suppliers while rewarding domestic R&D investment. Stakeholders must decide whether to absorb certification overhead or cede share to vertically integrated rivals with captive test facilities.
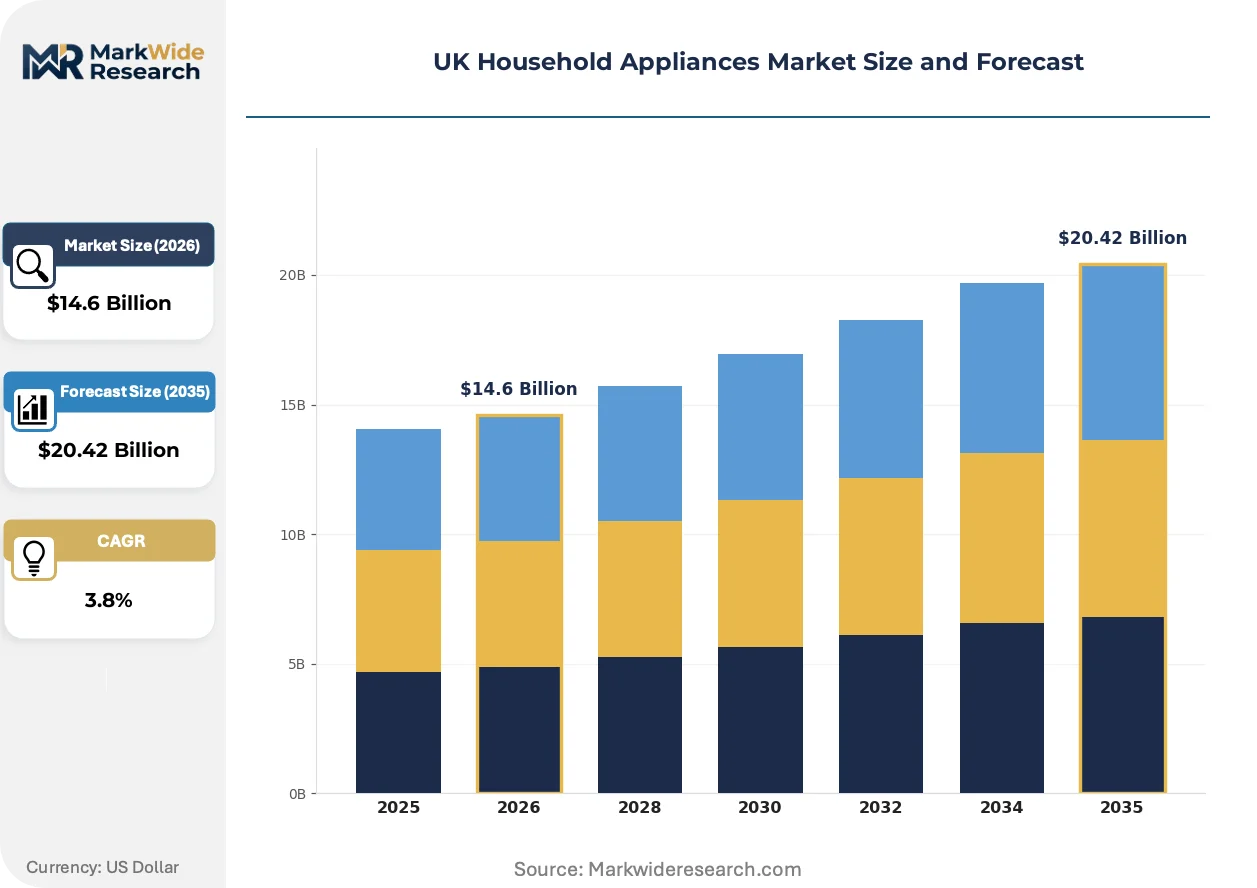
Market Dynamics
BEIS energy labelling rescaling and F-gas phase-down mandates are forcing compressor architecture redesigns across refrigeration and laundry equipment, raising compliance costs for import-dependent suppliers while rewarding domestic R&D investment.
Growth Catalysts
- EPC-linked landlord compliance:Minimum Energy Performance Certificate thresholds compel rental housing operators to replace inefficient refrigeration and heating appliances ahead of regulatory deadlines.
- Heat-pump technology:BEIS Net Zero Strategy targets are accelerating specification of heat-pump-based laundry systems in new-build developments and retrofit projects.
- Greater London housing density:Concentrated buy-to-let ownership in the capital sustains replacement volume for mid-life appliance refresh cycles.
Market Restraints
- Refrigerant input cost volatility:Lower-GWP refrigerant transitions under Environment Agency F-gas regulations expose manufacturers to supply tightness in R-290 and R-600a alternatives.
- UKCA certification friction:Post-Brexit conformity assessment divergence from CE marking creates dual-testing overhead for EU-imported component suppliers.
- Heat-pump technical limitation:Extended drying cycles and higher unit costs versus resistive heating constrain tenant acceptance in cost-sensitive social housing.
Strategic Opportunities
- Smart appliance firmware monetization:Energy optimization algorithms and predictive maintenance subscriptions create recurring revenue attachment beyond hardware margins.
- South East buy-to-let expansion:Commuter-belt rental growth outside London proper offers underpenetrated replacement demand for premium-specification appliance portfolios.
- Connected-device diagnostics channel:Direct-to-tenant service apps bypass traditional retailer warranty chains and capture aftermarket service revenue.
Industry Challenges
- Heat-pump engineering talent scarcity:Compressor thermodynamics and refrigerant circuit design skills concentrate among a limited pool of specialist engineers.
- UKCA timeline compression:Parallel testing against retained EU law and new British standards strains certification laboratory capacity.
- Legacy resistive-heating integration:Hybrid system control logic must reconcile incompatible firmware architectures between traditional and heat-pump heating elements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Household Appliances Market |
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Washing Machines, Microwaves, Dishwashers Technology: Smart Appliances, Energy-Efficient, Traditional, Hybrid End User: Residential, Commercial, Rentals, Institutional Distribution Channel: Online, Offline, Direct Sales, Retail Chains |
| Companies Covered | Samsung Electronics, Whirlpool Corporation, Electrolux Group, BSH Home Appliances Group, LG Electronics, Haier Smart Home, Miele & Cie. KG, Dyson, Arçelik (Beko), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Household Appliances Market Trends and Innovations
Appliance functionality is pivoting from standalone hardware toward software-enabled service platforms, with firmware update cycles and energy management algorithms becoming primary differentiation vectors.
Heat-pump drying technology is migrating from premium standalone units toward integrated washer-dryer combinations and built-in kitchen configurations. Social housing providers and build-to-rent developers are specifying these systems to meet SAP 10 compliance requirements. The technology is migrating from niche eco-segments toward standard mid-market specifications as BEIS efficiency thresholds tighten.
Environment Agency F-gas regulations are compressing allowable Global Warming Potential ratings for domestic refrigeration equipment on a phased schedule. Manufacturers must redesign compressor architectures and refrigerant circuits to accommodate propane and isobutane alternatives. Cold-chain equipment suppliers serving the UK market are accelerating in-house testing facility investment to manage UKCA marking divergence from EU procedures.
Tenant procurement preferences are fragmenting across direct-to-consumer subscription models and landlord-bulk-procurement frameworks. Build-to-rent operators are unbundling appliance selection from property management, allowing residents to customize specifications through digital portals. This pattern concentrates in Greater London and Manchester build-to-rent schemes where tenant retention metrics drive amenity differentiation.
UK Household Appliances Market Segmentation
UK household appliances segment along four critical dimensions that determine service intensity, margin architecture, and procurement channel design. Product type and technology classifications drive after-sales revenue attachment, while end-user and distribution splits dictate warranty structures and replacement cycle timing.
Product Type:
After-sales-service intensity varies sharply across product categories, with refrigeration and fabric care equipment generating the highest recurring maintenance revenue streams.
- Refrigerators:Compression systems and refrigerant circuits require specialized technician dispatch under F-gas regulations. Demand concentrates in Greater London rental stock where EPC compliance deadlines force accelerated replacement of pre-2010 units.
- Washing Machines:Drum assemblies, motor controllers, and water inlet systems sustain parts-and-labor revenue across 7-10 year lifecycles. South East buy-to-let operators are standardizing on mid-tier models with extended warranty bundles to reduce tenant turnover costs.
- Microwaves:Magnetron replacement economics rarely justify service calls; disposal-driven replacement dominates this segment.
- Dishwashers:Pump and seal failures generate moderate service revenue, though lower installed base limits aftermarket scale compared to refrigeration.
By volume, Washing Machines leads. By growth pace, Refrigerators is ahead.
Technology:
Margin pools migrate toward firmware-enabled categories where software subscriptions supplement hardware economics.
- Smart Appliances:WiFi-connected refrigerators and washing machines support predictive maintenance algorithms and energy optimization services.
- Energy-Efficient:Heat-pump dryers and inverter-compressor refrigeration command specification premiums in new-build developments targeting SAP 10 compliance.
- Traditional:Resistive-heating appliances face margin compression as BEIS efficiency thresholds tighten.
- Hybrid:Dual-mode systems combining conventional and heat-pump elements balance tenant acceptance with compliance requirements.
By volume, Traditional leads. By expansion trajectory, Smart Appliances is climbing the fastest.
End User:
Procurement authority fragmentation creates divergent channel strategies across customer types.
- Residential:Direct-to-consumer purchases emphasize brand reputation and retailer financing terms.
- Commercial:Hospitality and foodservice operators prioritize total-cost-of-ownership calculations and rapid-response service SLAs.
- Rentals:Build-to-rent and social housing providers drive bulk procurement with standardized specifications and centralized asset management.
- Institutional:Universities and NHS facilities operate on capital-budget cycles with extended tender processes.
By volume, Residential leads. By contract value concentration, Rentals is gaining share fastest.
Distribution Channel:
Channel economics determine warranty fulfillment responsibility and customer data ownership.
- Online:E-commerce platforms capture price-sensitive demand with drop-ship fulfillment and third-party installation networks.
- Offline:Independent retailers maintain service relationships that sustain parts-and-labor revenue attachment.
- Direct Sales:Manufacturer-controlled channels capture customer data for subscription service monetization.
- Retail Chains:Currys and John Lewis negotiate exclusive model lines with volume-based rebate structures.
By volume, Retail Chains leads. By margin expansion, Direct Sales is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic appliance manufacturing clusters concentrate in Germany, China, South Korea, and Poland, with UK demand served primarily through import channels and localized assembly operations. Regulatory divergence post-Brexit is reshaping supplier certification strategies across these source markets.
Germany
Engineering-intensive refrigeration and laundry equipment originates from Baden-Württemberg and Bavaria manufacturing corridors. The KBA and federal environment ministry enforce F-gas phase-down schedules that UK importers must mirror under parallel Environment Agency rules. Stuttgart-area compressor specialists are expanding UKCA testing capacity to maintain cross-channel appliance flows.
China
Cost-optimized component fabrication and finished goods assembly dominate Guangdong and Zhejiang industrial zones. MIIT energy efficiency standards and GB certification requirements create baseline engineering that UK-bound products must augment with BEIS-specific labelling. Shenzhen-connected appliance makers are establishing London-based compliance liaison offices.
South Korea
Smart appliance firmware development and display panel integration concentrate in Seoul Capital Area and Gyeonggi-do research parks. METI-aligned efficiency benchmarks inform product architectures that UK distributors specify for premium rental housing segments. Suwon-based electronics conglomerates leverage existing CE testing infrastructure for dual UKCA conformity assessment.
Poland
White goods final assembly for European distribution clusters in Lower Silesia and Greater Poland voivodeships. EU F-Gas Regulation compliance provides partial alignment with UK Environment Agency requirements, though post-Brexit divergence is accelerating local UKCA certification investment. Wrocław-area facilities are adding British-standard refrigerant handling protocols.
Italy
Specialized cooking appliance and built-in refrigeration manufacturing concentrates in Lombardy and Veneto industrial districts. Ecodesign Directive implementation experience transfers partially to UK BEIS threshold compliance, though cooker hood energy rescaling creates distinct testing obligations. Milan-headquartered design houses are reconfiguring product lines for split regulatory regimes.
UK Household Appliances Market Competitive Landscape
Vertically integrated conglomerates and specialist premium brands split the market between scale-driven cost optimization and technology-led margin capture. Samsung Electronics and LG Electronics anchor the volume tier through integrated component supply chains and firmware platform ecosystems. Whirlpool Corporation and Electrolux Group occupy mid-market positions balancing manufacturing scale with regional brand equity. Strategic moves center on heat-pump technology licensing partnerships and direct-to-consumer channel bypass of traditional retail intermediaries.
Among Asia-Pacific headquartered conglomerates, Samsung Electronics exemplifies the connected-appliance archetype through ecosystem lock-in strategies, while LG Electronics occupies a parallel position emphasizing display and motor technology integration. European specialists Miele & Cie. KG and Dyson represent the engineering-premium tier, with the former emphasizing durability-rated mechanical systems and the latter leveraging proprietary motor and air-moving intellectual property. BSH Home Appliances Group anchors the regional integrated manufacturer category through localized production and retailer-exclusive model differentiation.
| Leading Market Players |
|---|
| Samsung Electronics |
| Whirlpool Corporation |
| Electrolux Group |
| BSH Home Appliances Group |
| LG Electronics |
| Haier Smart Home |
| Miele & Cie. KG |
| Dyson |
| Arçelik (Beko) |
| Others |
Pricing and Supply Chain Analysis
UKCA certification friction determines both pricing tier spreads and supply chain shape, compressing margins for EU-imported components while rewarding domestic testing facility investment with premium positioning power.
Pricing Analysis
BEIS energy labelling rescaling dictates the pricing tier structure across the UK household appliances market. Three-tier pricing structure across premium, standard, and economy levels separates connected firmware-enabled models from basic compliance-grade units and entry-level imports. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because UKCA dual-testing overhead falls disproportionately on smaller import-dependent suppliers. Social housing procurement teams exhibit highest price sensitivity, while build-to-rent operators in Greater London demonstrate lowest sensitivity due to tenant retention value capture.
Supply Chain Analysis
Electronics manufacturing services in Poland, China, and South Korea hold contract assembly capacity for UK-bound appliance production. Component sourcing draws from German compressor specialists, Chinese control board fabricators, and South Korean display panel integrators. Raw material dependencies include copper winding stock, rare-earth magnet materials, and lower-GWP refrigerant alternatives. Single-source vulnerability concentrates in heat-pump compressor thermodynamics expertise. Distribution runs through Rotterdam port consolidation followed by Midlands distribution hubs serving retailer chains and direct-to-consumer fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK household appliances market functions as a defensive-moat story where regulatory entrenchment through UKCA certification and BEIS efficiency compliance creates sustainable barriers against import-dependent competitors.
For Market Incumbents: Entrench market position through captive UKCA testing facility investment and heat-pump engineering talent acquisition. Absorb certification overhead to force share consolidation among import-dependent rivals unable to sustain dual-testing costs. Deepen backward integration into compressor architectures to control refrigerant circuit redesign timelines against Environment Agency F-gas phase-down acceleration.
For New Entrants and Emerging Players: South East commuter-belt buy-to-let expansion outside Greater London proper offers underpenetrated replacement demand with less incumbent saturation. Target mid-tier smart appliance specifications for social housing retrofit programs where EPC compliance deadlines concentrate procurement volume. Pursue direct-to-tenant service app deployment to bypass established retailer warranty chains and capture aftermarket revenue attachment.
For Investors and Strategic Acquirers: Specialist firmware developers with predictive maintenance algorithm capabilities represent the most attractive acquisition target archetype for smart appliance monetization exposure. Long-term viability hinges on software subscription revenue attachment displacing hardware margin dependence across the analysis window. Monitor heat-pump drying cycle performance acceptance rates in cost-sensitive social housing deployments as inflection indicator for technology migration pace.
| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Testing Facility Investment | Captive certification capacity locks out import-dependent competitors facing dual-testing overhead. |
| Heat-Pump Technology Licensing | Compressor thermodynamics IP partnerships accelerate SAP 10 compliance product pipelines. |
| Direct-to-Consumer Channel Expansion | Manufacturer-controlled data capture enables predictive maintenance subscription monetization. |
| Smart Appliance Firmware Platform | Energy optimization algorithm deployment creates recurring revenue beyond hardware margins. |
| South East Distribution Hub Expansion | Commuter-belt logistics proximity captures buy-to-let replacement cycle concentration. |
Research Methodology
Initial hypotheses were tested against primary input from appliance manufacturer product strategy directors, BEIS regulatory compliance officers, build-to-rent asset managers, and independent retailer service heads and refined through secondary validation against customs import records, BEIS energy label registration databases, Environment Agency F-gas permitting data, and retailer rebate disclosure filings. Bottom-up shipment volume estimates triangulated against top-down housing stock replacement cycle modeling.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user procurement authority, and distribution channel control structure. CAGRs were derived from replacement cycle timing analysis overlaid with regulatory deadline clustering effects. Forecast inputs incorporated EPC compliance deadline phasing and heat-pump technology cost curve assumptions.
Practitioners should monitor UKCA certification timeline compression and heat-pump tenant acceptance metrics for early signals of supply constraint or demand inflection. Forecasts reflect assumptions regarding regulatory enforcement continuity and refrigerant alternative supply scaling. Quarterly review of build-to-rent procurement tender volumes and social housing retrofit program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
Asia-Pacific Small Home Appliances Market
Home Appliances
Connected Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
Global Residential Water Heaters Market
Home Appliances
High-End French Door Refrigerator Market
Home Appliances
North America Built-In Home Appliances Market
Home Appliances
Oman Small Home Appliances Market
Home Appliances
Built-In Appliance Market
Home Appliances
India Small Home Appliances Market
Home Appliances
China Small Home Appliances Market
Home Appliances
Americas Range Hood Market
Home Appliances
Europe Washing Machine Market
Home Appliances
Japan Household Appliance Market
Home Appliances
Germany Household Side by Side Refrigerator Market
Home Appliances
GCC Major Home Appliances Market
Home Appliances
Chile Home Appliances Market