
 Saudi Arabia Infrastructure Sector Market | 2026-2036
Saudi Arabia Infrastructure Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Infrastructure Sector Market Analytics
Modular construction and digital twin integration is rewriting project delivery timelines across the Saudi Arabia Infrastructure Sector. Almabani leverages prefabrication capabilities to compress building schedules for hospitality and healthcare assets. Saudi Binladin Group anchors mega-project credibility through decades of mosque, airport, and highway execution at scale. Bechtel competes on complex energy and transport infrastructure where technical risk transfer governs contract awards.
The Saudi Arabia Infrastructure Sector encompasses the planning, engineering, procurement, and construction of physical systems including transport networks, water and power utilities, commercial and residential buildings, and digital telecommunications backbone, typically executed through EPC or PPP contract models with design life specifications exceeding fifty years for major civil structures. Transportation and Utilities project types command the dominant share of public budget allocation under Vision 2030 giga-project mandates. Smart Grids and Construction Automation within the Technology segment attract the fastest-growing private investment as developers pursue operational efficiency and labor productivity gains.
MOHAP enforces building safety and environmental health standards that shape material selection and contractor qualification across healthcare and residential developments. SFDA regulates construction material imports and product certifications, creating compliance barriers for unapproved suppliers. The Saudi Building Code and SASO technical regulations mandate seismic resilience and energy efficiency parameters that elevate engineering costs. Stakeholders must monitor how NEOM and Qiddiya project procurement rules evolve local content requirements and joint venture structures.
Market Dynamics
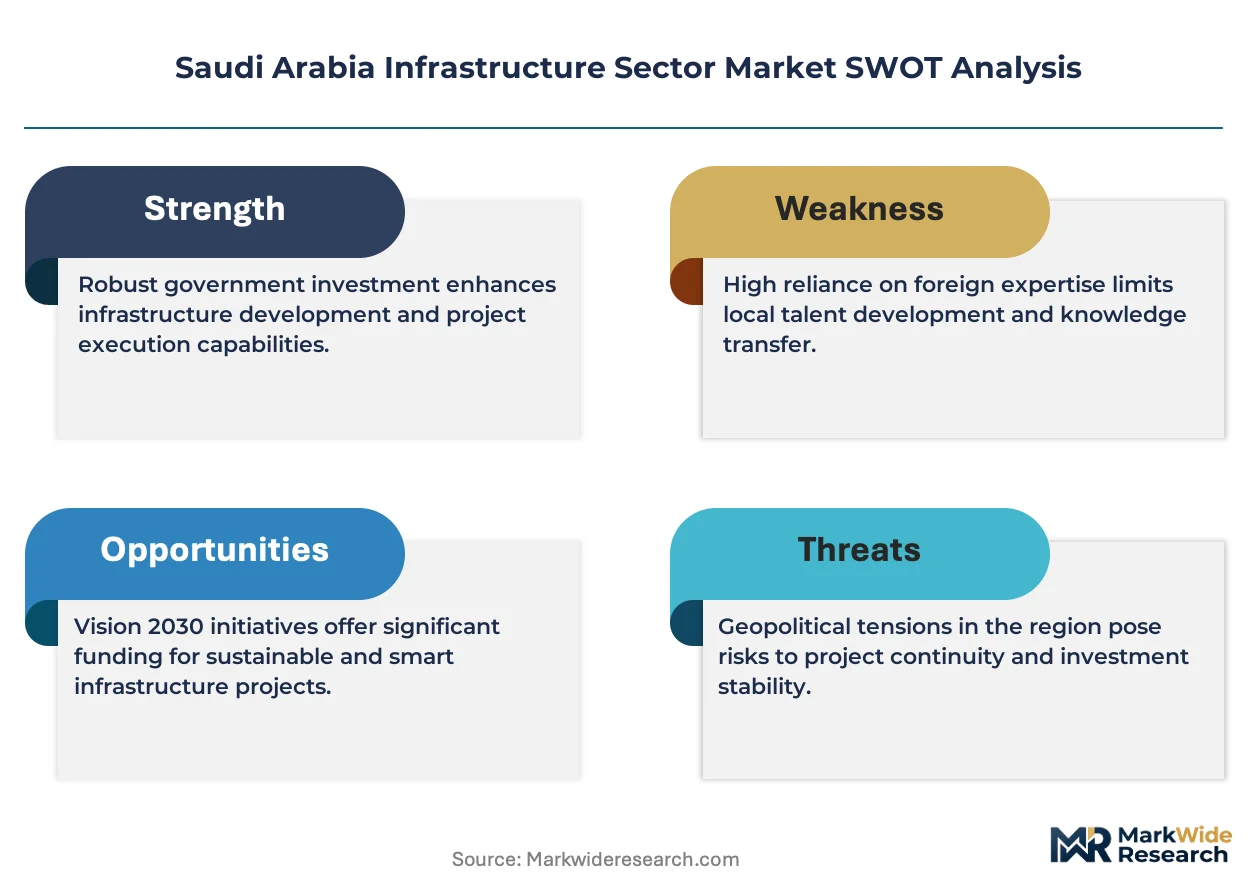
Vision 2030 giga-projects are compressing traditional project delivery cycles while MOHAP and SFDA compliance layers add regulatory friction that reshapes contractor qualification and material sourcing decisions.
Growth Catalysts
- NEOM procurement mandates:Local content requirements and joint venture structures channel capital toward domestic engineering capacity and workforce development.
- Red Sea coastal zone acceleration:Qiddiya and giga-project clusters concentrate demand for transport corridors, utility networks, and hospitality infrastructure.
- Modular construction adoption:Prefabrication capabilities compress building schedules for healthcare and hospitality assets while reducing on-site labor dependency.
Market Restraints
- Steel and cement input volatility:Construction material import regulations under SASO create price uncertainty and supply timing risks for contractors.
- Seismic engineering cost elevation:Saudi Building Code mandates for seismic resilience and energy efficiency parameters inflate structural engineering expenditures.
- Specialized contractor concentration:Limited domestic EPC firms capable of complex energy and transport infrastructure create bottleneck risk in high-technical-risk segments.
Strategic Opportunities
- Digital twin convergence:Integration of IoT sensor networks with BIM platforms enables predictive maintenance contracts for utility operators.
- Smart grid deployment:Operational efficiency mandates from the Saudi Energy Efficiency Center accelerate private investment in automated distribution systems.
- Western Province logistics:Underpenetrated industrial zones near Jeddah and Yanbu offer first-mover positioning for modular manufacturing facilities.
Industry Challenges
- BIM and digital engineering skill scarcity:Shortage of technicians capable of operating integrated design platforms slows technology adoption timelines.
- Multi-regulator compliance sequencing:SFDA material certifications, MOHAP safety clearances, and SASO technical approvals create overlapping timeline risks.
- Legacy utility integration:Grid interconnection requirements for new renewable assets impose technical complexity on independent power producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Infrastructure Sector Market |
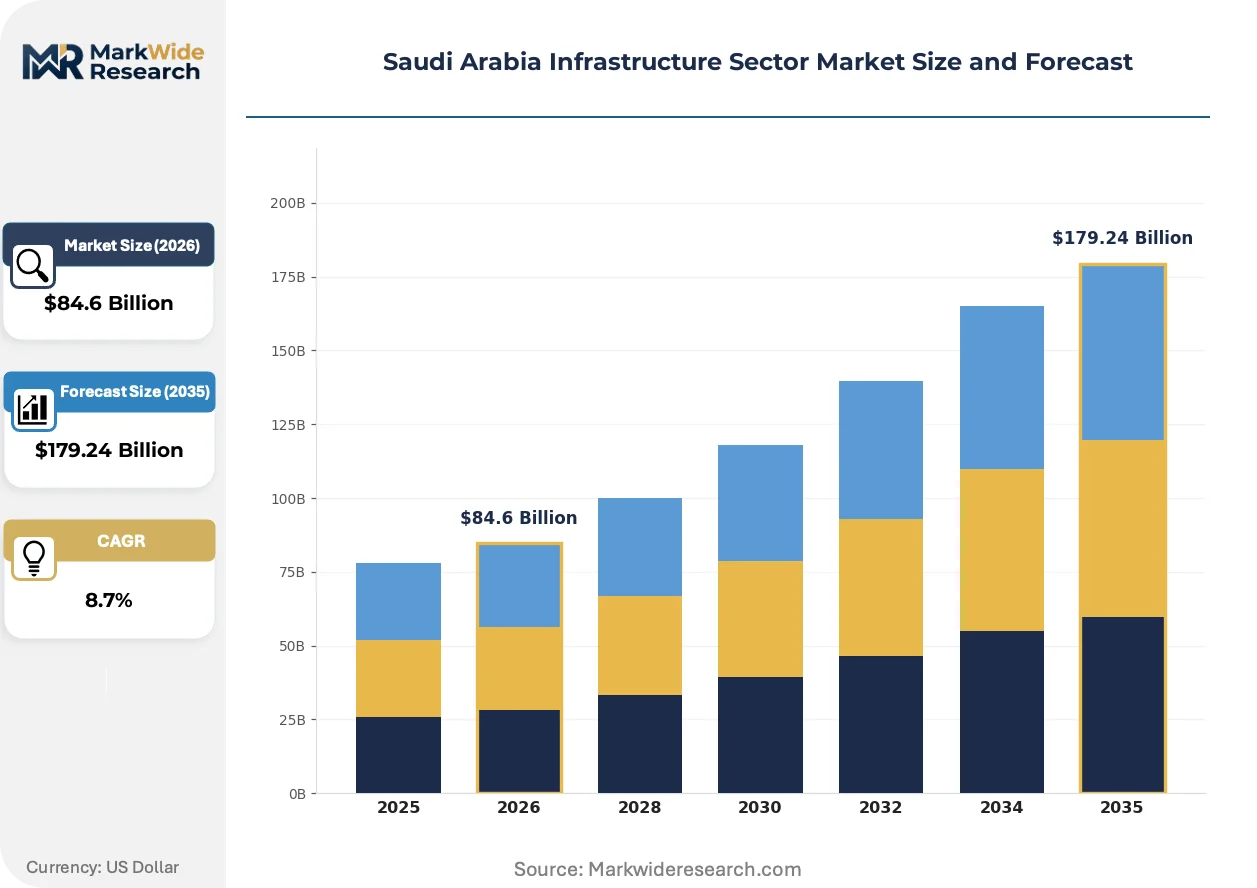
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $179.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Transportation, Utilities, Buildings, Telecommunications End User: Government, Private Sector, Contractors, Developers Funding Source: Public Financing, Private Investment, Foreign Aid, Joint Ventures Technology: Smart Grids, IoT Solutions, Renewable Energy, Construction Automation |
| Companies Covered | Almabani, Alfanar Construction, Saudi Binladin Group, Al-Yamama Group, WeBuild, Nesma & Partners Contracting, Fluor Corporation, China Harbor Engineering Company (CHEC), Bechtel, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Infrastructure Sector Market Evolving Landscape
Digital infrastructure layers are penetrating physical asset lifecycles from design through operations, while regulatory tightening around material traceability and energy performance rewrites procurement specifications.
Building Information Modeling integrated with real-time sensor feeds is virtualizing asset commissioning and handover processes. Major hospital and airport developers now require digital twin deliverables as contract milestones. This capability compression is eliminating traditional paper-based inspection workflows and enabling remote facility management.
SFDA construction material import regulations now mandate batch-level traceability documentation for structural steel and cement products. Industrial consequence includes elevated documentation burden for international suppliers and preference shifts toward SASO-certified domestic manufacturers. Healthcare and residential segments are responding by pre-qualifying suppliers with established Saudi certification histories.
Asset-as-a-service contracting is displacing traditional lump-sum EPC awards in select utility segments. Independent water and power producers now seek operational partnerships spanning twenty-five year concessions rather than pure construction handoffs. This pattern concentrates most visibly in desalination and renewable energy clusters where operational risk transfer governs financing structures.
Saudi Arabia Infrastructure Sector Market Segmentation
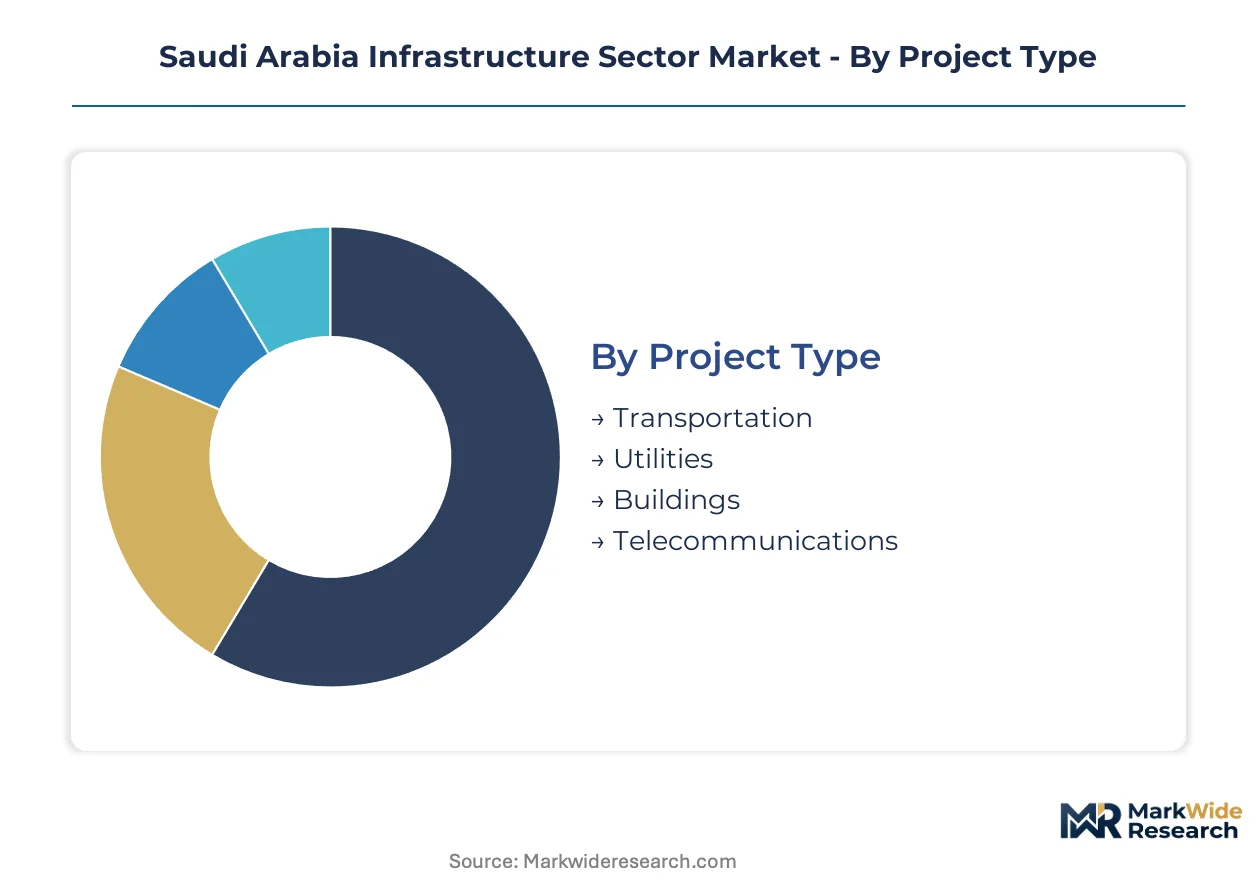
Vision 2030 giga-projects fragment procurement patterns across multiple buyer types and funding structures. Contractors must navigate distinct technical specifications, compliance timelines, and risk allocation models that vary sharply by segment.
Project Type:
Mature civil engineering disciplines dominate capital deployment, while emerging digital infrastructure layers reshape project economics.
- Transportation:Highway corridors, rail networks, and airport expansions absorb the largest public budget allocations under Vision 2030. Riyadh metro extensions and Red Sea coastal connectivity projects concentrate demand for steel-intensive bridge and tunnel engineering.
- Utilities:Water desalination, power generation, and wastewater treatment assets carry fifty-year design life specifications. NEOM and Qiddiya clusters drive demand for integrated utility corridors that bundle electricity, water, and digital distribution.
- Buildings:Healthcare, hospitality, and residential assets execute through EPC contracts with MOHAP safety mandates.
- Telecommunications:5G backbone and fiber optic networks penetrate giga-project master plans as embedded infrastructure.
Transportation handles the majority of throughput; Utilities is gaining share fastest as renewable integration accelerates.
End User:
Public procurement concentration contrasts with emerging private delivery models that transfer operational risk.
- Government:Ministries of Transport, Energy, and Health deploy sovereign capital through traditional EPC awards. MOF budget cycles and SAMA financing guarantees govern project scheduling and contractor qualification.
- Private Sector:Independent power producers and water developers pursue BOO and BOOT concessions spanning twenty-five years. PIF-backed giga-project vehicles now dominate private infrastructure origination.
- Contractors:Tier-1 EPC firms self-perform on balance sheet or syndicate risk through joint venture structures.
- Developers:Mixed-use master planners bundle infrastructure costs into land value capture mechanisms.
Government retains the dominant procurement volume; Private Sector is climbing the fastest as asset-as-a-service contracting expands.
Funding Source:
Sovereign balance sheet reliance is diluting as project finance structures attract institutional capital.
- Public Financing:Ministry of Finance appropriations and PIF direct allocations fund strategic corridor and utility backbone construction. SAMA local bond issuance and international sukuk programs provide long-dated riyal and dollar funding.
- Private Investment:Pension funds, infrastructure funds, and regional banks deploy capital into operational concessions with contracted revenue streams.
- Foreign Aid:Multilateral development bank participation appears selectively in water and renewable energy clusters.
- Joint Ventures:Local content mandates force technology transfer partnerships between international contractors and Saudi engineering firms.
Public Financing carries the heaviest deployment; Private Investment is expanding most quickly as regulatory frameworks mature.
Technology:
Operational efficiency mandates are accelerating digital infrastructure penetration across physical asset lifecycles.
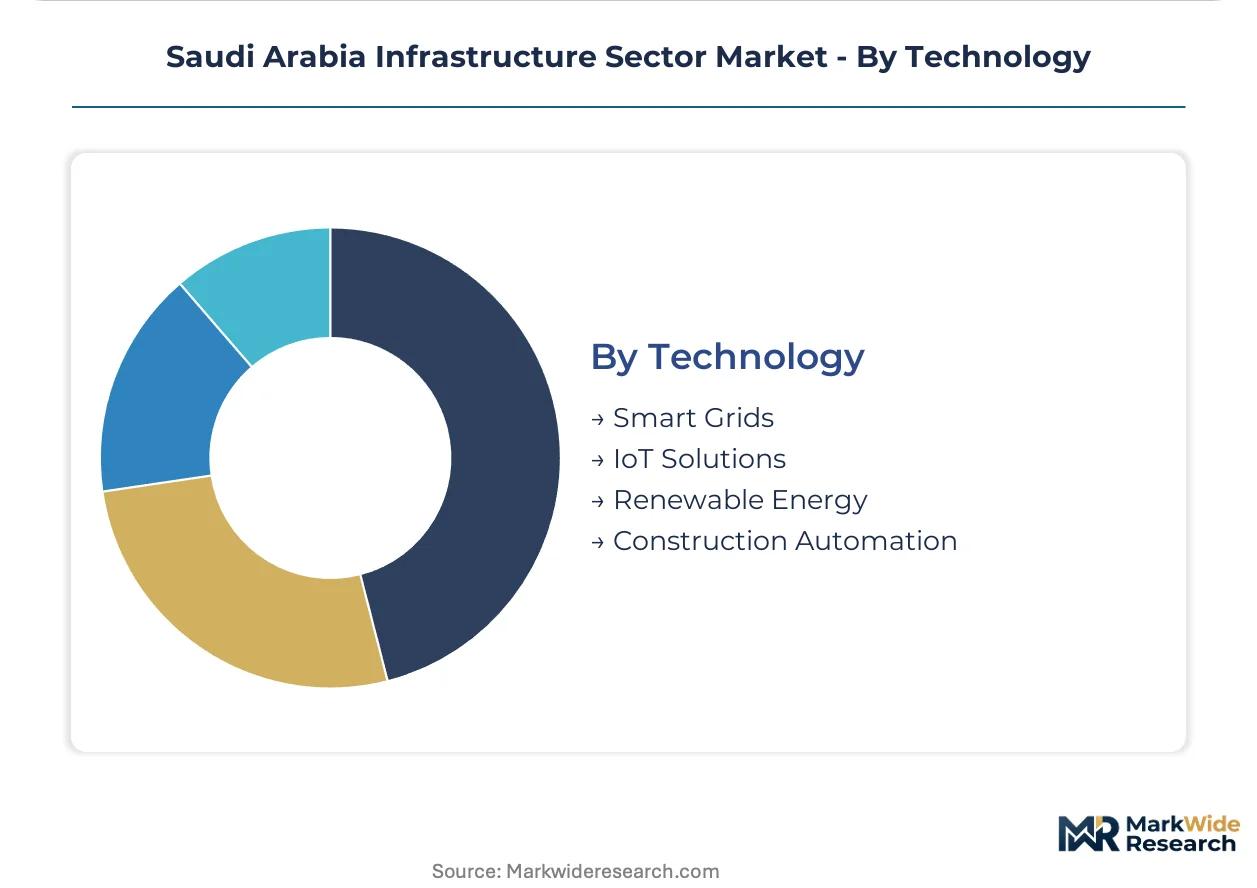
- Smart Grids:Automated distribution systems with real-time load balancing and predictive fault detection. Saudi Energy Efficiency Center mandates accelerate deployment across Riyadh and Jeddah utility networks.
- IoT Solutions:Sensor networks embedded in bridges, tunnels, and buildings enable condition-based maintenance contracts. Digital twin deliverables now appear as mandatory handover milestones for hospital and airport developers.
- Renewable Energy:Solar PV and wind generation assets require grid interconnection and storage co-location.
- Construction Automation:Prefabrication, robotics, and BIM-integrated project controls compress delivery schedules.
Smart Grids absorbs the largest technology capital allocation; IoT Solutions is the fastest mover on share as BIM mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's infrastructure sector draws capital from Gulf sovereign wealth funds and Asian development finance into Red Sea coastal megaprojects. Turkish and Italian contractors supply specialized engineering for transport corridors while Chinese EPC firms dominate utility-scale renewable installations.
Riyadh
Riyadh metro extensions and Qiddiya entertainment infrastructure absorb the largest capital commitments under Vision 2030. MOHAP building codes enforce seismic resilience standards for healthcare and hospitality assets. King Abdullah Financial District anchors demand for smart building integration and district cooling networks.
Eastern Province
Jubail Industrial City and Ras Al-Khair drive demand for integrated utility corridors spanning power, water, and digital distribution. SASO technical regulations mandate batch-level traceability for structural steel imports. Aramco-backed energy clusters require fifty-year design life specifications for desalination and petrochemical infrastructure.
Western Region
Jeddah Islamic Port expansion and Makkah pilgrimage infrastructure concentrate transport engineering demand. SFDA material certifications create compliance barriers for cement and steel suppliers without established Saudi approval histories. King Abdulaziz International Airport modernization mandates digital twin deliverables as contract milestones.
NEOM Northwest
THE LINE and Oxagon industrial city procurement channels capital toward modular construction and renewable energy integration. NEOM procurement mandates enforce local content requirements and joint venture structures for international contractors. Trojena and Sindalah island developments compress traditional delivery cycles through prefabrication adoption.
Saudi Arabia Infrastructure Sector Market Competitive Landscape
On the supply side, the industry is tiered between sovereign-backed domestic conglomerates, international EPC specialists, and emerging modular fabricators. Saudi Binladin Group and Al-Yamama Group anchor the domestic tier through decades of mosque, airport, and highway execution. International contractors compete on complex energy and transport infrastructure where technical risk transfer governs contract awards. Dominant competitive moves include joint venture formation to satisfy local content mandates and backward integration into prefabrication capabilities.
Among domestic heavy civil specialists, Saudi Binladin Group exemplifies the scale-driven archetype through legacy execution credibility across giga-project portfolios. Almabani occupies a position within the modular fabrication tier, representing prefabrication capabilities that compress building schedules for hospitality and healthcare assets. Bechtel sits within the international risk-transfer tier, anchoring complex energy and transport infrastructure where technical specifications exceed domestic engineering capacity.
| Leading Market Players |
|---|
| Almabani |
| Alfanar Construction |
| Saudi Binladin Group |
| Al-Yamama Group |
| WeBuild |
| Nesma & Partners Contracting |
| Fluor Corporation |
| China Harbor Engineering Company (CHEC) |
| Bechtel |
| Others |
Value Network & Pricing Analysis
Steel mill undercapacity in the Eastern Province is tightening rebar availability and pushing contractors toward long-term offtake agreements with SASO-certified domestic producers. This utilization squeeze simultaneously elevates input costs and fragments procurement leverage across tiered EPC firms.
Pricing Analysis
Project-based pricing gaps separate conventional EPC awards from digital-twin-enabled delivery contracts. Three-tier pricing structure across premium, standard, and economy levels tracks contractor certification tier and BIM integration depth. Cost compression in standard-tier civil packages is intensifying because international steel volatility feeds through SASO import documentation delays. Government ministry procurement shows lowest price sensitivity; speculative private developers exhibit highest.
Supply Chain Analysis
Prefabrication capacity concentrates with Almabani and Nesma & Partners Contracting in Riyadh industrial zones. Raw material flows draw from China, Turkey, and UAE for structural steel and cement clinker. Single-source vulnerability runs through Red Sea shipping lanes where Jeddah Islamic Port congestion disrupts just-in-time delivery schedules. Distribution runs through contractor-controlled logistics networks bypassing traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vision 2030 giga-project acceleration is disrupting traditional EPC contracting as NEOM procurement mandates force joint venture structures and technology transfer partnerships.
For Market Incumbents: Harden prefabrication capabilities through backward integration into modular manufacturing facilities in Riyadh and Yanbu industrial zones. Secure SASO certification pipelines for structural steel suppliers to preempt SFDA documentation delays that threaten project schedules.
For New Entrants and Emerging Players: Western Province logistics corridors near Jeddah offer underpenetrated positioning for construction automation equipment leasing services. Target independent power producer segments with asset-as-a-service operational partnerships rather than pure EPC competition.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across modular construction sub-segments as prefabrication compresses labor dependency. Acquisition targets should display established MOHAP safety clearance histories and NEOM joint venture credentials. Watch NEOM procurement rule evolution for local content threshold adjustments as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | NEOM local content mandates force technology transfer partnerships with domestic engineering firms. |
| Backward Integration | In-house prefabrication capabilities compress delivery schedules for healthcare and hospitality assets. |
| Digital Twin Certification | MOHAP and airport developers now mandate BIM-integrated deliverables as contract milestones. |
| SASO Certification Investment | Batch-level traceability requirements elevate preference toward approved domestic steel and cement suppliers. |
| Modular Manufacturing Scale-Up | Trojena and Sindalah island developments accelerate demand for offsite construction capacity. |
Research Methodology
Operator-level perspectives from EPC project directors, MOHAP compliance officers, SFDA certification specialists, and PIF procurement managers anchored the qualitative base. Secondary validation drew from SAMA bond issuance disclosures, SASO technical regulation updates, NEOM procurement bulletins, and contractor financial filings. Bottom-up project pipeline aggregation triangulated against top-down sovereign budget allocation analysis.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled include project type, end user archetype, funding source structure, and technology integration tier. CAGRs derived from weighted capacity deployment curves and capital commitment trajectories. Forecast inputs incorporated Vision 2030 giga-project execution timelines and regulatory compliance cost evolution.
Practitioners should monitor steel import documentation processing times and NEOM local content threshold adjustments for early signals. Forecasts reflect assumptions regarding sustained sovereign capital deployment and modular construction adoption curves. Quarterly review of contractor qualification backlogs and SFDA certification approval rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
United Kingdom Data Center Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
El Salvador Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
North America Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
Oman Construction Market
Building Construction
UAE Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
India Construction Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Saudi Arabia Construction Market