
 Prefabricated Buildings Market | 2026-2036
Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Buildings Market Outlook
Project delivery channels for large-scale developments is tilting toward design-build and turnkey contracts that embed offsite fabrication from inception. Skanska AB leverages its integrated project delivery model to control scheduling risk across European and North American infrastructure. Bouygues Construction anchors its competitive stance through factory-based manufacturing platforms in France that reduce on-site labor dependency. Sekisui House, Ltd. dominates Japanese residential prefabrication with steel-frame precision systems and vertically integrated supply chains.
Prefabricated buildings are factory-manufactured structural assemblies produced under controlled conditions, typically incorporating steel frames, cross-laminated timber, or precast concrete panels with specified fire ratings and thermal performance metrics, then transported to sites for rapid erection to compress construction schedules and improve quality consistency. Modular homes lead residential volume due to repeatable floor plans and financing familiarity, while panelized buildings capture commercial margin pools through customization flexibility for offices and healthcare facilities. Pre-cast structures occupy industrial and infrastructure applications where load-bearing capacity and durability specifications are paramount.
Japan's METI enforces seismic performance standards that effectively mandate factory-quality control for mid-rise residential construction, while the EU Green Deal and national building codes in Germany and France impose embodied carbon disclosure requirements that favor offsite methods with material traceability. In the United States, OSHA and ICC code alignment shapes factory safety protocols and modular installation standards across state jurisdictions. Stakeholders must monitor how evolving ESG disclosure rules and skilled labor shortages in construction trades reshape procurement criteria for permanent versus temporary facility applications.
Market Dynamics
EU Green Deal embodied carbon disclosure rules and tightening building energy codes across Germany and France are forcing developers to abandon traditional stick-built methods in favor of factory-controlled manufacturing with full material traceability.
Growth Catalysts
- Healthcare infrastructure mandates:Hospital and clinic construction projects are embedding offsite fabrication from schematic design to compress infection-sensitive construction timelines and meet accelerated occupancy deadlines.
- China's urban renewal programs:Affordable housing mandates in Shenzhen and Chengdu are driving large-scale modular deployment for residential density targets and construction waste reduction quotas.
- Cross-laminated timber maturation:Fire-rated mass timber panels are penetrating mid-rise commercial and institutional segments previously reserved for concrete and steel structural systems.
Market Restraints
- Specialized transport logistics:Oversized module dimensions trigger route restrictions, pilot car requirements, and bridge load limits that inflate last-mile costs unpredictably across state and provincial jurisdictions.
- Skilled factory labor scarcity:CNC equipment operation, precision welding certification, and quality control engineering talent pools remain shallow in manufacturing regions outside established prefabrication clusters.
- Traditional construction bonding:Surety markets apply unfamiliar risk models to modular projects, requiring higher collateral or excluding factory fabrication from standard performance bond coverage.
Strategic Opportunities
- Data center vertical expansion:Hyperscale cloud operators are specifying prefabricated electrical and mechanical skids to compress commissioning schedules for AI training facility deployments.
- EU Green Deal renovation wave:Deep energy retrofit mandates for existing building stock are creating demand for facade-integrated panel systems with embedded insulation and MEP routing.
- Design-build contract proliferation:Single-source accountability models are displacing design-bid-build procurement, enabling fabricators to capture margin pools previously fragmented across general contractor and subcontractor tiers.
Industry Challenges
- Jurisdictional code harmonization:State-level modular building codes, factory inspection protocols, and installation standards vary significantly, forcing multi-state operators to maintain redundant certification and quality systems.
- Legacy system integration:Existing hospital campuses, university districts, and industrial facilities require precise interface coordination between factory-built modules and aging infrastructure with incomplete as-built documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Buildings Market |
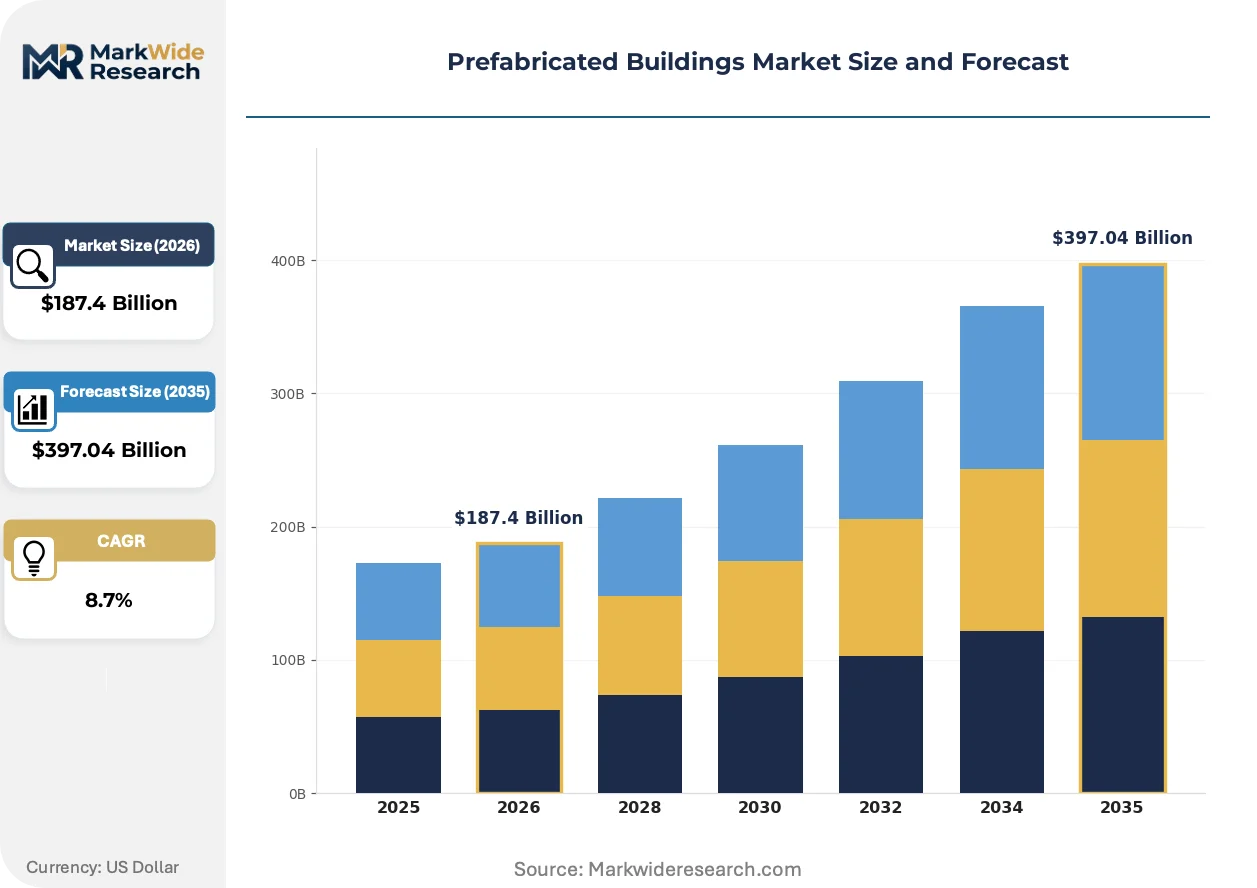
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Buildings, Pre-Cast Structures, Shipping Container Homes Construction Method: Traditional Manufacturing, Lean Manufacturing, 3D Printing, Hybrid Construction End User: Residential Projects, Commercial Developments, Industrial Facilities, Educational Institutions Application: Temporary Facilities, Emergency Housing, Permanent Housing, Retail Outlets |
| Companies Covered | Daiwa House Industry Co., Ltd., Skanska AB, Clayton Homes, ATCO Ltd., Bouygues Construction, Skyline Champion Corporation, Sekisui House, Ltd., Lendlease Group, Cavco Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Buildings Market Strategic Shifts
Digital fabrication workflows and material science advances are compressing the gap between architectural customization and manufacturing repeatability, eroding the historical trade-off between speed and design flexibility.
Building information modeling is collapsing the traditional sequence of design, engineering, and production into concurrent workflows where structural analysis, MEP coordination, and CNC cutting paths generate simultaneously from unified digital twins. Healthcare and education developers are adopting these platforms to reduce change-order exposure on complex institutional projects. The compression of design-to-fabrication timelines is enabling just-in-sequence delivery that minimizes site inventory and weather risk.
The EU Green Deal's embodied carbon disclosure requirements are mandating environmental product declarations for structural materials, favoring offsite manufacturers with captive supply chain data and penalizing conventional builders with fragmented subcontractor sourcing. Germany's national building energy code and France's RE2020 environmental regulations are tightening operational and embodied carbon limits in parallel. Panelized and volumetric suppliers with certified timber supply chains and recycled steel content are capturing specification preference in public procurement frameworks.
Hospital systems and university endowments are consolidating vendor relationships around turnkey design-build partnerships that transfer schedule risk to integrated delivery teams. These procurement patterns displace fragmented general contractor bidding with single-source accountability for cost, timeline, and performance guarantees. The shift is most visible in North American healthcare construction, where owner-operators prioritize occupancy certainty over first-cost minimization for revenue-generating clinical facilities.
Prefabricated Buildings Market Segmentation
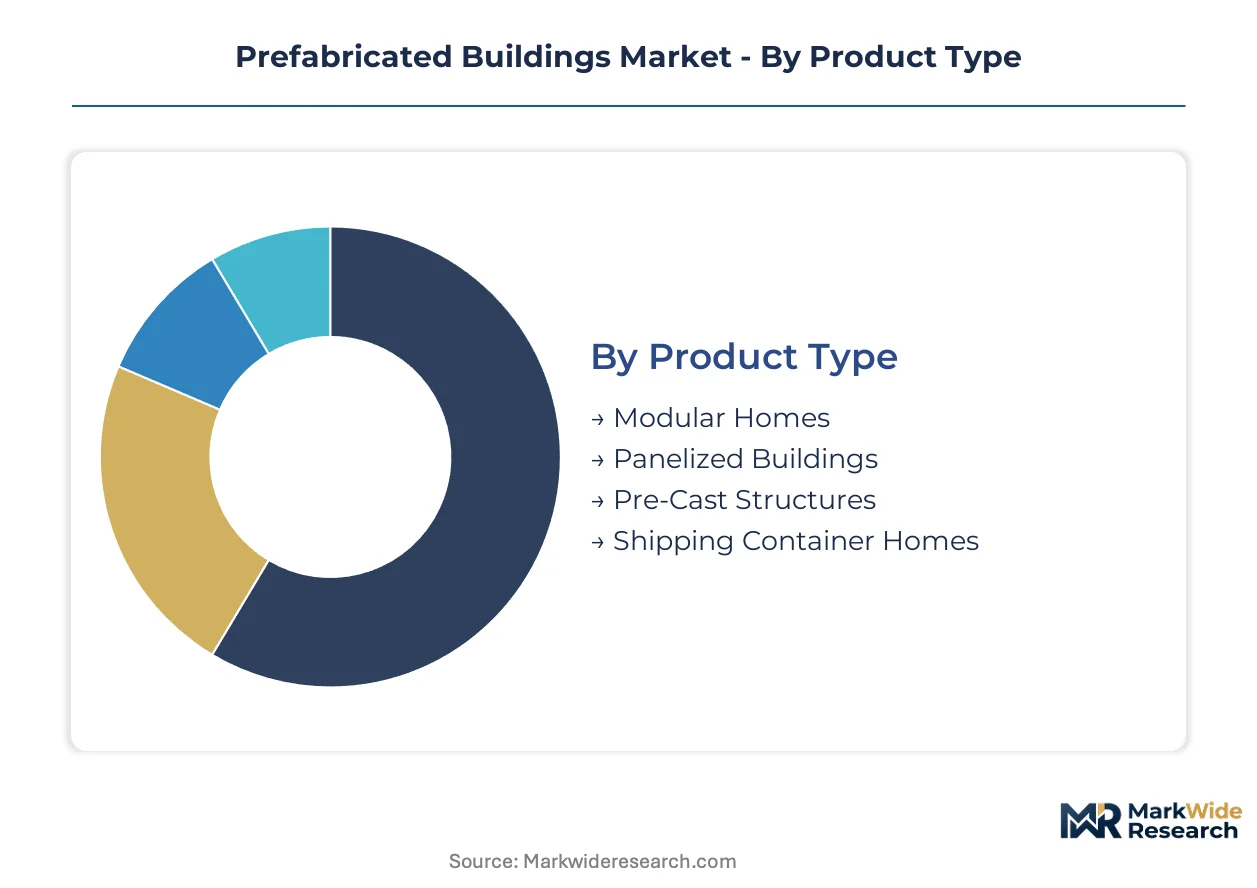
Prefabricated buildings fragment across four distinct segmentation axes that capture manufacturing methodology, structural form, buyer category, and deployment duration. Understanding these dimensions reveals where margin pools concentrate and which technical specifications command specification preference.
Product Type:
Cost tier differentiation separates standardized volumetric systems from customized panel assemblies and structural precast elements.
- Modular Homes:Factory-built volumetric units with complete interior fit-outs, steel or timber frames, and code-compliant MEP systems. Demand concentrates in China's affordable housing mandates across Shenzhen and Chengdu, driven by municipal construction waste reduction quotas and compressed occupancy timelines.
- Panelized Buildings:Flat-packed wall, floor, and roof assemblies shipped for on-site erection, offering customization flexibility for commercial facades. Healthcare developers in Germany and France specify these systems to meet EU Green Deal embodied carbon disclosure requirements while accommodating complex building geometries.
- Pre-Cast Structures:Load-bearing concrete elements for industrial and infrastructure applications requiring seismic resilience and fire ratings.
- Shipping Container Homes:Repurposed intermodal units adapted for residential and emergency shelter deployment.
Modular homes command the established base. The steepest expansion runs through panelized buildings.
Construction Method:
Volume concentration and production velocity separate legacy factory workflows from emerging additive and hybrid techniques.
- Traditional Manufacturing:Established assembly-line production with fixed tooling, quality control protocols, and skilled labor dependencies. Japanese residential builders leverage this method to satisfy METI seismic performance standards through precision welding and CNC cutting of steel-frame components.
- Lean Manufacturing:Just-in-sequence material flows and waste reduction principles adapted from automotive production. European fabricators deploy these systems to compress design-to-delivery timelines for healthcare and education projects under design-build contracts.
- 3D Printing:Robotic extrusion of concrete or polymer composites for complex geometries and material optimization.
- Hybrid Construction:Combined offsite fabrication with targeted on-site assembly for legacy system integration.
Traditional manufacturing commands the established base. Lean manufacturing captures the steepest expansion trajectory.
End User:
Customer type determines specification complexity, financing structures, and procurement risk allocation.
- Residential Projects:Single-family and multi-family housing with repeatable floor plans and established mortgage financing channels. China's urban renewal programs drive large-scale deployment in tier-one cities.
- Commercial Developments:Office, retail, and hospitality facilities requiring facade customization and MEP coordination.
- Industrial Facilities:Manufacturing plants, warehouses, and distribution centers prioritizing clear spans and load-bearing capacity. Pre-cast concrete dominates this segment where durability specifications override first-cost sensitivity.
- Educational Institutions:Schools and university buildings with accelerated summer construction windows.
Residential projects command the established base. Commercial developments are climbing the fastest.
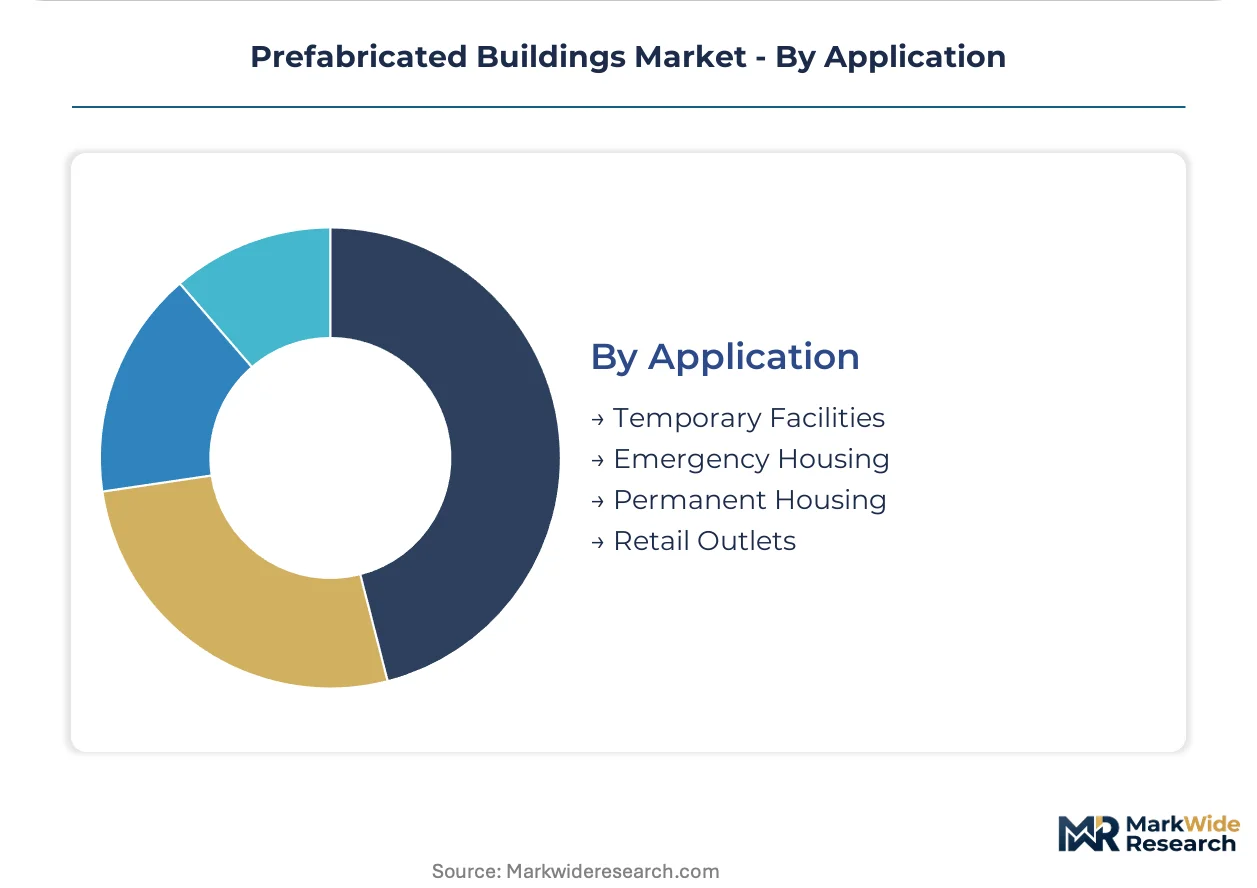
Application:
Deployment duration separates temporary and emergency use cases from permanent installations with full code compliance.
- Temporary Facilities:Construction site offices, event infrastructure, and interim healthcare with reduced foundation requirements. Panelized systems serve this segment where rapid relocation or lease expiration drives procurement.
- Emergency Housing:Post-disaster shelter and refugee accommodation with compressed delivery timelines. Shipping container adaptations and modular units concentrate demand in seismically active regions and conflict zones.
- Permanent Housing:Code-compliant dwellings with full utility connections and long-term financing eligibility.
- Retail Outlets:Branded storefronts and quick-service restaurants with standardized footprints.
Permanent housing commands the established base. Emergency housing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites the Netherlands' role as Europe's prefabricated building logistics hub, while China's Belt and Road rail corridors accelerate module transport to Central Asian construction sites.
China
Shenzhen and Chengdu urban renewal programs drive volumetric module demand for affordable housing density targets. Municipal construction waste reduction quotas enforced by MEE tighten embodied carbon limits for developers. The Pearl River Delta manufacturing cluster supplies steel-frame precision systems to domestic megaprojects and Southeast Asian export markets.
United States
OSHA-aligned factory safety protocols and ICC modular installation standards shape procurement across state jurisdictions. Hospital systems in Texas and Florida specify design-build contracts with offsite fabrication to compress infection-sensitive construction timelines. The Southeast manufacturing corridor concentrates panelized production capacity serving commercial and healthcare verticals.
Germany
National building energy codes impose parallel operational and embodied carbon disclosure requirements favoring material traceability. Factory-based manufacturing platforms in Baden-Württemberg reduce on-site labor dependency for healthcare and education projects. The Stuttgart industrial cluster integrates cross-laminated timber supply chains with automated CNC cutting workflows.
Japan
METI seismic performance standards mandate factory-quality control for mid-rise residential construction. Steel-frame precision systems dominate Tokyo and Osaka metropolitan housing markets. The Nagoya manufacturing belt supplies vertically integrated components to Kansai region developers under compressed delivery schedules.
France
RE2020 environmental regulations tighten embodied carbon limits for new construction and deep energy retrofits. Bouygues Construction anchors factory-based manufacturing platforms serving public procurement frameworks. The Lyon-Auvergne-Rhône-Alpes cluster specializes in facade-integrated panel systems with embedded MEP routing for EU Green Deal renovation wave projects.
Prefabricated Buildings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying precision-engineered subassemblies. The vendor base organizes around three strategic archetypes: vertically integrated developers controlling captive manufacturing, modular fabricators serving project-specific contracts, and material-technology suppliers licensing panel systems. Competitive positioning hardens through design-build contract capture and geographic clustering near established logistics corridors.
Among Japanese steel-frame residential specialists, Daiwa House Industry Co., Ltd. and Sekisui House, Ltd. exemplify the vertically integrated archetype with captive supply chain control. Skanska AB represents the platform integrator model with integrated project delivery capabilities spanning European and North American infrastructure markets.
| Leading Market Players |
|---|
| Daiwa House Industry Co., Ltd. |
| Skanska AB |
| Clayton Homes |
| ATCO Ltd. |
| Bouygues Construction |
| Skyline Champion Corporation |
| Sekisui House, Ltd. |
| Lendlease Group |
| Cavco Industries |
| Others |
Value Chain & Pricing Dynamics
Factory undercapacity in China's Pearl River Delta manufacturing cluster is compressing lead times for steel-frame precision systems while simultaneously inflating spot pricing for urgent healthcare and data center projects. This utilization squeeze rewards fabricators with captive production assets and penalizes project developers dependent on third-party module sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates EU Green Deal-certified panel systems with full material traceability from conventional factory-built modules and basic precast concrete elements. Price differentiation centers on certification grade and volume scale, with municipal affordable housing mandates in Shenzhen commanding steep discounts against one-off commercial healthcare specifications. Cost compression in the standard tier is intensifying because Chinese steel input volatility and specialized transport logistics inflate last-mile delivery unpredictably. Residential developers remain most price-sensitive, while hospital systems and hyperscale data center operators prioritize schedule certainty over first-cost minimization.
Supply Chain Analysis
Upstream feedstock for structural assemblies draws from Chinese steel production, German cross-laminated timber processing, and Japanese precision manufacturing clusters. Raw material dependencies center on hot-rolled steel sections, engineered wood products, and precast concrete admixtures. Single-source vulnerability concentrates in the Pearl River Delta for volumetric module fabrication and Baden-Württemberg for automated CNC cutting workflows. Distribution runs through design-build contractors capturing margin pools previously fragmented across general contractor tiers, with turnkey contracts embedding factory fabrication from schematic design.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prefabricated building markets increasingly monetize through service-attach revenue streams, with factory-based maintenance contracts and module lifecycle upgrade programs expanding faster than standalone hardware sales. This recurring-revenue layer commands superior margin profiles and customer retention versus transactional project delivery.
For Market Incumbents: Insulate core manufacturing positions through backward integration into cross-laminated timber supply chains and steel-frame precision component production. Skanska AB and Bouygues Construction demonstrate how captive factory platforms reduce exposure to skilled labor scarcity and input cost volatility. Certification investment in EU Green Deal environmental product declarations creates switching costs against lower-tier competitors lacking material traceability infrastructure.
For New Entrants and Emerging Players: Establish a beachhead in emergency housing and post-disaster shelter deployment where compressed delivery timelines override incumbent relationship advantages. Shipping container adaptations and rapid-deployment modular units face less entrenched competition than permanent residential or commercial healthcare verticals. Partner with international development agencies and humanitarian organizations to secure anchor contracts that validate production quality for subsequent public procurement frameworks.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated developers controlling captive manufacturing platforms with design-build contract capture. Long-term viability across the projection horizon favors archetypes with demonstrated EU Green Deal compliance and established logistics corridors near Rotterdam-class container hubs. Watch municipal construction waste reduction quotas in Chinese tier-one cities as the inflection signal for accelerated modular adoption mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive cross-laminated timber sourcing secures EU Green Deal certification preference in German and French public procurement. |
| Design-Build Contract Capture | Single-source accountability transfers schedule risk from hospital systems to integrated delivery teams across North American healthcare. |
| Factory Automation Investment | CNC cutting workflows and robotic welding reduce dependency on scarce precision certification talent in Japanese steel-frame production. |
| Logistics Corridor Positioning | Manufacturing clustering near Rotterdam container throughput minimizes oversized module transport restrictions across European jurisdictions. |
| Environmental Product Declaration Certification | Full material traceability meets RE2020 embodied carbon limits for French deep energy retrofit and new construction specifications. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with factory operations directors, design-build contract managers, hospital procurement committees, and municipal housing authority planners; and secondary validation against EU Green Deal regulatory filings, national building energy code amendments, customs trade data for prefabricated structural assemblies, and SEC disclosures from publicly traded fabricators. Bottom-up module shipment tracking and top-down construction spending allocation were triangulated to anchor volume estimates.
Forecast inputs considered manufacturing capacity utilization across the Pearl River Delta and Baden-Württemberg clusters, municipal affordable housing mandate trajectories, and embodied carbon disclosure requirement phase-ins. Segmentation dimensions modeled include product type, construction method, end user category, and deployment duration application. CAGRs were derived from regression analysis against historical construction cost indices and factory output correlations with traditional on-site build rates.
Stress conditions across steel input cost volatility, specialized transport route restrictions, and skilled factory labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation timelines and Chinese urban renewal program continuity. Cross-checking against national construction spending surveys and factory capacity utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Prefabricated Construction Market
Building Construction
North America Modular Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Dominican Republic Construction Market
Building Construction
Africa Construction Market
Building Construction
US Modular Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
China Modular Construction Market
Building Construction
China Building Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Vertical Garden Construction Market