
 Russia Prefabricated Buildings Market | 2026-2036
Russia Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Prefabricated Buildings Market Insights
Residential housing is restructuring its procurement model as Russian developers shift from cast-in-place concrete toward off-site fabrication for mid-rise apartment blocks. PIK Group of Companies leverages its captive panel production capacity to compress construction schedules across Moscow-region projects. LSR Group St. Petersburg anchors its market position through integrated manufacturing of reinforced concrete elements serving Northwestern Federal District developments. Segezha Group competes via cross-laminated timber specialization, capitalizing on Russia's extensive softwood resource base and evolving fire-safety engineering standards.
Prefabricated buildings are structures manufactured in factory conditions and transported to sites for assembly, typically incorporating standardized structural modules with specified load-bearing capacities, thermal insulation ratings, and seismic resistance parameters designed for permanent or semi-permanent occupancy. Steel structures dominate commercial and industrial applications due to their span capabilities and recyclability, while modular units capture residential momentum through volumetric completeness that minimizes on-site trade coordination. Panelized systems occupy a mature position in single-family construction, though hybrid construction methods that combine off-site fabrication with localized structural integration represent the fastest-growing configuration as contractors balance speed with design flexibility.
Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) enforces GOST construction standards that govern material specifications and structural performance, while the Ministry of Construction and Housing and Communal Services oversees building codes that increasingly reference energy efficiency benchmarks for envelope assemblies. Compliance with these frameworks shapes product development priorities, as manufacturers must certify thermal performance and durability metrics before securing procurement contracts with government agencies or large developers. Stakeholders should monitor regulatory harmonization pressures between national standards and Eurasian Economic Union technical regulations, as divergence in certification requirements could fragment supply chain configurations across member states.
Market Dynamics
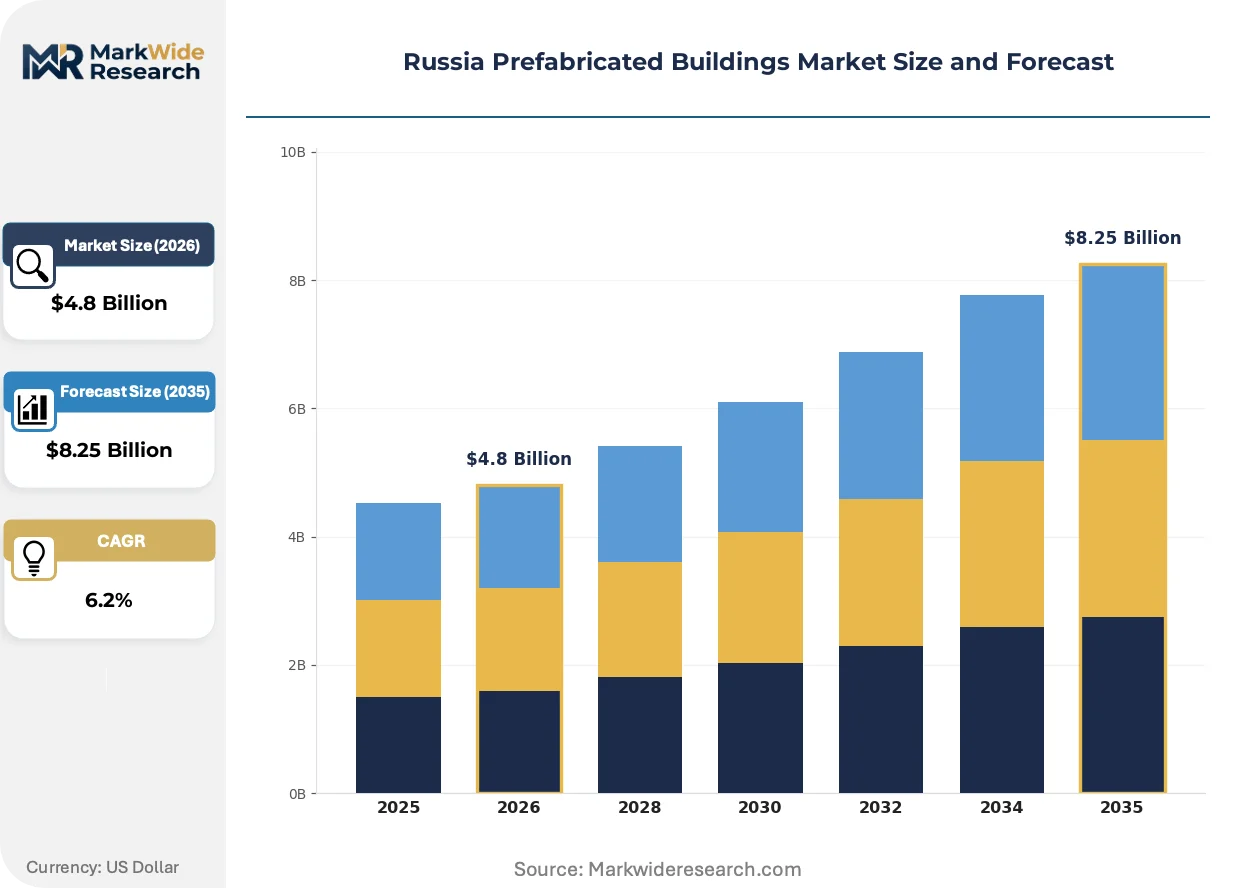
Russia's prefabricated buildings sector is reconfiguring around factory-based construction methods as Moscow-region developers accelerate project timelines to meet housing delivery targets under federal modernization programs.
Growth Catalysts
- Technical Regulation Modernization:Rosstandart's updated GOST standards for energy efficiency and seismic resistance are mandating higher-performance envelope assemblies that favor precision-manufactured panel systems over site-built alternatives.
- Central Federal District Urban Density:Moscow's ring road expansion and satellite city development are concentrating demand for rapid-assembly housing solutions that minimize on-site labor exposure to weather delays.
- Cross-Laminated Timber Engineering:Fire-safety engineering advances for mass timber construction are unlocking residential applications previously reserved for concrete and steel structural systems.
Market Restraints
- Reinforcement Steel Price Volatility:Fluctuations in domestic steel billet pricing compress margins for reinforced concrete element manufacturers serving Northwestern Federal District projects.
- Transportation Infrastructure Constraints:Limited heavy-haul capacity from factory locations in Karelia and Arkhangelsk Oblast to Central Russian construction sites restricts module size and extends delivery windows.
- Site-Built Concrete Substitution:Cast-in-place methods retain cost advantages for high-rise structures exceeding twelve stories, capping prefabrication penetration in premium residential towers.
Strategic Opportunities
- Far Eastern Federal District Underpenetration:Vladivostok and Khabarovsk housing programs lack established prefabrication supply chains, creating first-mover positioning for panel producers with logistics optimization capabilities.
- Digital Fabrication Integration:Building information modeling linked directly to CNC cutting equipment is reducing material waste and enabling mass customization for standardized module platforms.
- Eurasian Economic Union Harmonization:Convergence of technical regulations with Kazakhstan and Belarus certification requirements would unlock cross-border procurement contracts for Russian manufacturers with compliant production lines.
Industry Challenges
- Seismic Engineering Certification Bottlenecks:Extended approval timelines for innovative connection systems under Rosstandart's revised structural safety protocols delay product launches by twelve to eighteen months.
- Skilled Installation Labor Scarcity:Shortages of certified crane operators and module alignment specialists in Siberian Federal District construction markets inflate on-site assembly costs and extend project handover schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Prefabricated Buildings Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Structures, Modular Units, Wood Panels, Concrete Elements Application: Residential Housing, Commercial Buildings, Industrial Facilities, Institutional Structures Construction Method: Off-Site Fabrication, On-Site Assembly, Hybrid Construction, Panelized Systems End User: Developers, Contractors, Government Agencies, Private Homeowners |
| Companies Covered | PIK Group of Companies, LSR Group St. Petersburg, Segezha Group, Renaissance Construction, Setl Group St. Petersburg, K Modul, Story House, Pallada Eco, INSI Holding, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Prefabricated Buildings Market Trends and Innovations
Digital manufacturing integration and regulatory pressure for energy performance are compressing traditional construction timelines while expanding material options for Russian developers.
Volumetric modular construction is overtaking panelized systems in mid-rise residential applications. These fully fitted three-dimensional units incorporate MEP rough-ins and interior finishes under factory conditions. Moscow-region developers are specifying volumetric solutions for projects up to eight stories to minimize trade coordination on constrained urban sites. This technology is overtaking conventional stick-built methods by compressing weather-dependent construction phases from months to weeks.
Rosstandart's phased implementation of stricter thermal transmittance coefficients for building envelopes is forcing insulation specification upgrades across all prefabrication categories. Manufacturers must recertify wall and roof assemblies to demonstrate compliance with revised GOST R 54851 standards before securing government-backed procurement contracts. Panel producers in Tatarstan and Bashkortostan are responding by integrating vacuum insulation panels into hybrid envelope systems for premium residential segments.
Developer purchasing departments are consolidating supplier relationships around turnkey design-build contracts that transfer engineering liability to prefabrication specialists. Single-source accountability for structural performance, energy modeling, and warranty coverage is displacing fragmented subcontractor management models. This concentration is most visible in Saint Petersburg's waterfront redevelopment zones, where LSR Group and similar integrated operators capture multi-phase contracts through captive manufacturing capacity.
Russia Prefabricated Buildings Market Segmentation
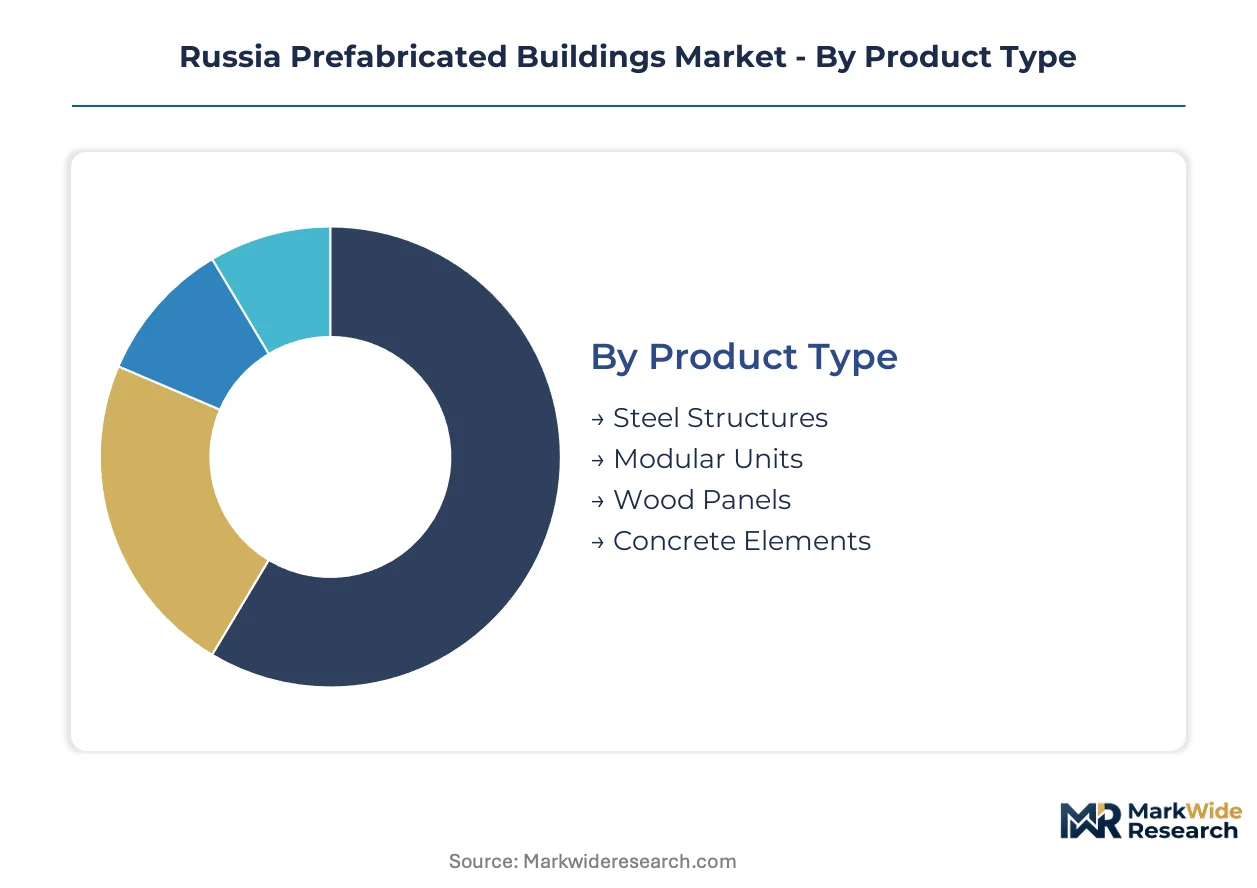
Prefabricated building procurement in Russia follows distinct technical and commercial logics that shape manufacturer specialization. Developers select structural systems based on project scale, seismic requirements, and labor availability at destination sites.
Product Type:
Material specifications determine load-bearing capacity, thermal performance, and factory-to-site logistics economics across Russia's climatic zones.
- Steel Structures:Hot-rolled and cold-formed steel framing delivers long-span capability for commercial and industrial envelopes. Moscow-region logistics hubs concentrate procurement for multi-story office developments where speed of erection outweighs material cost premiums.
- Modular Units:Three-dimensional volumetric units ship with MEP rough-ins and interior finishes complete. Central Federal District developers specify these for mid-rise residential blocks to compress weather-dependent construction phases.
- Wood Panels:Cross-laminated timber and glulam assemblies leverage Russia's softwood resource base. Northwestern Federal District projects near Karelia sourcing clusters favor these for low-rise residential envelopes.
- Concrete Elements:Precast reinforced wall panels and hollow-core slabs dominate high-load applications. LSR Group and similar integrated operators deploy captive production for Saint Petersburg waterfront developments.
Concrete Elements leads on scale; Modular Units leads on momentum.
Application:
End-use requirements dictate fire-safety ratings, acoustic performance, and facade specifications that filter supplier eligibility.
- Residential Housing:Multi-family apartment blocks and single-family homes drive procurement volume. Moscow's satellite city programs generate sustained demand for rapid-assembly envelope systems meeting updated GOST thermal standards.
- Commercial Buildings:Office and retail developments prioritize flexible floor plates and fast-track delivery. Panelized steel-concrete hybrid systems capture share in Central Federal District business park construction.
- Industrial Facilities:Warehousing and manufacturing plants specify wide-span steel framing with minimal interior columns. Procurement concentrates near transport corridors and special economic zones.
- Institutional Structures:Schools, hospitals, and administrative buildings face stringent seismic and durability requirements. Extended Rosstandart certification timelines constrain supplier participation.
Residential Housing dominates procurement volume; Commercial Buildings shows steepest expansion trajectory as Moscow-region office stock modernizes.
Construction Method:
Fabrication location and assembly sequencing determine project risk allocation between manufacturers and general contractors.
- Off-Site Fabrication:Complete structural modules or panelized elements manufactured under factory conditions. Quality control and weather-independent production compress delivery schedules for Central Federal District developers.
- On-Site Assembly:Pre-cut components delivered for sequential installation by local crews. Siberian Federal District projects with limited heavy-haul access favor this approach despite weather exposure.
- Hybrid Construction:Factory-fabricated primary structure combined with site-built secondary elements. This configuration balances speed with design flexibility for complex urban infill sites.
- Panelized Systems:Flat wall and roof panels requiring on-site lifting and connection. Mature technology dominates single-family construction in Tatarstan and Bashkortostan.
Off-Site Fabrication leads on scale; Hybrid Construction leads on momentum as contractors seek risk-adjusted delivery models.
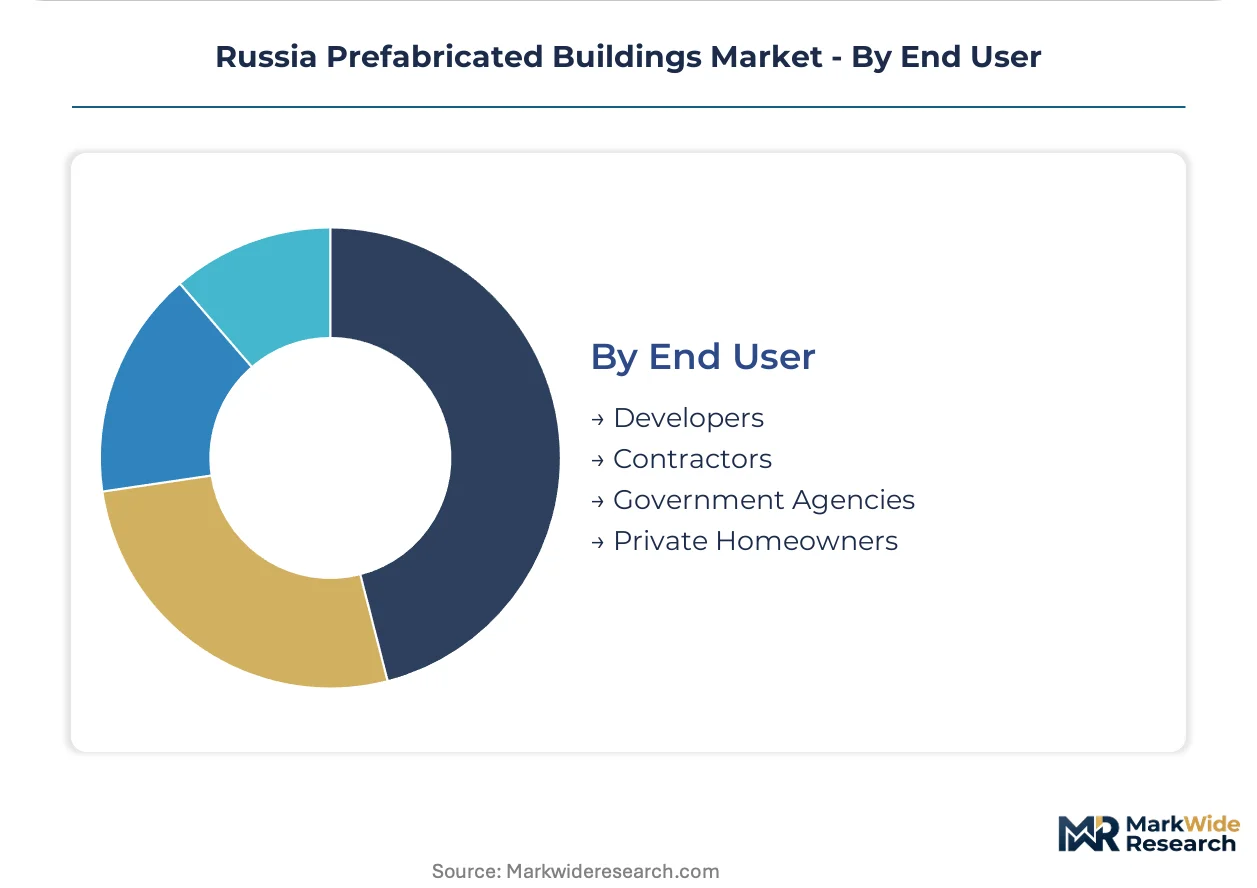
End User:
Purchasing authority and technical capability shape contract structures and warranty expectations.
- Developers:Large-scale residential and commercial project sponsors with in-house engineering teams. PIK Group and similar operators leverage captive manufacturing to secure cost and schedule certainty.
- Contractors:General construction firms subcontracting envelope installation. These intermediaries prioritize supplier technical support and crane-operator training for module alignment.
- Government Agencies:Federal and municipal procurement for social housing and infrastructure. Compliance with revised GOST R 54851 thermal standards is mandatory for contract eligibility.
- Private Homeowners:Individual purchasers of single-family prefabricated dwellings. This segment favors wood panel systems from regional producers with localized delivery networks.
Developers lead on scale; Government Agencies leads on momentum as federal housing programs expand procurement volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rosstandart's tightening certification requirements for thermal performance and seismic resistance are redistributing production capacity toward federal districts with lower compliance execution costs. Manufacturers migrate fabrication to regions with streamlined permitting and established testing infrastructure.
Central Federal District
Moscow's satellite city expansion drives procurement volume for rapid-assembly envelope systems. The Ministry of Construction's federal housing modernization programs mandate GOST R 54851 thermal compliance for all government-backed contracts. Podolsk and Domodedovo industrial zones concentrate panel production capacity serving the capital region's ring road developments.
Northwestern Federal District
Saint Petersburg waterfront redevelopment generates sustained demand for precast concrete elements. Regional building codes enforce stricter durability standards for Baltic Sea coastal exposure. LSR Group anchors manufacturing in Vsevolozhsk and Gatchina to supply captive production for multi-phase residential contracts.
Siberian Federal District
Novosibirsk and Krasnoyarsk housing programs face heavy-haul logistics constraints that favor on-site assembly over module delivery. Extended Rosstandart approval timelines for seismic connection systems delay prefabrication penetration. Regional producers in Kemerovo and Tomsk specialize in panelized systems for single-family construction.
Far Eastern Federal District
Vladivostok and Khabarovsk federal housing targets exceed established prefabrication supply chain reach. The Ministry of Construction's Far East development subsidies prioritize speed of delivery over capital cost minimization. First-mover panel producers with optimized logistics configurations capture underpenetrated procurement volumes.
Volga Federal District
Tatarstan and Bashkortostan host mature wood panel manufacturing clusters leveraging regional softwood resources. Republic-level industrial policy supports vacuum insulation panel integration for premium residential segments. Naberezhnye Chelny and Ufa factories serve Central Russian markets through rail-linked distribution networks.
Russia Prefabricated Buildings Market Competitive Landscape
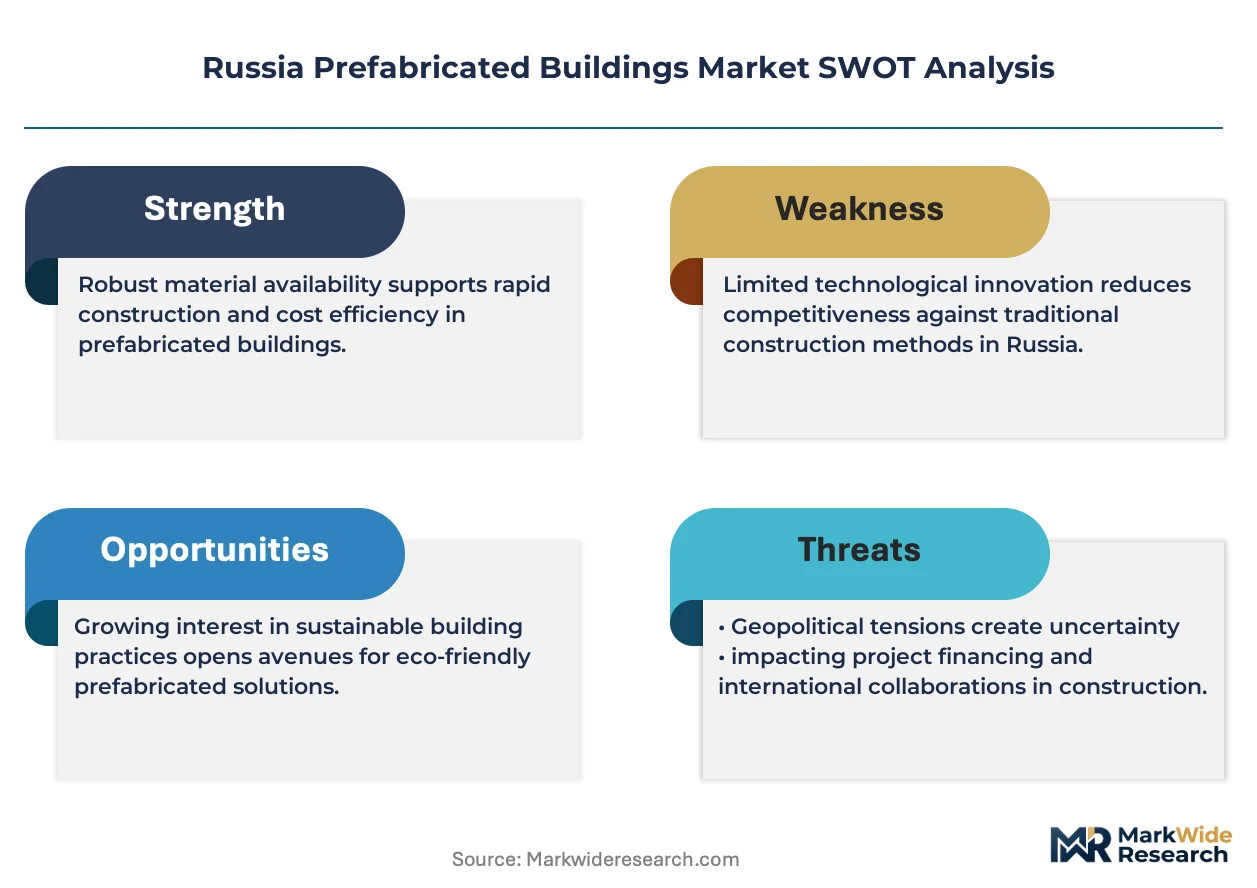
Branded specialists and contract manufacturers split share differently across segments, with integrated developers capturing government contracts through captive production while independent fabricators serve private residential demand. The vendor base clusters around three archetypes: vertically integrated construction conglomerates with in-house panel plants, regional wood processing specialists with cross-laminated timber capabilities, and modular unit assemblers targeting mid-rise volumetric applications. Dominant competitive moves include backward integration into primary material production and strategic partnerships with crane service providers to secure installation capacity.
Among Moscow-based integrated developers, PIK Group of Companies exemplifies the captive manufacturing archetype through controlled panel production capacity. LSR Group St. Petersburg occupies a parallel position in the Northwestern Federal District, anchoring market presence through reinforced concrete element fabrication. Segezha Group represents the resource-backed specialization vector, leveraging Karelia softwood access for cross-laminated timber engineering.
| Leading Market Players |
|---|
| PIK Group of Companies |
| LSR Group St. Petersburg |
| Segezha Group |
| Renaissance Construction |
| Setl Group St. Petersburg |
| K Modul |
| Story House |
| Pallada Eco |
| INSI Holding |
| Others |
Pricing and Supply Chain Analysis
Rosstandart's phased GOST R 54851 thermal transmittance mandates gate qualified supply access and premium-tier pricing power for panel producers serving Moscow-region government contracts. Manufacturers lacking certified envelope assemblies face exclusion from federal housing procurement, compressing viable supplier pools and amplifying margin capture for compliant operators.
Pricing Analysis
Direct-to-developer contracts bypass distributor markups entirely, concentrating price negotiation leverage with large integrated construction groups. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-insulation-panel hybrids from baseline mineral-wool systems and commodity-grade concrete elements. Pricing pressure stems from reinforcement steel billet volatility eroding margins for Northwestern Federal District precast producers. Government agencies exhibit lowest price sensitivity due to mandated compliance premiums, while private homeowners in single-family segments drive hardest bargain negotiations.
Supply Chain Analysis
Crane-operator and module-alignment specialist shortages in Siberian Federal District factory zones constrain production scaling and inflate wage costs for panel producers. Manufacturing gravity centers on Tatarstan and Bashkortostan for wood panels, Podolsk industrial zone for concrete elements, and Karelia for cross-laminated timber. Raw material flows draw from domestic softwood forests, Cherepovets steel billet output, and regional concrete admixture suppliers. Single-source vulnerability runs through heavy-haul capacity from Arkhangelsk Oblast to Central Russian sites. Distribution runs through rail-linked networks from Naberezhnye Chelny and Ufa to Moscow-region construction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's prefabricated buildings sector reads as a late-cycle quality story as developer procurement shifts toward turnkey design-build contracts demanding single-source warranty accountability.
For Market Incumbents: Lock in crane-service partnerships and certified installation labor pools before Siberian Federal District scarcity intensifies. Deepen backward integration into primary steel billet supply to hedge Cherepovets pricing volatility. Prioritize Rosstandart connection-system certification investment to compress twelve-to-eighteen-month approval bottlenecks.
For New Entrants and Emerging Players: Capture Far Eastern Federal District first-mover positioning in Vladivostok and Khabarovsk where federal housing targets exceed established supply chain reach. Target government agency procurement with GOST R 54851 pre-certified panel systems. Lead with logistics-optimized delivery models addressing heavy-haul infrastructure gaps.
For Investors and Strategic Acquirers: Roll-up economics work for regional wood-panel specialists because Tatarstan and Bashkortostan industrial policy supports vacuum insulation integration for premium residential segments. Five-to-ten-year viability hinges on Eurasian Economic Union harmonization unlocking Kazakhstan and Belarus cross-border contracts. Monitor Rosstandart-EAEU regulatory convergence as inflection signal for scalable platform value.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Billet Supply | Cherepovets sourcing control hedges reinforced concrete margin compression from domestic pricing volatility. |
| Digital Fabrication Integration | CNC-linked building information modeling reduces material waste for Tatarstan wood-panel producers. |
| Far Eastern Logistics Optimization | Rail-heavy-haul hybrid configurations unlock Vladivostok government housing procurement volumes. |
| Seismic Connection Certification Investment | Rosstandart approval acceleration captures twelve-to-eighteen-month competitive lead in institutional segments. |
| Turnkey Design-Build Contract Consolidation | Single-source engineering liability transfer displaces fragmented subcontractor management in Saint Petersburg waterfront zones. |
Research Methodology
Bottom-up residential housing modeling reconciled against top-down panel production capacity tracking forms the analytical core of this study. Primary interviews with Moscow-region developer procurement directors, Tatarstan plant operations managers, Rosstandart certification engineers, and Siberian Federal District crane-service operators combined with secondary validation against GOST regulatory filings, Ministry of Construction housing program disclosures, and Eurasian Economic Union technical regulation harmonization documents. Top-down customs data on softwood lumber flows and steel billet pricing indices triangulated against bottom-up project pipeline tracking across Central and Northwestern Federal Districts.
Input-output matrices map prefabrication system demand by construction method, material type, and end-user purchasing authority across the projection horizon. Segmentation dimensions span product type, application, construction method, and end-user archetype with regional production hub overlay. CAGRs derived from housing delivery target trajectories under federal modernization programs, weighted by GOST compliance execution timelines and logistics accessibility indices. Forecast inputs incorporate seismic engineering certification bottlenecks and heavy-haul capacity constraints as supply-side dampeners.
Regulatory divergence between Rosstandart and EAEU technical regulations, reinforcement steel price volatility spikes, and Far Eastern logistics infrastructure delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding GOST R 54851 phased implementation adherence and federal housing program budget continuity. Material deviation in named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
El Salvador Construction Market
Building Construction
India Commercial Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Thailand Construction Market
Building Construction
Construction Market
Building Construction
Prefabricated Buildings Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Qatar Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Middle East Data Center Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Honduras Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
South Africa Prefabricated Buildings Market