
 Vietnam Construction Market | 2026-2036
Vietnam Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Construction Market Outlook
Aftermarket facility management revenue is tilting toward developers with captive property portfolios. Hoa Binh Construction Group sustains dominance in high-rise residential execution across southern Vietnam. Coteccons Construction JSC leverages its precast concrete technology leadership to differentiate on speed-to-completion. Vinaconex JSC anchors its position through backward integration into building materials supply.
Vietnam construction encompasses the physical assembly of structures using reinforced concrete, structural steel, and curtain-wall systems to create habitable and functional built environments for residential occupancy, commercial activity, and industrial production. The sector spans project types where infrastructure and industrial segments capture expanding margin pools from state-backed transport corridors and foreign manufacturing relocation, while residential volume concentrates in private developer-led urban cores. Material type segmentation shows concrete maintaining cost-driven prevalence in mid-rise housing, with steel gaining share in commercial high-rises and factory frameworks. Service type dynamics reveal design-build integration compressing traditional engineering-construction handoffs as developers seek single-point accountability.
Vietnam's Ministry of Construction enforces QCVN building codes that mandate seismic resistance and fire safety standards, while the country's national construction regulator inspects project compliance through provincial departments. The BIS-aligned technical standards for structural materials shape import substitution patterns as domestic steel and cement producers scale capacity. Stakeholders must monitor regulatory enforcement consistency across provincial jurisdictions where permitting velocity directly impacts project feasibility timelines.
Market Dynamics
Vietnam's construction sector is compressing project delivery timelines as design-build integration eliminates traditional engineering-construction handoffs, forcing contractors to absorb accountability that previously sat with separate design houses.
Growth Catalysts
- QCVN 09:2023 Energy Codes:The Ministry of Construction's tightened building efficiency standards is mandating upgraded envelope performance and HVAC specifications across new commercial and residential stock, pulling demand for higher-grade materials and systems integration.
- Foreign Manufacturing Relocation:Industrial park development in Binh Duong and Bac Ninh provinces is concentrating demand for factory frameworks and supporting infrastructure as electronics and automotive suppliers establish Vietnam production bases.
- Mid-Rise Residential Expansion:Private developers in Ho Chi Minh City and Hanoi are accelerating housing stock additions to capture urbanization-driven demand, sustaining concrete volume and precast component throughput.
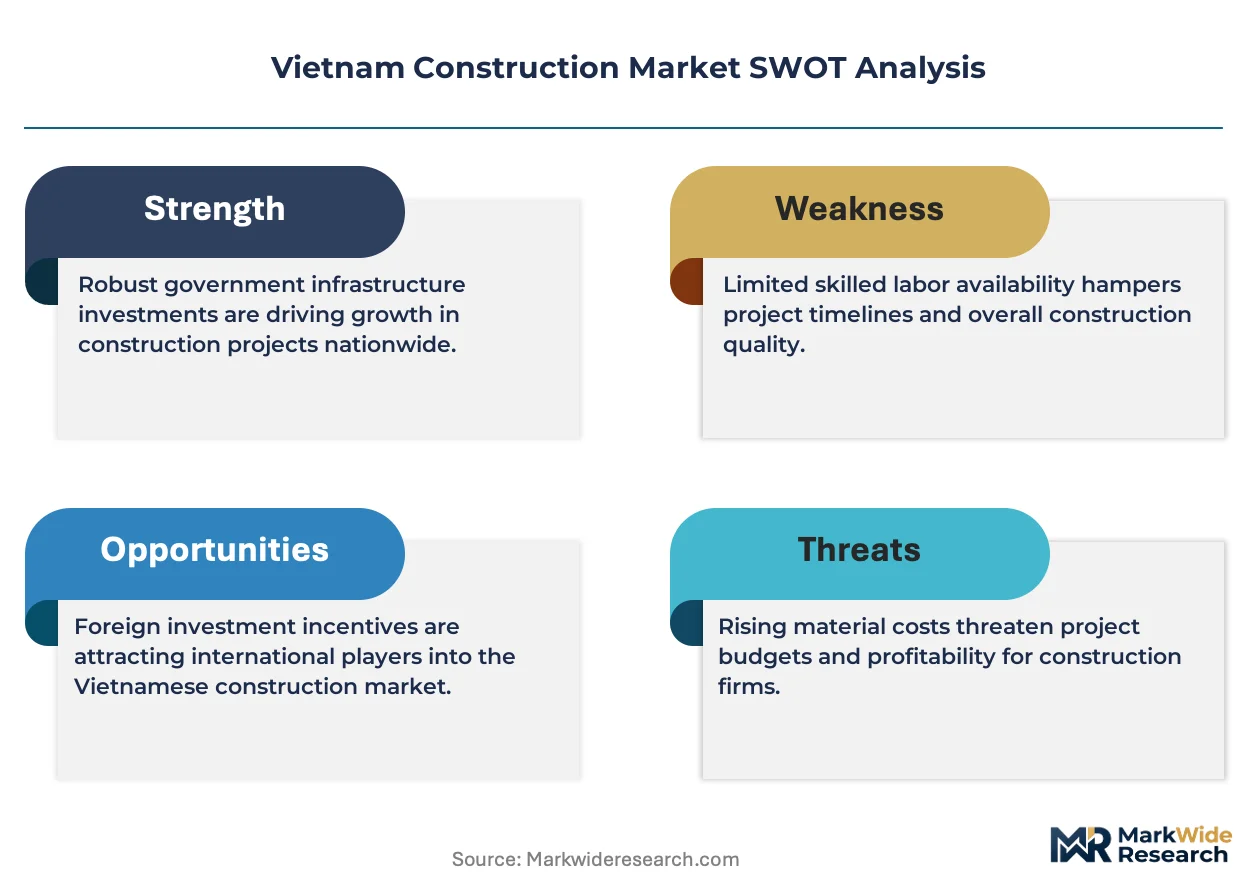
Market Restraints
- Structural Steel Import Dependency:Domestic rolling capacity constraints force reliance on imported sections, exposing project budgets to currency volatility and international freight rate swings that compress fixed-price contract margins.
- Provincial Permitting Velocity Variation:Enforcement consistency gaps across provincial construction departments create timeline uncertainty, with some jurisdictions requiring extended technical review cycles that stall project mobilization.
- Skilled Labor Pool Constraints:Shortages of certified welders and structural engineers limit execution capacity for complex high-rise and industrial frameworks, forcing wage premiums that erode contractor competitiveness.
Strategic Opportunities
- Central Coast Industrial Corridors:Underdeveloped provinces including Quang Nam and Binh Dinh are attracting logistics and light manufacturing investment, opening greenfield construction demand outside the saturated southern and northern hubs.
- Design-Build Contract Expansion:Developer preference for single-point accountability is compressing traditional engineer-procure-construct sequences, rewarding contractors with in-house architectural and structural design capabilities.
- Building Energy Retrofit Mandates:Anticipated extensions of QCVN efficiency requirements to existing building stock would activate renovation demand for envelope upgrades and mechanical system replacements.
Industry Challenges
- BIM Implementation Skill Gaps:Contractor adoption of building information modeling for clash detection and quantity surveying outpaces workforce training pipelines, forcing reliance on expensive external specialists.
- Legacy Subcontractor Coordination:Fragmented site-level execution through traditional labor-only subcontractors creates quality control and schedule synchronization friction that design-build integration has not fully eliminated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Construction Market |
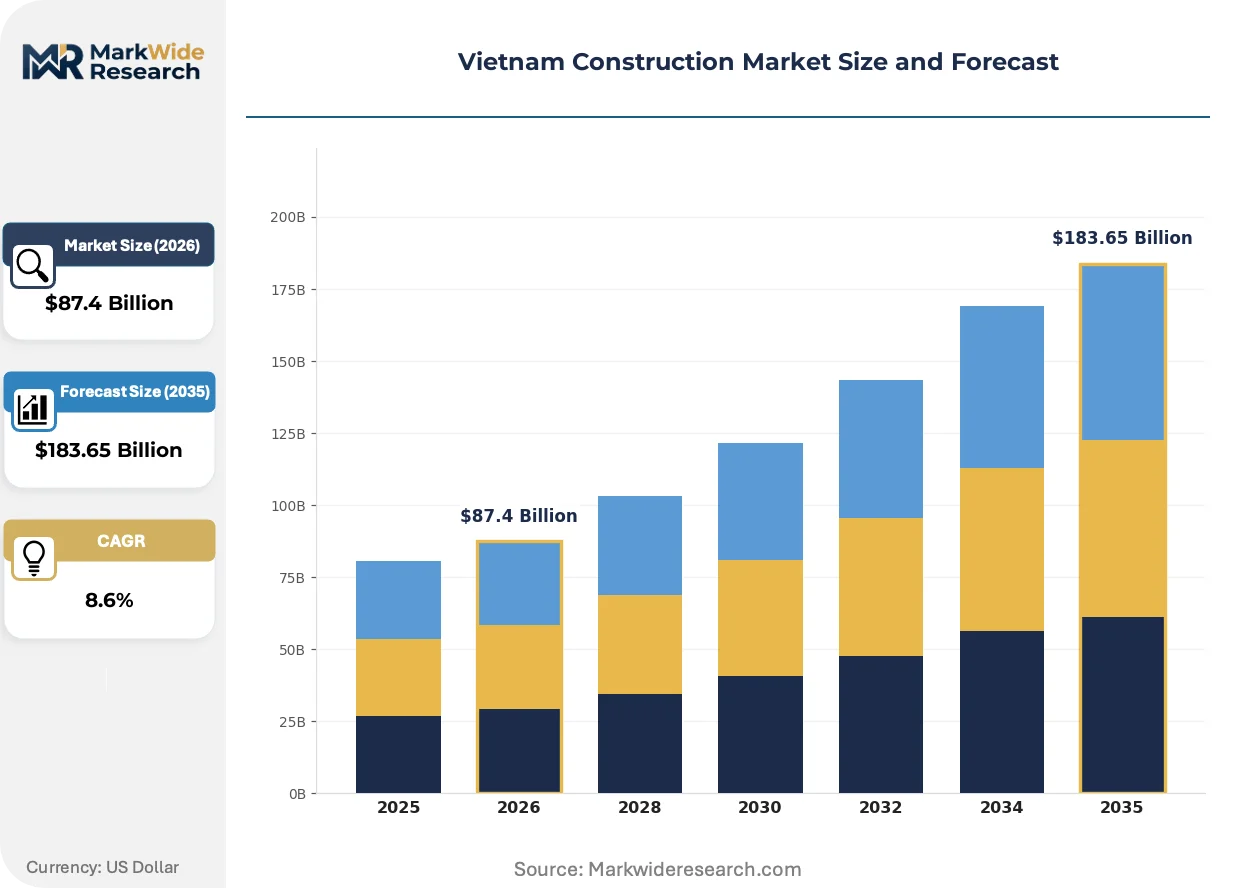
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $183.65 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Wood, Glass Service Type: Design, Engineering, Construction, Project Management End User: Private Developers, Government Agencies, Institutional Investors, Contractors |
| Companies Covered | Central Construction JSC, Construction Company No. 1 (CC1), Coteccons Construction JSC, Fecon Corp JSC, Newtecons Construction Company, Hoa Binh Construction Group JSC, Vinaconex JSC, An Phong Construction, Delta Construction Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Construction Market Strategic Shifts
Construction execution in Vietnam is digitizing at the project-management layer while materials innovation concentrates at the structural systems level, compressing both design cycles and on-site assembly duration.
Precast concrete technology is migrating from standard hollow-core flooring to integrated wall-and-facade systems that combine structural load-bearing with finished architectural surfaces. Mid-rise residential developers in Hanoi are specifying these components to compress floor-cycle times from seven days to four days. The technology is migrating from a cost-driven alternative to a schedule-critical enabler that differentiates contractor bids on speed-to-completion rather than unit pricing alone.
Vietnam's Ministry of Construction is enforcing QCVN seismic resistance and fire safety standards through provincial department inspections that now mandate third-party structural verification for buildings exceeding twenty stories. Industrial developers are responding by specifying higher-grade concrete mixes and redundant structural redundancy that exceed minimum code requirements to accelerate permitting approval. The policy is tightening technical barriers for smaller contractors lacking in-house engineering verification capacity.
Facility management services are unbundling from construction contracts as captive developer portfolios expand, creating standalone revenue streams for contractors with operational maintenance capabilities. Industrial park operators in Bac Ninh are separating ten-year maintenance agreements from initial build contracts, favoring contractors that retain specialized MEP servicing divisions. The shift is most visible in foreign-invested manufacturing facilities where operational continuity requirements override first-cost minimization in vendor selection.
Vietnam Construction Market Segmentation
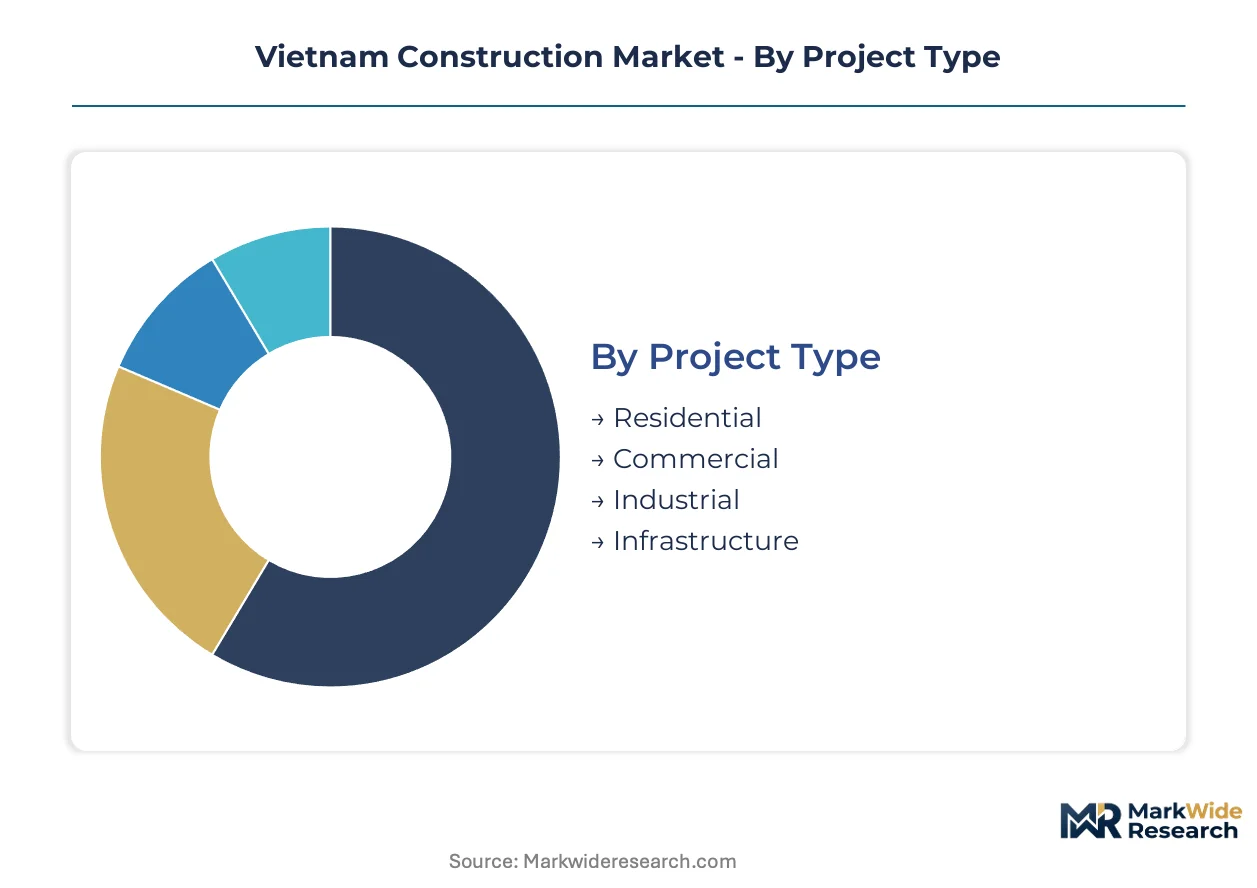
Segmentation in Vietnam's construction market reveals how project economics, material specifications, and service bundling create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity requirements that shape contractor specialization strategies.
Project Type:
Cycle times vary dramatically across project types, with industrial factory shells turning over in 8-12 months versus infrastructure corridors requiring 3-5 year execution windows.
- Residential:Mid-rise housing in Ho Chi Minh City and Hanoi drives concrete volume through repetitive floor plates and standardized precast components. Private developers compress design cycles to capture urbanization-driven absorption rates.
- Commercial:High-rise office and retail frameworks demand complex curtain-wall integration and extended foundation systems. Steel structural share climbs here as developers prioritize column-free spans and accelerated vertical construction.
- Industrial:Factory frameworks in Binh Duong and Bac Ninh provinces concentrate foreign manufacturing demand. Quick-delivery specifications favor portal steel frames and prefabricated cladding systems.
- Infrastructure:Transport corridors and utility networks require state-backed financing and multi-year mobilization. QCVN technical standards mandate seismic-resistant bridge piers and tunnel linings that exceed private-sector specifications.
Residential dominates installed base. Industrial is where expansion concentrates.
Material Type:
Cost tiers separate segments, with concrete maintaining unit-cost advantage in mid-rise applications while steel commands premium positioning in high-span and high-rise frameworks.
- Concrete:Reinforced concrete formulations dominate Vietnamese construction through domestic cement capacity and established formwork trades. Precast technology migration is compressing floor-cycle times in Hanoi residential towers.
- Steel:Structural steel sections enable longer spans and faster erection for commercial high-rises and industrial frameworks. Import dependency for rolled sections exposes project budgets to currency volatility.
- Wood:Timber framing concentrates in low-rise resort and residential applications where aesthetic specifications override cost minimization. Domestic plantation supply remains underdeveloped versus Southeast Asian neighbors.
- Glass:Curtain-wall glazing systems integrate with steel and concrete superstructures for commercial envelopes. QCVN 09:2023 thermal performance mandates are upgrading specification grades.
Concrete anchors volume share. Steel is climbing the fastest as high-rise and industrial specifications advance.
Service Type:
Customer type dynamics reveal design-build integration displacing traditional handoffs as developers seek single-point accountability for schedule risk.
- Design:Architectural and structural design services are consolidating under contractor umbrellas to compress procurement cycles. In-house design capability differentiates bids on speed-to-completion.
- Engineering:Structural verification and MEP engineering face capacity constraints as QCVN mandates tighten third-party review requirements for buildings exceeding twenty stories.
- Construction:Physical assembly execution remains fragmented through labor-only subcontractor networks, creating quality control friction that integrated contractors seek to capture.
- Project Management:Owner-representative services are unbundling from construction contracts as captive developer portfolios expand, particularly for industrial park operators separating ten-year maintenance agreements.
Construction captures the revenue base. Design-build integration is where margin expansion concentrates.
End User:
Volume concentration varies by procurement sophistication, with institutional investors demanding outcome-based contracts while government agencies navigate extended technical review cycles.
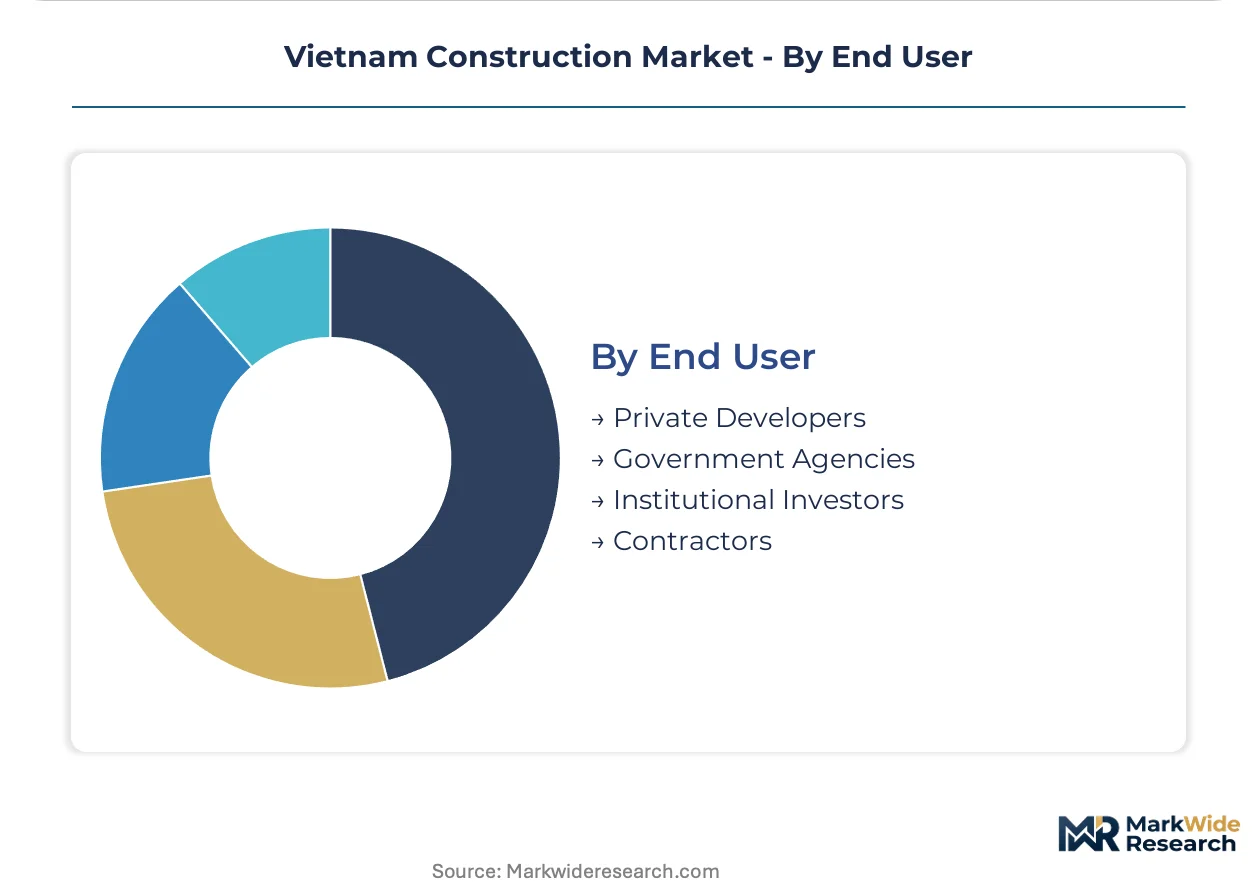
- Private Developers:Urban residential and commercial project sponsors in Ho Chi Minh City and Hanoi prioritize schedule certainty over unit-cost minimization, rewarding contractors with precast and design-build capabilities.
- Government Agencies:Ministry of Transport and provincial infrastructure authorities deploy state-backed financing for transport corridors. Permitting velocity variation across provincial departments creates timeline uncertainty.
- Institutional Investors:Foreign manufacturing sponsors and logistics operators in Bac Ninh specify operational continuity requirements that override first-cost considerations in vendor selection.
- Contractors:Self-performed development by integrated construction groups creates captive demand for building materials and facility management services.
Private developers dominate transaction velocity. Institutional investors are where contract value expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in southern Vietnam show the highest price sensitivity, driven by competitive contractor density and standardized precast specifications. Northern buyers prioritize schedule certainty over unit costs, reflecting tighter permitting cycles and foreign manufacturing deadlines. Central provinces exhibit elastic demand as infrastructure investment lags industrial relocation.
Ho Chi Minh City
Mid-rise residential developers dominate construction demand through repetitive floor plates and accelerated absorption timelines. Vietnam's Ministry of Construction enforces QCVN 09:2023 energy efficiency codes that mandate upgraded envelope performance across new commercial stock. Binh Duong province, adjacent to the metro, concentrates industrial park construction as electronics suppliers establish Vietnam production bases.
Hanoi
High-rise residential towers drive precast concrete technology adoption to compress floor-cycle times from seven days to four days. Provincial construction departments under the Ministry of Construction mandate third-party structural verification for buildings exceeding twenty stories. Bac Ninh province anchors northern industrial demand through foreign manufacturing facilities requiring quick-delivery factory frameworks.
Da Nang
Logistics and light manufacturing investment is activating greenfield construction demand outside saturated southern and northern hubs. Central Coast development corridors face extended technical review cycles that stall project mobilization relative to major metros. Quang Nam province attracts industrial park operators separating ten-year maintenance agreements from initial build contracts.
Can Tho
Mekong Delta infrastructure corridors require state-backed financing and multi-year mobilization for transport networks. Provincial permitting velocity variation creates timeline uncertainty compared to Ho Chi Minh City regulatory efficiency. The region's construction demand concentrates in residential stock additions capturing secondary urbanization flows.
Hai Phong
Port-adjacent industrial frameworks favor portal steel frames and prefabricated cladding systems for rapid deployment. Foreign logistics operators specify operational continuity requirements that override first-cost considerations in vendor selection. Cat Hai district and Dinh Vu-Cat Hai economic zone concentrate manufacturing construction demand.
Vietnam Construction Market Competitive Environment
Capability concentration sits with integrated contractors possessing in-house design verification and precast production; scale advantage sits with diversified construction groups commanding multi-province labor networks. The market structures around three tiers: national champions with captive material supply, regional specialists dominating single metros, and foreign-backed entrants targeting industrial park specifications. Two competitive moves define positioning: design-build integration compressing traditional engineering-construction handoffs, and backward integration into building materials supply securing margin control.
Within the national champion tier, Coteccons Construction JSC and Hoa Binh Construction Group JSC exemplify divergent specialization strategies—one leveraging precast concrete technology leadership, the other sustaining high-rise residential execution dominance across southern Vietnam. Vinaconex JSC anchors the state-linked segment through backward integration into building materials supply. These three occupy positions that reward either speed-to-completion differentiation or captive portfolio servicing.
| Leading Market Players |
|---|
| Central Construction JSC |
| Construction Company No. 1 (CC1) |
| Coteccons Construction JSC |
| Fecon Corp JSC |
| Newtecons Construction Company |
| Hoa Binh Construction Group JSC |
| Vinaconex JSC |
| An Phong Construction |
| Delta Construction Group |
| Others |
Value Chain & Pricing Dynamics
Steel import dependency from China and South Korea determines both pricing tier spreads and supply chain shape in Vietnam's construction sector, compressing margins for contractors locked into fixed-price contracts while rewarding those with captive material sourcing or precast fabrication capabilities.
Pricing Analysis
Aftermarket facility management revenue drives lifetime value as industrial park operators in Bac Ninh separate ten-year maintenance agreements from initial construction contracts. Three-tier pricing structure across premium, standard, and economy levels separates design-build integrators from traditional engineer-procure-construct contractors. Pricing pressure stems from currency volatility affecting imported structural steel sections, with foreign-invested manufacturing facilities showing least price sensitivity due to operational continuity requirements.
Supply Chain Analysis
Supplier-financing through extended payment terms dominates upstream relationships as domestic cement producers scale capacity against BIS-aligned technical standards. Raw material flows draw from China for structural steel sections, South Korea for high-grade rolled products, and domestic sources for cement and aggregates. Single-source vulnerability concentrates in specialized precast component molds and curtain-wall glazing systems. Distribution runs through provincial construction material hubs with direct-to-site delivery for large-scale projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Facility management services represent the fastest-expanding recurring-revenue layer, with captive developer portfolios and industrial park maintenance agreements outpacing traditional construction contract growth across the analysis window.
For Market Incumbents: Build captive precast production capacity as the defensive moat against margin compression from imported steel volatility. Hoa Binh Construction Group and Coteccons Construction JSC demonstrate how backward integration into building materials supply secures cost control. Absorb design verification capabilities to accelerate QCVN permitting timelines that stall smaller competitors.
For New Entrants and Emerging Players: Establish a beachhead in Central Coast industrial corridors where Quang Nam and Binh Dinh provinces exhibit elastic demand and lower contractor density. Target logistics and light manufacturing facilities requiring quick-delivery portal steel frames. Differentiate through BIM-enabled project management that addresses implementation skill gaps.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated contractors with in-house design verification and multi-province labor networks. Five-to-ten year viability hinges on exposure to state-backed infrastructure financing versus private developer-led residential volume. Watch QCVN code enforcement consistency across provincial jurisdictions as the inflection indicator for execution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Integration | Compresses traditional engineering-construction handoffs, rewarding Coteccons with single-point accountability contracts. |
| Precast Production Scale-Up | Enables floor-cycle compression from seven days to four days in Hanoi residential towers. |
| Facility Management Unbundling | Creates standalone revenue streams from Bac Ninh industrial park ten-year maintenance agreements. |
| Backward Integration | Vinaconex anchors position through captive building materials supply controlling margin capture. |
| Central Coast Geographic Expansion | Opens greenfield demand in Quang Nam and Binh Dinh outside saturated southern and northern hubs. |
Study Parameters
The analysis maps residential, commercial, industrial, and infrastructure project types, each validated through contractor project directors, developer procurement leads, provincial construction department officials, and facility management operators. Primary interviews combined with secondary validation from Ministry of Construction QCVN filings, BIS technical standards documentation, provincial permitting databases, and industrial park development records. Bottom-up project pipeline assessment triangulates against top-down macro construction output indicators.
Assumptions held fixed include QCVN 09:2023 enforcement trajectory and foreign manufacturing relocation pace, while currency volatility and provincial permitting velocity were modeled as variable stress conditions. Segmentation dimensions span project type, material specification, service bundling, and end-user procurement sophistication. CAGRs derive from installed base growth and replacement cycle analysis across concrete, steel, and precast component throughput.
Stress conditions across steel import pricing bands, provincial regulatory enforcement consistency, and skilled labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Macroeconomic deviation, regulatory enforcement shifts, or precast technology adoption acceleration would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Qatar Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Construction Market
Building Construction
Oman Construction Market
Building Construction
Egypt Residential Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
GCC Cement Market
Building Construction
UK Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
GCC Green Buildings Market
Building Construction
Indonesia Construction Market
Building Construction
North America Prefabricated Buildings Market