
 United Arab Emirates Infrastructure Market | 2026-2036
United Arab Emirates Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Infrastructure Market Insights
Premium infrastructure contracts in the United Arab Emirates is rebalancing toward complex, technology-integrated developments while commodity road and bridge work faces margin compression. Bechtel leverages its engineering depth to dominate nuclear and mega-transport schemes. Arabtec Holding anchors residential and commercial construction across Dubai and Abu Dhabi. ALEC Engineering & Contracting specializes in high-rise and hospitality infrastructure where technical complexity commands premium pricing.
Infrastructure encompasses the physical systems and facilities that enable economic activity, including transport networks, utilities, and built environments designed to specified load capacities, seismic resilience ratings, and service life targets spanning fifty to one hundred years. Concrete remains the dominant material by volume, though prefabricated elements gain share as modular construction reduces site labor and accelerates project schedules. Government end users command the largest project pipeline, while private sector participation expands under public-private partnership frameworks that transfer operational risk to contractors. Design and construction services capture the majority of value, though maintenance contracts lengthen revenue visibility for incumbents.
MOHAP and the UAE's federal building codes enforce fire safety, accessibility, and environmental performance standards that elevate material specifications and contractor qualification thresholds. Dubai Municipality's green building regulations and Abu Dhabi's Estidama Pearl rating system mandate water and energy efficiency, directing demand toward low-carbon concrete and smart infrastructure technologies. Stakeholders must monitor how evolving federal procurement rules and emirate-level sustainability mandates reshape contractor eligibility and project economics.
Market Dynamics
Abu Dhabi's dual carbon goals and Dubai's building efficiency mandates are fundamentally reshaping material specifications across the UAE infrastructure sector. Contractors now face escalating qualification thresholds tied to environmental performance standards.
Growth Catalysts
- Estidama Pearl Rating System:Abu Dhabi's mandatory sustainability framework drives demand for low-carbon concrete and water-efficient systems in new industrial zone developments.
- Smart City Deployments:Dubai's logistics corridor expansion integrates IoT-enabled transport networks that require technology-integrated construction methodologies.
- Federal PPP Frameworks:Risk-transfer mechanisms under evolving procurement rules expand private sector participation in utility and transport assets.
Market Restraints
- Steel and Cement Input Volatility:Regional supply concentration exposes project economics to commodity price swings from GCC producers.
- Seismic Resilience Upgrades:Federal building codes now mandate enhanced structural ratings that extend engineering timelines and certification cycles.
- Precast Module Substitution:Modular construction methods reduce conventional cast-in-place concrete volumes for standardized building types.
Strategic Opportunities
- Al Dhafra Industrial Zone:Abu Dhabi's underdeveloped western region offers greenfield logistics and manufacturing infrastructure capacity.
- Digital Twin Convergence:Integration of BIM platforms with real-time sensor networks creates new service revenue streams for contractors.
- Nuclear Maintenance Contracts:Long-term operational risk transfer agreements at Barakah extend revenue visibility beyond construction phases.
Industry Challenges
- BIM-Enabled Project Management:Skill scarcity in digital construction workflows limits contractor readiness for complex integrated developments.
- Estidama Certification Timelines:Pearl rating documentation requirements extend pre-construction phases and compress execution windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Infrastructure Market |
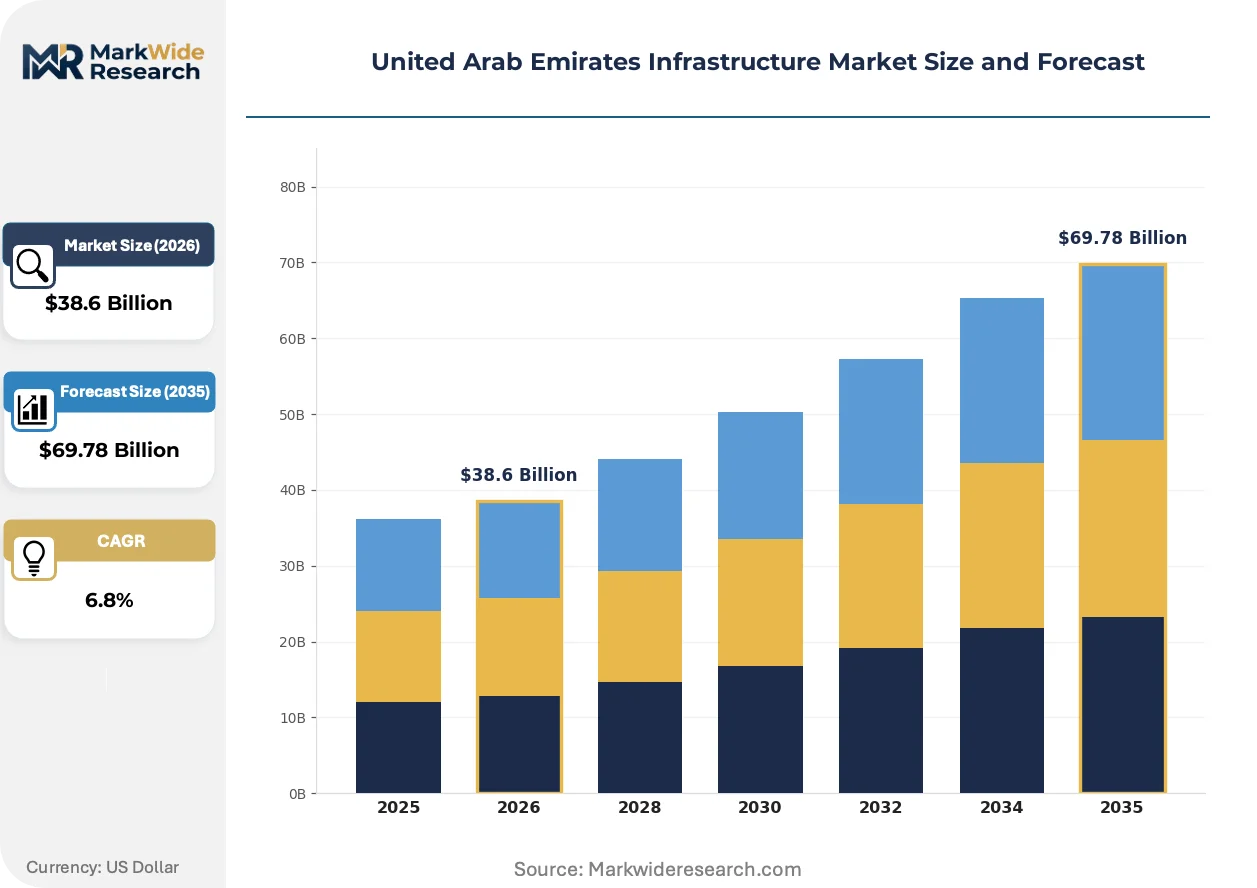
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Bridges, Railways, Airports Material: Concrete, Steel, Asphalt, Prefabricated Elements Service Type: Design, Construction, Maintenance, Consultancy End User: Government, Private Sector, Contractors, Utilities |
| Companies Covered | Bechtel, Arabtec Holding, Al Habtoor Group, Fluor Corporation, Aegion Corporation, Drake & Scull International, ALEC Engineering & Contracting, Arabian Construction Company (ACC), Jacobs, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Infrastructure Market Trends and Innovations
Digital construction methodologies and sustainability mandates are converging to redefine competitive capability across UAE infrastructure. Technology integration now separates premium contract winners from commodity players.
Building Information Modeling (BIM) is unifying design, procurement, and asset management workflows across mega-transport schemes. Abu Dhabi Department of Municipalities and Transport mandates BIM Level 2 compliance for projects exceeding defined thresholds. This technology compression eliminates information silos between engineering teams and facility operators.
Dubai Municipality's green building regulations now enforce minimum energy performance standards that exceed baseline federal requirements. The Al Sa'fat rating system mandates solar readiness and cooling load limits for all new commercial developments. High-rise and hospitality segments face the steepest compliance ramps as existing design templates require fundamental redesign.
Public-private partnership procurement models are displacing traditional design-bid-build contracts for complex infrastructure assets. Government end-users now prioritize operational risk transfer over lowest-bid selection, reshaping contractor capability requirements. This shift concentrates most visibly in Dubai's logistics corridor and Abu Dhabi's industrial zone pipelines.
United Arab Emirates Infrastructure Market Segmentation
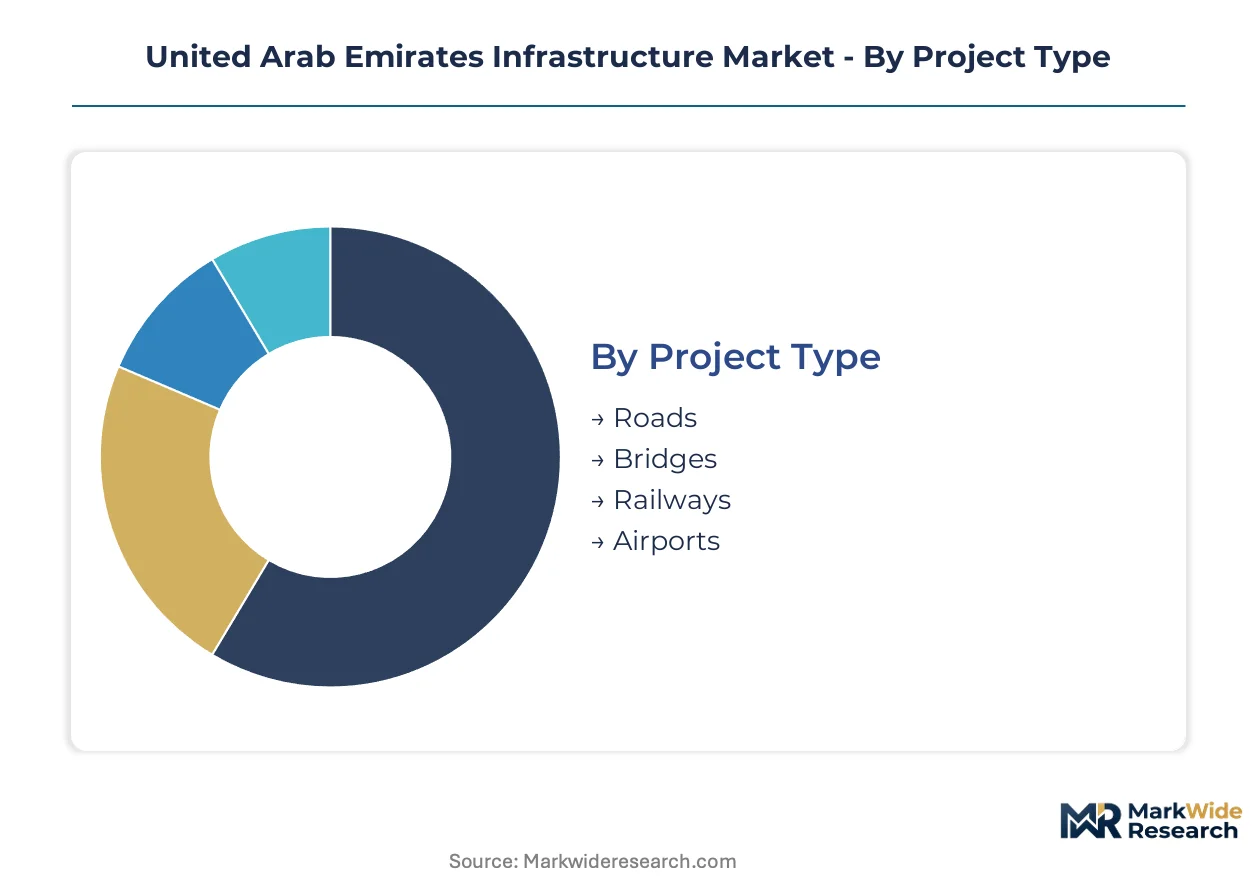
Segmentation in UAE infrastructure reveals how procurement concentration, material specifications, and service complexity diverge across emirate-level mandates. Understanding these splits exposes where contractor capabilities must align with Dubai's logistics corridor demands versus Abu Dhabi's industrial zone requirements.
Project Type:
Standardized corridor work competes with bespoke mega-transport schemes for capital allocation across the seven emirates.
- Roads:Arterial highway networks dominate volume, with Dubai's logistics corridor expansion driving demand for multi-lane freight routes capable of handling heavy-vehicle load ratings. Federal procurement concentrates this segment in inter-emirate connectivity projects.
- Bridges:Complex structural engineering defines this tier, where seismic resilience upgrades under MOHAP-mandated building codes extend design timelines. Signature crossings over Dubai Creek and Abu Dhabi mangrove corridors command premium contractor qualifications.
- Railways:Etihad Rail's freight and passenger networks integrate with GCC-wide connectivity schemes.
- Airports:Al Maktoum International expansion and Abu Dhabi International upgrades anchor aviation infrastructure pipelines.
Most installed capacity flows through Roads. Expansion is steepest in Railways.
Material:
Cost tiers separate commodity bulk supplies from specification-grade inputs tied to Estidama Pearl certification thresholds.
- Concrete:Low-carbon formulations now dominate Abu Dhabi's industrial zone specifications under dual carbon goals. Dubai Municipality's green building regulations accelerate demand for supplementary cementitious materials that reduce embodied carbon in high-rise foundations.
- Steel:Structural rebar and high-strength sections face regional GCC supply concentration, exposing project economics to input volatility. Seismic resilience upgrades mandate enhanced grade specifications that elevate procurement costs.
- Asphalt:Warm-mix technologies gain share in road surfacing contracts.
- Prefabricated Elements:Modular construction methods reduce site labor and compress schedules for standardized building types.
Volume leadership sits with Concrete. Specification complexity climbs fastest in Prefabricated Elements.
Service Type:
Customer type splits the market between government-mandated design-build contracts and private sector consultancy engagements.
- Construction:Execution risk concentrates in this phase, where public-private partnership frameworks now transfer operational liability to contractors. Dubai's logistics corridor and Abu Dhabi's Al Dhafra Industrial Zone anchor the largest capital deployment.
- Maintenance:Long-term operational contracts at Barakah nuclear and transport assets extend revenue visibility beyond construction completion. Federal procurement rules increasingly favor lifecycle performance over lowest-bid selection.
- Design:BIM Level 2 compliance mandates from Abu Dhabi Department of Municipalities and Transport reshape engineering workflows.
- Consultancy:Advisory services cluster around sustainability certification and digital twin integration.
Revenue concentration favors Construction. Contract duration advantages are expanding most quickly in Maintenance.
End User:
Geography drives divergence between federal pipeline control and emirate-level procurement autonomy.
- Government:Federal and emirate-level entities command the project pipeline, with Dubai's logistics corridor and Abu Dhabi's industrial zones representing the largest capital commitments. Procurement rules under evolving PPP frameworks prioritize risk transfer over cost minimization.
- Private Sector:Developer-led commercial and hospitality projects face Dubai Municipality's Al Sa'fat green building mandates that exceed baseline federal requirements. High-rise segments encounter the steepest compliance ramps.
- Contractors:Tier-one firms self-perform capability development through captive project pipelines.
- Utilities:Water and power infrastructure operators expand asset bases under federal privatization programs.
Project origination concentrates with Government. Procurement flexibility is broadening fastest in Private Sector.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools concentrated in Dubai and Abu Dhabi anchor the UAE's infrastructure delivery capacity. Federal procurement rules and emirate-level sustainability mandates create divergent qualification requirements across the seven emirates.
Dubai
The logistics corridor expansion drives demand for multi-lane freight routes and IoT-enabled transport networks. Dubai Municipality's Al Sa'fat green building regulations enforce minimum energy performance standards exceeding federal baselines. The Jebel Ali industrial cluster concentrates high-rise and hospitality projects facing steep compliance ramps.
Abu Dhabi
Dual carbon goals reshape material specifications across industrial zone developments. MOHAP and the Estidama Pearl rating system mandate water-efficient systems and low-carbon concrete formulations. The Al Dhafra western region offers greenfield logistics and manufacturing infrastructure capacity.
Sharjah
Mid-market commercial and residential construction segments concentrate procurement activity. Federal building codes enforced through MOHAP elevate fire safety and accessibility standards. The Hamriyah Free Zone industrial cluster attracts manufacturing-linked infrastructure investment.
Northern Emirates
Ras Al Khaimah and Fujairah anchor tourism and logistics infrastructure pipelines outside the two dominant emirates. Federal PPP frameworks expand private sector participation in utility assets. Port and industrial zone developments in Fujairah leverage strategic Gulf of Oman positioning.
United Arab Emirates Infrastructure Market Competitive Landscape
Capital-heavy engineering conglomerates compete with asset-light specialized contractors for premium infrastructure contracts. Market structure concentrates around tier-one firms with nuclear, mega-transport, and smart city credentials. Three archetypes dominate: integrated engineering-procurement-construction operators, high-rise and hospitality specialists, and maintenance-focused lifecycle contractors. Competitive moves center on public-private partnership qualification and BIM-enabled project management capability acquisition.
Among US-based engineering conglomerates, Bechtel and Fluor Corporation exemplify capital-heavy archetypes with nuclear and mega-transport scheme dominance. ALEC Engineering & Contracting represents the high-rise and hospitality specialist tier where technical complexity commands premium positioning. Arabtec Holding anchors the residential and commercial construction segment across Dubai and Abu Dhabi emirates.
| Leading Market Players |
|---|
| Bechtel |
| Arabtec Holding |
| Al Habtoor Group |
| Fluor Corporation |
| Aegion Corporation |
| Drake & Scull International |
| ALEC Engineering & Contracting |
| Arabian Construction Company (ACC) |
| Jacobs |
| Others |
Pricing and Supply Chain Analysis
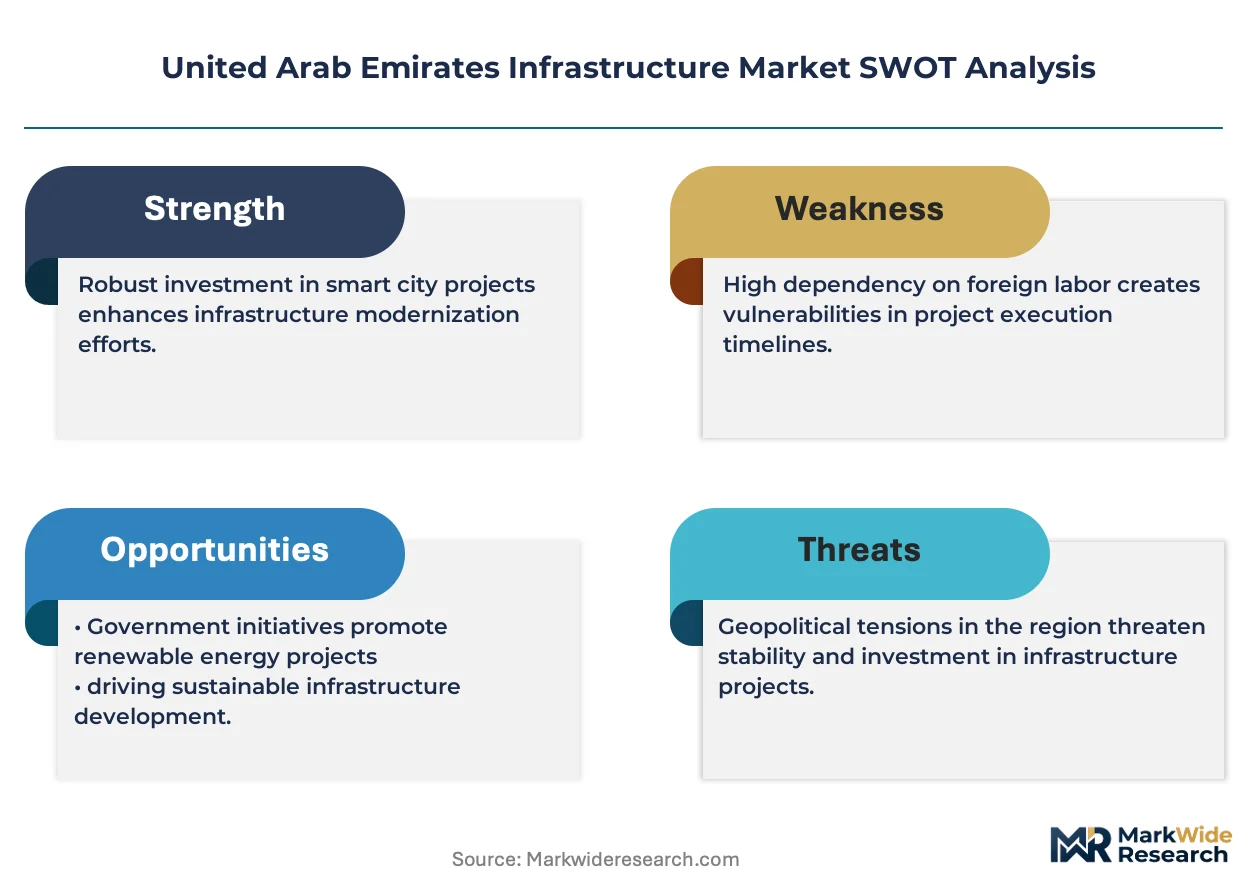
Engineering talent pools concentrated in Dubai and Abu Dhabi create labor-cost differentials that widen pricing-tier spreads between premium technology-integrated contracts and commodity roadwork. Estidama Pearl certification requirements and BIM Level 2 compliance mandates elevate contractor qualification thresholds, compressing margins for undifferentiated players while sustaining premium pricing for integrated service providers.
Pricing Analysis
Bundled design-build-maintain contracts command substantial premiums over unbundled procurement, particularly for nuclear and mega-transport schemes where operational risk transfer reshapes contractor economics. Price differentiation rests on BIM capability depth and Estidama certification status, with Pearl-rated contractors capturing margin advantages in Abu Dhabi's industrial zones. Cost compression in standardized road and bridge segments intensifies as modular construction methods displace conventional cast-in-place volumes. Government end-users exhibit lowest price sensitivity due to lifecycle performance procurement rules, while private developers face acute margin pressure from Al Sa'fat compliance ramps.
Supply Chain Analysis
Workforce availability constraints in UAE manufacturing geographies tether project execution timelines to expatriate labor inflows from India, Pakistan, and the Philippines. Raw material dependencies center on GCC-sourced cement and steel rebar, with regional supply concentration exposing economics to commodity price swings. Single-source vulnerability runs through structural steel sections from Saudi and Omani mills. Distribution feeds from integrated engineering-procurement-construction operators through direct site delivery, bypassing traditional wholesale channels for specification-grade inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE infrastructure sector functions as a regulatory compounder, where MOHAP building code enforcement and emirate-level sustainability mandates continuously escalate contractor qualification barriers. Dubai Municipality's Al Sa'fat regulations and Abu Dhabi's dual carbon goals generate durable demand for certified, technology-capable service providers.
For Market Incumbents: Cement BIM-enabled project management capabilities through targeted capability acquisition in digital twin integration, defending against modular construction substitution in standardized building segments. Deepen upstream control over low-carbon concrete supply chains to meet Estidama Pearl formulation requirements. Prioritize nuclear maintenance contract extensions at Barakah to lengthen revenue visibility beyond construction completion.
For New Entrants and Emerging Players: Enter via Al Dhafra Industrial Zone greenfield logistics capacity, where greenfield development timelines and lower incumbent saturation create penetrable white space. Target consultancy services around sustainability certification and digital twin advisory, segments where technical complexity sustains premium positioning without capital-heavy EPC asset requirements. Pursue public-private partnership qualification as the primary go-to-market pathway.
For Investors and Strategic Acquirers: Integrated engineering-procurement-construction operators with nuclear credentials are the most active acquirer in this space, consolidating BIM-capable mid-tier firms to fill capability gaps. Long-term viability favors lifecycle contractors with maintenance revenue streams extending beyond construction phases. Monitor federal PPP framework evolution and emirate-level procurement rule changes as inflection indicators for contract flow concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| BIM Capability Acquisition | Abu Dhabi Department of Municipalities and Transport mandates Level 2 compliance for threshold projects. |
| Low-Carbon Concrete Backward Integration | Estidama Pearl rating system drives specification-grade formulation demand in industrial zones. |
| Nuclear Maintenance Contract Extension | Barakah operational risk transfer agreements lengthen revenue visibility for qualified incumbents. |
| Al Dhafra Industrial Zone Presence | Abu Dhabi's western region offers greenfield logistics capacity outside saturated Dubai corridors. |
| Digital Twin Service Development | Integration of BIM platforms with real-time sensor networks creates new advisory revenue streams. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and the Northern Emirates, with primary inputs from each emirate's construction ecosystem. Primary interviews engaged EPC contract directors, municipal planning officers, sustainability certification consultants, and procurement leads at federal infrastructure agencies. Secondary validation drew from Dubai Municipality regulatory filings, Abu Dhabi Department of Municipalities and Transport project databases, Etihad Rail development disclosures, and federal PPP framework documentation. Bottom-up project pipeline aggregation triangulated against top-down emirate-level capital expenditure assessments.
Rate-of-change decomposition separated volume growth from price evolution across the projection horizon, with analytical frameworks modeling project type, material specification tier, service complexity, and end-user procurement channel. Segmentation dimensions included transport modality, concrete grade certification, construction versus maintenance revenue, and government versus private origination. CAGRs derived from fitted trend extrapolation adjusted for regulatory milestone impacts and material substitution dynamics. Forecast inputs incorporated BIM adoption curves, Estidama certification velocity, and modular construction penetration rates.
Inputs from municipal regulatory databases and federal procurement portals were available through the study window; gaps in private developer pipeline visibility and unannounced PPP tender schedules introduce uncertainty bands around near-term contract flow projections. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and labor inflow stability. Practitioners should monitor federal building code amendment cycles and emirate-level carbon target revisions for early signals of qualification threshold shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Vertical Garden Construction Market
Building Construction
Thailand Construction Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Global Modular Fabrication Market
Building Construction
China Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Dominican Republic Construction Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Turkey Construction Market
Building Construction
Saudi Arabia Construction Market