
 Japan Construction Market | 2026-2036
Japan Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Construction Market Outlook
Government infrastructure agencies is redrawing contractor selection criteria across Japan's public works pipeline. Taisei Corporation leverages its integrated design-build capability to capture complex urban renewal mandates. Kajima Corporation anchors its position through sustained investment in seismic engineering R&D and robotics-assisted construction.
Japan construction encompasses the physical assembly of buildings and civil structures using concrete, steel, wood, and glass materials, governed by JIS structural standards and the Building Standard Law's seismic performance requirements, serving residential habitation, commercial activity, industrial production, and public infrastructure functions. Residential project types currently lead volume as demographic shifts drive compact urban housing demand, while sustainable construction methods represent the fastest-expanding segment as METI decarbonization targets reshape procurement specifications. Prefabricated methods occupy a mature but evolving niche where Sumitomo Forestry and Daiwa House compete on manufacturing scale and supply chain integration.
METI enforces energy efficiency standards through the CASBEE green building certification framework, while the Ministry of Land, Infrastructure, Transport and Tourism (MLIT) administers the Building Standard Law's seismic retrofit mandates, collectively redirecting capital toward low-carbon materials and disaster-resilient designs. PMDA and JIS standards additionally govern fire safety and structural material specifications, tightening compliance costs for conventional concrete-heavy approaches. Stakeholders must monitor how upcoming revisions to the Act on Promotion of Global Warming Countermeasures reshape allowable embodied carbon thresholds across public procurement.
Market Dynamics
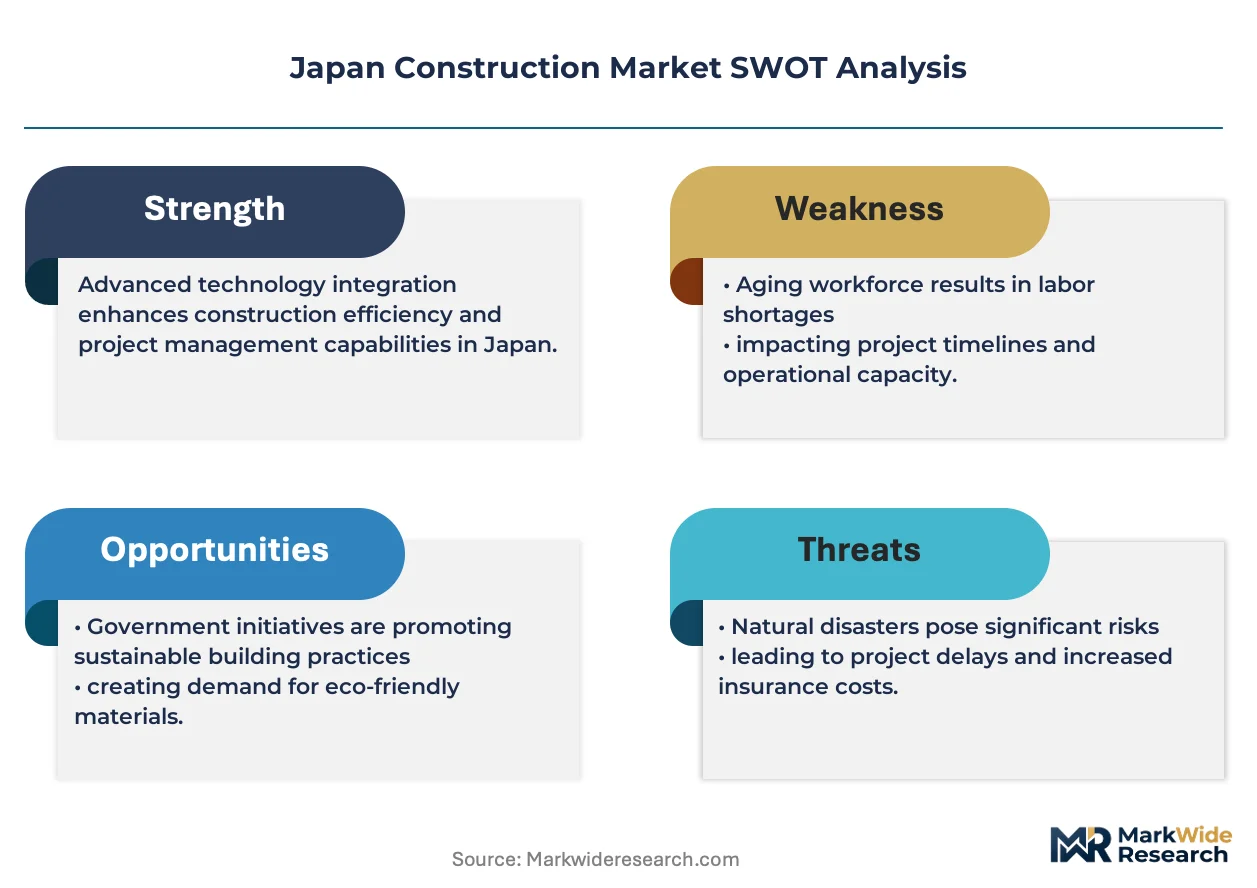
Japan's construction sector is undergoing a fundamental reconfiguration as METI's carbon-neutral building codes force material substitution away from conventional concrete toward cross-laminated timber and low-emission alternatives, compressing traditional contractor margins while opening procurement pathways for integrated design-build specialists.
Growth Catalysts
- Seismic Retrofit Mandates:MLIT's Building Standard Law enforcement is accelerating public infrastructure renewal across aging bridges and highways. Municipal agencies are bundling resilience upgrades into transit-oriented development corridors.
- Cross-Laminated Timber Adoption:Mass timber engineering is penetrating mid-rise commercial and institutional segments as fire-rated CLT systems gain JIS certification. Prefabrication yards are retooling for hybrid steel-timber structural packages.
- Greater Tokyo Urban Redevelopment:The capital region's mixed-use pipeline around Shibuya, Toranomon, and Shinagawa stations is concentrating demand for high-density, transit-integrated construction formats.
Market Restraints
- Domestic Cement Price Volatility:Energy-intensive clinker production faces input cost pressure from electricity tariffs and carbon levies, squeezing ready-mix concrete economics for mid-tier contractors.
- Specialized Timber Supply Concentration:Structural-grade Japanese cedar and imported spruce sourcing clusters in Hokkaido and British Columbia, creating vulnerability to weather-driven harvest disruptions.
- Skilled Labor Density Limits:Aging ironworker and formwork carpenter cohorts constrain project velocity without equivalent robotics deployment, capping throughput for conventional cast-in-place methods.
Strategic Opportunities
- Osaka-Kansai Expo Infrastructure:The 2025 international exposition is unlocking integrated district energy and modular hospitality construction contracts with compressed delivery timelines.
- Robotics-Assisted Assembly:Convergence of automated rebar tying and 3D site surveying is reducing skilled labor dependency for high-rise structural frames.
- Prefabricated Bathroom Unit Export:Japanese wet-module engineering standards are gaining traction in Southeast Asian hospital and senior care facility procurement.
Industry Challenges
- CASBEE Certification Timeline Compression:Green building documentation requirements are extending pre-construction phases by 4-6 months, straining project finance structures.
- Legacy BIM System Integration:Mid-size contractors face data interoperability friction when connecting proprietary design software with MLIT's digital submission portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Construction Market |
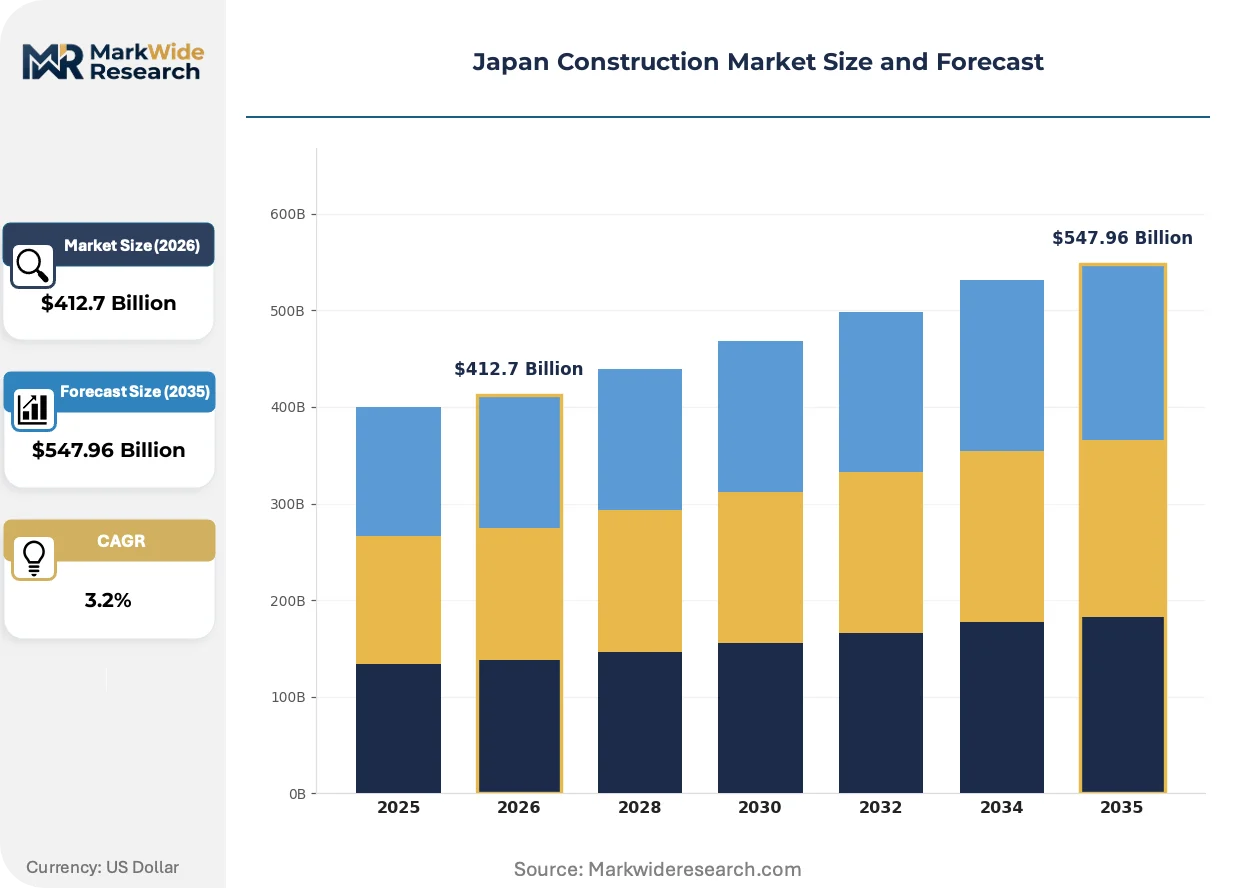
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $547.96 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Wood, Glass Construction Method: Traditional, Modular, Prefabricated, Sustainable End User: Government, Private Developers, Contractors, Architects |
| Companies Covered | Taisei Corporation, Maeda Corporation, Obayashi Corporation, Sekisui House Ltd, Daiwa House Industry Co., Ltd., Kajima Corporation, Takenaka Corporation, Sumitomo Forestry Co. Ltd, Shimizu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Construction Market Strategic Shifts
Digital fabrication and material science advances are compressing traditional construction timelines while METI's decarbonization framework redefines permissible building assemblies. Three developments are restructuring competitive capability requirements.
Cross-laminated timber is decomposing the steel-concrete duopoly in mid-rise commercial construction. Developers in Yokohama and Fukuoka are specifying 12-16 story hybrid timber cores for office and residential towers. The technology is decomposing conventional structural engineering workflows by enabling off-site prefabrication of load-bearing wall panels.
METI's 2024 revision to the Act on Promotion of Global Warming Countermeasures is tightening embodied carbon thresholds for public building procurement. General contractors must now submit whole-life carbon assessments alongside conventional bids. Institutional clients in healthcare and education segments are extending these requirements to private developments through joint-venture structures.
Integrated project delivery contracts are displacing traditional design-bid-build sequences for complex urban renewal mandates. Real estate investment trusts and municipal redevelopment agencies are consolidating vendor relationships around single-source accountability. The shift is most pronounced in Tokyo's five major station-adjacent districts where land assembly complexity demands coordinated design and construction execution.
Japan Construction Market Segmentation
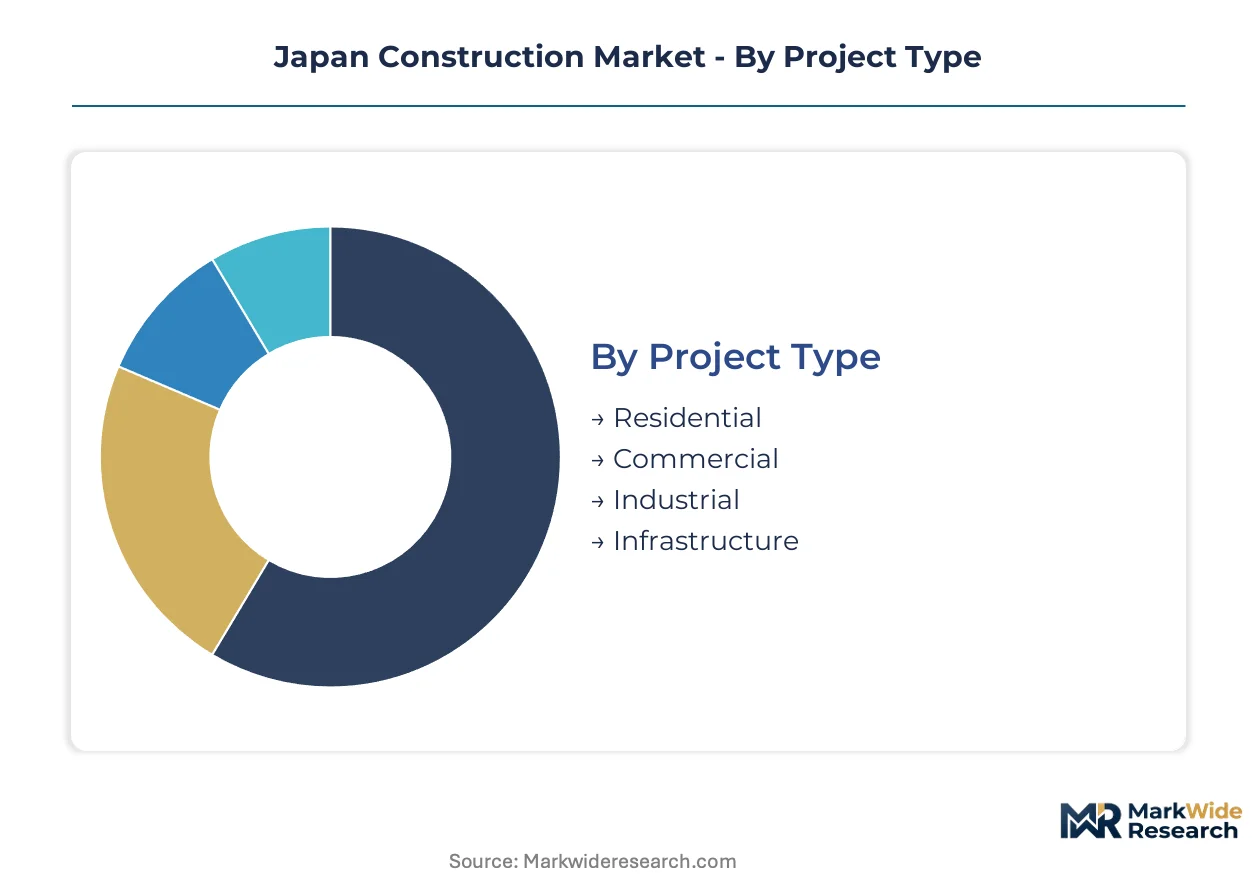
Japan's construction market fragments across structural methodologies and procurement channels that determine contractor capability requirements and margin profiles. Understanding these segment boundaries clarifies where METI decarbonization mandates and MLIT seismic standards reshape competitive positioning.
Project Type:
Residential and commercial work clusters in Greater Tokyo's urban corridor, while infrastructure and industrial spreads across prefectural renewal programs.
- Residential:Compact urban housing dominates volume as demographic shifts concentrate demand in Tokyo, Osaka, and Fukuoka metro areas. Kajima and Daiwa House capture share through seismic-engineered mid-rise formats aligned with MLIT's Building Standard Law retrofit timelines.
- Commercial:Transit-oriented mixed-use towers around Shibuya, Toranomon, and Shinagawa stations drive specification intensity. Developers bundle office, retail, and hospitality functions into integrated design-build contracts with compressed delivery schedules.
- Industrial:Semiconductor fabrication facilities and pharmaceutical cleanrooms in Kyushu and Tohoku regions require vibration-isolated structural systems. METI's industrial cluster subsidies are redirecting capital toward these specialized builds.
- Infrastructure:Highway bridges, port facilities, and flood control systems span national renewal pipelines. MLIT's seismic retrofit mandates are accelerating replacement cycles for aging concrete structures.
Residential holds the largest share; momentum sits with commercial as station-adjacent redevelopment intensifies.
Material Type:
Cost tiers separate commodity bulk materials from specification-grade alternatives governed by JIS certification requirements.
- Concrete:Ready-mix formulations face margin compression from electricity tariffs and carbon levies on clinker production. Contractors are substituting blast-furnace slag and fly ash blends to meet METI's embodied carbon thresholds.
- Steel:High-strength structural sections anchor high-rise frames in Tokyo's dense districts. Nippon Steel and JFE Holdings supply fire-rated beams compliant with revised Building Standard Law thermal performance standards.
- Wood:Cross-laminated timber and glulam systems are penetrating mid-rise commercial segments as JIS fire certification expands. Hokkaido-sourced Japanese cedar and British Columbia spruce supply face weather-driven harvest volatility.
- Glass:High-performance curtainwall units with thermal breaks dominate commercial tower specifications. Double and triple-glazed assemblies align with CASBEE energy efficiency scoring requirements.
Concrete retains volume leadership; wood materials are climbing the fastest as mass timber engineering gains code acceptance.
Construction Method:
Maturity gradients separate established techniques from emerging formats requiring new capital equipment and workforce training.
- Traditional:Cast-in-place concrete and steel erection still anchor infrastructure and high-rise commercial work. Aging ironworker and formwork carpenter cohorts constrain throughput without robotics deployment.
- Modular:Volumetric units for hotels and senior care facilities are scaling through Sumitomo Forestry and Daiwa House manufacturing yards. Standardized wet-module bathrooms are finding export demand in Southeast Asian hospital procurement.
- Prefabricated:Panelized wall and floor systems reduce site labor hours for residential developers. Supply chain integration determines cost competitiveness against traditional stick-frame alternatives.
- Sustainable:Whole-life carbon assessment and renewable material sourcing are becoming bid requirements for public healthcare and education projects. METI's 2024 Act revision is extending these specifications to private joint-venture structures.
Traditional methods retain the largest share; sustainable construction shows the steepest expansion trajectory as procurement codes tighten.
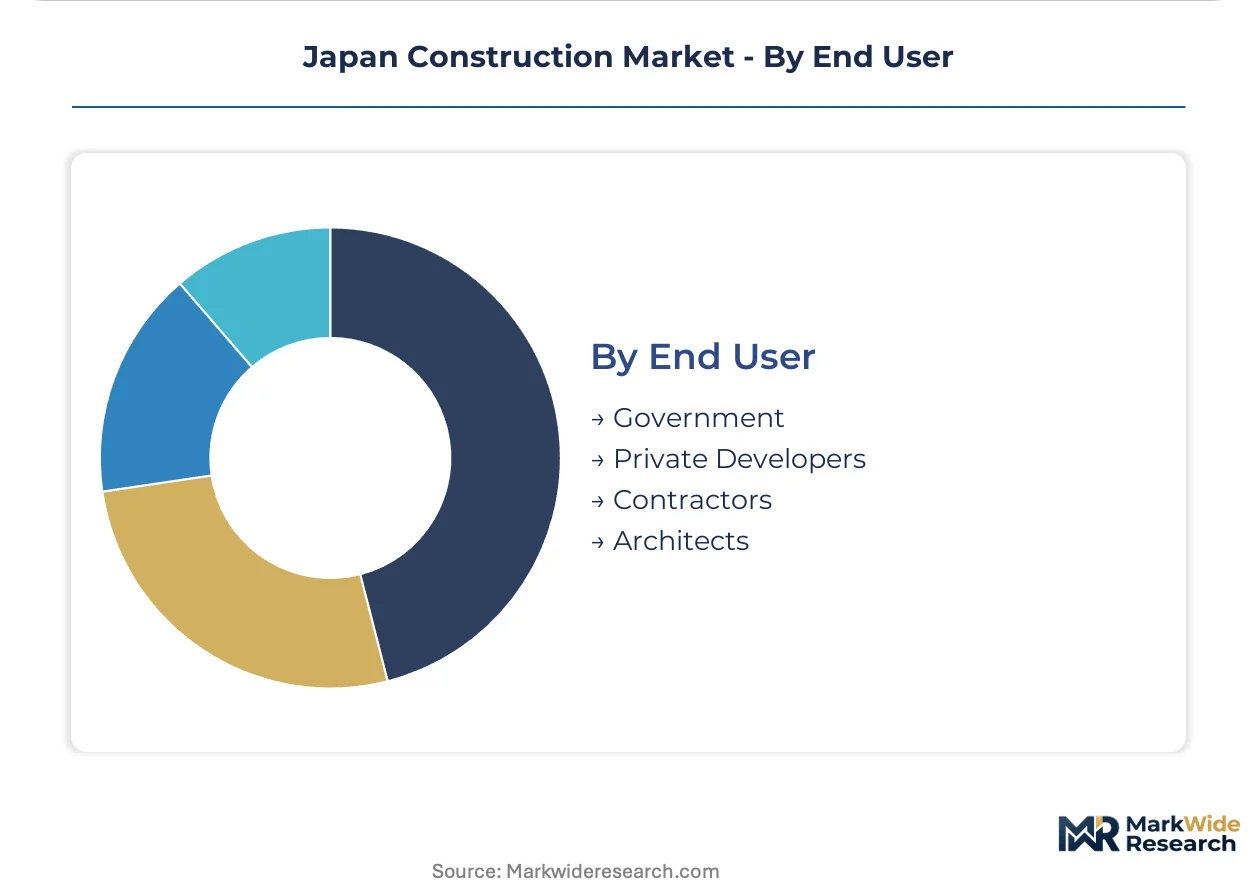
End User:
Customer type determines contract structure complexity and payment security profiles across the project pipeline.
- Government:National and prefectural agencies bundle seismic resilience upgrades with transit-oriented development mandates. Integrated design-build procurement is displacing conventional design-bid-build sequences for complex urban renewal.
- Private Developers:Real estate investment trusts in Tokyo's five major station districts are consolidating vendor relationships around single-source accountability. Land assembly complexity demands coordinated execution timelines.
- Contractors:General contractors like Taisei and Kajima are repositioning as integrated service providers with in-house design and manufacturing capabilities. Robotics-assisted assembly investments reduce skilled labor dependency.
- Architects:Design firms are embedding CASBEE documentation specialists to manage green building certification timelines that extend pre-construction phases. BIM interoperability with MLIT digital submission portals remains a friction point.
Government procurement holds the largest share; private developers are gaining share fastest as REIT capital concentrates in urban redevelopment corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese construction equipment and material exports flow primarily to Southeast Asian infrastructure markets, with Vietnam and Thailand absorbing prefabricated housing systems and seismic engineering expertise developed for domestic high-density urban corridors.
Kanto/Tokyo
Greater Tokyo's station-adjacent redevelopment corridor concentrates demand for transit-oriented mixed-use towers. MLIT's Building Standard Law enforcement accelerates seismic retrofit mandates across aging commercial stock. Shibuya, Toranomon, and Shinagawa districts host integrated design-build contracts bundling office, retail, and hospitality functions.
Kansai/Osaka
The 2025 Osaka-Kansai Expo infrastructure program unlocks district energy and modular hospitality construction with compressed delivery timelines. METI's industrial cluster subsidies redirect capital toward pharmaceutical cleanrooms and semiconductor fabrication facilities. The Osaka Bay area hosts specialized vibration-isolated structural systems for advanced manufacturing.
Chubu/Nagoya
Automotive supplier networks drive industrial construction demand for precision manufacturing facilities. Prefabricated methods penetrate automotive R&D campus expansion as Daiwa House and Sekisui House deploy manufacturing-scale supply chain integration. Toyota's surrounding supplier ecosystem requires seismic-resilient logistics infrastructure.
Kyushu
Semiconductor fabrication facility construction concentrates in Fukuoka and Kumamoto prefectures. METI's carbon-neutral building codes reshape material specifications toward low-emission concrete for cleanroom environments. TSMC's Kumamoto fab anchors a cluster of specialized contractor capability in vibration-controlled structural engineering.
Hokkaido
Structural-grade Japanese cedar sourcing clusters face weather-driven harvest volatility affecting cross-laminated timber supply chains. Prefabrication yards retool for hybrid steel-timber structural packages as JIS fire certification expands. Sapporo's urban renewal pipeline tests mass timber engineering in cold-climate commercial applications.
Japan Construction Market Competitive Environment
Player mix skews toward integrated design-build specialists with in-house manufacturing capabilities. The contractor base concentrates around five national general contractors with seismic engineering R&D programs and robotics-assisted assembly investments. Two strategic archetypes dominate: vertically integrated housing manufacturers controlling prefabrication supply chains, and civil engineering specialists capturing public infrastructure renewal mandates. Competitive moves center on integrated project delivery contract capture and cross-laminated timber manufacturing capacity expansion.
Within the integrated design-build tier, Taisei Corporation and Kajima Corporation anchor positions through sustained seismic engineering capability and robotics deployment. Daiwa House Industry Co., Ltd. exemplifies the manufacturing-integrated archetype with prefabricated housing scale. Takenaka Corporation occupies a position in complex urban renewal execution. These three represent the capability spectrum from civil infrastructure to manufactured housing systems.
| Leading Market Players |
|---|
| Taisei Corporation |
| Maeda Corporation |
| Obayashi Corporation |
| Sekisui House Ltd |
| Daiwa House Industry Co., Ltd. |
| Kajima Corporation |
| Takenaka Corporation |
| Sumitomo Forestry Co. Ltd |
| Shimizu Corporation |
| Others |
Value Chain & Pricing Dynamics
Integrated design-build contracts lock in multi-year material offtakes and price visibility for Japanese general contractors, binding cross-laminated timber suppliers to fixed-rate structures while exposing mid-tier concrete specialists to spot-market volatility in energy-intensive clinker production.
Pricing Analysis
Technology-generation pricing gaps separate conventional cast-in-place concrete from modular prefabrication and mass timber engineering, with premium-mid-economy pricing differentiation driven by CASBEE certification tiers and seismic performance ratings. Cost compression in commodity concrete runs through electricity tariff exposure and carbon levy pass-throughs, while integrated contractors with captive CLT manufacturing command price premiums. Public infrastructure buyers exhibit highest price sensitivity due to fixed-budget procurement mandates, whereas private REIT developers prioritize schedule certainty over unit cost.
Supply Chain Analysis
Inventory lead times for structural-grade Japanese cedar and British Columbia spruce stretch 8-14 weeks depending on harvest cycles, constraining just-in-time delivery for hybrid steel-timber projects. Domestic supply draws from Hokkaido forestry clusters and Canadian import channels, with ready-mix concrete sourcing anchored in regional batching plants. Single-source vulnerability concentrates in specialized timber engineering, where JIS-certified CLT fabrication rests on three domestic manufacturers. Distribution runs through general contractor-controlled logistics networks for major urban renewal, with prefabricated modules flowing direct from manufacturing yards to Tokyo station-adjacent sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's construction sector faces high-growth disruption as METI's carbon-neutral building codes force material substitution and procurement restructuring across the entire project pipeline.
For Market Incumbents: Shield core revenue streams by deepening backward integration into cross-laminated timber manufacturing and robotics-assisted assembly capabilities. Cement-dependent mid-tier contractors face margin erosion from carbon levies; priority defensive investment targets seismic engineering certification and integrated design-build contract capture to lock out modular specialists. For New Entrants and Emerging Players: Service-layer gaps in CASBEE documentation and whole-life carbon assessment consulting offer immediate white-space entry, as incumbent general contractors under-resource pre-construction compliance support. Prefabricated bathroom unit export to Southeast Asian hospital procurement represents the most penetrable expansion corridor, with go-to-market traction through Japanese trading house distribution partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturing-integrated housing specialists with captive rental property management arms. Long-term viability across the five-to-ten year horizon favors targets with CLT production capacity and robotics deployment pipelines. The signal to watch is MLIT digital submission portal integration capability, separating acquisition-ready mid-caps from legacy system-dependent laggards.| Strategic Initiative | Industry Significance |
|---|---|
| CLT Manufacturing Capacity Expansion | Captures METI procurement mandates for low-carbon public buildings. |
| Robotics-Assisted Assembly Investment | Reduces ironworker dependency for Tokyo high-rise structural frames. |
| Integrated Design-Build Contract Capture | Consolidates single-source accountability for station-adjacent redevelopment. |
| Prefabricated Module Export Program | Routes Japanese wet-module standards into Southeast Asian hospital procurement. |
| CASBEE Certification Service Launch | Compresses pre-construction timelines for green building compliance. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Construction industry stakeholders including general contractor project directors, METI policy officers, MLIT building standards administrators, timber engineering specialists, and REIT development heads provided operational perspective. Secondary sources encompass JIS certification databases, MLIT seismic retrofit program disclosures, METI carbon-neutral building code revisions, and prefectural procurement records. Bottom-up project pipeline analysis triangulates against top-down macro construction expenditure tracking.
Sensitivity analysis around electricity tariff trajectories and timber harvest volatility frames the quantitative outputs across the projection horizon. Segmentation modeling incorporates project type, material specification, construction methodology, and end-user procurement channel dimensions. CAGRs derive from historical expenditure patterns adjusted for policy-driven inflection points, with forecast inputs including semiconductor fab construction cycles and Osaka-Kansai Expo infrastructure delivery schedules.
Underlying assumptions cover stable enforcement of METI decarbonization timelines and MLIT seismic retrofit mandates, with deviation risk concentrated in weather-driven timber supply disruptions and skilled labor cohort attrition. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Turkey Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
UAE Facade Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Global Modular Fabrication Market
Building Construction
GCC Construction Market
Building Construction
Egypt Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
China Building Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Singapore Data Center Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Vietnam Construction Market
Building Construction
Dominican Republic Construction Market