
 Africa Construction Market | 2026-2036
Africa Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Construction Market Analysis
A shortage of certified project engineers is unwinding execution timelines across East and West African megaprojects. China Communications Construction Company leverages its port and highway portfolio to anchor contract flows along the East African coast. Julius Berger Nigeria sustains dominance in Abuja's federal infrastructure pipeline through backward integration into quarry and concrete operations. Mota-Engil Africa competes on Portuguese-speaking corridor projects, navigating Angolan and Mozambican procurement cycles with established joint-venture structures.
Construction across Africa encompasses the assembly of civil, commercial, and residential structures using Portland cement blends, reinforcing steel, and timber framing systems, with compressive strength specifications typically ranging from 20 to 40 MPa for structural concrete. The sector serves urbanization, resource extraction logistics, and national connectivity objectives. Infrastructure project types occupy the largest share of public budgets, while modular construction methods are gaining traction in rapid-deployment housing and health facility programs. Cement as a material type commands the deepest supply chain investments, with pan-African producers extending clinker capacity to reduce import dependence.
Kenya's National Construction Authority enforces structural audits and contractor registration tiers that filter market access. South Africa's National Regulator for Compulsory Specifications mandates SABS-approved steel and cement for public works eligibility. Nigeria's Federal Ministry of Works maintains its own highway design standards alongside state-level environmental impact requirements. Stakeholders must monitor how AfCFTA rules of origin reshape material sourcing patterns and contractor qualification reciprocity across member states.
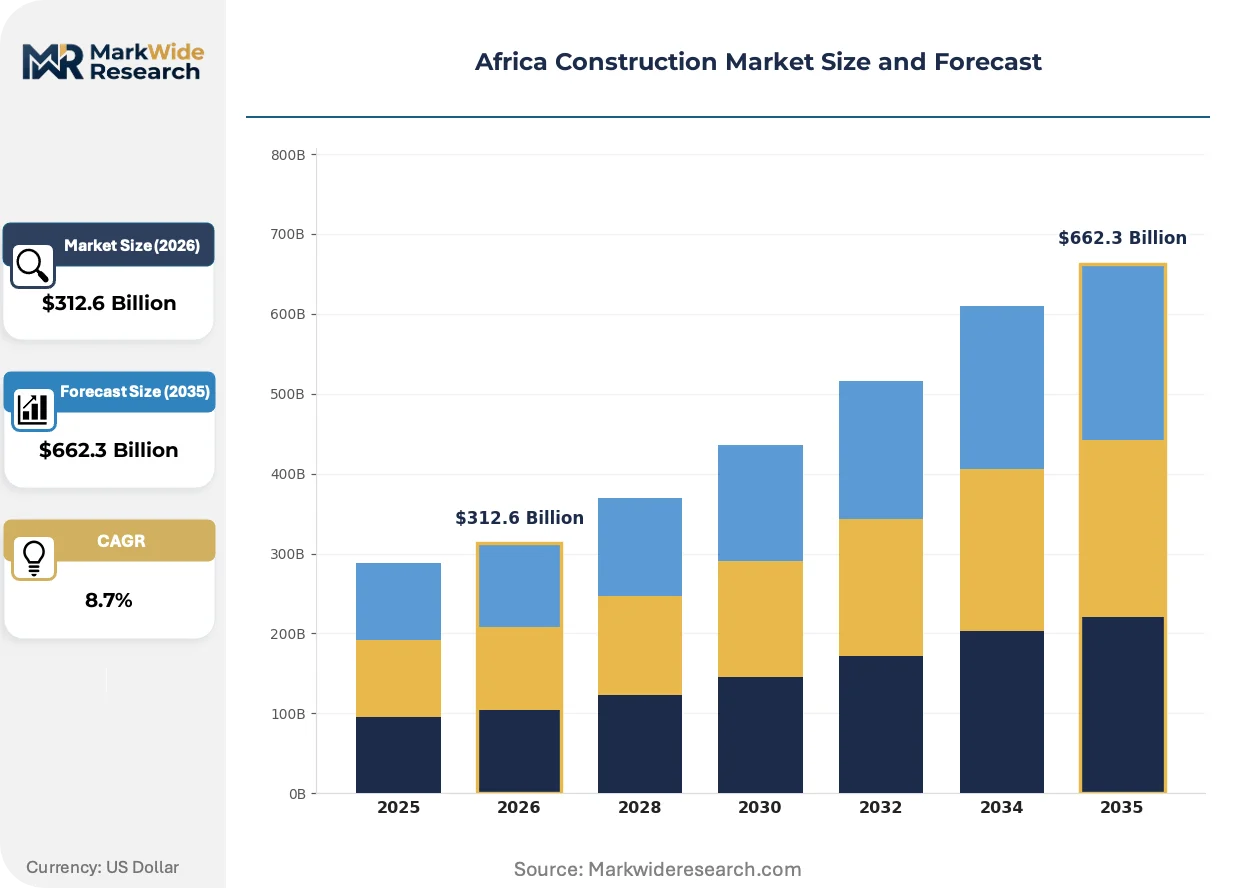
Market Dynamics
Urbanization pressure across African capitals is compressing project timelines and forcing modular delivery methods into mainstream infrastructure procurement. Lagos and Nairobi housing shortfalls are pulling cement capacity toward residential verticals while federal highway corridors absorb the bulk of heavy-civil engineering resources.
Growth Catalysts
- Nigeria's Federal Infrastructure Corridor:The Abuja-Port Harcourt highway expansion is anchoring demand for structural concrete and steel reinforcement across multiple state jurisdictions.
- Kenya's National Construction Authority tiered registration:Contractor certification requirements are filtering market access and concentrating execution capability among pre-qualified firms.
- Portland cement clinker localization:Pan-African producers are extending captive kiln capacity to reduce import dependence and stabilize input costs for megaproject concrete supply.
Market Restraints
- Reinforcing steel price volatility:Scrap metal and billet import exposure leaves structural concrete budgets vulnerable to currency fluctuation in import-dependent markets.
- Certified project engineer scarcity:East and West African megaprojects face execution timeline extension due to limited professional accreditation pipeline capacity.
- Cement supply concentration:Clinker production clusters in North and East Africa create logistics cost premiums for West and Central African project sites.
Strategic Opportunities
- Angolan and Mozambican Portuguese-speaking corridors:Established joint-venture structures offer entry points for contractors navigating procurement cycles in Lusophone markets.
- AfCFTA rules of origin harmonization:Material sourcing pattern reciprocity across member states is creating cross-border contractor qualification pathways.
- Modular rapid-deployment health facilities:Prefabricated structural systems are penetrating underserved rural healthcare infrastructure gaps.
Industry Challenges
- Structural audit compliance timelines:Kenya's National Construction Authority enforcement is extending pre-construction approval cycles for complex commercial developments.
- Legacy quarry integration:Backward integration into aggregate supply requires capital deployment for site rehabilitation and environmental permitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Construction Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $662.3 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Cement, Steel, Wood, Glass End User: Government, Private Developers, Contractors, NGOs Construction Method: Traditional, Modular, Sustainable, Prefabricated |
| Companies Covered | China Communications Construction Company, China Railway Construction Corporation, Vinci Construction, Bouygues Construction, Mota-Engil Africa, Orascom Construction, Aveng Grinaker-LTA, Julius Berger Nigeria, Hassan Allam Construction, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Construction Market Emerging Trajectories
Digital fabrication and alternative cement chemistries are compressing traditional construction cycles while regulatory pressure on embodied carbon intensifies material specification scrutiny. Three developments are restructuring competitive capability requirements across the sector.
Geopolymer and calcined clay binder systems are displacing conventional Portland cement in structural concrete formulations. Nigerian and Kenyan precast manufacturers are piloting these blends to meet tightening carbon disclosure requirements for federal contract eligibility. The technology is miniaturizing batch plant footprints and enabling distributed production closer to remote project sites.
South Africa's National Regulator for Compulsory Specifications mandates SABS-approved steel and cement for public works eligibility. This certification gate is compressing supplier lists and forcing import-dependent contractors toward local sourcing partnerships. Heavy-civil and federal infrastructure segments are absorbing the compliance cost burden through specification-grade material premiums.
Buyer consortiums in Lagos and Nairobi are consolidating procurement for multi-tower residential developments. Volume aggregation is displacing fragmented single-project tendering and compressing contractor margin structures. This concentration is most visible in private-sector urban housing verticals where development finance packages bundle design-build obligations.
Africa Construction Market Segmentation
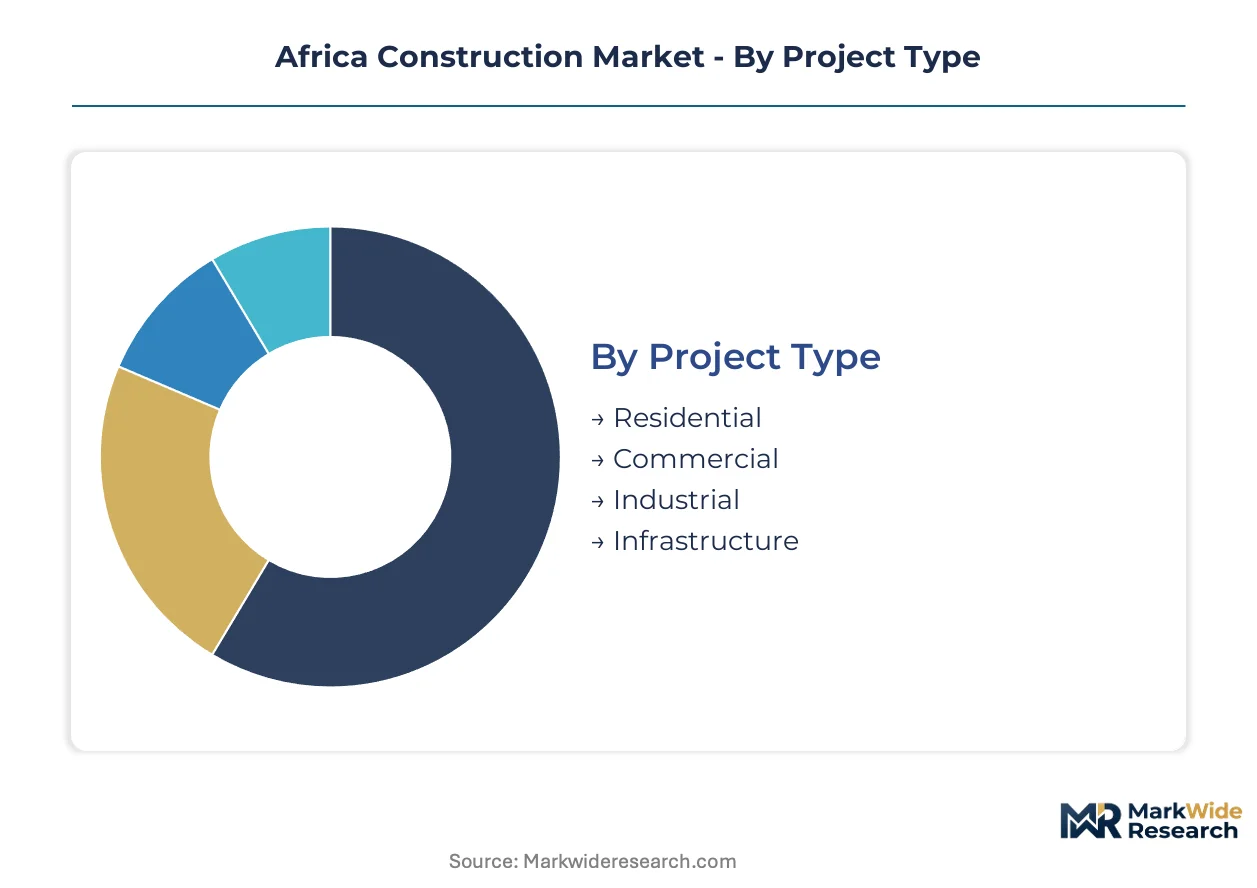
Structural concrete specifications and certification tiers fragment procurement patterns across African construction verticals. Material sourcing obligations and contractor registration requirements reshape competitive positioning within each segment boundary.
Project Type:
Kenya's National Construction Authority applies differentiated structural audit intensities across project categories, filtering execution capability toward compliance-heavy segments.
- Infrastructure:Heavy-civil engineering dominates public budget absorption, with federal highway corridors like Abuja-Port Harcourt anchoring steel and concrete demand across multiple state jurisdictions. Nigeria's Federal Ministry of Works maintains dedicated design standards that concentrate contractor qualification among pre-approved heavy-civil specialists.
- Residential:Vertical housing developments in Lagos and Nairobi pull cement capacity toward multi-tower projects, compressing timelines through buyer consortium procurement consolidation. Kenya's tiered contractor registration filters market access, concentrating execution among firms with proven high-rise delivery records.
- Commercial:Complex commercial developments face extended pre-construction approval cycles under Kenya's National Construction Authority enforcement.
- Industrial:Resource extraction logistics and manufacturing facility construction serve national connectivity and export objectives.
Established volume favors Infrastructure; emerging adoption favors Residential.
Material Type:
Pan-African producers extend captive kiln capacity to stabilize input costs, creating geographic cost tier differentiation across clinker production clusters.
- Cement:Portland cement blends command the deepest supply chain investments, with compressive strength specifications typically ranging from 20 to 40 MPa for structural concrete. Clinker localization in North and East Africa creates logistics premiums for West and Central African sites, while geopolymer and calcined clay binder systems displace conventional formulations in Nigerian and Kenyan precast manufacturing.
- Steel:Reinforcing steel faces scrap metal and billet import exposure that leaves structural concrete budgets vulnerable to currency fluctuation. South Africa's National Regulator for Compulsory Specifications mandates SABS-approved steel for public works eligibility, compressing supplier lists toward local sourcing partnerships.
- Wood:Timber framing systems serve rapid-deployment applications and residential verticals with lighter structural requirements.
- Glass:Commercial facade and interior specification drives demand in urban commercial developments.
Cost concentration favors Cement; specification premium capture favors Steel.
End User:
Procurement authority concentration determines contract flow stability, with federal pipeline visibility diverging sharply from fragmented private development finance.
- Government:Federal infrastructure corridors absorb the bulk of heavy-civil engineering resources, with Nigeria's Federal Ministry of Works and Kenya's National Construction Authority maintaining parallel design standards and contractor registration systems. Public budget cycles and election timelines compress project execution windows.
- Private Developers:Buyer consortiums in Lagos and Nairobi consolidate procurement for multi-tower residential developments, displacing fragmented single-project tendering. Volume aggregation compresses contractor margin structures while bundling design-build obligations into development finance packages.
- Contractors:Execution firms navigate tiered registration requirements and joint-venture structures to access cross-border opportunities.
- NGOs:Rapid-deployment health and education facilities drive modular construction adoption in underserved rural infrastructure gaps.
Contract volume stability favors Government; margin expansion favors Private Developers.
Construction Method:
Timeline compression pressure from urbanization is forcing delivery method innovation into mainstream procurement, with certification gaps determining adoption speed.
- Modular:Prefabricated structural systems penetrate rapid-deployment housing and health facility programs, miniaturizing batch plant footprints through distributed production models. Digital fabrication enables site-adjacent manufacturing closer to remote project locations, bypassing cement supply concentration constraints.
- Sustainable:Geopolymer and calcined clay binder systems gain traction under tightening carbon disclosure requirements for federal contract eligibility in Nigeria and Kenya. Alternative cement chemistries enable specification compliance while reducing clinker import dependence.
- Traditional:Cast-in-place concrete and timber framing remain dominant in markets with limited modular supply chain maturity.
- Prefabricated:Off-site component manufacturing accelerates timeline-sensitive federal infrastructure delivery.
Current execution volume favors Traditional; steepest expansion trajectory favors Modular.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nigeria's Federal Ministry of Works anchors the continent's largest infrastructure pipeline, with procurement cycles concentrated along federal highway corridors and state-level environmental compliance requirements shaping contractor qualification pathways across West Africa.
Nigeria
Abuja-Port Harcourt highway expansion absorbs structural concrete and steel reinforcement across multiple state jurisdictions. State-level environmental impact requirements layer onto federal design standards, extending pre-construction approval timelines. Lagos housing shortfalls pull cement capacity toward residential verticals, compressing delivery schedules through buyer consortium procurement consolidation.
Kenya
Nairobi's urban housing deficit drives multi-tower residential development concentration. The National Construction Authority enforces tiered contractor registration and structural audit intensities that filter market access toward pre-qualified firms. Mombasa port logistics corridors anchor heavy-civil engineering resource allocation along the East African coast.
South Africa
The National Regulator for Compulsory Specifications mandates SABS-approved steel and cement for public works eligibility, compressing supplier lists toward local sourcing partnerships. Johannesburg and Cape Town commercial developments face specification-grade material premiums. Heavy-civil segments absorb compliance cost burdens through certified product requirements.
Angola
Portuguese-speaking corridor projects navigate procurement cycles with established joint-venture structures. Luanda's infrastructure rehabilitation programs concentrate execution capability among firms with Lusophone market experience. State-level contract flows favor contractors integrated into Angolan quarry and aggregate supply networks.
Mozambique
Coastal logistics and extractive industry infrastructure drive demand for modular rapid-deployment methods. Maputo corridor development links South African supply chains with Northern Mozambique gas project logistics. Procurement authority fragmentation between state and federal levels creates contract flow volatility for execution firms.
Africa Construction Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding federal infrastructure pipelines through backward integration into captive aggregate and concrete supply. Mid-scale execution firms compete on tiered registration compliance and joint-venture access to cross-border opportunities. Two strategic archetypes dominate: pan-African producers extending clinker localization, and corridor-specialist contractors leveraging Portuguese-language procurement networks. Competitive moves concentrate on quarry site rehabilitation for environmental permitting and modular fabrication capacity for timeline-compressed housing programs.
Among China-based infrastructure contractors, China Communications Construction Company and China Railway Construction Corporation occupy positions exemplifying port and highway portfolio anchoring along East African coastlines. Within the integrated West African tier, Julius Berger Nigeria represents backward integration archetypes through quarry and concrete operations. Mota-Engil Africa sits within the Lusophone corridor specialist category, navigating Angolan and Mozambican procurement structures.
| Leading Market Players |
|---|
| China Communications Construction Company |
| China Railway Construction Corporation |
| Vinci Construction |
| Bouygues Construction |
| Mota-Engil Africa |
| Orascom Construction |
| Aveng Grinaker-LTA |
| Julius Berger Nigeria |
| Hassan Allam Construction |
| Others |
Supply Flow & Price Mechanics
Kenya's National Construction Authority tiered contractor registration gates both supply qualification and price differentiation simultaneously, compressing margin structures for non-certified firms while enabling premium capture among pre-qualified specialists. Federal procurement standards in Nigeria and South Africa layer certification costs onto material specifications, creating price stratification across compliance-heavy and informal market tiers.
Pricing Analysis
Geographic price spreads between North African clinker production clusters and West African project sites run 15-25% on delivered cement costs. Project-based pricing dominates heavy-civil and federal infrastructure segments, with specification-grade material premiums separating SABS-certified steel from generic billet imports. Cost compression in residential verticals is intensifying because buyer consortiums in Lagos and Nairobi consolidate multi-tower procurement, squeezing contractor margins. Private developers show highest price sensitivity, while government agencies absorb compliance premiums through dedicated budget lines.
Supply Chain Analysis
Egypt and Morocco anchor clinker production capacity, feeding grinding operations across West and Central Africa. Nigerian and Kenyan precast manufacturers draw from calcined clay and geopolymer feedstocks to reduce Portland cement dependence. Single-source vulnerability concentrates around Egyptian clinker exports through Suez Canal logistics chokepoints. Distribution runs through pan-African producer networks with captive kiln capacity, supplemented by independent bulk importers serving fragmented project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across regulatory jurisdictions creates niche opportunities for specialized contractors. Modular delivery methods and alternative cement chemistries are opening execution gaps that tiered registration systems have not yet captured.
For Market Incumbents: Fortify quarry and aggregate supply positions through site rehabilitation investments that accelerate environmental permitting timelines. Backward integration into captive concrete batching capacity defends margin structures against buyer consortium procurement consolidation. Pre-qualified contractor registries in Kenya and Nigeria pose substitution threats from certified mid-tier entrants.
For New Entrants and Emerging Players: Anchor in Angolan and Mozambican Portuguese-speaking corridors where established joint-venture structures lower procurement cycle barriers. Rapid-deployment health facilities and modular housing programs represent the most penetrable white-space segments. Go-to-market positioning should emphasize digital fabrication capabilities that compress timeline-sensitive delivery schedules.
For Investors and Strategic Acquirers: AfCFTA rules of origin harmonization reshapes the acquisition landscape by enabling cross-border contractor qualification reciprocity. Long-term viability centers on firms with demonstrated Lusophone corridor execution and clinker localization investments. Watch for cement import substitution policy shifts as inflection indicators for pan-African producer valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinker Localization Investment | Egyptian and Moroccan kiln capacity extensions reduce West African import dependence and stabilize input costs. |
| Modular Fabrication Capacity Buildout | Distributed production models bypass cement logistics premiums for remote health facility deployments. |
| Tiered Contractor Registration Compliance | Kenya's National Construction Authority certification opens access to federal infrastructure pipeline flows. |
| Portuguese-Language Joint Venture Formation | Lusophone corridor structures unlock Angolan and Mozambican state-level procurement cycles. |
| Geopolymer Binder System Adoption | Alternative cement chemistries meet Nigerian and Kenyan carbon disclosure requirements for federal eligibility. |
Methodological Framework
Initial hypotheses were tested against primary input from project engineers at heavy-civil contractors, procurement officers at federal ministries of works, quarry operations managers, and precast manufacturing directors, and refined through secondary validation against customs and trade data, National Construction Authority registration databases, clinker production capacity disclosures, and SEC filings from listed construction materials producers. Bottom-up project pipeline aggregation and top-down macroeconomic scenario modeling were triangulated to cross-check volume assumptions.
Variance-decomposition across project type, material specification tier, construction method, and end-user procurement authority shaped the analytical framework. CAGRs were derived from segment-level volume build-ups applied to price trajectory assumptions, with urbanization density indices and federal budget allocation patterns serving as construction-specific forecast inputs across the projection horizon.
Underlying assumptions cover clinker import substitution timelines and AfCFTA implementation pace, with deviation risk concentrated in currency volatility for steel billet imports and regulatory enforcement intensity variations across member states. Recalibration cycles align with material shifts in federal infrastructure budget announcements and National Construction Authority audit protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Eastern Europe Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Vertical Garden Construction Market
Building Construction
China Building Construction Market
Building Construction
Tunnels Design and Construction Market
Building Construction
Qatar Construction Market
Building Construction
US Modular Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
GCC Green Buildings Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Sweden New Construction Market
Building Construction
China Modular Construction Market
Building Construction
Indonesia Prefabricated Buildings Market