
 China Modular Construction Market | 2026-2036
China Modular Construction Market Size, Share, and Industry Trends Forecast 2026-2036
China Modular Construction Market Insights
Multi-source procurement for structural steel and prefabricated envelope systems is pivoting toward vertically integrated domestic suppliers. CIMC Modular Building Systems leverages captive manufacturing of containerized modules to control cost volatility. Hangxiao Steel Structure anchors high-rise modular projects through proprietary steel connection technology. China State Construction sustains its position via state-backed infrastructure pipelines and direct municipal contracting authority.
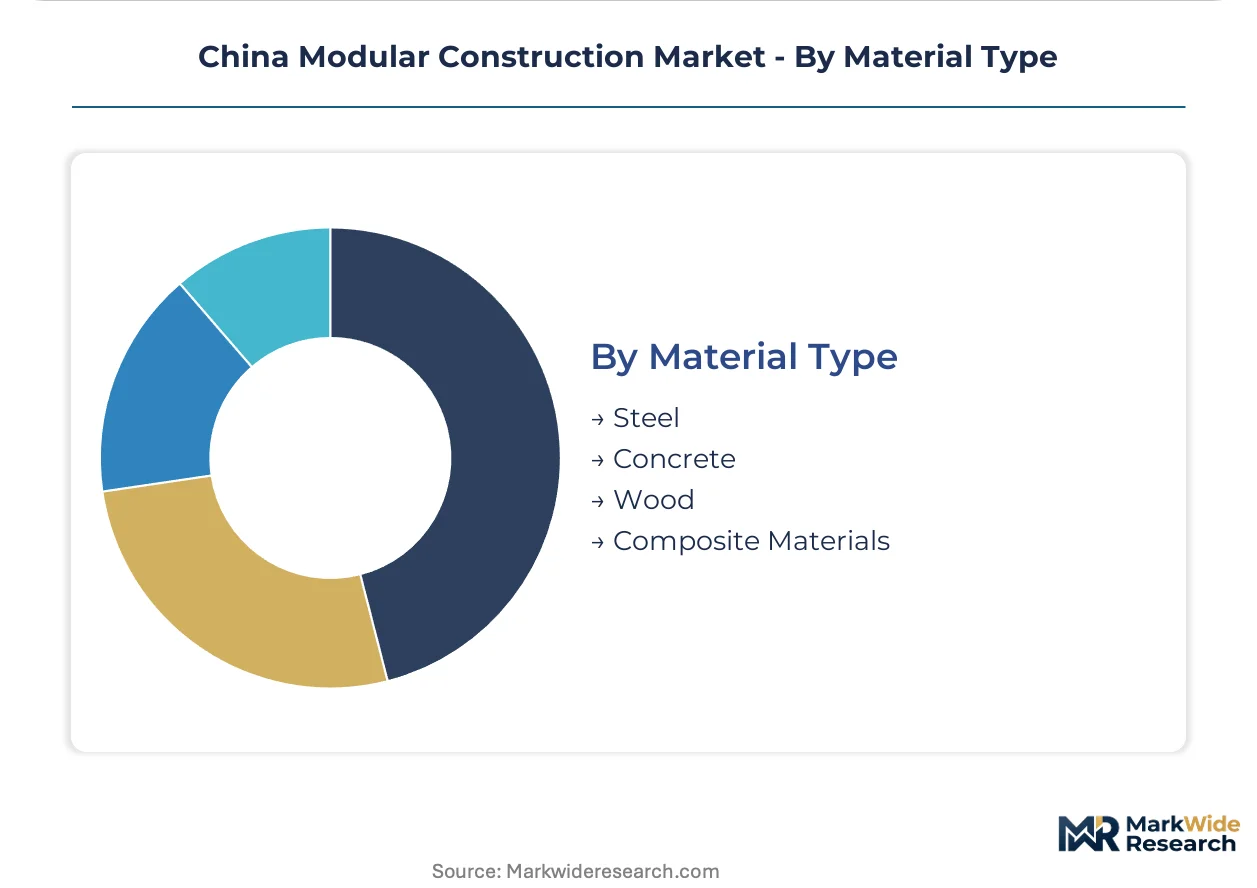
Modular construction denotes the off-site fabrication of building sections—typically steel-framed boxes with integrated MEP, fire-rated insulation, and weatherproof cladding—subsequently transported and craned into final position. These units achieve structural performance through welded moment frames or bolted node connections, with tolerances controlled to within two millimeters during factory assembly. Permanent Modular commands the dominant share of value given its compliance with GB 50011 seismic codes and eligibility for mortgage financing, while Relocatable Modular serves temporary educational and disaster-relief applications with faster depreciation schedules. Steel-based modules lead material type selection due to China's abundant domestic mill capacity and the MIIT preference for recyclable structural systems in public projects.
GB standards issued by SAMR and sectoral rules from MEE enforce energy-efficiency benchmarks and embodied-carbon limits that filter out non-compliant factory operators. The dual carbon goals framework tightens steel production emissions quotas, indirectly raising input costs for module fabricators without captive electric-arc capacity. Stakeholders must track whether provincial governments in Jiangsu and Zhejiang expand modular procurement mandates for affordable housing beyond current pilot thresholds.
Market Dynamics
MIIT's dual carbon goals framework is compressing steel production quotas while tier-two cities accelerate affordable housing procurement mandates, creating simultaneous supply constraint and demand pull for factory-built structural systems.
Growth Catalysts
- GB 50011 Seismic Compliance:Permanent modular structures meeting these standards qualify for mortgage financing, unlocking residential demand in Jiangsu and Zhejiang provinces.
- Yangtze River Delta Production Clusters:Shanghai and Suzhou anchor captive steel-frame manufacturing capacity, reducing logistics costs for high-rise modular delivery.
- Affordable Housing Procurement Mandates:Municipal governments in tier-two cities are embedding prefabricated quotas into land-use planning requirements.
Market Restraints
- Electric-Arc Furnace Capacity Scarcity:Steel input costs fluctuate with carbon quota enforcement, squeezing fabricators lacking captive low-emission mill supply.
- Transportation Infrastructure Gaps:Module dimensions exceed standard highway clearances in interior provinces, constraining addressable geography.
- Concrete Structure Substitution:Cast-in-place methods retain cost advantages in low-rise applications below six stories.
Strategic Opportunities
- MEE Embodied-Carbon Limits:Early compliance positions fabricators for preferred supplier status in state-backed infrastructure pipelines.
- Disaster-Relief Applications:Relocatable modular serves temporary educational and emergency housing with accelerated depreciation schedules.
- BIM-IoT Convergence:Digital twin integration during factory assembly enables predictive maintenance contracts for institutional buyers.
Industry Challenges
- Welding Certification Bottlenecks:Factory-grade structural welders require GB-specific qualifications that training programs struggle to scale.
- Multi-Party Integration Complexity:Coordinating MEP subcontractors with envelope suppliers across dispersed fabrication sites delays project handoffs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Modular Construction Market |
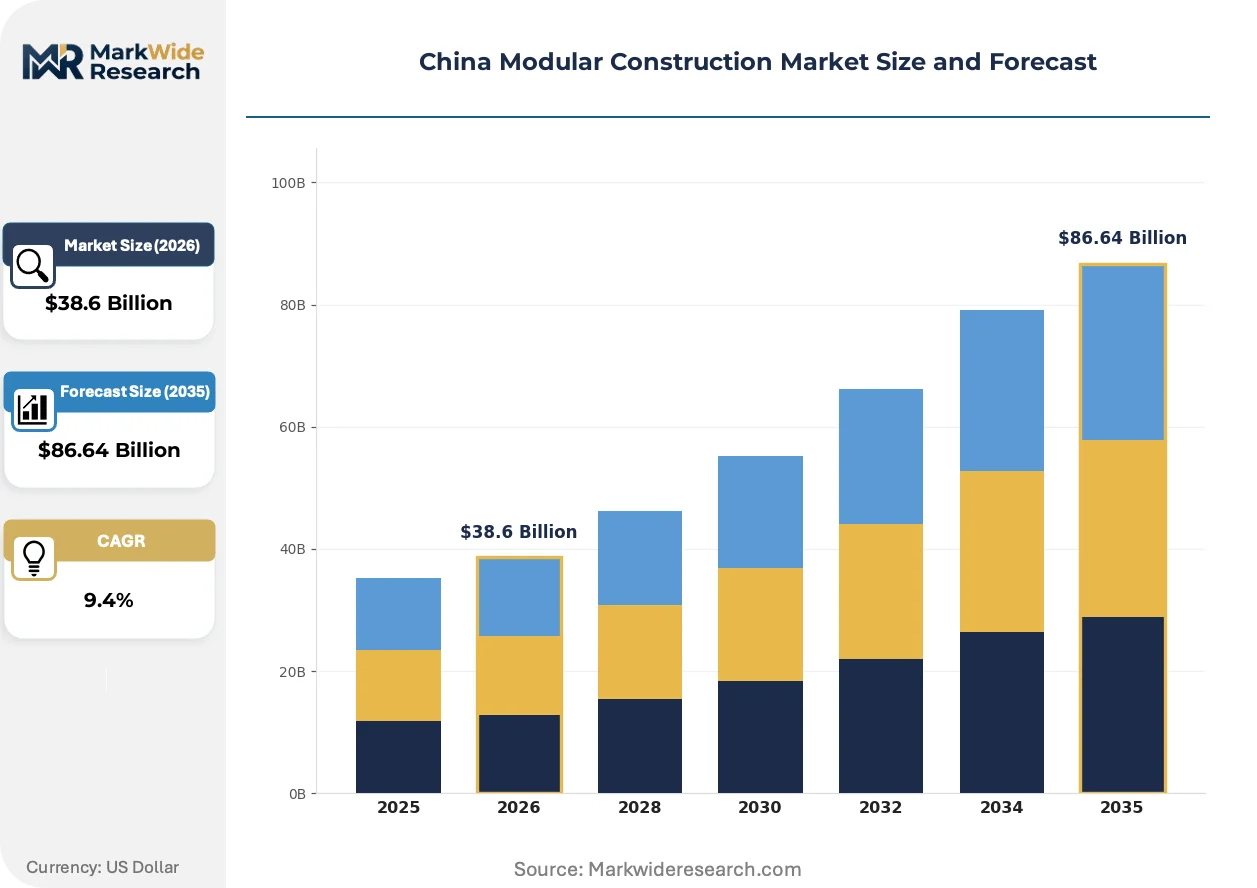
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Permanent Modular, Relocatable Modular, Hybrid Modular, Modular Components End User: Residential Buildings, Commercial Complexes, Industrial Facilities, Educational Institutions Installation Type: On-site Installation, Off-site Installation, Prefabricated Construction, Integrated Systems Material Type: Steel, Concrete, Wood, Composite Materials |
| Companies Covered | CIMC Modular Building Systems, Hangxiao Steel Structure, China State Construction, Ningbo Deepblue Smart House, Atlantic Modular System, Ark Prefab, Archi Space, Yuanda Modular Construction, Guangdong Rongtai Intelligent Housing, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Modular Construction Market Trends and Innovations
Digital fabrication and regulatory carbon accounting are compressing traditional construction timelines while reshaping how developers evaluate total-project risk. Factory-based quality control is displacing site-dependent inspection regimes.
Building Information Modeling integrated with automated steel cutting is unifying structural design and MEP routing into single-factory workflows. High-rise residential developers in Shanghai are adopting these platforms to compress coordination cycles from months to weeks. This unifying architecture is collapsing the traditional separation between structural engineers and systems integrators.
MIIT's green building standards issued through SAMR are tightening material compliance thresholds for public project eligibility. Fabricators must now document recycled content ratios and embodied-carbon footprints to bid on state infrastructure. Steel-frame modular suppliers with captive electric-arc capacity are securing preferred procurement status in Jiangsu municipal pipelines.
Developer purchasing departments are consolidating supplier rosters around vertically integrated fabricators capable of single-source accountability. General contractors in Suzhou are ceding procurement authority to owners who demand factory-direct warranty structures. This concentration is most visible in Yangtze River Delta affordable housing projects where municipal owners specify turnkey module supply.
China Modular Construction Market Segmentation
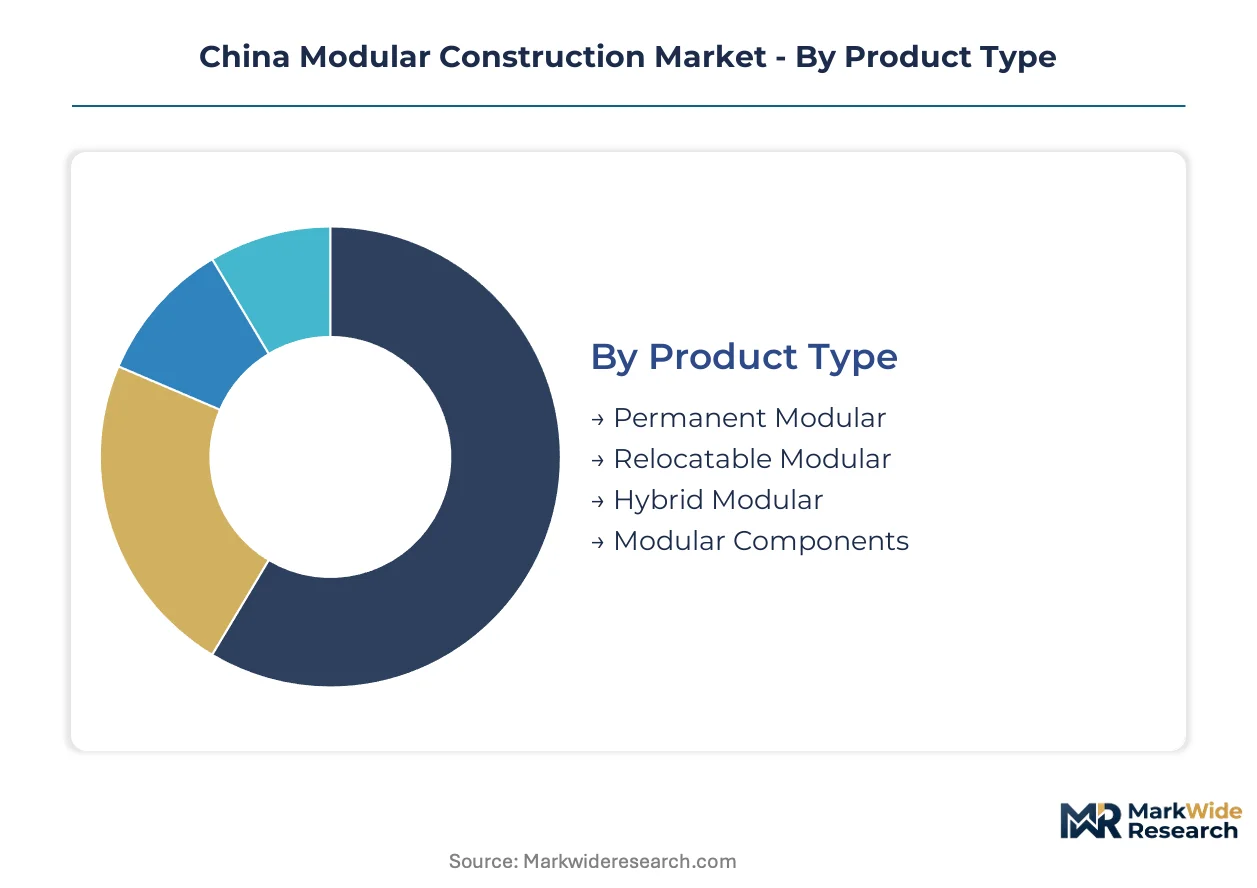
Segmentation in China's modular construction market reveals how regulatory frameworks and procurement mandates reshape buyer priorities across structural systems. Developers in Jiangsu and Zhejiang provinces select product configurations based on GB 50011 seismic compliance eligibility and municipal affordable housing quotas.
Product Type:
Financing eligibility and depreciation schedules drive product selection, with mortgage-qualifying structures commanding premium procurement attention.
- Permanent Modular:Steel-framed boxes with welded moment frames achieve GB 50011 seismic certification, unlocking residential mortgage financing in Shanghai and Suzhou affordable housing pipelines. Municipal land-use mandates in tier-two cities specify this category for public procurement.
- Relocatable Modular:Bolted node connections enable rapid disassembly for temporary educational facilities and disaster-relief housing across interior provinces. Accelerated depreciation schedules attract institutional buyers with shorter holding periods.
- Hybrid Modular:Combines permanent structural cores with relocatable infill panels for institutional clients requiring phased expansion flexibility.
- Modular Components:Prefabricated MEP risers and facade panels integrate with cast-in-place structures for mid-rise retrofits in legacy urban districts.
Permanent Modular leads on scale; Relocatable Modular leads on momentum.
End User:
Procurement authority concentration varies sharply across buyer categories, with state-backed pipelines dominating volume allocation.
- Residential Buildings:Affordable housing mandates in tier-two cities embed prefabricated quotas into land-use planning requirements, with Yangtze River Delta municipalities specifying steel-frame modular for high-rise density targets.
- Commercial Complexes:Shanghai developers adopt BIM-integrated factory workflows to compress coordination cycles for mixed-use towers. Turnkey module supply with factory-direct warranty structures consolidates procurement authority.
- Industrial Facilities:Manufacturing parks in Jiangsu specify modular utility buildings to accelerate production line commissioning.
- Educational Institutions:Provincial education bureaus deploy relocatable classrooms for enrollment surge response in rapidly urbanizing counties.
Residential Buildings anchor volume commitment; Commercial Complexes expand most quickly.
Installation Type:
Logistics infrastructure maturity determines feasible installation modes, with highway clearance constraints filtering options in interior provinces.
- On-site Installation:Module craning and connection sequencing requires proximity to Yangtze River Delta production clusters where factory-to-site logistics minimize transport damage risk.
- Off-site Installation:Complete building assembly in factory yards before modular transport suits remote industrial sites with limited local skilled labor.
- Prefabricated Construction:Panelized systems ship flat-packed to congested urban sites where module dimensions exceed highway clearances.
- Integrated Systems:MEP-heavy configurations with factory-tested commissioning reduce site coordination complexity for institutional buyers.
On-site Installation dominates coastal provinces; Prefabricated Construction gains share fastest in interior logistics-constrained markets.
Material Type:
Carbon quota enforcement and domestic mill capacity reshape material economics, with recyclable structural systems securing preferred procurement status.
- Steel:Abundant domestic mill capacity and MIIT preference for recyclable systems in public projects anchor Yangtze River Delta production. Electric-arc furnace scarcity raises input costs for fabricators lacking captive low-emission supply.
- Concrete:Cast-in-place methods retain cost advantages below six stories in low-rise applications where seismic performance requirements moderate.
- Wood:Cross-laminated timber modules serve boutique residential and educational projects with explicit sustainability procurement criteria.
- Composite Materials:Fiber-reinforced polymer panels enable lightweight facade systems for high-rise modular envelope applications.
Steel commands procurement volume; Composite Materials climb the fastest as envelope performance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in China's modular construction sector drives production migration toward provinces with lower carbon-compliance costs and stronger state procurement pipelines. MIIT's dual carbon goals enforce stricter steel production quotas in coastal manufacturing hubs, pushing module fabricators toward interior regions with captive electric-arc capacity and municipal affordable housing mandates.
Yangtze River Delta
Shanghai and Suzhou anchor the nation's densest steel-frame modular production clusters, serving high-rise residential density targets through GB 50011-compliant permanent structures. MIIT green building standards issued via SAMR tighten material compliance thresholds for public project eligibility here. Factory-to-site logistics minimize transport damage risk across this coastal corridor, sustaining premium procurement positioning despite elevated input costs.
Pearl River Delta
Guangdong province accelerates modular uptake through provincial education bureau deployments of relocatable classrooms for enrollment surge response. MEE embodied-carbon limits filter non-compliant factory operators from state infrastructure bidding pools. Shenzhen-based fabricators specialize in composite material envelope systems for high-rise modular applications.
Beijing-Tianjin-Hebei
Affordable housing procurement mandates in Beijing embed prefabricated quotas into municipal land-use planning requirements. The dual carbon goals framework compresses regional steel production quotas, raising input costs for module fabricators lacking captive low-emission mill supply. Tianjin's port infrastructure supports export-oriented modular component manufacturing.
Sichuan-Chongqing
Western China's interior logistics constraints favor panelized prefabricated construction over module transport where highway clearances limit dimensional feasibility. Provincial governments here expand modular procurement mandates for disaster-relief housing beyond current pilot thresholds. Chongqing's manufacturing base serves industrial facility modular utility building demand.
Shandong Peninsula
Jiangsu and Zhejiang provincial governments specify steel-frame modular for tier-two city affordable housing pipelines, with Qingdao fabricators capturing spillover demand. Electric-arc furnace capacity scarcity in northern mills fluctuates steel input costs for non-integrated producers. Regional clusters focus on mid-rise retrofits using prefabricated MEP risers and facade panels.
China Modular Construction Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital fabrication and carbon-accounting differentiation to bypass incumbent scale advantages. The vendor base concentrates around state-backed infrastructure contractors and captive steel manufacturers with municipal procurement authority. Three archetypes dominate: vertically integrated steel producers controlling input costs, state-owned construction enterprises with direct contracting pipelines, and specialized smart housing technologists targeting relocatable applications. Competitive moves center on backward integration into electric-arc steel supply and BIM-IoT platform licensing for predictive maintenance contracts.
Among Yangtze River Delta-based fabricators, CIMC Modular Building Systems and Hangxiao Steel Structure exemplify the integrated-production archetype, while China State Construction occupies a position within the state-contracting tier. These three entities represent distinct competitive positioning vectors: captive manufacturing control, proprietary connection technology, and municipal pipeline access respectively. Ningbo Deepblue Smart House sits within the smart housing specialization cluster alongside Ark Prefab and Archi Space. Yuanda Modular Construction and Guangdong Rongtai Intelligent Housing exemplify regional production concentration in the Pearl River Delta corridor.
| Leading Market Players |
|---|
| CIMC Modular Building Systems |
| Hangxiao Steel Structure |
| China State Construction |
| Ningbo Deepblue Smart House |
| Atlantic Modular System |
| Ark Prefab |
| Archi Space |
| Yuanda Modular Construction |
| Guangdong Rongtai Intelligent Housing |
| Others |
Pricing and Supply Chain Analysis
MIIT's dual carbon goals framework and GB 50011 seismic certification mandates are compressing supplier rosters toward vertically integrated fabricators with captive electric-arc capacity, forcing price stratification across compliance tiers and reshaping procurement authority concentration in Yangtze River Delta affordable housing pipelines.
Pricing Analysis
Input-cost pass-through from carbon-quota enforcement and steel mill emissions compliance is intensifying margin pressure on non-integrated fabricators. Three-tier pricing structure across premium, standard, and economy levels separates GB-certified permanent modular from relocatable units and unverified imports. Price differentiation hinges on seismic certification grade and factory-direct warranty bundling. Municipal buyers in Jiangsu and Zhejiang exhibit lowest price sensitivity given state-backed financing eligibility, while interior province developers face acute cost compression from logistics-constrained module transport.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta production clusters where Shanghai and Suzhou anchor steel-frame module fabrication. Raw material dependencies center on domestic hot-rolled steel sections, fire-rated insulation batts, and MEP riser assemblies. Supply chain risk manifests through electric-arc furnace capacity scarcity under tightening emissions quotas. Distribution runs through state-contracting pipelines with direct municipal procurement authority, bypassing traditional general contractor intermediaries in tier-two city affordable housing projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where developer procurement departments consolidate around fabricators delivering GB-certified permanent modular with factory-direct accountability, displacing site-dependent inspection regimes and unverified component suppliers.
For Market Incumbents: Deploy captive electric-arc steel supply as the priority defensive lever. Secure preferred supplier status in Jiangsu and Zhejiang municipal pipelines by documenting embodied-carbon footprints ahead of MEE enforcement deadlines. Counter concrete structure substitution threats below six stories through BIM-integrated coordination cycle compression for high-rise density targets. For New Entrants and Emerging Players: Digital twin integration for predictive maintenance contracts offers the most penetrable wedge into institutional buyer segments. Target disaster-relief and educational relocatable applications in Sichuan-Chongqing where interior logistics constraints favor panelized systems and highway clearance limitations filter incumbent module transport advantages. Lead with factory-tested MEP commissioning to reduce site coordination complexity. For Investors and Strategic Acquirers: Asymmetric upside sits with smart housing technologists combining composite material envelope systems with carbon-accounting compliance infrastructure. Long-term viability centers on fabricators with backward integration into low-emission steel supply and municipal contracting authority. Watch provincial government expansion of modular procurement mandates beyond current pilot thresholds as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Electric-Arc Capacity Buildout | MIIT emissions quotas favor fabricators controlling low-emission steel input costs. |
| GB 50011 Certification Investment | Seismic compliance unlocks mortgage financing eligibility in residential pipelines. |
| BIM-IoT Platform Licensing | Digital twin contracts enable recurring revenue from institutional maintenance budgets. |
| Provincial Procurement Mandate Alignment | Land-use planning requirements in tier-two cities embed prefabricated quotas. |
| Composite Envelope R&D Partnership | MEE embodied-carbon limits filter non-compliant facade suppliers from state bidding. |
Research Methodology
Bottom-up residential and commercial end-use modeling reconciled against top-down steel-frame production capacity tracking forms the analytical core. Primary interviews with municipal procurement officers, factory operations directors, structural engineering consultants, and affordable housing developers combined with secondary validation from MIIT policy circulars, SAMR GB standard documentation, provincial land-use planning filings, and Yangtze River Delta customs trade records. Triangulation across these sources grounds volume estimates in observable procurement pipeline commitments and certified production capacity.
Historical trendline analysis of permanent versus relocatable modular shipment ratios informs the projection framework across the analysis window. Segmentation dimensions span product type, end-user category, material composition, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves calibrated against affordable housing mandate expansion scenarios and electric-arc capacity commissioning timelines. Industry-specific inputs include steel mill emissions quota enforcement schedules and provincial education bureau classroom deployment budgets.
The model holds under continued MIIT dual carbon goals enforcement and tier-two city land-use mandate expansion; deviation in central government infrastructure stimulus withdrawal or interior highway clearance standard relaxation would shift volume allocation toward cast-in-place substitution. Forecasts reflect documented policy trajectories and observable production capacity rather than speculative demand creation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
GCC Cement Market
Building Construction
United States Commercial Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Australia Construction Market
Building Construction
Global Dry Construction Market
Building Construction
Vietnam Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Oman Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Spain Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
Eastern Europe Construction Market