
 Spain Prefabricated Buildings Market | 2026-2036
Spain Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Prefabricated Buildings Market Insights
Social housing procurement is pivoting toward factory-built solutions as Spanish municipalities face backlog pressures. Grupo ALCO Modular leverages its Andalusian manufacturing base to serve this institutional channel. Europa Prefabri anchors the modular homes segment through standardized timber-frame designs. Algeco España dominates temporary structures for infrastructure and events, sustaining rental revenue streams across Iberian project cycles.
Prefabricated buildings are structural assemblies manufactured in controlled factory conditions, typically achieving dimensional tolerances of ±2mm, then transported and erected on permanent foundations. Their primary purpose is compressing construction schedules while maintaining quality consistency impossible under conventional site-built methods. Steel and concrete materials command the industrial and educational application segments where span requirements and fire resistance dominate specifications. Modular homes within the residential application category attract margin concentration as buyers accept premium pricing for customization flexibility. Factory-built construction method leads volume throughput, though turnkey solutions capture higher value per project by bundling design, permitting, and installation.
Spain's Ministry of Transport and Urban Agenda enforces the Technical Building Code (CTE), which mandates near-zero energy building standards that prefabricated systems increasingly satisfy through integrated envelope engineering. BIS-equivalent structural certification and CE marking requirements under EU Construction Products Regulation govern market access for imported components. The EU Green Deal and national recovery fund conditionality direct public procurement toward circular material specifications. Stakeholders must monitor how upcoming EU-wide embodied carbon thresholds for construction materials reshape material selection between timber, steel, and composite alternatives.
Market Dynamics
Spain's prefabricated buildings sector is compressing delivery timelines as municipal housing authorities face acute backlog pressures. The Technical Building Code's near-zero energy mandates are forcing factory-level integration of envelope engineering, creating a structural advantage for offsite manufacturers over conventional site-built competitors.
Growth Catalysts
- CTE Energy Mandates:Spain's Technical Building Code updates require near-zero energy performance that prefabricated systems satisfy through integrated thermal envelope engineering, accelerating public procurement pivots.
- Tourism Corridor Concentration:Mediterranean coastal demand from Valencia to Málaga favors rapid-build solutions for hospitality and residential projects where speed-to-revenue dominates developer calculus.
- Cross-Laminated Timber:Engineered wood products achieve dimensional tolerances of ±2mm in factory conditions while meeting EU Green Deal circular material specifications, expanding residential application viability.
Market Restraints
- Steel Input Volatility:Structural steel price fluctuations compress margins for industrial and educational segment manufacturers where span requirements mandate metallic framing.
- Andalusian Supply Concentration:Manufacturing gravity centers on southern Spain, exposing procurement timelines to regional logistics bottlenecks and single-source dependency risks.
- Foundation Integration Limits:Transportable module dimensions face highway clearance constraints that restrict design flexibility for large-format commercial applications.
Strategic Opportunities
- Basque Country Expansion:Underpenetrated northern markets present white space for modular healthcare and educational facilities where institutional procurement budgets remain robust.
- EU Green Deal Alignment:Recovery fund conditionality directing public procurement toward circular material specifications creates preferential bidding access for timber-frame and recycled-content manufacturers.
- Turnkey Bundling:Design-permit-installation integration captures higher value per project than component-only supply, with Madrid and Barcelona municipalities piloting single-contractor models.
Industry Challenges
- Building Systems Integration:MEP coordination between factory-built modules and site-installed infrastructure requires specialized technicians scarce in Spain's construction labor pool.
- CE Marking Timelines:EU Construction Products Regulation certification for novel composite materials extends product launch cycles by 8-14 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Prefabricated Buildings Market |
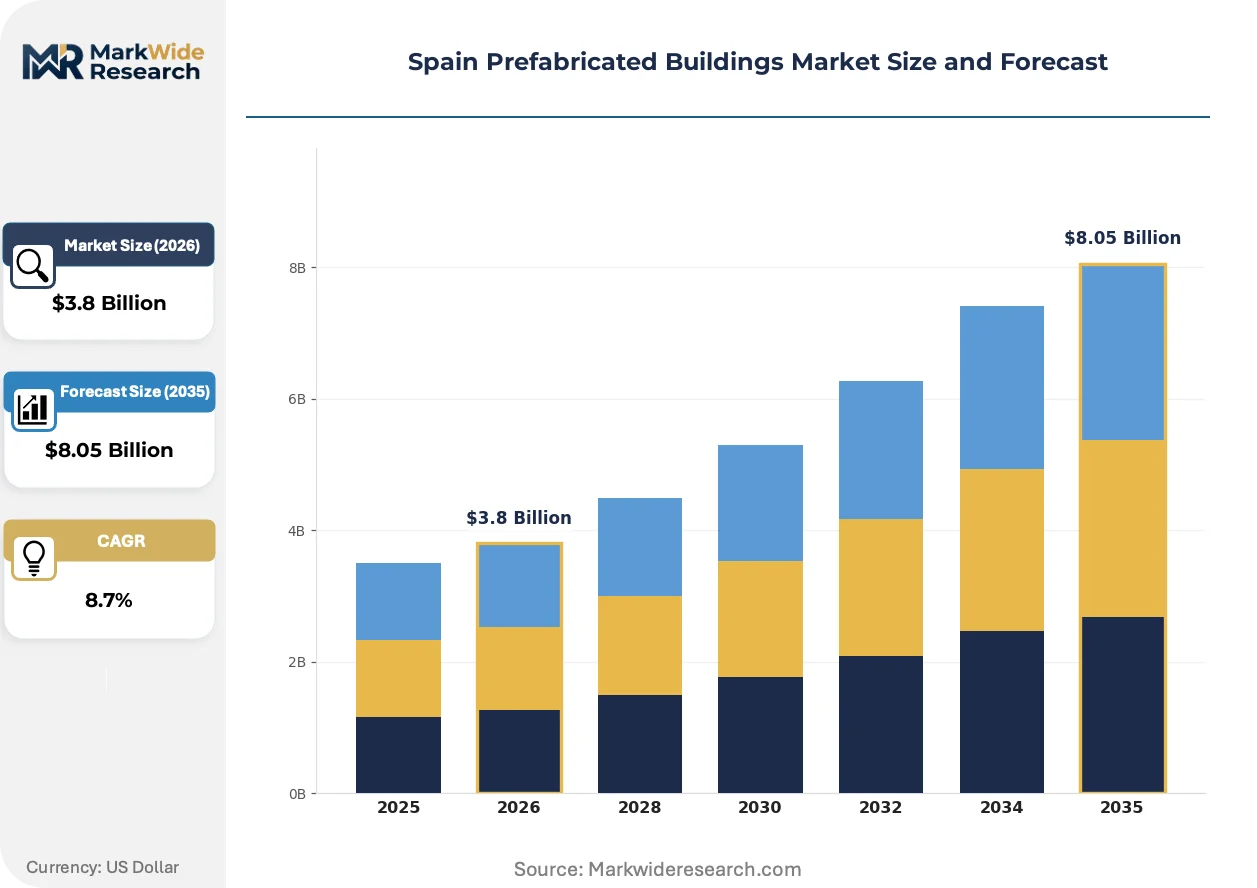
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefab Offices, Temporary Structures, Panelized Buildings Material: Wood, Steel, Concrete, Composite Application: Residential, Commercial, Industrial, Educational Construction Method: Factory-Built, On-Site Assembly, Hybrid, Turnkey Solutions |
| Companies Covered | Grupo ALCO Modular, Europa Prefabri, Algeco España, Atlantida Homes, Cualimetal, Grupo Avintia, Wallex, Pacadar Group, Compact Habit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Prefabricated Buildings Market Trends and Innovations
Digital fabrication and regulatory tightening are converging to redefine competitive advantage in Spanish offsite construction. Manufacturers are racing to embed energy performance into factory workflows before site-built methods can adapt.
Cross-laminated timber is overtaking conventional steel framing in mid-rise residential applications across Catalonia and Madrid. Social housing authorities specify engineered wood for its carbon sequestration credentials and precision-fit assembly. The material is compressing foundation-to-occupancy schedules from 18 months to under 8 months for comparable unit counts.
Spain's Ministry of Transport and Urban Agenda is enforcing stricter embodied carbon disclosure requirements through CTE amendments aligned with EU Green Deal trajectory. Industrial consequence: manufacturers must document lifecycle emissions for structural components to qualify for public tenders. Modular homes segment faces the steepest compliance curve as timber suppliers retrofit chain-of-custody certification.
Institutional buyers are consolidating vendor relationships around full-service contracts that absorb design liability and permitting risk. Madrid's regional housing authority now mandates single-point accountability for modular school and clinic deliveries, displacing fragmented general contractor arrangements. This pattern is most visible in Castilla-La Mancha and Extremadura where municipal technical capacity constraints are most acute.
Spain Prefabricated Buildings Market Segmentation
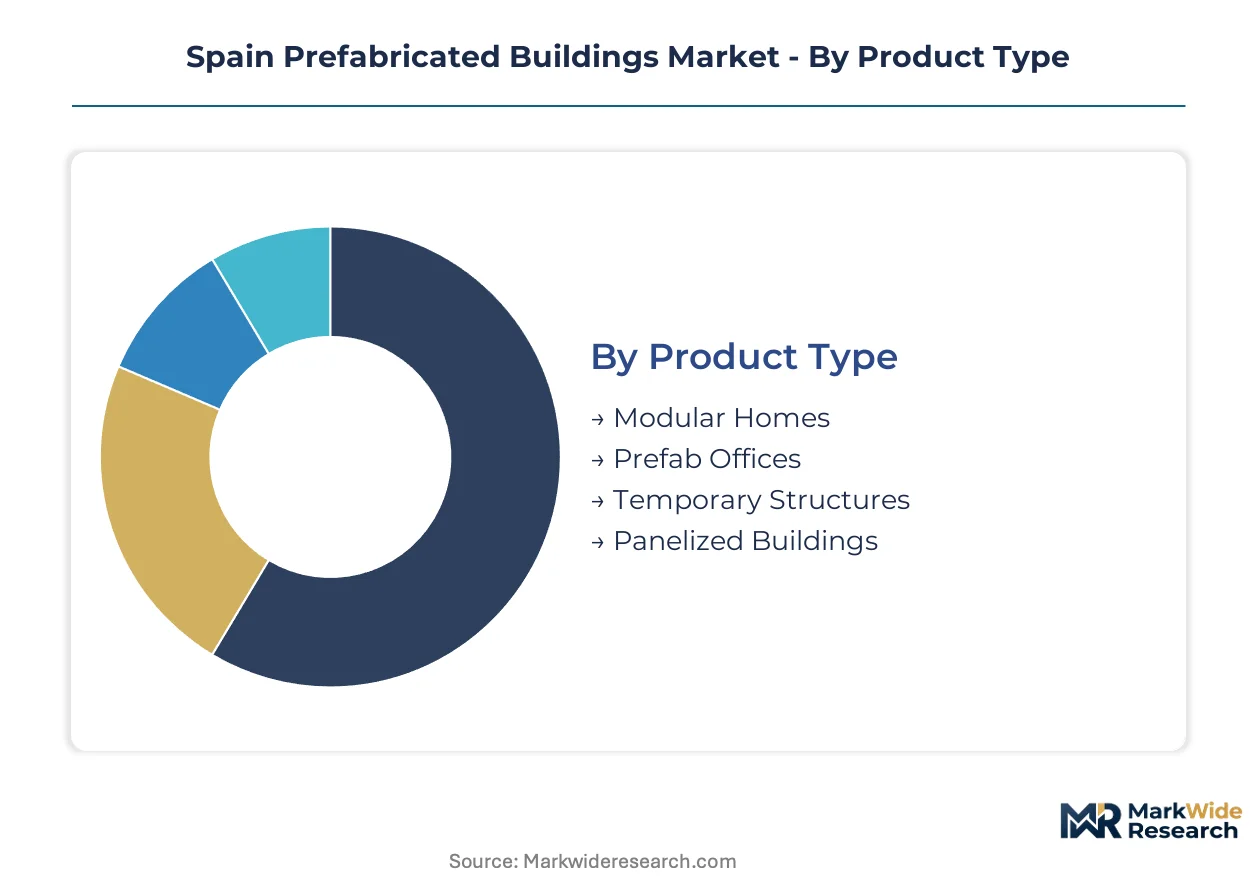
Segmentation in Spain's prefabricated buildings market reveals how distinct technical specifications and procurement channels fragment competitive positioning. Material selection and construction methodology determine which manufacturers capture institutional versus private demand.
Product Type:
Dimensional precision and transport logistics differentiate product categories across the Mediterranean coastal corridor.
- Modular Homes:Three-dimensional volumetric units manufactured to ±2mm tolerances arrive 80% complete from factory floors. Catalonia's social housing authorities specify these for compressed foundation-to-occupancy schedules in Barcelona's peripheral municipalities.
- Prefab Offices:Single-story or low-rise commercial modules integrate MEP systems during factory assembly. Madrid's logistics parks and Valencia's port-adjacent business zones absorb volume where speed-to-occupancy outweighs customization demands.
- Temporary Structures:Rental-focused units serve infrastructure project offices and event hospitality. Algeco España dominates this channel through Iberian-wide depot networks.
- Panelized Buildings:Flat-pack wall and roof components ship efficiently to constrained sites. Castilla-La Mancha agricultural processing facilities favor this format for expandable footprints.
Mature deployment sits with Temporary Structures. Newer deployment is concentrated in Modular Homes.
Material:
Structural performance requirements and EU Green Deal procurement conditionality reshape material selection across application segments.
- Wood:Cross-laminated timber achieves carbon sequestration credentials that satisfy CTE near-zero energy mandates. Engineered wood products from Basque Country suppliers penetrate Catalonia's institutional residential specifications.
- Steel:Metallic framing commands industrial and educational segments where fire resistance ratings and column-free spans dominate. Price volatility in structural steel inputs compresses margins for Andalusian manufacturers.
- Concrete:Precast concrete panels deliver acoustic separation and thermal mass for multi-unit residential. Mediterranean coastal humidity exposure limits deployment without specialized envelope engineering.
- Composite:Fiber-reinforced polymer and hybrid assemblies target lightweight commercial applications. CE marking timelines for novel composites extend product launch cycles.
Wood materials are gaining share fastest in public procurement. Steel retains volume leadership in private industrial development.
Application:
End-use specifications determine whether factory-built or hybrid construction methods prove economically viable.
- Residential:Social housing backlog pressures across Madrid and Barcelona metropolitan areas accelerate modular adoption. Timber-frame designs from Europa Prefabri anchor this segment through standardized catalog offerings.
- Commercial:Tourism-driven hospitality projects from Valencia to Málaga favor rapid-build solutions. Speed-to-revenue calculus dominates developer procurement decisions.
- Industrial:Warehouse and manufacturing facilities require wide clear spans that steel framing satisfies. Foundation integration limits constrain module dimensions for large-format footprints.
- Educational:Municipal school construction in Extremadura and Castilla-La Mancha consolidates around single-contractor turnkey models. Technical capacity constraints drive vendor consolidation.
Commercial application shows steepest expansion trajectory. Educational deployment remains procurement-constrained by municipal budget cycles.
Construction Method:
Value capture potential varies sharply between component supply and integrated service delivery.
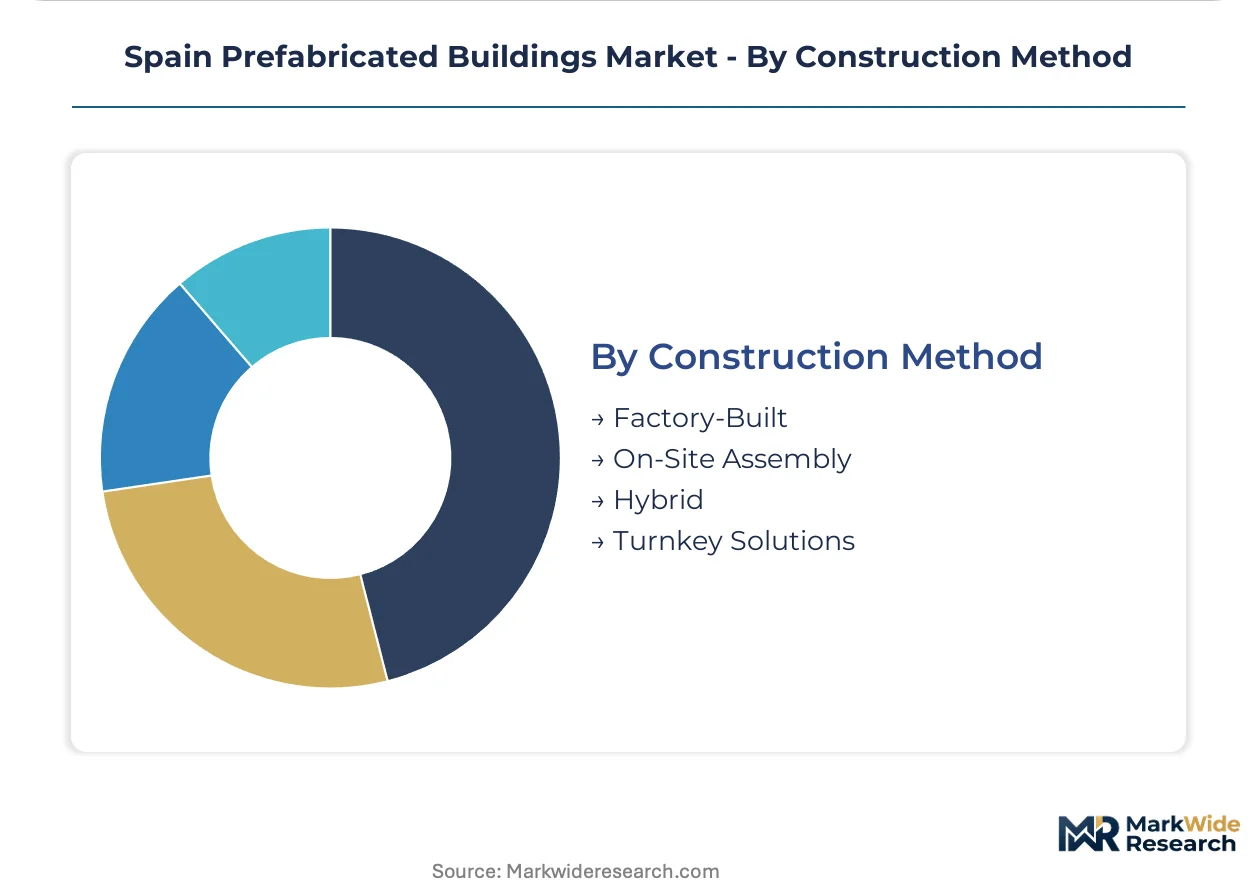
- Factory-Built:Volumetric modules complete with finishes and MEP systems roll off production lines in Andalusian manufacturing clusters. Volume throughput concentrates here though margin per project trails bundled alternatives.
- On-Site Assembly:Panelized or kit-of-parts systems erect on permanent foundations using local labor. Rural Galicia and Asturias projects favor this format where transport distances penalize volumetric modules.
- Hybrid:Factory-produced structural frames combine with site-installed infill and envelope systems. Mid-rise residential in Madrid's densifying suburbs adopts this compromise.
- Turnkey Solutions:Design-permit-installation bundling captures higher value per project. Madrid and Barcelona municipalities pilot single-contractor accountability for modular public facilities.
Factory-Built methods dominate current throughput. Turnkey Solutions represent the fastest-climbing value capture mechanism.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusian manufacturing clusters supply prefabricated modules across Spain while Mediterranean coastal provinces absorb the majority of domestic consumption. Production concentrates in Seville and Málaga industrial zones, yet deployment tilts toward Catalonia and Madrid where institutional procurement accelerates.
Madrid
Municipal housing authorities compress foundation-to-occupancy schedules through modular school and clinic deliveries. Spain's Ministry of Transport and Urban Agenda enforces Technical Building Code near-zero energy mandates that factory-built systems satisfy. The capital's metropolitan periphery anchors turnkey pilot programs where single-contractor accountability displaces fragmented general contractor arrangements.
Catalonia
Social housing backlog pressures across Barcelona's peripheral municipalities accelerate volumetric module procurement. CE marking requirements under EU Construction Products Regulation govern market access for cross-laminated timber components. Engineered wood suppliers from the Basque Country penetrate institutional residential specifications through carbon sequestration credentials.
Andalusia
Tourism-driven hospitality projects from Seville to Málaga favor rapid-build solutions where speed-to-revenue dominates developer calculus. EU Green Deal recovery fund conditionality directs public procurement toward circular material specifications. Manufacturing gravity centers on southern Spain expose procurement timelines to regional logistics bottlenecks and highway clearance constraints for transportable modules.
Valencia
Port-adjacent business zones absorb prefab office volume where speed-to-occupancy outweighs customization demands. Spain's Technical Building Code updates mandate integrated thermal envelope engineering that offsite manufacturers embed during factory assembly. The Mediterranean coastal corridor stretches deployment patterns toward Alicante where residential developers spec modular units for second-home markets.
Basque Country
Underpenetrated northern markets present white space for modular healthcare and educational facilities where institutional procurement budgets remain robust. BIS-equivalent structural certification requirements create compliance barriers for imported steel components. Bilbao and San Sebastián industrial clusters supply engineered wood products southward to Catalonia's timber-frame residential segment.
Spain Prefabricated Buildings Market Competitive Landscape
Top-tier vendors anchor turnkey solutions and factory-built volumetric modules, while mid-tier specialists occupy panelized systems and temporary structures. The vendor base stratifies across material competencies — timber-frame, steel framing, precast concrete — with each archetype serving distinct procurement channels. Three strategic archetypes dominate: integrated design-build operators, component-scale fabricators, and rental-focused temporary structure providers. Competitive moves concentrate on geographic expansion into underpenetrated northern provinces and bundling design-permit-installation services to capture higher value per project.
Among Spanish-based operators, Grupo ALCO Modular and Europa Prefabri exemplify contrasting market positions. Grupo ALCO Modular occupies the integrated manufacturing tier with Andalusian production assets serving institutional channels. Europa Prefabri anchors the standardized timber-frame segment through catalog-driven residential offerings. Algeco España represents the rental-focused archetype, sustaining revenue streams across Iberian infrastructure and event cycles through depot network density rather than permanent installation models.
| Leading Market Players |
|---|
| Grupo ALCO Modular |
| Europa Prefabri |
| Algeco España |
| Atlantida Homes |
| Cualimetal |
| Grupo Avintia |
| Wallex |
| Pacadar Group |
| Compact Habit |
| Others |
Pricing and Supply Chain Analysis
CTE certification-grade divergence between near-zero energy prefabricated systems and conventional site-built methods manifests in both pricing premiums and supply chain configurations across Spain's Mediterranean corridor. Factory-integrated thermal envelope engineering commands lead-time premiums while non-certified competitors absorb spot-market steel volatility.
Pricing Analysis
Lead-time-driven pricing compression distinguishes Spain's prefabricated buildings market, with turnkey bundling commanding premiums for sub-6-month delivery while component-only suppliers discount for spot inventory clearance. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels tracks CTE energy performance tiers. Pricing pressure stems from structural steel input volatility compressing margins for industrial segment manufacturers. Social housing authorities exhibit highest price sensitivity, while tourism hospitality developers accept premium positioning for speed-to-revenue certainty.
Supply Chain Analysis
Single-source vulnerability sits with Andalusian manufacturing clusters concentrated around Seville and Málaga, exposing national procurement timelines to regional logistics bottlenecks. Cross-laminated timber feeds from Basque Country engineered wood suppliers, while structural steel hinges on Iberian Peninsula mill capacity and imported coil. Highway clearance constraints for transportable modules constitute the dominant supply chain risk. Distribution runs through manufacturer-direct contracting for turnkey solutions and regional depot networks for temporary structure rentals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's prefabricated buildings sector occupies a technology-transition phase where cross-laminated timber and factory-integrated MEP systems displace conventional steel framing and site-built envelope construction.
For Market Incumbents: Extend turnkey service bundling into underpenetrated Basque Country and northern Castile markets before regional specialists consolidate institutional relationships. Backward integration into cross-laminated timber supply secures margin protection against Basque Country supplier pricing power. CE marking investment for novel composite materials defends against regulatory acceleration under EU Green Deal embodied carbon thresholds. For New Entrants and Emerging Players: Capture modular healthcare facility demand in Bilbao and San Sebastián metropolitan zones where institutional procurement budgets remain robust and incumbent presence thins. Basque Country educational construction presents the most penetrable geography given technical capacity constraints and vendor consolidation pressure. Lead with single-contractor accountability models that absorb municipal permitting risk. For Investors and Strategic Acquirers: Re-rating potential sits with integrated design-build operators given EU recovery fund conditionality directing public procurement toward circular material specifications. Long-term viability favors manufacturers with captive timber supply and CTE certification depth over component-scale fabricators exposed to steel price volatility. Monitor Basque Country engineered wood supplier consolidation as inflection indicator for input cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey Service Bundling | Design-permit-installation integration captures higher value per project in Madrid municipal procurement. |
| Cross-Laminated Timber Backward Integration | Captive engineered wood supply secures margin protection against Basque Country supplier concentration. |
| CE Marking Investment | EU Construction Products Regulation certification defends market access for novel composite materials. |
| Basque Country Geographic Expansion | Underpenetrated northern markets offer white space for modular healthcare and educational facilities. |
| Single-Contractor Accountability Models | Madrid and Barcelona municipalities pilot this procurement structure for public facility delivery. |
Research Methodology
Document review covered Spain's Ministry of Transport and Urban Agenda CTE amendments, EU Construction Products Regulation guidance, and regional municipal procurement databases, complemented by interviews with modular manufacturing plant managers, social housing procurement officers, timber-frame engineering directors, and temporary structure rental depot operators. Secondary validation drew from EU Green Deal implementation documents, Spain's national recovery fund conditionality frameworks, and customs records for cross-laminated timber imports. Bottom-up project pipeline analysis triangulated against top-down construction sector expenditure models.
Cross-referencing historical foundation-to-occupancy timelines against expert panel input on CTE compliance cost curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include material type, construction methodology, application sector, and regional regulatory cluster. CAGRs derived from installed base growth rates and replacement demand patterns. Industry-specific forecast inputs encompass tourism hospitality development permits along the Valencia-Málaga corridor and social housing backlog clearance schedules in Madrid and Barcelona metropolitan areas.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU-wide embodied carbon threshold implementation timing and structural steel price volatility. Forecasts reflect assumptions on CTE amendment enforcement consistency and recovery fund disbursement continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
North America Construction Market
Building Construction
GCC Cement Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Energy-Efficient Building Market
Building Construction
Middle East Data Center Construction Market
Building Construction
China Prefabricated Buildings Market
Building Construction
Africa Construction Market
Building Construction
US Modular Construction Market
Building Construction
India Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Vietnam Construction Market
Building Construction
UAE Facade Market
Building Construction
UK Construction Market
Building Construction
Africa Prefabricated Housing Market
Building Construction
France Prefab Wood Building Market