
 United Kingdom Data Center Construction Market | 2026-2036
United Kingdom Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Data Center Construction Market Insights
The UK's net-zero carbon building mandate is repositioning data center design toward energy-efficient infrastructure. AECOM leverages its engineering portfolio to dominate complex hyperscale projects across England. Arup anchors sustainable design credentials through integrated MEP and structural solutions. Atkins sustains competitive positioning with modular construction methods that compress delivery timelines.
United Kingdom data center construction encompasses the full lifecycle of facility creation from site preparation and shell construction through mechanical, electrical, and plumbing systems integration, typically requiring power densities exceeding 20 kW per rack for modern deployments. The primary purpose is delivering mission-critical infrastructure with tiered redundancy for digital service continuity. New build construction captures the dominant share of capital allocation as cloud service providers and colocation operators expand capacity. Direct liquid cooling emerges as the fastest-growing cooling technology segment as heat loads from AI training clusters exceed air-cooling thresholds. Colocation providers represent the most active end-user category, driven by enterprise outsourcing of IT infrastructure.
Ofgem's electricity grid connection reforms and the UK's Building Regulations Part L standards shape facility power architecture and thermal performance requirements. The Health and Safety Executive enforces construction site standards that influence project timelines and contractor qualification. BSI standards for resilient infrastructure further define structural and fire-safety specifications. Stakeholders must monitor grid connection queue positions and local authority planning decisions as these gate the pace of capacity additions.
Market Dynamics
Direct liquid cooling is compressing mechanical infrastructure footprints as AI training clusters push rack densities past air-cooling limits across Greater London and the Thames Valley.
Growth Catalysts
- Building Regulations Part L:The UK's net-zero carbon mandate accelerates retrofit demand for energy-efficient MEP systems in legacy facilities.
- Hyperscale cloud expansion:Colocation providers in Slough and Manchester are procuring modular shell construction to compress delivery timelines for enterprise outsourcing contracts.
- Liquid-cooled infrastructure:Heat loads exceeding 20 kW per rack are forcing migration from traditional CRAC units to immersive and cold-plate cooling architectures.
Market Restraints
- Grid connection queues:Ofgem's reform backlog extends energization timelines for new facilities beyond 36 months in constrained zones.
- Steel and copper volatility:Raw material input swings compress contractor margins on fixed-price EPC contracts for hyperscale shells.
- Land scarcity in London Docklands:Brownfield site competition with residential developers limits expansion corridors for mission-critical facilities.
Strategic Opportunities
- Secondary markets:Manchester and Birmingham offer untapped power capacity with lower land costs than the Thames Valley corridor.
- Waste heat recovery:District heating integration creates dual-revenue streams for facilities adjacent to residential zones.
- Modular prefabrication:Off-site MEP assembly compresses on-site construction windows and reduces skilled labor exposure.
Industry Challenges
- Liquid cooling technician shortage:Specialized plumbing and dielectric fluid handling skills outpace vocational training pipeline output.
- Tier certification timelines:Uptime Institute and BSI resilience audits extend commissioning phases by four to six months.
- Legacy electrical integration:Retrofitting 480V/277V infrastructure into 415V/240V British standards creates compatibility friction for international operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Data Center Construction Market |
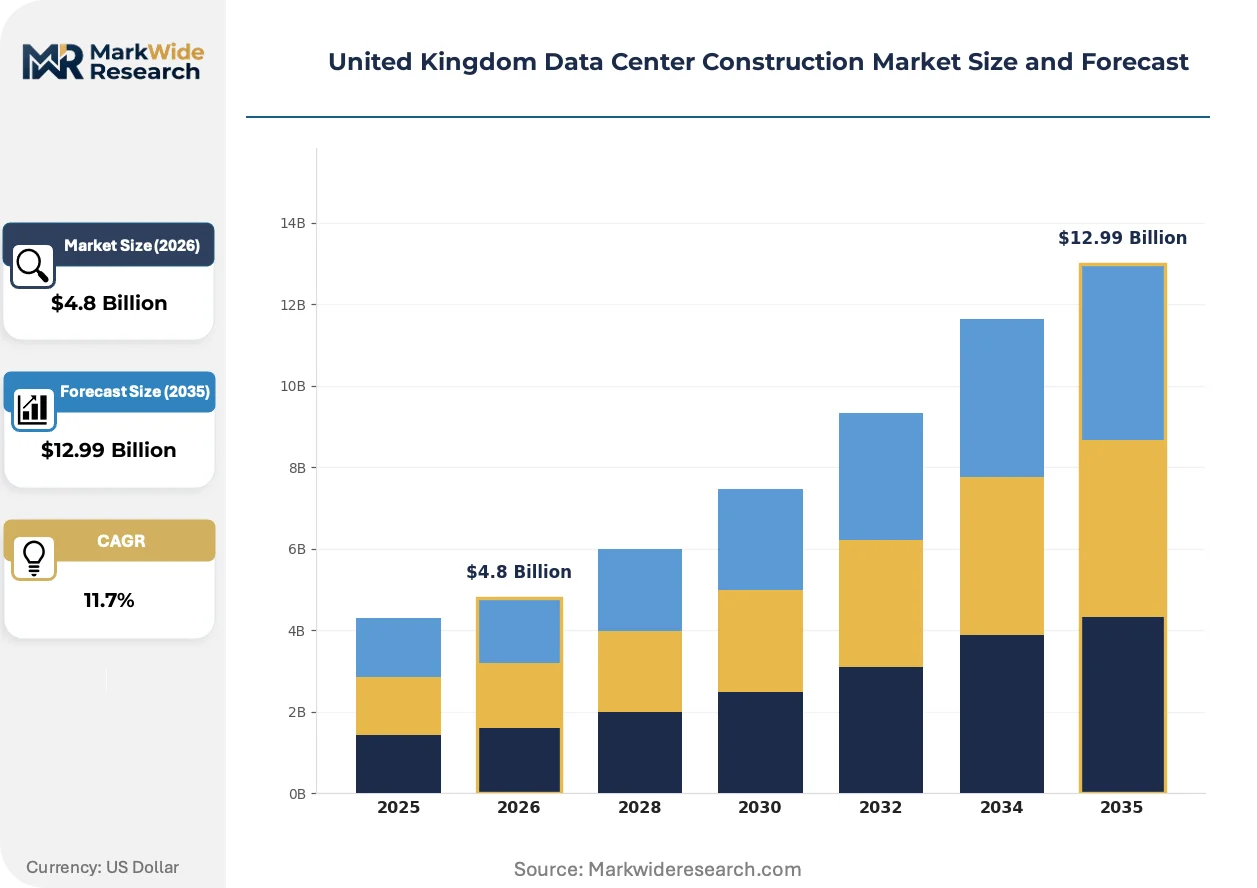
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Construction Type: New Build, Expansion, Retrofit, Upgrade Power Supply: Grid Connection, Renewable Energy, Diesel Generators, Hybrid Systems Cooling Technology: Direct Liquid Cooling, Air Cooling, Chilled Water Systems, Evaporative Cooling End User: Colocation Providers, Enterprises, Cloud Service Providers, Government Agencies |
| Companies Covered | AECOM, Arup, Atkins, Bouygues Construction, JCA Engineering, BladeRoom Data Centres, 2bm, Kirby Engineering Group, Deerns, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Data Center Construction Market Trends and Innovations
Facility architecture is pivoting from discrete mechanical systems toward integrated thermal-electric platforms that compress capital deployment cycles.
Intelligent power distribution units with embedded metering and switching are unifying rack-level visibility with building management systems. Hyperscale operators in Slough are specifying these units as standard for all new white space. The technology is unifying previously siloed electrical and thermal monitoring into single-pane operational dashboards.
The UK's Building Regulations Part L updates impose airtightness and thermal bridging standards that exceed legacy data center envelope specifications. Contractors must now integrate continuous insulation and thermal break detailing into shell designs. Colocation providers in London Docklands are responding with building-integrated photovoltaics and advanced glazing assemblies to meet operational carbon targets.
Enterprise buyers are consolidating vendor relationships from multi-contractor arrangements toward single-source EPC partnerships. This compression eliminates interface risk between civil, MEP, and commissioning phases. Financial institutions with London headquarters are driving this pattern as they outsource primary data center operations to specialized operators.
United Kingdom Data Center Construction Market Segmentation
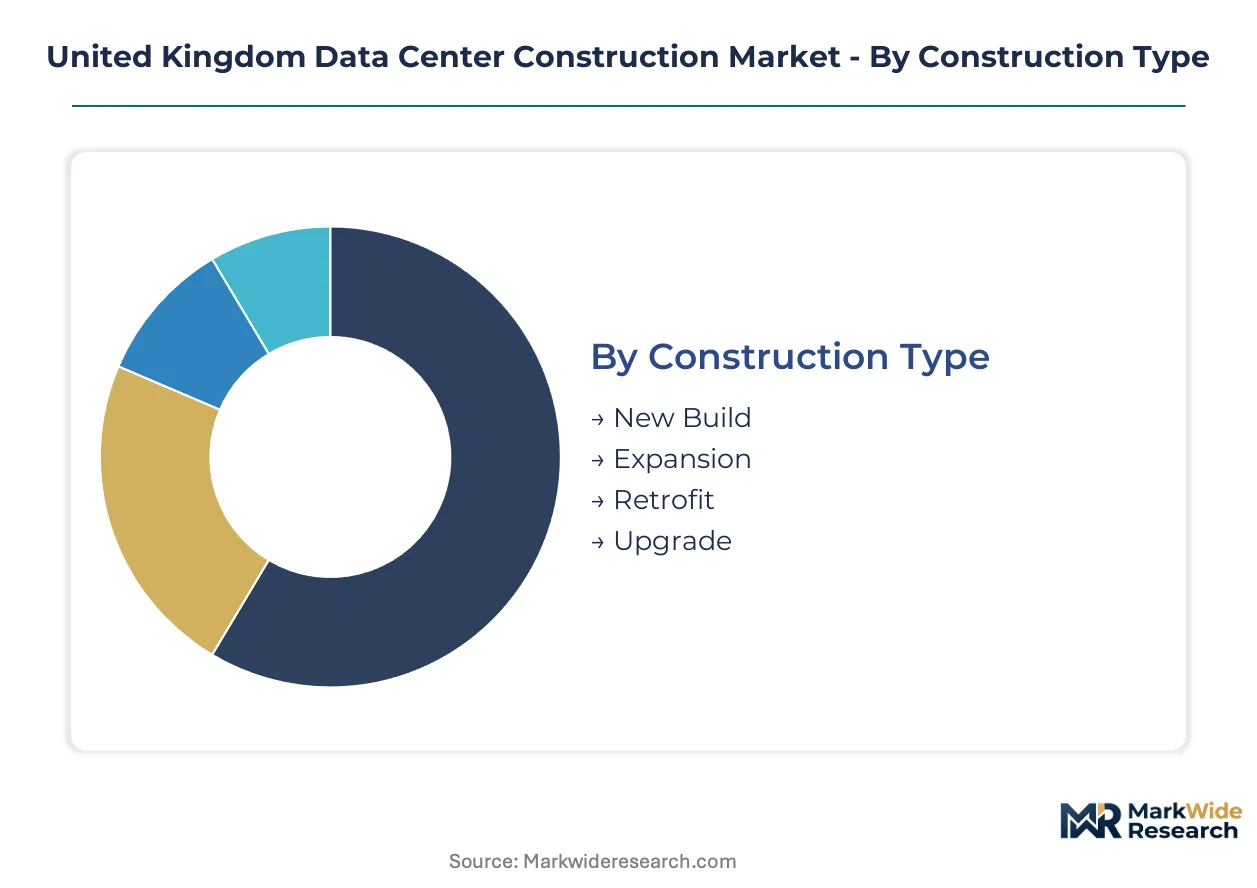
Segmentation in United Kingdom data center construction reveals how capital allocation splits between greenfield capacity and brownfield optimization. Construction type and cooling technology choices determine project economics as Ofgem grid reforms and Building Regulations Part L reshape facility specifications across Greater London and the Thames Valley.
Construction Type:
New build commands premium capital deployment while retrofit and expansion segments capture volume through legacy facility optimization.
- New Build:Greenfield shell construction with integrated MEP systems delivers hyperscale capacity for cloud service providers in Slough and Manchester. These projects attract fixed-price EPC contracts where steel and copper volatility compress contractor margins.
- Expansion:Modular additions to existing facilities compress delivery timelines for colocation providers responding to enterprise outsourcing demand. This segment concentrates in London Docklands where land scarcity forces vertical densification rather than horizontal growth.
- Retrofit:Legacy facility upgrades address Building Regulations Part L compliance through airtightness improvements and thermal bridge remediation.
- Upgrade:Electrical infrastructure refresh projects resolve 480V/277V to 415V/240V compatibility friction for international operators.
Today's leader: New Build. Tomorrow's challenger: Retrofit.
Power Supply:
Grid dependency versus energy independence shapes facility resilience architecture and operational carbon positioning.
- Grid Connection:Direct utility supply dominates where Ofgem queue positions allow energization within project timelines. Facilities in constrained zones face 36-month connection delays that threaten cloud provider expansion schedules.
- Renewable Energy:Power purchase agreements and on-site generation align with net-zero mandates while reducing exposure to grid volatility. Colocation providers in Manchester leverage this segment to differentiate enterprise offerings.
- Diesel Generators:Traditional backup systems face regulatory pressure as Part L standards tighten operational emissions thresholds.
- Hybrid Systems:Battery storage paired with renewable generation and grid connection optimizes resilience while meeting carbon targets.
Grid Connection anchors current deployment. Renewable Energy is climbing the fastest as PPA structures mature.
Cooling Technology:
Rack density thresholds determine mechanical infrastructure selection as AI training clusters force thermal architecture decisions.
- Direct Liquid Cooling:Immersive and cold-plate systems handle heat loads exceeding 20 kW per rack that overwhelm traditional CRAC units. Cloud service providers across the Thames Valley specify this technology as standard for AI training infrastructure.
- Air Cooling:Legacy mechanical systems retain cost advantage for standard enterprise workloads below density thresholds. This segment contracts as hyperscale operators migrate liquid-cooled architectures.
- Chilled Water Systems:Centralized plant configurations serve multi-tenant colocation facilities with predictable thermal profiles.
- Evaporative Cooling:Adiabatic systems reduce mechanical refrigeration load in facilities with suitable water availability and ambient conditions.
Air Cooling holds volume share. Direct Liquid Cooling gains share fastest as rack densities escalate.
End User:
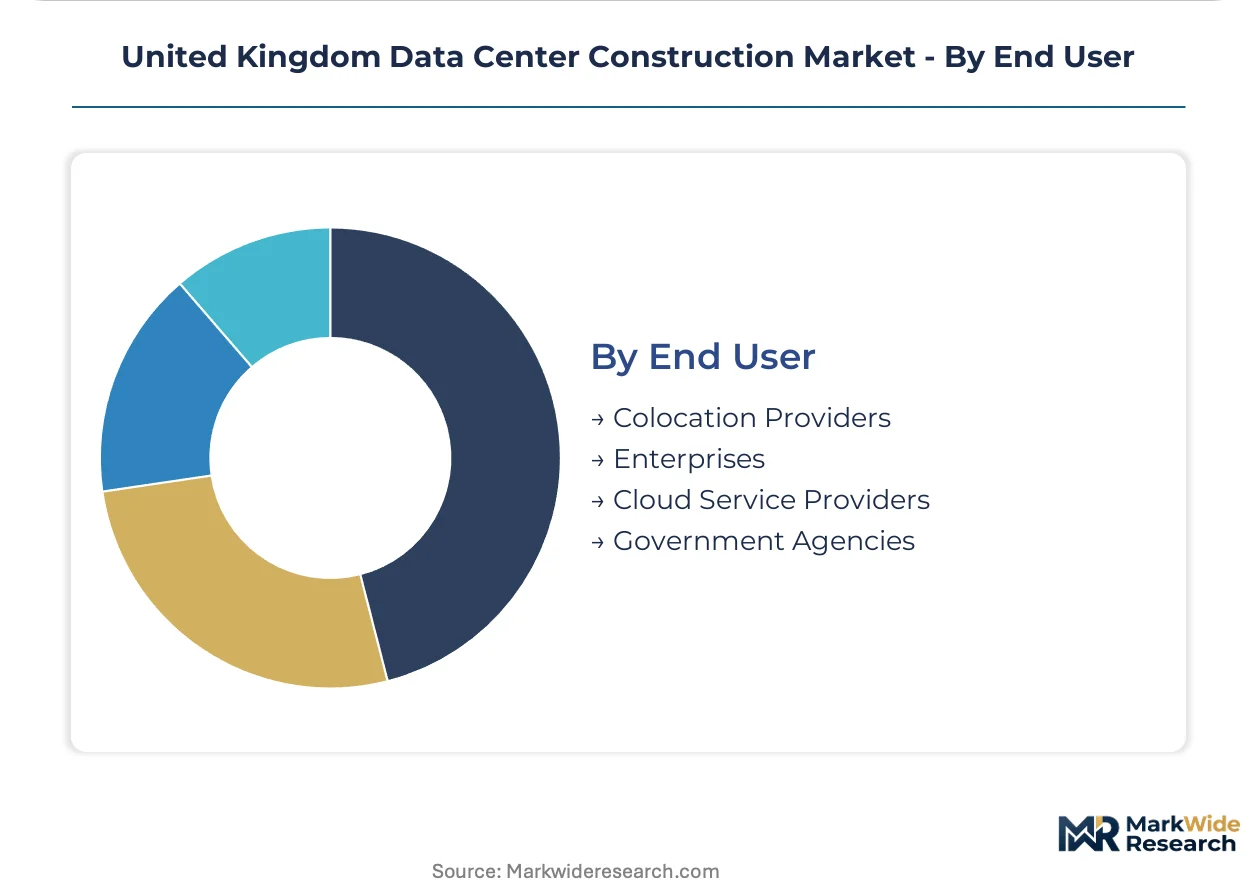
Outsourcing intensity versus captive infrastructure ownership determines project scale and specification complexity.
- Colocation Providers:Multi-tenant facility operators procure modular construction to compress delivery timelines for enterprise contracts. This category concentrates procurement activity in Slough and Manchester where power access aligns with land availability.
- Cloud Service Providers:Hyperscale operators drive demand for direct liquid cooling and tiered redundancy specifications across Greater London. Their projects anchor the new build segment with long-term EPC partnerships.
- Enterprises:Financial institutions with London headquarters are consolidating vendor relationships toward single-source arrangements that eliminate interface risk.
- Government Agencies:Public sector deployments emphasize BSI resilience standards and extended commissioning phases for mission-critical applications.
Colocation Providers dominate current volume. Cloud Service Providers show the steepest expansion trajectory as AI infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized construction workforce clusters anchor the United Kingdom's data center development pipeline. Engineering talent concentrates in Greater London and the Thames Valley, with mechanical and electrical trades supporting liquid-cooled facility deployment. Regional capacity splits between established hyperscale corridors and emerging secondary markets.
Greater London and Thames Valley
Cloud service providers drive demand for direct liquid cooling infrastructure across Slough and London Docklands. Building Regulations Part L mandates airtightness standards that exceed legacy envelope specifications. The corridor hosts the densest concentration of colocation providers procuring modular shell construction for enterprise contracts.
North England
Manchester offers untapped grid capacity with lower land costs than southeastern corridors. Ofgem's electricity grid connection reforms shape facility power architecture across the region. Data center operators are targeting the city for hyperscale expansion as Thames Valley land scarcity intensifies.
Midlands
Birmingham emerges as a secondary market with favorable power access and reduced brownfield competition. The Health and Safety Executive enforces construction site standards influencing contractor qualification across West Midlands projects. Modular prefabrication specialists are establishing assembly facilities to serve regional demand.
Scotland
Cooler ambient temperatures reduce mechanical cooling loads for facilities in Edinburgh and Glasgow. Renewable energy availability through power purchase agreements aligns with net-zero carbon mandates. Operators are evaluating sites for AI training clusters requiring dense liquid-cooled architectures.
United Kingdom Data Center Construction Market Competitive Landscape
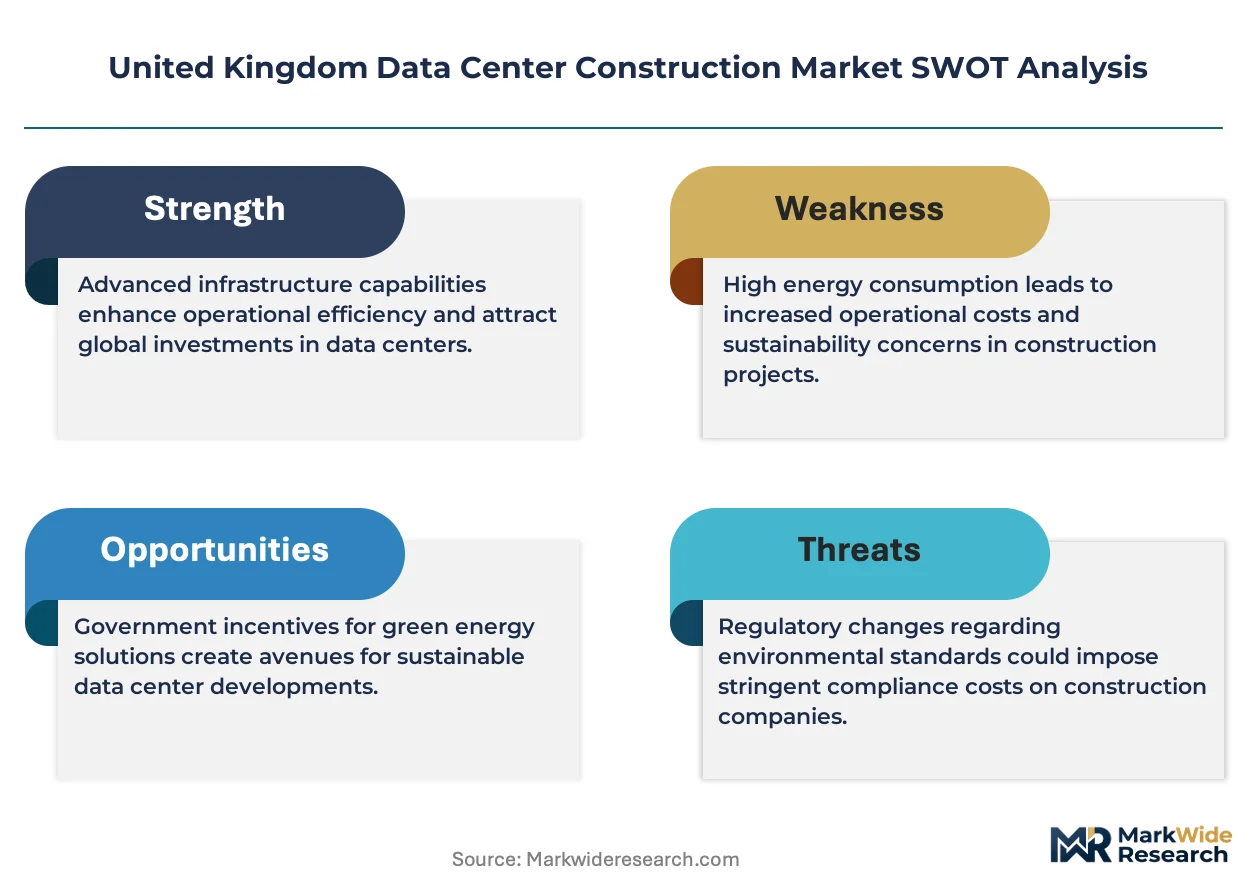
Capital-heavy engineering firms compete with specialized modular fabricators for data center construction contracts across the United Kingdom. The market structures around tiered capabilities, with full-service EPC providers anchoring hyperscale projects and niche operators capturing retrofit and modular segments. Three archetypes dominate: integrated engineering consultancies with MEP design-build capacity, modular prefabrication specialists compressing delivery timelines, and regional contractors with local authority planning relationships. Competitive positioning hardens through long-term EPC partnerships and vertical capability expansion into commissioning and tier certification support.
Within the integrated engineering tier, AECOM and Arup represent archetypal positioning for complex hyperscale developments across Greater London. Atkins exemplifies modular construction methods that compress project delivery. Among specialized fabricators, BladeRoom Data Centres and Kirby Engineering Group occupy positions serving colocation providers with repeatable facility designs. Bouygues Construction anchors international contractor presence for flagship developments. These players collectively illustrate how capability depth in liquid cooling integration and regulatory compliance shapes competitive differentiation.
| Leading Market Players |
|---|
| AECOM |
| Arup |
| Atkins |
| Bouygues Construction |
| JCA Engineering |
| BladeRoom Data Centres |
| 2bm |
| Kirby Engineering Group |
| Deerns |
| Others |
Pricing and Supply Chain Analysis
Steel and copper price indices cascade through fixed-price EPC contracts into three distinct pricing tiers for hyperscale shell construction across Greater London and the Thames Valley. Contractors absorb raw material volatility on legacy projects while passing through indexed costs on new procurement, compressing margins at the standard tier and widening spreads to premium liquid-cooled specifications.
Pricing Analysis
Bundled EPC contracts versus unbundled multi-contractor arrangements split the market into divergent pricing architectures. Tiered pricing separates turnkey hyperscale delivery from modular shell-only procurement, with certification grade and geographic delivery cost as primary differentiation drivers. Cost compression in standard air-cooled infrastructure intensifies as steel input volatility erodes contractor margins. Colocation providers in Slough exhibit highest price sensitivity due to competitive enterprise outsourcing pressure, while cloud service providers anchor premium tier demand with limited elasticity for AI training cluster specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese steel and copper semi-finished products feeding UK fabrication facilities. Mechanical and electrical equipment draws from Germany, the Netherlands, and domestic suppliers, with dielectric fluids for liquid cooling systems resting on Belgian and US chemical producers. Tariff exposure on steel imports creates margin risk for fixed-price shell contracts. Distribution runs through specialized data center contractors with direct relationships to hyperscale operators and colocation providers, bypassing traditional construction distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in UK data center construction hinges on modular prefabrication scale economies and premium-tier liquid cooling penetration. Liquid-cooled infrastructure specifications command pricing premiums that offset raw material volatility through reduced mechanical footprint and faster commissioning.
For Market Incumbents: Anchor defensive positioning through long-term EPC partnerships with cloud service providers that lock in liquid cooling specification standards. Pursue backward integration into off-site MEP assembly to capture modular construction premiums and compress on-site labor exposure. The threat of specialized liquid cooling technician scarcity demands captive training pipeline development alongside tier certification support capabilities. For New Entrants and Emerging Players: Regional contractors with Birmingham and Manchester planning authority relationships offer the most penetrable entry vector. Target secondary market modular shell contracts where Thames Valley incumbents face land scarcity constraints. A go-to-market angle through waste heat recovery integration with district heating schemes differentiates offerings in residential-adjacent zones where Building Regulations Part L compliance creates dual-revenue opportunities. For Investors and Strategic Acquirers: Asymmetric upside sits with modular prefabrication specialists possessing repeatable facility designs and established colocation provider relationships. The long-term viability window favors operators with vertical integration into commissioning and tier certification support, reducing interface risk for enterprise buyers consolidating vendor relationships. Watch Ofgem grid connection queue clearance rates as the inflection signal for secondary market expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Scale-Up | Off-site MEP assembly compresses delivery timelines and reduces skilled labor exposure for Slough and Manchester projects. |
| Liquid Cooling Integration Partnership | Dielectric fluid handling capabilities differentiate contractors for AI training cluster specifications exceeding 20 kW per rack. |
| Secondary Market Geographic Expansion | Birmingham and Manchester capacity addresses Thames Valley land scarcity while leveraging favorable Ofgem queue positions. |
| Waste Heat Recovery Infrastructure | District heating integration creates dual-revenue streams for facilities adjacent to residential zones under Part L mandates. |
| Tier Certification Support Capability | Uptime Institute and BSI audit expertise extends contractor relationships through commissioning phases and operational handover. |
Research Methodology
Multiple input streams — primary interviews with EPC contractors and colocation procurement directors, secondary validation against Ofgem regulatory filings and Building Regulations Part L documentation, and customs data on steel and copper imports — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement encompassed hyperscale cloud operators, modular prefabrication specialists, MEP engineering consultants, and local authority planning officers across Greater London, Manchester, and Birmingham. Secondary sources included Health and Safety Executive enforcement data, BSI resilience standard documentation, and contractor financial disclosures.
Historical project completion data cross-referenced against panel input from industry participants informed the analytical framework across the projection horizon. Segmentation dimensions modeled encompassed construction type, cooling technology architecture, power supply configuration, and end-user category with geographic clustering by development corridor. CAGRs were derived from capacity addition pipelines and capital expenditure disclosure patterns. Forecast inputs incorporated Ofgem grid connection queue dynamics and Building Regulations Part L compliance cost curves.
Revisions become necessary when Ofgem reform implementation accelerates or stalls, when raw material price volatility exceeds historical bands, or when liquid cooling technician training pipeline output materially shifts. Forecasts reflect documented assumptions on grid energization timelines, regulatory enforcement intensity, and technology adoption thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Africa Prefabricated Housing Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
Turkey Construction Market
Building Construction
France Prefab Homes Market
Building Construction
Tanzania Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Qatar Construction Market
Building Construction
US Prefabricated Buildings Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Japan Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Sweden New Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Italy Construction Market
Building Construction
Indonesia Construction Market